
 UK Heavy Construction Equipment Rental Market | 2026-2036
UK Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
UK Heavy Construction Equipment Rental Market Insights
Buyer concentration across UK infrastructure developers is rebalancing as tier-one contractors consolidate project portfolios while smaller civil engineering firms fragment demand across shorter rental windows. Ashtead Group plc sustains national fleet scale through Sunbelt Rentals Ltd, which dominates multi-region coverage. HSS Hire Service Group Ltd specializes in compact urban equipment for constrained London sites. GAP Hire Solutions anchors Scottish and northern England operations with localized service density.
UK heavy construction equipment rental encompasses the temporary provision of mechanized earthmoving, lifting, and material handling machinery powered by diesel or electric drivetrains with operating weights exceeding 12 tonnes, typically deployed through fleet agreements rather than capital purchase. The primary commercial purpose substitutes operational expenditure for capital commitment while transferring maintenance, compliance, and residual value risk to rental providers. Excavators and cranes lead equipment type demand due to versatility across road construction and demolition applications, while long-term lease structures capture margin pools from infrastructure developers seeking cost predictability. Monthly rental durations are expanding fastest among utility service providers responding to regulatory-driven grid and water network upgrades.
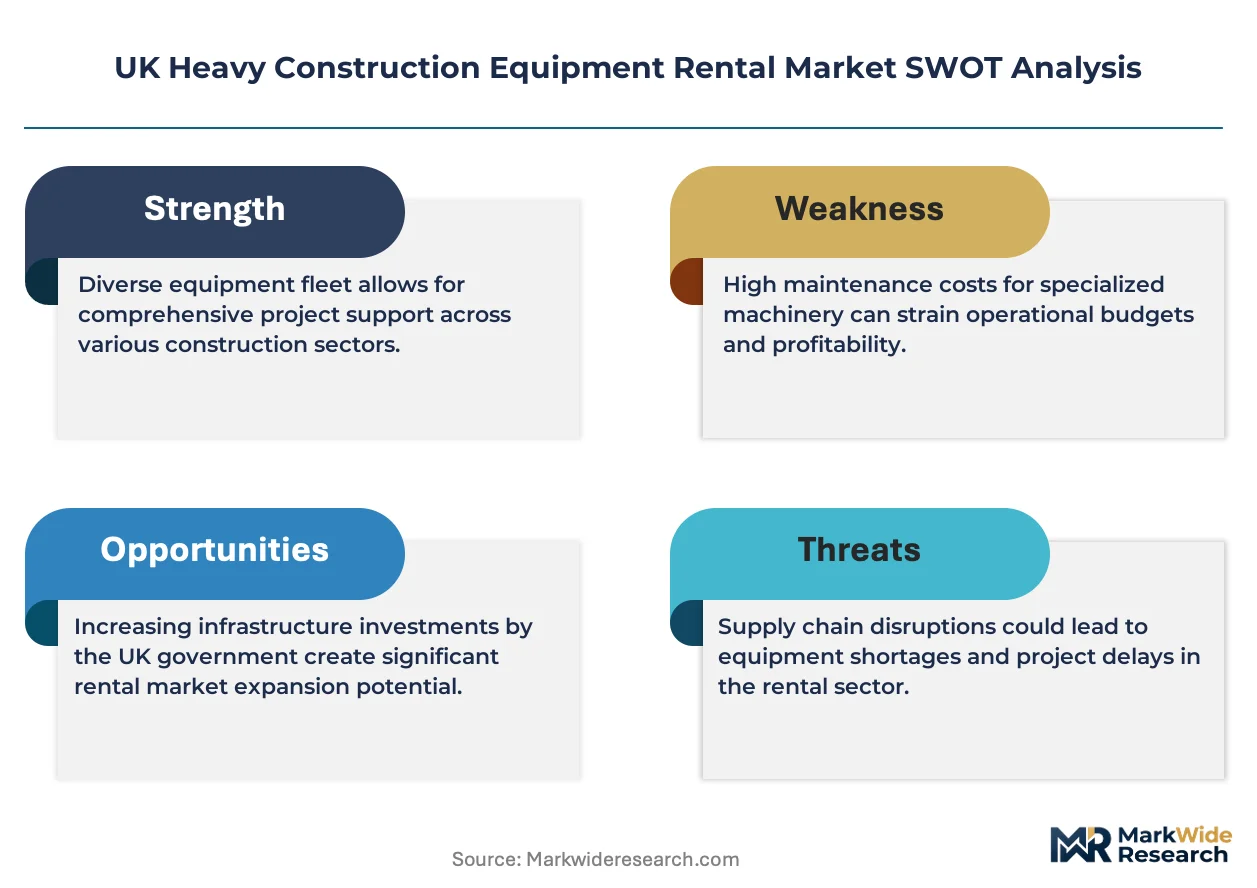
The Health and Safety Executive enforces LOLER and PUWER standards that mandate inspection intervals and operator certification, directly shaping fleet maintenance schedules and rental contract terms. The UK's Environment Agency implements non-road mobile machinery emissions regulations that phase out older diesel equipment, forcing rental providers to refresh capital-intensive inventories. Stakeholders must monitor how the Building Safety Regulator's emerging competence requirements reshape customer liability allocation between contractors and rental suppliers.
Market Dynamics
The UK's Construction Products Regulation and net-zero building standards are compressing diesel equipment residual values while accelerating electric fleet refresh cycles across rental portfolios.
Growth Catalysts
- HS2 and utility network upgrades:Infrastructure developers are locking in long-term rental agreements for earthmoving and lifting equipment across Greater London and northern England corridors.
- Environment Agency emissions phase-outs:Non-road mobile machinery regulations are forcing rental providers to retire older diesel inventories, creating replacement demand for compliant electric and hybrid units.
- Operator certification mandates:Health and Safety Executive enforcement of LOLER and PUWER standards is extending rental contract durations as contractors outsource compliance liability to fleet owners.
Market Restraints
- Steel and battery input volatility:Equipment manufacturing costs fluctuate with commodity markets, compressing rental yield predictability on long-term lease structures.
- Greater London site access constraints:Urban congestion and low-emission zones restrict diesel equipment deployment, fragmenting fleet utilization across geographically dispersed projects.
- Residual value uncertainty:Accelerated diesel obsolescence from tightening emissions standards is concentrating depreciation risk on rental balance sheets.
Strategic Opportunities
- Midlands equipment hub expansion:Logistics corridors connecting Birmingham and Manchester present underpenetrated density for regional service depots and rapid-response maintenance.
- Grid-scale battery storage co-location:Rental providers can bundle mobile power solutions with electric equipment packages for remote construction sites lacking grid connection.
- Building Safety Regulator competence frameworks:Emerging liability allocation rules create advisory service revenue streams around operator training and equipment specification compliance.
Industry Challenges
- Electric equipment technician scarcity:High-voltage drivetrain maintenance skills lag fleet electrification timelines, extending repair turnaround and contract penalty exposure.
- Multi-jurisdiction compliance complexity:Scottish environmental regulations and English building safety rules diverge on inspection intervals, forcing fragmented fleet management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Heavy Construction Equipment Rental Market |
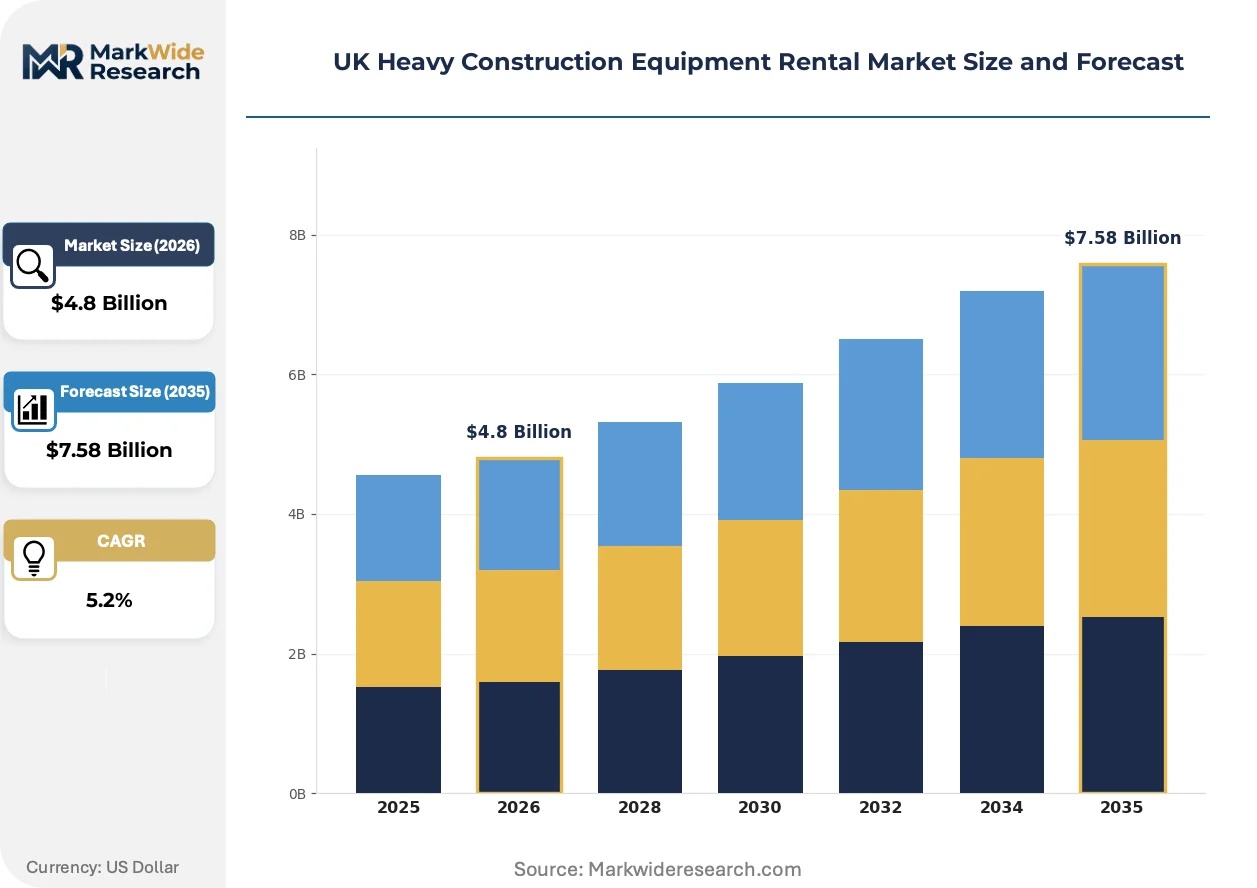
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders, Dump Trucks, Forklifts Rental Duration: Daily, Weekly, Monthly, Long-Term Lease Application: Road Construction, Bridge Building, Site Preparation, Material Handling, Demolition Customer Type: Contractors, Infrastructure Developers, Civil Engineering Firms, Utility Service Providers |
| Companies Covered | HSS Hire Service Group Ltd, Loxam, Ashtead Group plc, Ainscough, Boels Rental, Sunbelt Rentals Ltd, GAP Hire Solutions, Flannery, Speedy Hire plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Heavy Construction Equipment Rental Market Trends and Innovations
Electrification and telematics integration are restructuring how rental fleets are deployed, monitored, and priced across UK construction sites.
Telematics-enabled predictive maintenance is overtaking scheduled service intervals as the dominant fleet management protocol. Infrastructure contractors now mandate real-time equipment health dashboards as contract prerequisites. This compression of unplanned downtime is shifting rental pricing from day-rate models toward guaranteed-availability structures.
The UK's Environment Agency non-road mobile machinery emissions regulations are accelerating diesel equipment obsolescence. Rental providers must now front-load capital expenditure to secure compliant inventory ahead of 2025-2028 phase-out windows. Northern England utility contractors face the steepest compliance cliffs due to older fleet age profiles in water and energy network maintenance.
Flexible rental duration structures are displacing fixed-term leases as the preferred contracting format. Tier-one contractors now demand month-to-month extensions with termination options, transferring demand volatility risk to rental providers. This pattern concentrates most acutely in Greater London commercial development where planning permission delays disrupt project timelines unpredictably.
UK Heavy Construction Equipment Rental Market Segmentation
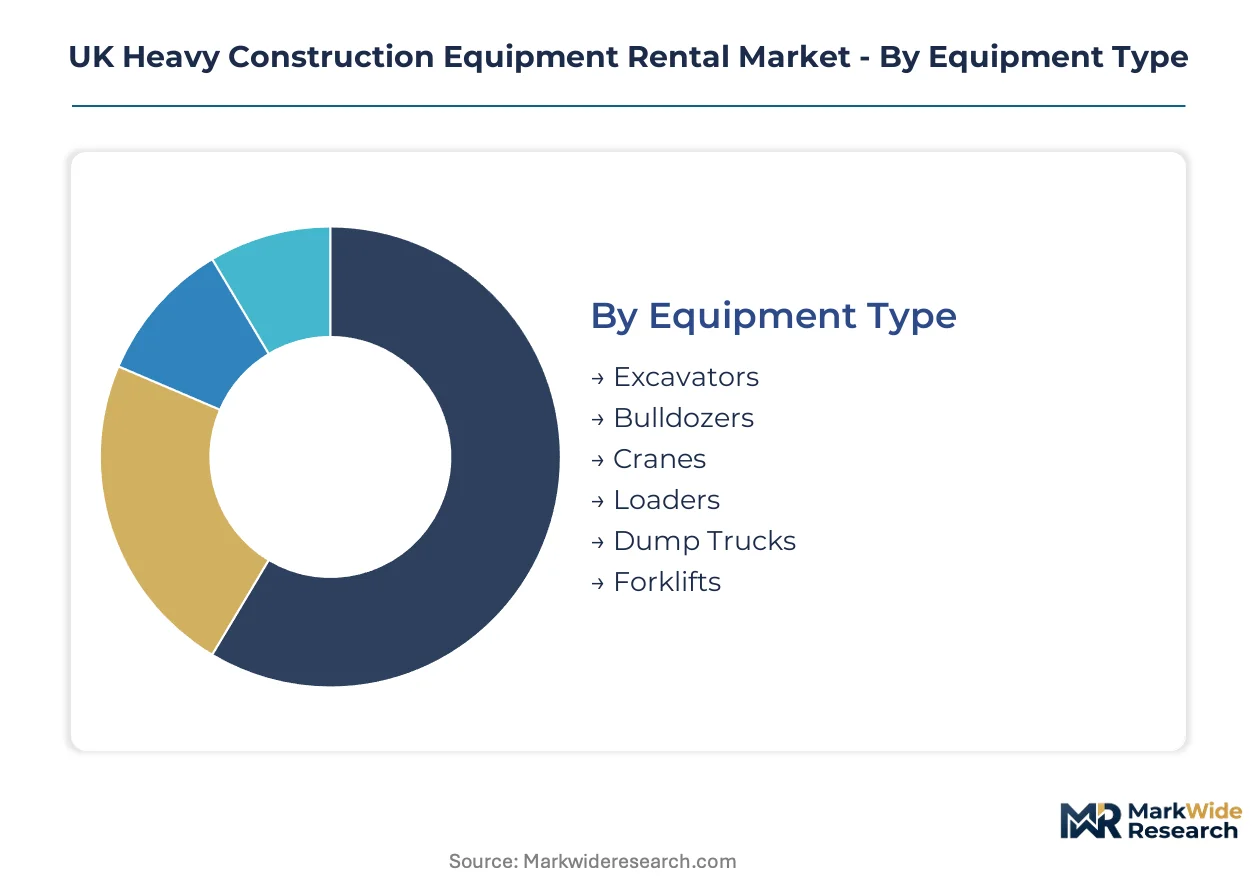
Equipment rental portfolios in the UK allocate capital unevenly across machine categories, with lifting and earthmoving assets commanding disproportionate balance sheet weight. Rental duration structures and customer contracting patterns further stratify working capital intensity and margin predictability across provider operations.
Equipment Type:
Capital intensity peaks with cranes and excavators, where acquisition costs and maintenance infrastructure demands concentrate provider investment.
- Excavators:Tracked and wheeled hydraulic machines with bucket capacities from 1.5 to 50 tonnes dominate earthmoving versatility across site preparation and utility trenching. HS2 corridor contractors in northern England are locking in dedicated excavator fleets for multi-year rail earthworks, stretching availability windows and compressing spot rental access.
- Cranes:Mobile all-terrain and crawler configurations with lifting capacities exceeding 100 tonnes require specialized transport logistics and certified rigging crews. Bridge building projects across the Midlands are absorbing tower crane capacity for extended durations, forcing providers to ration mobile crane availability for shorter-term commercial developments.
- Bulldozers:Tracked dozers with blade widths exceeding 3 metres serve bulk earthmoving and grading operations with high fuel consumption profiles.
- Loaders:Wheel loaders with operating weights from 12 to 30 tonnes handle material stockpiling and truck loading across aggregate processing sites.
- Dump Trucks:Articulated and rigid haulers with payload ratings from 25 to 40 tonnes move overburden and construction spoil in high-cycle operations.
- Forklifts:Counterbalance and telehandler variants under 12 tonnes fall outside heavy equipment classification but support material handling integration.
Excavators absorb the bulk of installed capacity; cranes are expanding most quickly on infrastructure project concentration.
Rental Duration:
Contracting structures segment working capital risk between providers and customers, with longer commitments trading yield predictability for utilization certainty.
- Long-Term Lease:Agreements spanning 12 to 60 months with fixed monthly rates and maintenance inclusion transfer residual value risk entirely to rental providers. Infrastructure developers facing Environment Agency emissions compliance deadlines are accelerating long-term lease uptake to secure electric and hybrid equipment allocations before phase-out windows tighten.
- Monthly:Rolling 30-day contracts with extension options dominate utility service provider procurement for regulatory-driven grid and water network upgrades. Greater London contractors facing planning permission volatility prefer monthly structures to preserve termination flexibility.
- Weekly:Seven-day rates with scaled discounts versus daily pricing serve medium-duration commercial construction with moderate schedule certainty.
- Daily:Spot rates with premium pricing accommodate emergency replacement and short-notice project startups, though utilization rates fluctuate seasonally.
Monthly structures claim the largest transaction volume; long-term leases are climbing the fastest on infrastructure developer risk transfer preferences.
Application:
End-use concentration in public infrastructure creates demand visibility divergence versus private commercial development exposure.
- Road Construction:Motorway widening and junction improvement schemes across England's strategic road network require coordinated fleets of excavators, dozers, and compactors with night-work lighting packages. National Highways procurement frameworks favor rental providers with multi-region depot density and 24-hour breakdown response.
- Bridge Building:Span construction and deck replacement projects demand specialized piling rigs and heavy-lift crawler cranes with engineered lift plans. Scottish bridge maintenance programs are concentrating crawler crane demand in northern England and Scottish depot catchments.
- Site Preparation:Bulk earthworks and ground remediation precede vertical construction, with equipment specifications varying by soil classification and contamination status.
- Material Handling:Aggregate processing and waste sorting operations utilize wheel loaders and hydraulic grabs with high hourly utilization rates.
- Demolition:High-reach excavators with specialized attachments and dust suppression systems serve urban deconstruction in Greater London's low-emission zones.
Road construction absorbs the bulk of fleet deployment hours; bridge building is gaining share fastest on multi-year project pipelines.
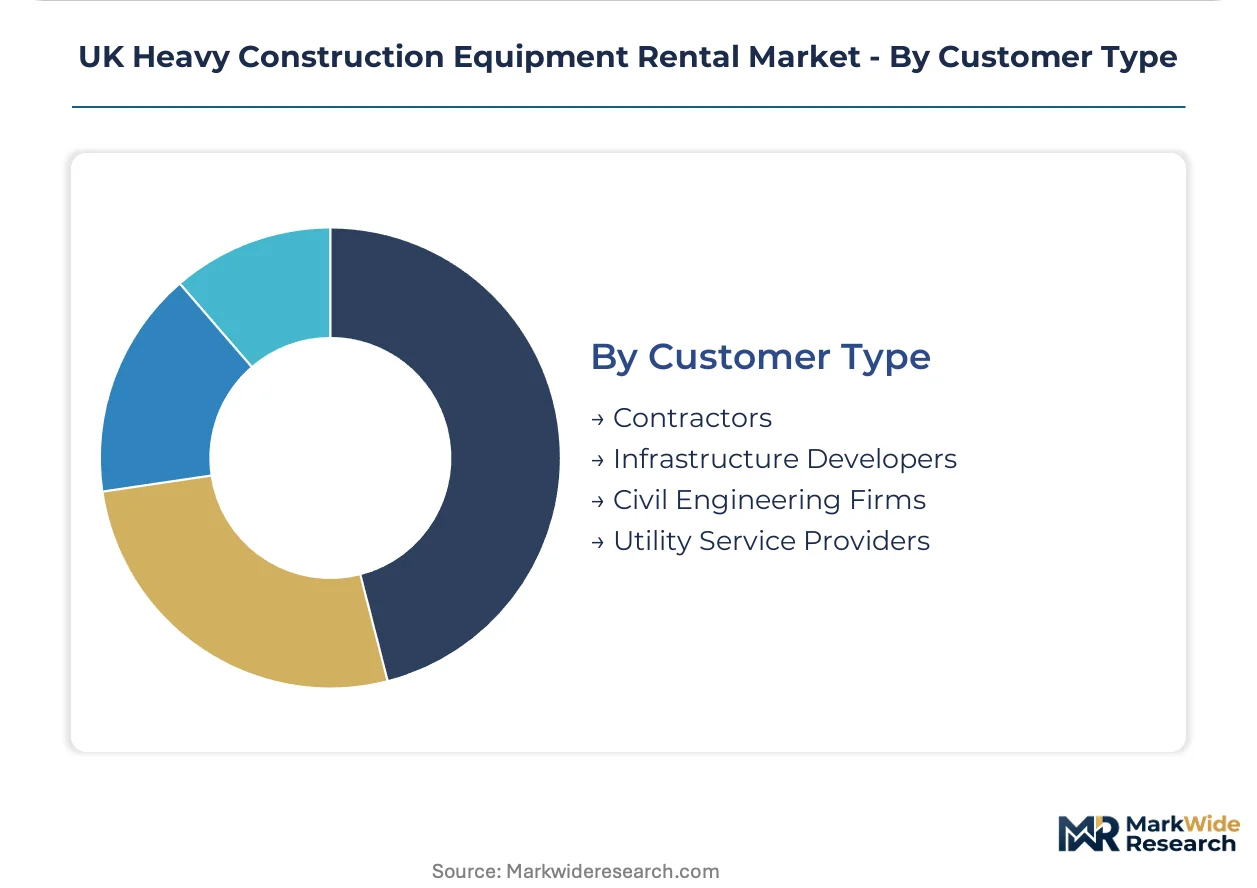
Customer Type:
Buyer scale and procurement sophistication determine contract structure complexity and service bundling requirements.
- Infrastructure Developers:National contractors with consolidated project portfolios negotiate master service agreements covering equipment, maintenance, and operator certification compliance across multiple concurrent sites. The Building Safety Regulator's emerging competence frameworks are extending these agreements to include advisory services on equipment specification and operator training.
- Utility Service Providers:Water and energy network operators facing regulatory-mandated infrastructure renewal are expanding rental durations for trenching and cable-laying equipment. Northern England utility contractors with aged diesel fleets face the steepest compliance cliffs under Environment Agency emissions phase-outs.
- Contractors:Regional construction firms with project-specific equipment needs rely on spot rental and short-term contracts with higher rate exposure.
- Civil Engineering Firms:Specialist groundworks and drainage contractors fragment demand across shorter rental windows with specialized attachment requirements.
Infrastructure developers absorb the bulk of provider revenue concentration; utility service providers are expanding most quickly on regulatory-driven network investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK infrastructure investment concentrates across three distinct economic corridors, each exhibiting divergent equipment utilization patterns and regulatory exposure profiles that reshape rental provider depot strategies.
Greater London
Low-emission zone enforcement and site access constraints are fragmenting diesel equipment deployment across commercial development projects. The Greater London Authority's tightening air quality standards are accelerating electric excavator and crane uptake among demolition and high-rise contractors. Canary Wharf and King's Cross regeneration schemes are absorbing dedicated crawler crane fleets for extended durations.
Midlands
HS2 Phase One earthworks between Birmingham and London are locking in multi-year excavator and dozer commitments from national rental providers. National Highways procurement frameworks favor fleet operators with rapid-response maintenance depots along the M6 and M1 corridors. Birmingham's emerging logistics hub density is creating underpenetrated territory for regional service expansion.
North England
Utility network upgrades across Yorkshire and Lancashire are expanding monthly rental structures for trenching equipment among water and energy contractors. Environment Agency emissions phase-outs are forcing retirement of aged diesel inventories in Manchester and Leeds catchment areas. Scottish border infrastructure programs are concentrating crawler crane demand in Newcastle and Carlisle depot networks.
Scotland
Bridge maintenance programs and renewable energy construction are sustaining specialized lifting equipment demand across Glasgow and Edinburgh metropolitan zones. Scottish environmental regulations diverge from English inspection intervals, forcing fragmented fleet management systems for cross-border operators. Aberdeen's decommissioning sector is absorbing heavy-lift capacity for offshore platform dismantling.
Wales
Coastal defense and flood management schemes are driving seasonal equipment surges along Cardiff and Swansea corridors. Welsh Government infrastructure procurement favors rental providers with bilingual operator certification programs and localized maintenance presence. Rural road improvement contracts fragment demand across shorter rental windows with specialized attachment requirements.
UK Heavy Construction Equipment Rental Market Competitive Landscape
Established rental groups occupy the standard tier with national fleet scale; emerging specialists pursue electrification and urban compact equipment niches. The UK market structures around three operational archetypes: multi-region fleet aggregators with depot density, urban-focused compact equipment specialists, and regional anchors with localized service intensity. Consolidation pressure is intensifying as tier-one contractors demand master service agreements spanning equipment, maintenance, and compliance advisory. Geographic expansion and portfolio electrification represent the dominant competitive vectors.
Among national-scale fleet operators, Ashtead Group plc and Sunbelt Rentals Ltd exemplify the multi-region aggregator archetype with coverage density across England's infrastructure corridors. HSS Hire Service Group Ltd occupies a position within the urban specialization tier, while GAP Hire Solutions anchors northern England and Scottish operations with regional service concentration. These three entities collectively represent the competitive spectrum from national scale through metropolitan focus to territorial density.
| Leading Market Players |
|---|
| HSS Hire Service Group Ltd |
| Loxam |
| Ashtead Group plc |
| Ainscough |
| Boels Rental |
| Sunbelt Rentals Ltd |
| GAP Hire Solutions |
| Flannery |
| Speedy Hire plc |
| Others |
Pricing and Supply Chain Analysis
Infrastructure developer consolidation into master service agreements is compressing day-rate premiums and forcing rental providers to absorb residual value risk through longer-term fixed-rate structures. This procurement shift concentrates pricing power with tier-one contractors while fragmenting spot-market yield for smaller fleet operators.
Pricing Analysis
Volume concentration in monthly and long-term lease structures trades margin predictability for utilization certainty, with three-tier pricing stratification across premium electric-hybrid units, standard compliant diesel, and economy-tier legacy equipment approaching phase-out. Price differentiation hinges on emissions certification tier under Environment Agency NRMM standards and bundled maintenance service levels. Cost compression in diesel equipment intensifies as residual values deteriorate ahead of compliance deadlines. Utility service providers exhibit highest price sensitivity due to regulatory-mandated budget cycles, while HS2 contractors accept premium pricing for guaranteed availability clauses.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese OEMs for high-capacity crawler crane chassis and hydraulic system components. Equipment manufacturing draws from Swedish steel for structural fabrication, South Korean battery cells for electric drivetrains, and Italian hydraulic pumps for precision control systems. Tariff exposure on European-origin components threatens margin stability for UK-assembled fleets. Distribution runs through regional depot networks with 24-hour parts logistics, concentrating spare inventory in Midlands and northern England catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK heavy construction equipment rental is consolidating around providers with capital depth to electrify fleets and absorb residual value risk, squeezing mid-scale operators unable to finance compliant inventory refresh cycles.
For Market Incumbents: Deploy backward integration into certified technician training programs to capture Building Safety Regulator advisory revenue streams. Lock in multi-year master service agreements with HS2 and National Highways contractors before tier-two competitors secure depot density along Birmingham-Manchester corridors. Electric equipment maintenance capability scarcity threatens utilization rates if high-voltage repair turnaround extends beyond contract penalty thresholds. For New Entrants and Emerging Players: Regional civil engineering firms with fragmented spot-rental needs represent the most penetrable buyer archetype. Target Midlands logistics hub expansion zones with rapid-response maintenance depots, exploiting underpenetrated territory between established national networks. Bundle mobile battery storage with electric excavator packages to differentiate from incumbent diesel-heavy portfolios. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing localized service density and electric fleet transition momentum given Environment Agency compliance deadlines. Acquisition candidates with Scottish border infrastructure exposure and bilingual certification capabilities align with divergent regulatory inspection intervals. Monitor HS2 Phase Two procurement announcements as volume inflection signal for northern England fleet utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Transition | Environment Agency NRMM phase-outs force capital-intensive diesel replacement with compliant hybrid and battery-electric units. |
| Regional Depot Expansion | Midlands logistics corridors between Birmingham and Manchester present underpenetrated density for rapid-response maintenance infrastructure. |
| Master Service Agreements | Tier-one infrastructure developers consolidate procurement across equipment, maintenance, and operator certification compliance. |
| Mobile Power Bundling | Grid-scale battery storage co-location with electric equipment packages serves remote construction sites lacking grid connection. |
| Technician Certification Investment | High-voltage drivetrain maintenance skills lag fleet electrification timelines, creating captive service revenue potential. |
Research Methodology
Document review covered Environment Agency emissions regulations, Health and Safety Executive inspection standards, and National Highways procurement frameworks, complemented by interviews with fleet operations directors at national rental providers, maintenance managers at regional depot networks, procurement leads at tier-one infrastructure contractors, and utility service provider equipment planners. Secondary validation drew from Construction Equipment Association trade statistics, UK customs import records for machinery components, and company regulatory filings. Bottom-up equipment deployment estimates triangulated against top-down infrastructure investment forecasts.
Market sizing and growth projections reflect segmentation across equipment type, rental duration structure, application, and customer archetype, with electric-diesel fleet mix modeled as a cross-cutting dimension. CAGRs were derived from infrastructure pipeline analysis and regulatory compliance timeline impacts. Forecast inputs incorporated HS2 phase progression, Environment Agency phase-out enforcement schedules, and Building Safety Regulator emerging competence framework implementation.
Revisions become necessary when infrastructure project delays, emissions regulation enforcement acceleration, or battery supply chain disruptions materialize beyond modeled assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Jackhammer Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
Truck Crane Market
Construction Equipment
Concrete Testers Market