
 Earthmoving Equipment Undercarriage Market | 2026-2036
Earthmoving Equipment Undercarriage Market Size, Share, and Industry Trends Forecast 2026-2036
Earthmoving Equipment Undercarriage Market Foresight
EPA Tier 4 Final and Stage V emissions rules is decoupling the cost-of-entry calculus for undercarriage suppliers serving North American and European fleets. Caterpillar Inc. leverages captive foundry capacity to control alloy formulations for high-wear track shoes. Komatsu Ltd. anchors its aftermarket position through proprietary diagnostic tools that predict roller fatigue. Berco SpA differentiates via specialized heat-treatment lines serving Italian and Polish OEM assembly plants.
Earthmoving equipment undercarriage refers to the tracked propulsion and support system comprising track shoes, idlers, rollers, and sprockets, typically fabricated from boron or manganese alloy steel through forged or cast processes and heat-treated to 450-550 Brinell hardness for abrasion resistance. Its primary purpose is to distribute machine weight across soft or uneven terrain while providing tractive force for excavation, grading, and material transport operations. Track shoes and rollers together capture the dominant share of component value, with rollers representing the fastest-replacement cycle due to direct ground contact loading. OEM supply agreements concentrate margin pools with excavator and dozer manufacturers, while aftermarket channels serve the larger installed base of aging construction and mining fleets.
The US EPA, EU Stage V framework, and China's MEE jointly enforce particulate and NOx limits that compel lighter undercarriage designs to offset powertrain aftertreatment weight. ISO 10265 and JIS standards further specify fatigue-test protocols for track link assemblies, creating compliance barriers for non-certified entrants. Stakeholders must monitor how alloy price volatility and regional emissions phase-in schedules reshape sourcing decisions between forged and cast component strategies.
Market Dynamics
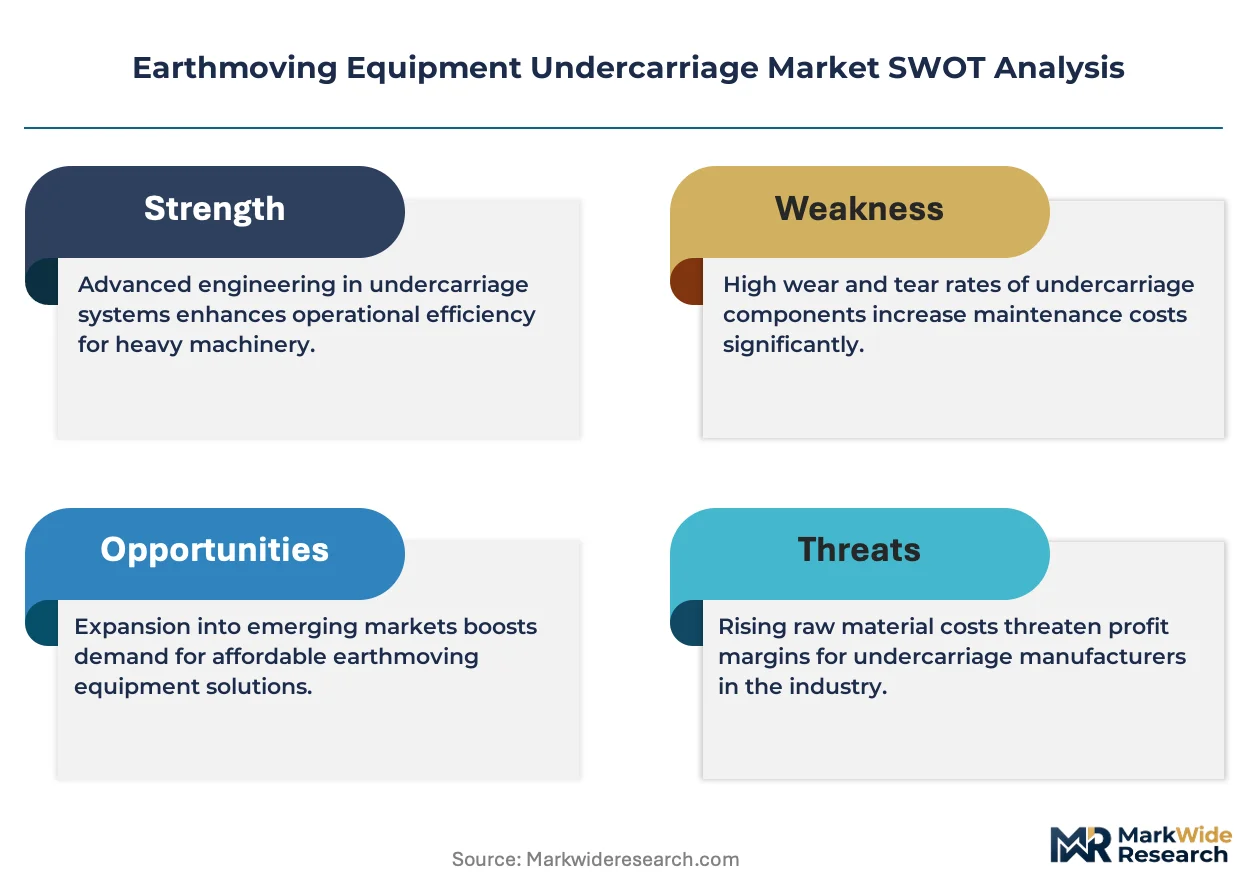
EPA Tier 4 Final and Stage V emissions rules are forcing undercarriage suppliers to engineer lighter track shoe and roller assemblies that offset powertrain aftertreatment weight penalties without sacrificing 450-550 Brinell hardness specifications.
Growth Catalysts
- Mining fleet renewal:Australian mining operators are accelerating replacement cycles for aging dozer and excavator undercarriages to maintain production targets amid ore grade decline.
- Emissions-driven material innovation:EPA and Stage V weight restrictions are pulling boron-manganese alloy formulations into mainstream track component specifications previously dominated by plain carbon steels.
- Infrastructure corridor development:China's western provinces are sustaining excavator deployment rates that consume roller assemblies at 1.5x replacement frequency versus eastern construction markets.
Market Restraints
- Alloy input volatility:Manganese and boron price swings compress margin predictability for forged track link producers locked into annual OEM supply agreements.
- Foundry capacity concentration:High-specification heat-treatment capacity for 500+ Brinell components clusters in northeastern Chinese industrial zones, creating single-source vulnerability.
- Technical substitution ceiling:Polymer track pad alternatives remain structurally incompatible with mining dozer operating weights above 50 tonnes, capping addressable market expansion.
Strategic Opportunities
- Western China penetration:Xinjiang and Sichuan infrastructure corridors remain underserved by premium undercarriage distributors, creating first-mover channel establishment potential.
- Predictive maintenance convergence:Integration of roller wear sensors with telematics platforms enables subscription-based component lifecycle management contracts.
- Remanufacturing regulatory tailwind:EU circular economy directives and China's dual carbon goals are elevating remanufactured track shoe acceptance in public procurement specifications.
Industry Challenges
- Heat-treatment skill scarcity:Specialized technicians capable of maintaining ±10 Brinell hardness tolerance across 2-meter track link batches are concentrated among retiring workforce cohorts in European and Japanese supplier bases.
- ISO 10265 certification timeline:Fatigue-test protocol compliance for new alloy formulations requires 18-24 month validation cycles that delay product launches relative to customer bid windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthmoving Equipment Undercarriage Market |
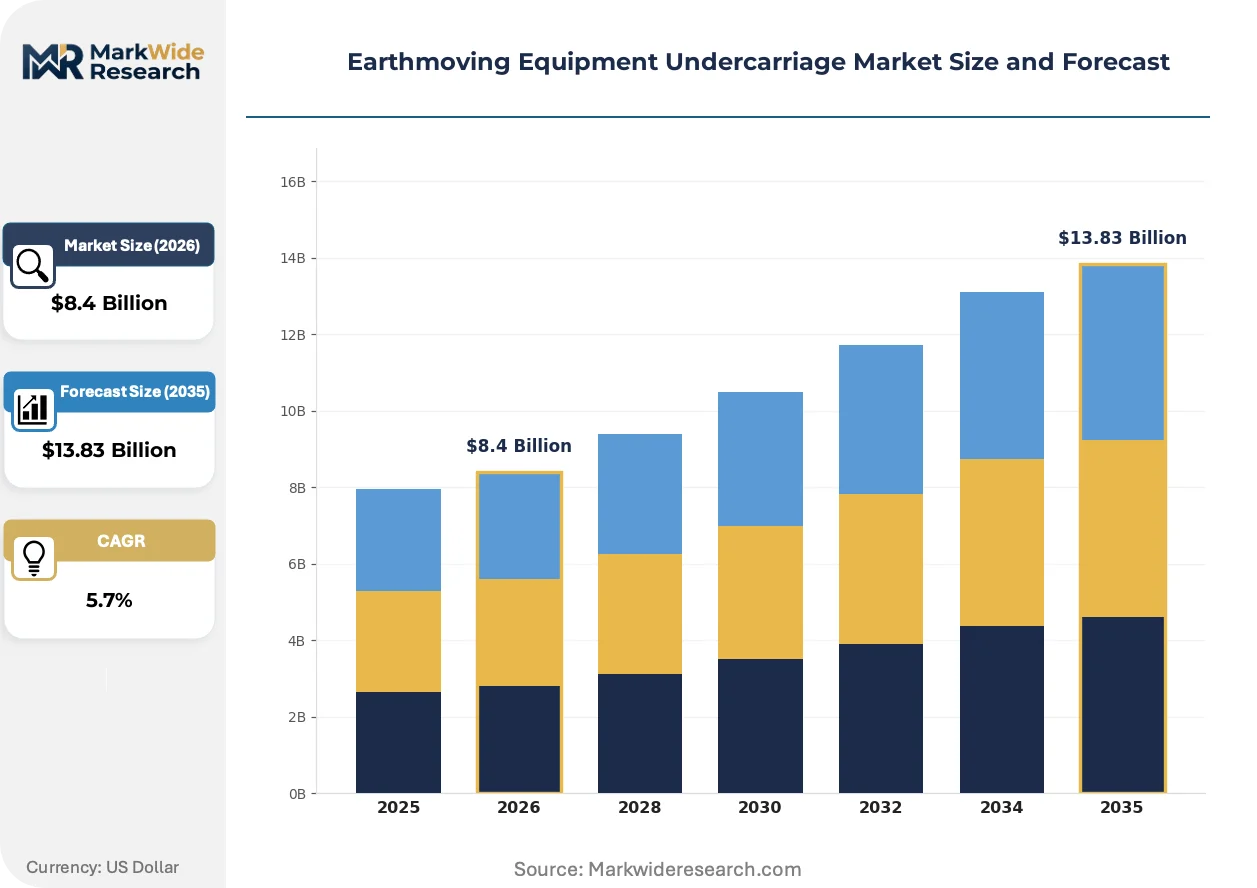
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Track Shoes, Idlers, Rollers, Sprockets Application: Excavation, Material Handling, Construction, Demolition Market Segment: OEM, Aftermarket, Replacement Parts, Custom Fabrication End User: Contractors, Rental Companies, Government Agencies, Mining Operations |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., John Deere, Berco SpA, ITR America LLC, Liebherr Group, Hitachi Construction Machinery, Volvo Construction Equipment, Titan International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthmoving Equipment Undercarriage Market Shifts & Advancements
Digitalization of component wear monitoring and alloy formulation science are compressing replacement cycle forecasting from calendar-based to condition-based models across mining and construction fleets.
Induction-hardened surface layers applied via precision-controlled frequency heating are rewriting durability benchmarks for track shoe ground-engaging surfaces. Large-scale copper and iron ore miners in Western Australia are specifying these treatments for 400+ hour monthly utilization machines. The technology is compressing total cost-of-ownership calculations that previously favored lowest-first-cost procurement.
EPA Tier 4 Final enforcement through 2027 is mandating undercarriage weight reductions of 8-12% on new excavator platforms to preserve hydraulic breakout force. OEM engineering teams are responding with hollow-core roller designs and reduced-section track link profiles. North American crawler dozer configurations are experiencing the most acute design tension between emissions compliance and ground pressure maintenance.
Condition-based procurement is displacing scheduled replacement programs among mid-size construction contractors. Equipment lessors are unbundling undercarriage wear coverage from base machine rates, transferring component risk to specialized aftermarket suppliers. This behavioral shift is most visible in German and French rental fleets where telematics penetration exceeds 70% on tracked machines.
Earthmoving Equipment Undercarriage Market Segmentation
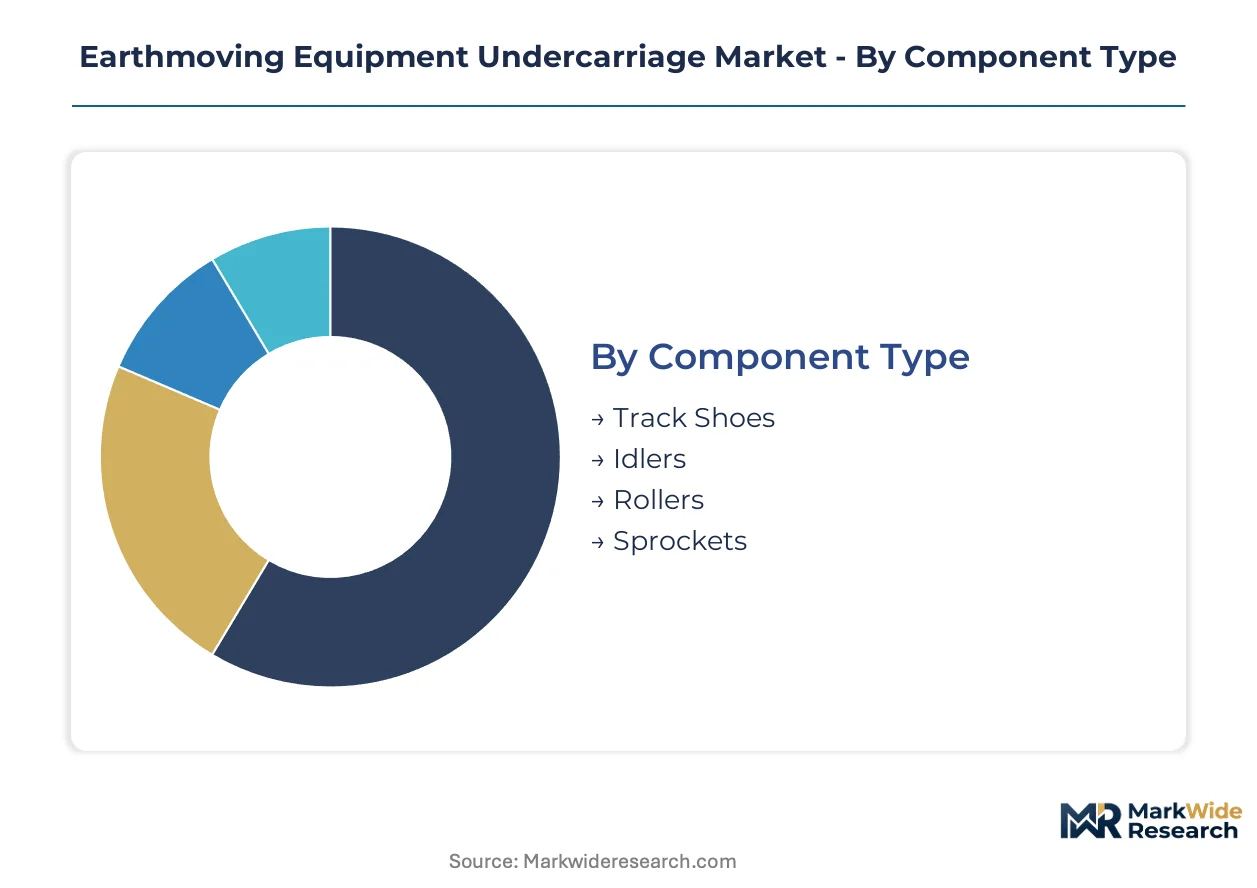
Undercarriage component selection varies sharply by duty cycle intensity and procurement channel economics. Mining operators prioritize Brinell hardness ratings above replacement cost, while rental fleets optimize for interchangeability across machine classes.
Component Type:
Buyers differentiate primarily by wear surface exposure and replacement frequency rather than unit cost.
- Track Shoes:Ground-engaging plates forged from boron-manganese alloy and heat-treated to 450-550 Brinell hardness. Australian iron ore mines specify induction-hardened surface layers for 400+ hour monthly utilization, compressing total cost-of-ownership calculations that previously favored lowest-first-cost procurement.
- Rollers:Load-bearing wheels maintaining track alignment under dynamic ground pressure. Western China infrastructure corridors consume roller assemblies at 1.5x replacement frequency versus eastern construction markets due to abrasive soil conditions and extended operating hours.
- Idlers:Front-mounted tensioning wheels guiding track engagement. Idler demand concentrates in high-hour mining fleets where tension maintenance prevents derailment downtime.
- Sprockets:Drive components meshing with track links to transmit engine torque. Sprocket replacement trails other components but commands premium pricing for final-drive-integrated designs.
Volume sits with track shoes; growth tilts toward rollers.
Application:
Operating weight and ground disturbance severity determine alloy specification and warranty terms.
- Excavation:Crawler machines deploying hydraulic breakout force in trenching and foundation work. EPA Tier 4 Final weight restrictions are forcing hollow-core roller designs and reduced-section track link profiles on new excavator platforms.
- Construction:General grading and site preparation with intermittent high-load events. German and French rental fleets are unbundling undercarriage wear coverage from base machine rates, transferring component risk to specialized aftermarket suppliers.
- Material Handling:Continuous loading operations at ports and waste facilities. Material handling applications stress idler bearings through repetitive directional changes.
- Demolition:Abrasive debris environments requiring enhanced seal protection. Demolition contractors specify labyrinth-sealed roller cartridges to extend service intervals.
Construction commands installed base volume; excavation shows the steepest specification upgrade trajectory.
Market Segment:
Channel selection reflects fleet scale and technical service requirements.
- OEM:Factory-installed undercarriage systems under machine warranty. OEM supply agreements concentrate margin pools with excavator and dozer manufacturers through multi-year alloy formulation lock-ins.
- Aftermarket:Post-warranty replacement through independent distributors. Condition-based procurement is displacing scheduled replacement programs among mid-size contractors as telematics penetration exceeds 70% on tracked machines in developed markets.
- Replacement Parts:Component-level sourcing for in-house maintenance operations. Replacement part buyers prioritize inventory compatibility across mixed fleet vintages.
- Custom Fabrication:Application-specific modifications for extreme duty cycles. Custom fabrication serves narrow-gauge mining configurations and amphibious machine conversions.
OEM captures specification-setting power; aftermarket claims transaction volume.
End User:
Procurement sophistication and total cost visibility separate institutional from opportunistic buyers.
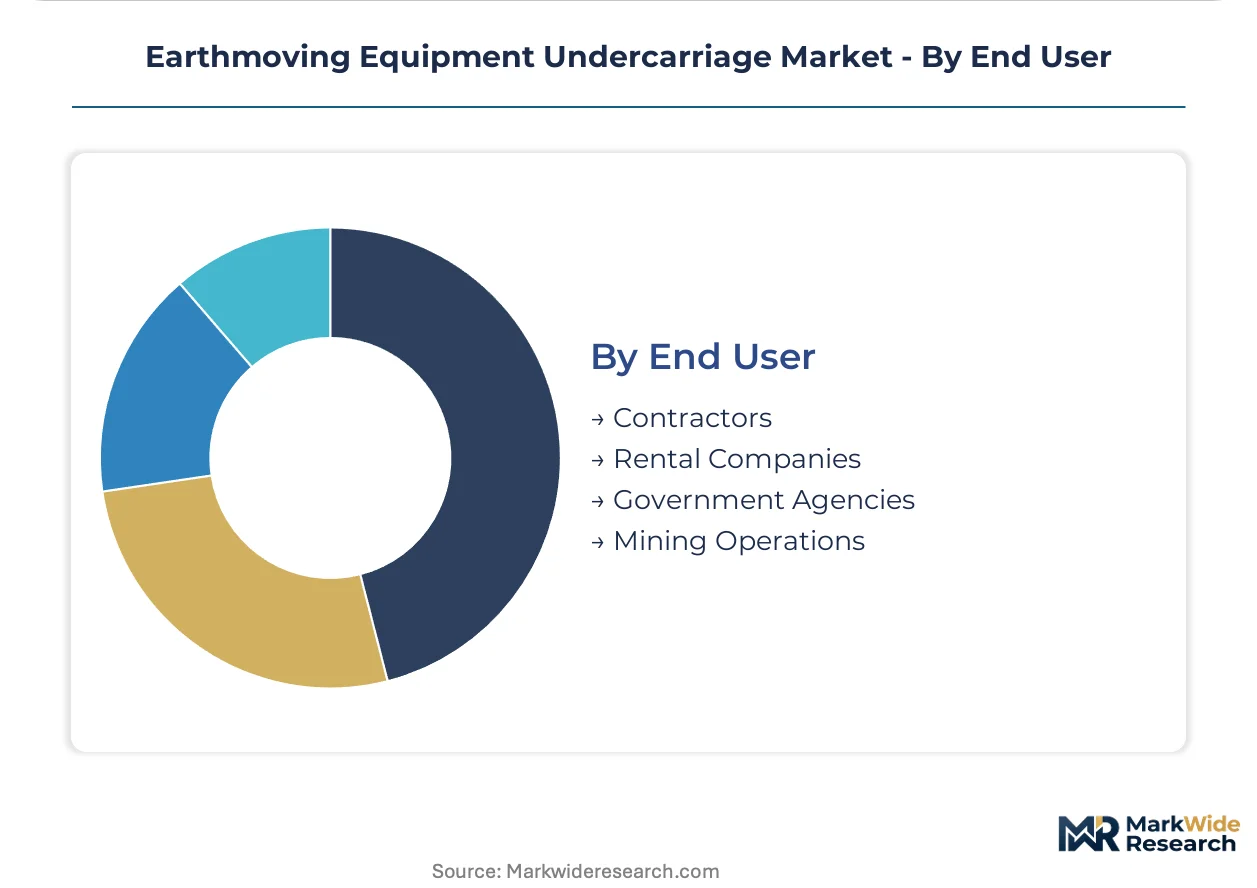
- Mining Operations:High-utilization fleets with dedicated maintenance infrastructure. Australian mining operators are accelerating replacement cycles for aging dozer and excavator undercarriages to maintain production targets amid ore grade decline.
- Contractors:Project-based equipment owners with variable utilization patterns. Contractors balance first-cost pressure against downtime risk in competitive bid environments.
- Rental Companies:Fleet lessors unbundling component risk from hourly rates. Equipment lessors in Germany and France are transferring undercarriage wear coverage to specialized aftermarket suppliers through telematics-enabled usage tracking.
- Government Agencies:Public procurement bound by circular economy directives. EU circular economy directives and China's dual carbon goals are elevating remanufactured track shoe acceptance in public procurement specifications.
Mining operations anchor premium specification demand; rental companies are restructuring procurement toward outcome-based contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's western infrastructure corridors operate as a de facto special economic zone for undercarriage consumption, with Xinjiang and Sichuan provinces sustaining excavator deployment rates that exceed eastern construction markets. Mining operations in Western Australia and the Pilbara region anchor premium specification demand for high-Brinell track components. EPA Tier 4 Final enforcement across the United States is mandating undercarriage weight reductions that reshape North American supplier engineering priorities.
United States
Construction fleet lessors in Texas and the Southeast are unbundling undercarriage wear coverage from base machine rates, transferring component risk to aftermarket specialists. EPA Tier 4 Final rules through 2027 mandate 8-12% weight reductions on new excavator platforms, forcing hollow-core roller designs and reduced-section track link profiles. Foundry capacity for 500+ Brinell heat-treatment clusters in Illinois and Ohio industrial zones, serving Caterpillar and John Deere assembly networks.
China
Xinjiang and Sichuan infrastructure corridors consume roller assemblies at 1.5x replacement frequency versus eastern construction markets due to abrasive soil conditions. MEE emissions standards and dual carbon goals are elevating remanufactured track shoe acceptance in public procurement specifications. High-specification heat-treatment capacity concentrates in northeastern Chinese industrial zones around Shenyang and Dalian, creating single-source vulnerability for 450-550 Brinell components.
Australia
Iron ore miners in Western Australia's Pilbara region are accelerating replacement cycles for aging dozer and excavator undercarriages to maintain production targets amid ore grade decline. TGA-equivalent mining safety frameworks enforce fatigue-test protocols for track link assemblies in high-utilization fleets. Perth and Brisbane serve as distribution hubs for premium induction-hardened track shoes specified for 400+ hour monthly utilization machines.
Germany
Rental fleets in Bavaria and North Rhine-Westphalia exhibit telematics penetration exceeding 70% on tracked machines, enabling condition-based procurement that displaces scheduled replacement programs. EU circular economy directives elevate remanufactured component acceptance in public infrastructure tenders. KBA-aligned equipment certification standards create compliance barriers for non-EU undercarriage suppliers seeking OEM supply agreements.
Japan
Construction machinery manufacturers in Aichi and Osaka prefectures anchor proprietary diagnostic tool development for roller fatigue prediction. JIS standards specify fatigue-test protocols that delay new alloy formulation launches by 18-24 months relative to customer bid windows. METI industrial policy supports captive foundry investments for boron-manganese alloy formulation control in premium track component production.
Earthmoving Equipment Undercarriage Market Competitive Landscape
Japanese and American producers anchor the premium tier; Italian and Chinese specialists hold positions in regional aftermarket distribution. The vendor base organizes around three strategic archetypes: integrated OEMs with captive foundry capacity, independent component specialists with heat-treatment differentiation, and regional fabricators serving price-sensitive construction fleets. Competitive moves concentrate on backward integration into alloy supply and telematics-enabled service contract expansion.
Among integrated OEMs, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by captive manufacturing infrastructure and proprietary diagnostic platforms. Berco SpA represents the specialist archetype, with Italian and Polish operational footprints serving European OEM assembly networks. These three companies exemplify how geographic concentration of heat-treatment expertise and alloy formulation control separates premium-tier positioning from commodity aftermarket competition.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| John Deere |
| Berco SpA |
| ITR America LLC |
| Liebherr Group |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| Titan International |
| Others |
Supply & Pricing Matrix
Manganese and boron alloy price indices cascade through three distinct pricing tiers that stratify across premium induction-hardened track shoes, standard heat-treated rollers, and economy-grade cast components serving price-sensitive construction contractors in emerging markets.
Pricing Analysis
Lead-time compression commands measurable premiums in the undercarriage market, with Australian mining operators paying substantial markups for guaranteed 30-day delivery of 500+ Brinell rollers while spot inventory of plain carbon steel track shoes trades at discounts in oversupplied Chinese distribution channels. Three-tier pricing structure across premium, standard, and economy levels reflects hardness certification grade and OEM supply agreement status, with EPA Tier 4 Final compliance costs intensifying price erosion in the North American hollow-core roller segment. Mining fleet procurement teams exhibit lowest price sensitivity due to total cost-of-ownership modeling, whereas mid-size rental companies in France and Germany demonstrate acute responsiveness to per-hour component rates.
Supply Chain Analysis
Remanufacturing flows for track shoes and rollers are gaining structural importance as EU circular economy directives and China's dual carbon goals elevate acceptance of refurbished components in public procurement specifications. High-specification heat-treatment capacity concentrates in northeastern Chinese industrial zones around Shenyang, Italian foundry clusters near Milan, and Japanese steel processing centers in Aichi prefecture. Boron-manganese alloy formulations and precision induction-hardening equipment constitute critical input dependencies, with single-source vulnerability in 500+ Brinell heat-treatment lines creating exposure to regional supply disruptions. Distribution runs through OEM captive networks for new machine builds and independent aftermarket channels serving the aging installed base across Australian mining corridors and Western China infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a backward integration race where captive control over boron-manganese alloy formulations and proprietary heat-treatment protocols separates premium-tier positioning from commoditized aftermarket competition.
For Market Incumbents: Anticipate margin compression from Chinese heat-treatment capacity expansion by locking multi-year alloy supply agreements with Australian and Brazilian mining operators before contract renewal windows close. Prioritize in-house production of induction-hardening equipment to defend specification-setting power against independent component specialists gaining telematics-enabled service contract traction.
For New Entrants and Emerging Players: Begin with aftermarket channel establishment in Xinjiang and Sichuan provinces where premium undercarriage distributor coverage remains sparse and infrastructure investment sustains elevated roller consumption rates. Target predictive maintenance software integration as the primary go-to-market wedge, partnering with equipment lessors in Germany and France to unbundle component risk from base machine hourly rates.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap heat-treatment specialists with ISO 10265 certification capabilities in European industrial zones where retiring workforce cohorts are concentrating technical scarcity. Long-term viability in this market hinges on telematics-enabled lifecycle management contract penetration rather than transactional component sales; monitor Australian mining fleet telematics adoption rates as the decisive inflection signal for subscription-based revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive boron-manganese formulation control insulates Caterpillar and Komatsu from raw material price volatility. |
| Predictive Maintenance Platform Launch | Roller wear sensor integration with telematics enables subscription contracts displacing scheduled replacement programs. |
| Remanufacturing Capacity Expansion | EU circular economy directives elevate refurbished track shoe acceptance in public infrastructure tenders. |
| Western China Distribution Buildout | Xinjiang and Sichuan corridors remain underserved by premium undercarriage distributors despite elevated consumption. |
| Heat-Treatment Certification Investment | ISO 10265 compliance creates 18-24 month barriers delaying competitor product launches relative to bid windows. |
Research Methodology
Multi-period observation of manganese alloy price indices, Australian mining fleet utilization rates, and EPA emissions phase-in schedules anchored the trend analysis, supplemented by interviews with maintenance directors at Pilbara iron ore operations, OEM procurement teams at Caterpillar and Komatsu, aftermarket service heads at European rental fleets, and heat-treatment specialists in Italian and Chinese foundry clusters. Secondary validation drew from customs trade data tracking boron steel imports, SEC filings of listed construction equipment manufacturers, ISO certification registries, and MEE emissions compliance disclosures. Bottom-up component demand modeling triangulated against top-down machinery production forecasts to establish market sizing boundaries.
Segment-weighting approaches applied differential growth assumptions across track shoes, rollers, idlers, and sprockets based on replacement frequency divergence between mining and construction duty cycles. Excavation versus construction versus material handling applications received distinct alloy specification and warranty term parameters. Regional modeling incorporated Western Australia's premium specification propensity, China's western infrastructure investment intensity, and North American weight reduction mandates. CAGRs were derived from installed base aging curves and fleet renewal timing rather than extrapolated shipment data.
Alloy price volatility, emissions regulation acceleration, and telematics adoption speed are the dominant revision risks that could compress or extend replacement cycle forecasts. Practitioners should monitor manganese futures pricing, MEE enforcement intensity, and German rental fleet sensor penetration rates for early signals of demand trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crane Buffer Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Dock Door Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Rotary Hammers Market