
 Egypt Construction Market | 2026-2036
Egypt Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Construction Market Analysis
Egypt's updated building code is restructuring capital requirements for contractors bidding on state megaprojects. The Arab Contractors leverages its vertically integrated supply chain to dominate transport infrastructure. Hassan Allam Holding anchors its position through captive aggregate quarries and marine construction capabilities. Orascom Construction competes via technology leadership in energy-efficient building envelopes for commercial towers.
Egypt construction encompasses the erection, alteration, and repair of buildings and civil works using cement, steel, aggregates, and timber composites, with structural concrete typically specified at 25-40 MPa compressive strength for high-rise frames. Residential project types currently absorb the largest share of material volumes as informal housing upgrades formalize, while green construction methods represent the fastest-expanding segment as BREEAM and LEED-aligned specifications penetrate premium commercial developments. Infrastructure project types concentrate the heaviest equipment and longest contract durations, creating distinct margin pools separate from speculative residential cycles.
Egypt's Housing and Building National Research Center sets material testing protocols, while the Egyptian Organization for Standardization and Quality enforces cement fineness and rebar ductility benchmarks that filter market access. The General Authority for Investment and Free Zones ties construction licensing to local content thresholds, redirecting procurement toward domestic steel and aggregate producers. Stakeholders must monitor how carbon accounting rules reshape eligibility for sovereign-guaranteed project finance before committing to long-dated equipment positions.
Market Dynamics
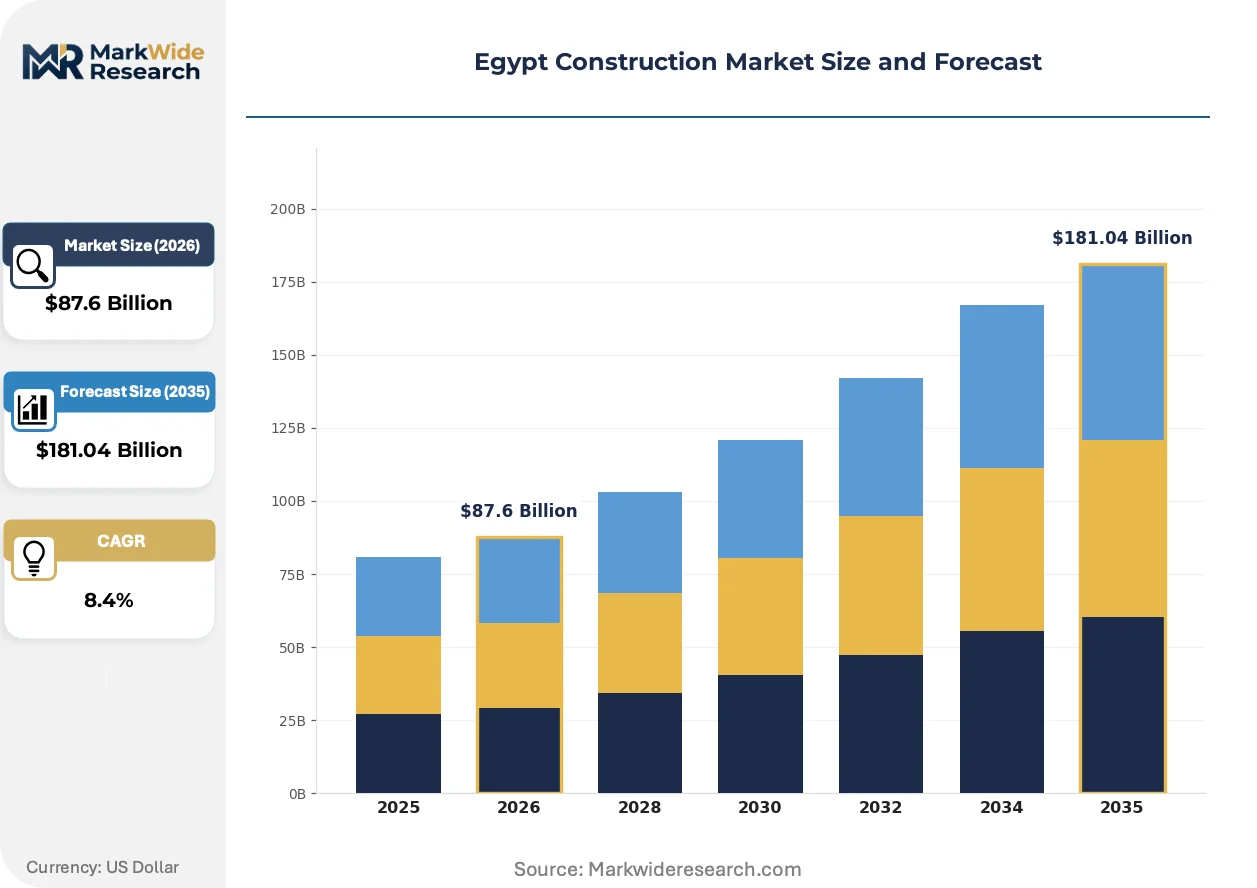
Egypt's sovereign-backed megaproject pipeline is compressing contractor margins while simultaneously locking in decade-long demand visibility for steel and cement producers. The New Administrative City's phased handover schedule creates synchronized procurement waves that amplify material price volatility.
Growth Catalysts
- New Administrative City Development:Government-mandated relocation of ministries and foreign embassies generates sustained institutional construction demand. The 700 square kilometer greenfield site requires complete utility and transport infrastructure buildout.
- Suez Canal Economic Zone incentives:The General Authority for Investment and Free Zones offers 50-year tax holidays and full foreign ownership rights for industrial zone developers. These terms attract logistics and manufacturing facility investments.
- Seismic code modernization:Egypt's updated building code mandates base isolation systems and ductile detailing for structures above 12 stories. This specification shift elevates engineering service intensity per project.
Market Restraints
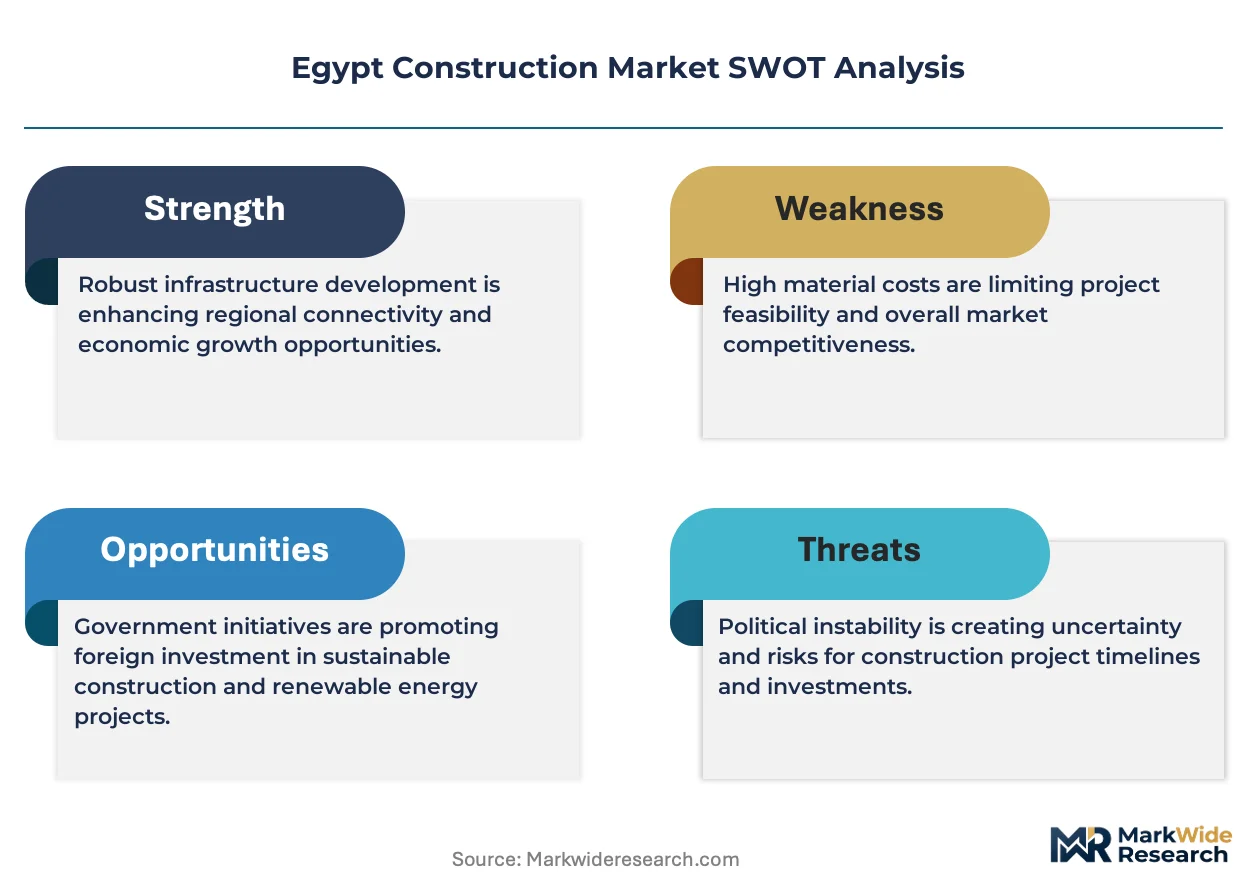
- Steel input cost volatility:Egypt's dependence on imported billets and scrap exposes contractors to exchange rate fluctuations. The central bank's foreign exchange rationing periodically disrupts mill operations.
- Cement sector overcapacity:Domestic clinker production exceeds effective demand by approximately 30 million tons annually. This structural surplus compresses pricing power across the value chain.
- Skilled labor scarcity:Formal technical training capacity lags behind megaproject workforce requirements. Informal workers dominate site operations, elevating quality control costs.
Strategic Opportunities
- Upper Egypt corridor development:Sohag, Qena, and Aswan governorates remain underserved by formal construction services. Government social housing programs are redirecting volume southward from saturated Delta markets.
- Green building certification penetration:BREEAM and LEED-aligned specifications are becoming mandatory for premium commercial developments in New Cairo. Early certification capability builds contractor differentiation.
- Modular prefabrication integration:Factory-produced wall panels and bathroom pods reduce site labor dependence. European and Gulf contractors are transferring these methods to Egyptian joint ventures.
Industry Challenges
- Payment cycle elongation:Public sector clients routinely stretch contractor receivables beyond 180 days. Working capital intensity constrains bidder eligibility for large packages.
- Local content compliance complexity:The General Authority for Investment and Free Zones applies varying domestic sourcing thresholds across project types. Documentation requirements delay equipment import clearances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Construction Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $181.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cement, Steel, Aggregates, Wood Project Type: Residential, Commercial, Infrastructure, Industrial End User: Government, Private Developers, Contractors, Investors Construction Method: Traditional, Modular, Prefabrication, Green |
| Companies Covered | The Arab Contractors, Orascom Construction, Hassan Allam Holding, Palm Hills Developments, H.A. Construction, DORRA Group, Rowad Modern Engineering, GAMA Construction, AL-AHLY Development, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Construction Market Emerging Trajectories
Construction methodology in Egypt is pivoting from labor-intensive cast-in-place systems toward industrialized building components. This transition is compressing project timelines while elevating capital requirements for market entry.
High-performance concrete admixtures incorporating silica fume and fly ash are electrifying structural specifications for high-rise frames in the New Administrative City. Commercial tower developers specify 50-60 MPa compressive strength to reduce column footprints. Egyptian ready-mix producers are retrofitting batch plants to accommodate these formulations.
Egypt's Housing and Building National Research Center has mandated thermal performance testing for all envelope materials used in government-subsidized housing. This regulatory intervention elevates insulation specification density across residential segments. Contractors must now document U-values and air permeability metrics to secure occupancy permits.
Developer procurement of construction services is fragmenting from single general contracts toward specialized package bidding. State megaprojects now separate civil works, MEP installation, and finishing trades into distinct tender lots. This disaggregation favors mid-sized specialists with narrow technical depth over traditional full-service contractors.
Egypt Construction Market Segmentation
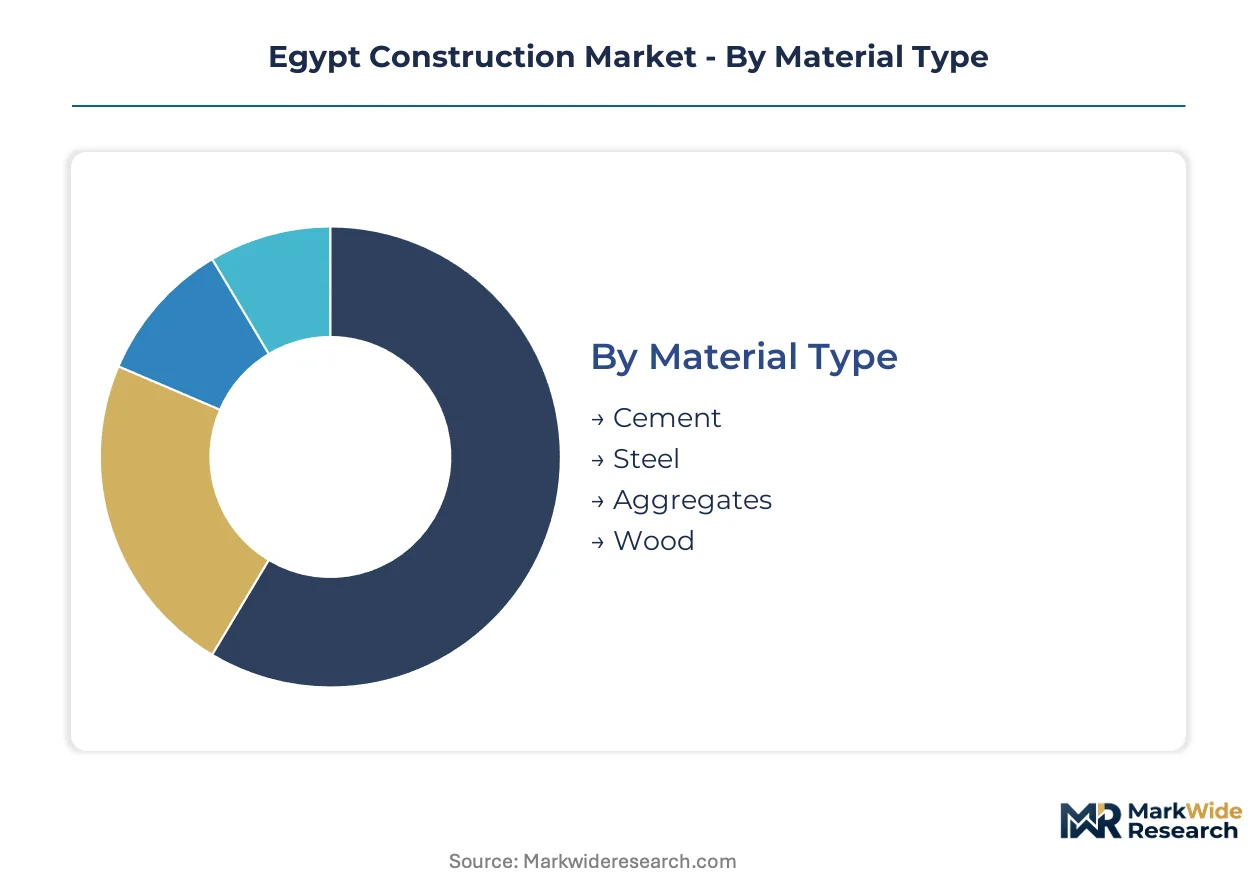
Construction procurement in Egypt fragments across material specifications, project scale, and delivery methodologies. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape contractor positioning.
Material Type:
Buyers select materials based on structural load requirements and local content mandates from the General Authority for Investment and Free Zones.
- Cement:Portland and blended varieties dominate structural concrete formulations. The Housing and Building National Research Center enforces fineness standards that filter import eligibility. New Administrative City megaprojects consume bulk volumes for foundation and superstructure work.
- Steel:Rebar and structural sections specified at 400-500 MPa yield strength per updated seismic codes. Domestic billet shortages force contractors to navigate central bank foreign exchange rationing for imported inputs.
- Aggregates:Crushed limestone from captive quarries supplies ready-mix batching.
- Wood:Imported timber composites serve formwork and finishing applications.
Volume sits with cement; growth tilts toward high-strength steel as seismic specifications tighten.
Project Type:
Contract duration and payment security vary sharply across project categories, dictating working capital deployment strategies.
- Residential:Social housing programs and informal settlement formalization absorb the largest material volumes. Government subsidy mechanisms concentrate demand in the Nile Delta corridor while redirecting social housing investment toward Upper Egypt governorates.
- Infrastructure:Transport and utility megaprojects lock in decade-long demand visibility for heavy equipment operators. The Suez Canal Economic Zone and New Administrative City utility buildouts extend contract durations beyond five years.
- Commercial:Premium tower developments in New Cairo specify BREEAM and LEED-aligned envelope performance.
- Industrial:Manufacturing facility investments concentrate in free zone developments with tax holiday incentives.
Residential commands current volume; infrastructure offers the longest demand visibility.
End User:
Procurement authority determines specification stringency and payment cycle reliability.
- Government:Sovereign-backed megaprojects mandate local content thresholds and seismic compliance documentation. Ministry relocations to the New Administrative City generate sustained institutional construction demand.
- Private Developers:Premium commercial towers in New Cairo drive green certification penetration and high-performance concrete specifications.
- Contractors:Subcontracting specialists capture disaggregated tender lots as state projects fragment civil works from MEP and finishing trades.
- Investors:Industrial zone developers leverage Suez Canal Economic Zone incentives for logistics and manufacturing facilities.
Government anchors procurement volume; private developers are expanding most quickly in premium segments.
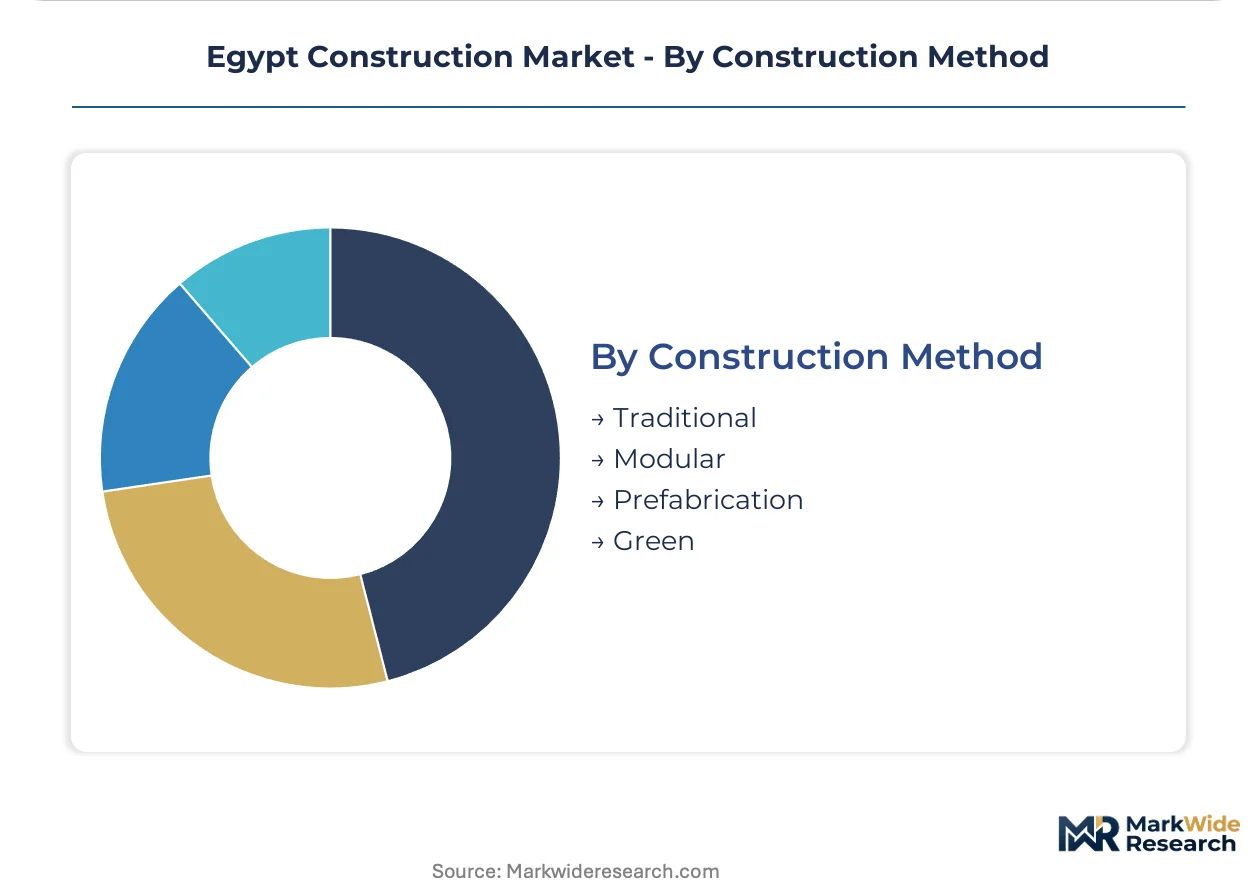
Construction Method:
Labor availability and timeline compression reshape methodology selection across project scales.
- Traditional:Cast-in-place concrete systems retain dominance in residential and infrastructure segments. Informal workforce abundance sustains labor-intensive approaches despite quality control costs.
- Modular:Factory-produced wall panels reduce site labor dependence and accelerate project timelines. European and Gulf contractors transfer these methods to Egyptian joint ventures for social housing programs.
- Prefabrication:Bathroom pods and structural components gain traction in commercial tower developments.
- Green:BREEAM and LEED-aligned specifications become mandatory for premium commercial projects in New Cairo.
Traditional methods retain volume dominance; modular approaches are gaining share fastest as skilled labor scarcity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Economic Zone anchors construction demand concentration across Egypt's strategic corridors. Government incentives redirect investment flows toward underdeveloped territories while established urban centers absorb premium commercial development.
Cairo Governorate
The New Administrative City's phased handover compresses contractor timelines while amplifying material procurement waves. The Housing and Building National Research Center enforces seismic compliance documentation for structures above twelve stories. New Cairo's commercial tower cluster drives BREEAM-aligned envelope specifications as premium developers compete on certification credentials.
Alexandria and the Nile Delta
Informal housing formalization absorbs the largest cement volumes across Egypt's most densely populated corridor. The General Authority for Investment and Free Zones applies local content thresholds that filter steel procurement toward domestic mills. Borg El-Arab's industrial zone concentrates precast concrete manufacturing for social housing programs redirecting volume southward.
Suez Canal Zone
Logistics and manufacturing facility investments leverage fifty-year tax holidays and full foreign ownership rights. The Suez Canal Authority coordinates utility infrastructure buildouts extending contract durations beyond five years. Port Said and Ismailia anchor heavy equipment deployment for industrial zone developers capturing free zone incentives.
Upper Egypt Governorates
Sohag, Qena, and Aswan remain underserved by formal construction services as government social housing redirects investment southward. The Ministry of Housing's subsidized unit programs concentrate demand in corridor cities bypassed by Delta saturation. Aswan's granite quarries supply captive aggregate streams for regional batching operations.
Red Sea Coastal Territory
Tourism and residential resort developments concentrate demand for marine construction capabilities and coastal protection systems. The Red Sea Governorate's environmental regulations elevate engineering service intensity for shoreline projects. Hurghada's hospitality cluster specifies imported timber composites and high-performance concrete for luxury developments.
Egypt Construction Market Vendor Landscape
Nile Delta producers anchor one tier; Upper Egypt specialists hold fragmented positions in social housing corridors. Contractor concentration tilts toward vertically integrated groups controlling captive aggregate and cement sourcing. Three archetypes dominate: state-affiliated megaproject specialists, private developers with land banking advantages, and European-Gulf joint ventures transferring modular methodologies. Capacity expansion and strategic partnerships represent the dominant competitive vectors as foreign exchange rationing elevates working capital requirements.
Within the state-affiliated tier, The Arab Contractors and Orascom Construction exemplify scale-driven positioning through transport infrastructure dominance and technology leadership in energy-efficient envelopes respectively. Hassan Allam Holding occupies a position among marine construction specialists with captive quarry control. These three anchors represent distinct strategic postures: vertical supply chain integration, technical specification leadership, and resource-backed project execution.
| Leading Market Players |
|---|
| The Arab Contractors |
| Orascom Construction |
| Hassan Allam Holding |
| Palm Hills Developments |
| H.A. Construction |
| DORRA Group |
| Rowad Modern Engineering |
| GAMA Construction |
| AL-AHLY Development |
| Others |
Supply Flow & Price Mechanics
Megaproject procurement waves from the New Administrative City and Suez Canal Economic Zone force suppliers to synchronize batching capacity with lumpy demand spikes, compressing margins for ready-mix producers unable to secure long-dated offtake contracts. This demand intermittency rewards contractors with captive quarry and clinker assets while squeezing spot-market-dependent specialists.
Pricing Analysis
Short-lead-time premiums dominate contractor bidding as ministry relocation deadlines compress project timelines, with penalties for delay exceeding material cost differentials. Three-tier pricing structure across certified high-performance, standard grade, and informal economy tiers reflects seismic code compliance gaps. Cost compression in standard-grade cement is intensifying because clinker overcapacity exceeds effective demand by substantial margins. Social housing programs exhibit highest price sensitivity; premium commercial developers in New Cairo show lowest sensitivity due to certification-driven specification rigidity.
Supply Chain Analysis
ISO-compliant rebar certification gates mill access to state megaprojects, filtering domestic producers from informal channel supply. Egypt's steel sector draws from imported Turkish and Chinese billets, with scrap feedstock sourced from Gulf collection networks. Single-source vulnerability concentrates in central bank foreign exchange rationing for billet imports. Distribution runs through vertically integrated contractor networks controlling aggregate quarries and batching plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Egypt construction sector functions as a vertical-integration race where captive aggregate supply and clinker production determine bidder eligibility for sovereign-backed megaprojects. Control over upstream raw material flows separates viable contenders from margin-squeezed subcontractors.
For Market Incumbents: Hedge against cement overcapacity erosion by locking long-dated offtake agreements with New Administrative City developers before additional kiln capacity enters service. Deepen backward integration into limestone quarries in Upper Egypt governorates to secure social housing program eligibility as procurement redirects southward.
For New Entrants and Emerging Players: European modular prefabrication specialists offer the most penetrable channel partnership for social housing programs seeking timeline compression. Target Upper Egypt corridor cities where formal construction services remain underserved and local content thresholds are less stringently enforced. Joint venture structures with established aggregate holders accelerate market access.
For Investors and Strategic Acquirers: The window for entry favors marine construction specialists with Suez Canal Authority relationships and captive quarry positions. Long-term viability rests on decade-long infrastructure contract visibility rather than speculative residential exposure. Watch central bank foreign exchange rationing intensity as the inflection signal for steel input cost volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Acquisition | Secures aggregate supply for New Administrative City foundation work under local content mandates. |
| High-Performance Concrete Certification | Unlocks premium commercial tower specifications requiring 50-60 MPa compressive strength ratings. |
| Modular Prefabrication Joint Venture | Transfers European factory-production methods to reduce site labor dependence in social housing. |
| Seismic Code Compliance Investment | Enables bidding on structures above twelve stories under Housing and Building National Research Center protocols. |
| Upper Egypt Corridor Expansion | Positions contractors for Ministry of Housing social housing redirection from saturated Delta markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Egypt construction sector assessment. Primary interviews with project directors at state megaproject developers, procurement leads at cement and steel producers, quarry operations managers, and Ministry of Housing planning officers validated demand assumptions. Housing and Building National Research Center technical bulletins, General Authority for Investment and Free Zones licensing databases, Suez Canal Authority infrastructure disclosures, and Egyptian Organization for Standardization and Quality enforcement records supplied segmentation parameters. Bottom-up project pipeline enumeration triangulated against top-down material consumption estimates.
Reconciliation of construction permit issuances, clinker production volumes, and rebar import customs declarations generated the analytical framework. Segmentation dimensions encompass material type, project category, end-user procurement authority, and construction methodology across the projection horizon. CAGRs derived from weighted capacity utilization trends and megaproject handover schedules. Seismic code implementation pace and foreign exchange rationing severity served as scenario-weighting inputs.
Caveats apply where central bank foreign exchange policy shifts or carbon accounting rule changes for sovereign-guaranteed finance could materially shift the outlook. Forecasts reflect assumptions about ministry relocation timelines and social housing program funding continuity. A model refresh is warranted upon material change in clinker capacity addition announcements or Suez Canal Economic Zone incentive modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Vietnam Construction Market
Building Construction
North America Modular Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
India Prefabricated Buildings Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Egypt Residential Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Pre-Engineered Building Market
Building Construction
Eastern Europe Construction Market
Building Construction
Middle East Building Construction Market
Building Construction
Japan Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
North America Construction Market