
 Static Crane Market | 2026-2036
Static Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Static Crane Market Analytics
A capital-intensity divergence between full-spectrum manufacturers and specialized tower crane producers is redrawing competitive boundaries in static crane supply. Liebherr Group leverages its in-house steel fabrication and component manufacturing to sustain margin control across European project cycles. Zoomlion Heavy Industry Science & Technology anchors its position through aggressive R&D spending on intelligent lifting systems for Chinese megaprojects.
Static cranes are fixed or semi-fixed lifting machines designed for repetitive vertical and horizontal load movement, with tower cranes typically achieving lifting heights exceeding 80 meters and load moments measured in tonne-meters to serve dense urban construction sites. Tower crane configurations dominate revenue contribution in mature European markets, while crawler crane demand accelerates in mining and heavy lifting applications across resource-intensive economies. Load capacity segmentation above 50 tons captures disproportionate margin pools due to engineering complexity and longer replacement cycles.
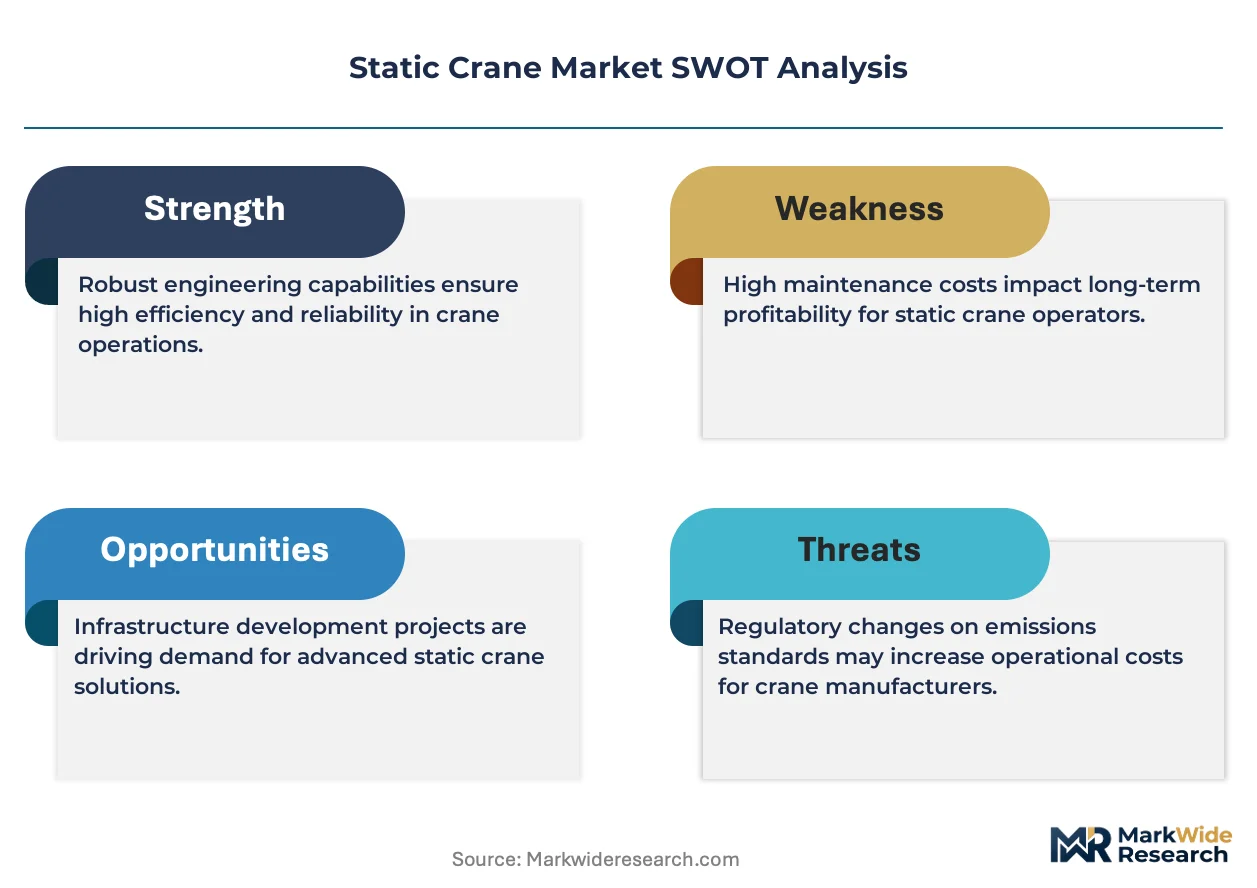
OSHA crane operator certification requirements in the United States, CE marking and the EU Machinery Directive in Europe, and China's GB/T 5031 tower crane standards collectively shape product design, inspection protocols, and market access timelines across major supply corridors. Stakeholders must monitor evolving carbon-emission benchmarks for construction equipment, as diesel-powered static cranes face escalating compliance thresholds in multiple jurisdictions.
Market Dynamics
China's GB standards for lifting machinery safety are tightening certification requirements, forcing manufacturers to reengineer control systems and structural components before market entry. This regulatory compression is redrawing competitive boundaries between full-spectrum manufacturers and specialized tower crane producers.
Growth Catalysts
- Urban densification:Tower crane adoption accelerates among high-rise construction firms in Mumbai and Delhi infrastructure corridors, driven by vertical expansion of commercial and residential stock.
- GB/T 5031 compliance upgrades:China's tower crane standards mandate enhanced anti-collision systems and remote monitoring capabilities, creating replacement demand across installed bases.
- Intelligent lifting systems:Automation integration for load positioning and wind compensation is penetrating megaproject sites, reducing operator fatigue and cycle times.
Market Restraints
- Steel input volatility:Structural steel price fluctuations compress margin predictability for crane fabricators with long-delivery project contracts.
- Specialized component concentration:High-capacity winch systems and precision gearboxes concentrate supply among German and Japanese precision engineering clusters.
- OSHA certification friction:Extended crane operator credentialing timelines in the United States delay equipment deployment on federally funded infrastructure sites.
Strategic Opportunities
- EU Green Deal alignment:Electrification retrofits and hybrid powertrains for diesel-powered static cranes open compliance-driven upgrade cycles in European construction fleets.
- Modular assembly systems:Rapid-erection tower crane configurations reduce site mobilization time, appealing to contractors with compressed project schedules.
- Aftermarket service digitization:Predictive maintenance platforms using IoT sensor networks create recurring revenue streams independent of new equipment sales.
Industry Challenges
- Certification timeline compression:CE marking under the EU Machinery Directive requires extended third-party validation for software-integrated control systems, delaying product launches.
- Integration complexity:Legacy fleet management systems resist seamless data exchange with new telemetry platforms, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static Crane Market |
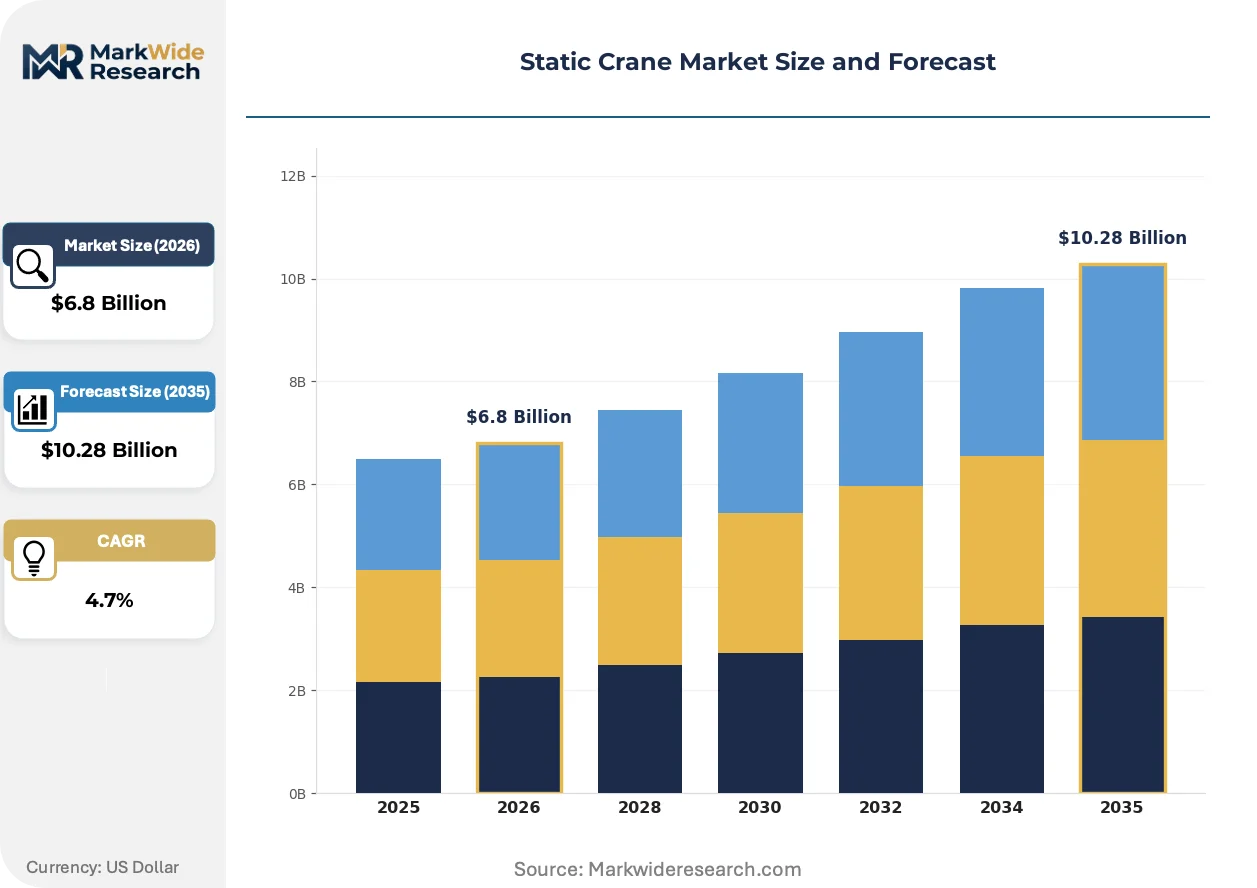
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck Mounted, Crawler, Tower, Rough Terrain Load Capacity: Under 10 Tons, 10-20 Tons, 20-50 Tons, Over 50 Tons Application: Construction, Mining, Shipbuilding, Heavy Lifting End User: Construction Firms, Marine Operators, Industrial Providers, Logistics Companies |
| Companies Covered | Liebherr Group, Terex Corporation, Manitowoc Company, SANY Group, Zoomlion Heavy Industry Science & Technology, XCMG Group, Kato Works, Konecranes, Sarens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static Crane Market Evolving Landscape
Digital control architectures and alternative powertrains are fragmenting traditional equipment specifications, forcing manufacturers to support multiple technical roadmaps simultaneously. This divergence pressures R&D allocation and aftermarket parts standardization.
Telematics-enabled load monitoring is fragmenting crane fleet management practices. Construction contractors with dispersed project portfolios deploy centralized dispatch systems that optimize equipment utilization across sites. Real-time structural stress data is compressing preventive maintenance intervals and extending component replacement cycles.
REACH substance restrictions and the EU Machinery Directive are tightening material composition and documentation requirements for European market access. Manufacturers must trace hazardous substance content through multi-tier supply chains. Tower crane exporters to Germany and France face extended conformity assessment timelines.
Rental and leasing arrangements are displacing direct equipment purchases among mid-tier construction firms. Equipment finance providers now bundle maintenance and certification services, capturing lifecycle value previously retained by manufacturers. This shift concentrates most visibly in the United Kingdom and Nordic markets where contractor balance-sheet constraints favor operational expenditure treatment.
Static Crane Market Segmentation
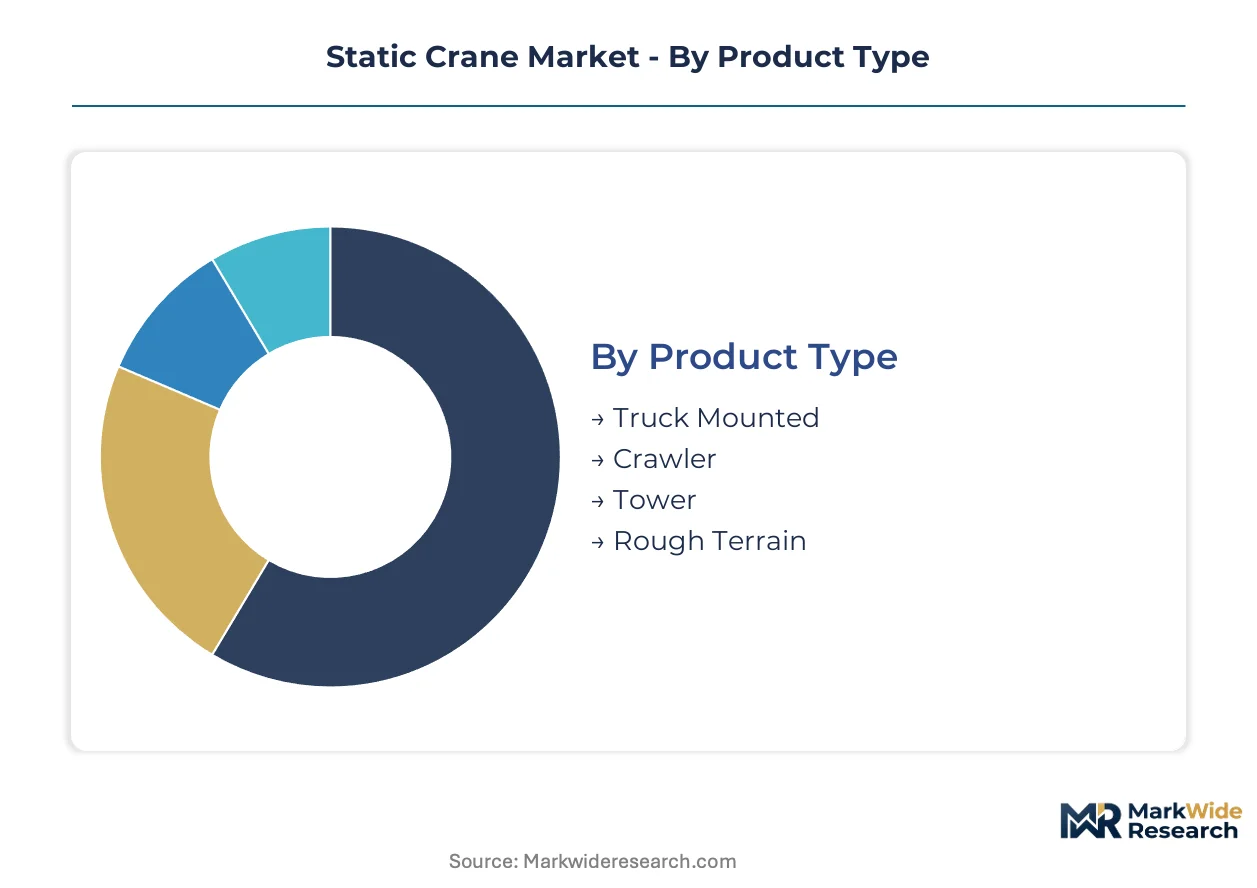
Static crane procurement decisions cluster around load-cycle intensity, site mobility constraints, and regulatory compliance burdens. Manufacturers must configure product portfolios across four intersecting dimensions to capture margin pools in urban construction, resource extraction, and heavy industrial verticals.
Product Type:
OSHA crane operator certification requirements in the United States, CE marking under the EU Machinery Directive, and China's GB/T 5031 tower crane standards each impose distinct control system and structural testing protocols that favor certain configurations in their respective jurisdictions.
- Tower:Fixed or climbing structures achieving lifting heights exceeding 80 meters with load moments measured in tonne-meters. Demand concentrates among urban high-rise construction firms in Mumbai and Delhi infrastructure corridors, driven by vertical densification of commercial and residential stock.
- Crawler:Tracked undercarriage systems delivering stability across unprepared terrain without outrigger deployment. Mining and heavy lifting applications across resource-intensive economies favor this configuration for load capacity above 50 tons and extended duty cycles.
- Truck Mounted:Highway-legal chassis with rapid deployment hydraulic booms for intermittent lifting tasks. Municipal infrastructure contractors and utility maintenance fleets prioritize mobility over cycle efficiency.
- Rough Terrain:Compact wheeled carriers with four-wheel drive and oscillating axles for confined construction sites. Residential and light commercial developers in geographies with limited paved access specify this category.
Tower configurations handle the majority of throughput in mature European markets; crawler systems are expanding most quickly in mining-intensive economies.
Load Capacity:
Engineering complexity and component sourcing constraints create sharp margin tiering across capacity bands, with precision gearbox and high-capacity winch availability concentrating among German and Japanese supply clusters.
- Over 50 Tons:Heavy-lift configurations requiring custom structural engineering and extended manufacturing lead times. Megaproject developers in China's infrastructure corridors specify these systems for intelligent lifting system integration and wind compensation automation.
- 20-50 Tons:Mid-range systems balancing mobility with structural capability for general construction and industrial maintenance. European rental fleet operators standardize on this band for cross-project utilization.
- 10-20 Tons:Compact systems for residential construction and light commercial verticals. Indian contractors in secondary cities favor this capacity for GB/T 5031 compliance cost containment.
- Under 10 Tons:Miniature and portable configurations for confined indoor applications and maintenance tasks. Logistics companies and small-scale marine operators deploy these for operational expenditure flexibility.
Above-50-ton systems command disproportionate margin pools; 10-20-ton equipment is climbing the fastest on unit volume.
Application:
End-use verticals impose divergent duty cycle, environmental exposure, and regulatory inspection requirements that reshape equipment specification and aftermarket service intensity.
- Construction:Dominant vertical spanning residential, commercial, and infrastructure project types. Tower crane adoption accelerates specifically among high-rise construction firms facing compressed urban site footprints.
- Heavy Lifting:Specialized applications including bridge erection, power plant component installation, and industrial relocation. Precision load positioning requirements drive specification of intelligent lifting systems with real-time structural monitoring.
- Mining:Continuous-duty extraction and processing support in surface and underground operations. Crawler configurations predominate due to terrain adaptability and maintenance access constraints.
- Shipbuilding:Large-scale hull assembly and outfitting in coastal yard facilities. Marine operators specify corrosion-resistant coatings and extended boom reach for drydock coverage.
Construction absorbs the majority of equipment shipments; heavy lifting is gaining share fastest on automation penetration.
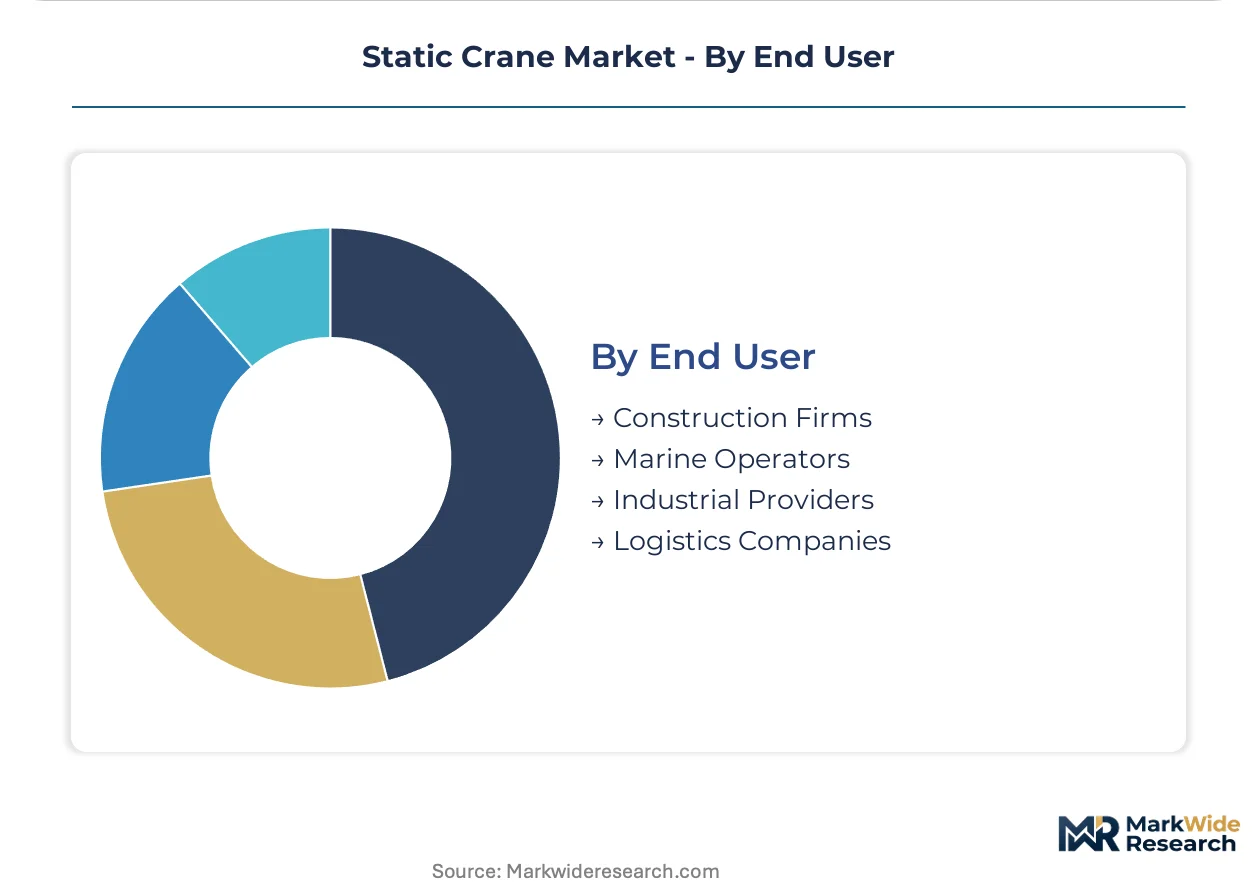
End User:
Procurement authority and lifecycle cost accountability vary sharply across customer types, with rental intermediaries displacing direct purchases among balance-sheet-constrained mid-tier contractors.
- Construction Firms:Primary demand channel spanning multinational developers to regional general contractors. Equipment finance providers now bundle maintenance and certification services, capturing lifecycle value previously retained by manufacturers.
- Industrial Providers:Manufacturing, energy, and process industry operators with captive maintenance capabilities. These users prioritize predictive maintenance platform integration and extended component replacement cycles.
- Marine Operators:Port authorities, shipyards, and offshore service companies with salt-exposure durability requirements. REACH substance restrictions and documentation mandates from ECHA extend conformity assessment timelines for European market access.
- Logistics Companies:Warehouse developers and intermodal terminal operators with intermittent lifting needs. Operational expenditure treatment favors short-term rental arrangements over capital deployment.
Construction firms account for the dominant share of new equipment procurement; logistics companies are expanding fastest on rental model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. European contractors prioritize rental-heavy fleet models with electrification compliance, while Chinese and Indian markets favor direct procurement for megaproject deployment with intelligent system integration.
United States
Federally funded infrastructure corridors around Texas and Florida drive crawler crane deployment for bridge and highway construction. OSHA crane operator certification requirements extend credentialing timelines, delaying equipment mobilization on government contracts. Houston's energy sector concentration sustains demand for heavy-lift configurations above 50 tons.
Germany
CE marking under the EU Machinery Directive and REACH substance documentation reshape import compliance for tower crane fabricators. The EU Green Deal accelerates electrification retrofit demand among construction fleets in North Rhine-Westphalia. Munich's high-rise residential pipeline concentrates tower crane procurement for vertical densification projects.
China
GB/T 5031 tower crane standards mandate anti-collision systems and remote monitoring capabilities, forcing control system reengineering. MIIT oversight of intelligent lifting system certification creates entry barriers for non-compliant equipment. Infrastructure corridors around Beijing and Shanghai anchor megaproject demand for automation-integrated cranes.
India
Urban densification in Mumbai and Delhi infrastructure corridors accelerates tower crane adoption among high-rise construction firms. BIS certification alignment with tightening structural safety protocols extends product validation timelines. Secondary cities favor 10-20 ton capacity systems for compliance cost containment.
Japan
JIS standards for lifting machinery impose distinct testing protocols favoring precision-engineered configurations. METI oversight of construction equipment carbon-emission benchmarks pressures diesel-powered fleet replacement. Osaka's industrial maintenance sector sustains demand for compact rough-terrain systems with telemetry integration.
Static Crane Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in static crane supply. Full-spectrum manufacturers with captive steel fabrication and component production sustain margin control across extended project cycles. Specialized tower crane producers compete on rapid-erection configurations and site-specific engineering. Strategic moves concentrate on intelligent system partnerships and electrification platform development rather than capacity expansion.
Within the integrated tier, Liebherr Group exemplifies European fabrication depth with in-house supply chain control, while Zoomlion Heavy Industry Science & Technology anchors Chinese megaproject positioning through R&D concentration. Terex Corporation occupies a position bridging North American rental market access with modular system design.
| Leading Market Players |
|---|
| Liebherr Group |
| Terex Corporation |
| Manitowoc Company |
| SANY Group |
| Zoomlion Heavy Industry Science & Technology |
| XCMG Group |
| Kato Works |
| Konecranes |
| Sarens |
| Others |
Value Network & Pricing Analysis
CE marking under the EU Machinery Directive gates both supplier qualification and price differentiation simultaneously, forcing non-European fabricators into extended third-party validation timelines that compress margin flexibility while enabling certified European producers to command structural premiums in regulated procurement channels.
Pricing Analysis
Long-term project-based contracts dominate static crane procurement, with megaproject developers locking in equipment packages spanning 18-36 month construction cycles. Pricing stratifies across premium, standard, and economy tiers based on certification grade and intelligent system integration depth. Cost compression in the mid-range 20-50 ton segment is intensifying because rental fleet operators standardize configurations for cross-project utilization. Municipal infrastructure contractors exhibit highest price sensitivity, while mining operators with continuous-duty requirements prioritize reliability over unit economics.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for precision gearbox and high-capacity winch shipments originating from German and Japanese engineering clusters. Structural steel fabrication concentrates in China, Germany, and South Korea, with component sourcing drawing from these hubs for cost-competitive chassis production. Single-source vulnerability in precision-engineered drive systems creates supply chain risk given limited qualified alternatives. Distribution runs through equipment finance providers and rental intermediaries that bundle maintenance and certification services, displacing direct manufacturer sales in European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in intelligent lifting system integration and GB/T 5031 compliance engineering represents the critical capability gap separating integrated leaders from commodity-positioned competitors, creating asymmetric returns for firms that bridge this technical divide.
For Market Incumbents: Shield margin pools in the above-50-ton heavy-lift segment through captive production of precision gearboxes and high-capacity winch systems, reducing exposure to German and Japanese supply concentration. Accelerate certification investment for China's MIIT intelligent lifting system standards before regulatory compression eliminates non-compliant equipment from megaproject tenders. Control channel positioning by deepening aftermarket service digitization with predictive maintenance platforms that create recurring revenue independent of new equipment sales. For New Entrants and Emerging Players: BIS certification fast-track for 10-20 ton tower crane configurations offers the most penetrable entry point into India's secondary city construction markets, where compliance cost containment drives procurement decisions. Target modular rapid-erection systems for contractors with compressed project schedules in Mumbai and Delhi infrastructure corridors. Pursue go-to-market partnerships with equipment finance providers that bundle maintenance and certification services, capturing rental market share without direct capital deployment against established manufacturer networks. For Investors and Strategic Acquirers: China's GB standards tightening reshapes the acquisition landscape by elevating compliance-engineering capabilities above manufacturing scale as valuation drivers. Long-term viability favors vertically integrated fabricators with in-house steel production and intelligent system R&D concentration over assembly-dependent specialists. Monitor MIIT certification timelines for intelligent lifting systems as the inflection signal distinguishing acquisition targets with sustainable market access from stranded asset risks.| Strategic Initiative | Industry Significance |
|---|---|
| Intelligent Lifting System Certification | MIIT compliance creates entry barriers protecting certified equipment in Chinese megaproject tenders. |
| Electrification Retrofit Development | EU Green Deal alignment opens compliance-driven upgrade cycles in European diesel-powered fleets. |
| Modular Rapid-Erection Configuration | Compressed mobilization timelines appeal to contractors with accelerated project schedules in urban corridors. |
| Predictive Maintenance Platform Deployment | IoT-enabled service digitization generates recurring revenue independent of new equipment sales cycles. |
| Backward Integration into Precision Components | In-house winch and gearbox production reduces exposure to German and Japanese supply concentration. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with crane fleet managers, OEM procurement directors, aftermarket service heads, and rental company operations executives; and secondary validation through customs and trade data, SEC filings of listed equipment manufacturers, national crane registration databases, and regulatory submission records. Bottom-up equipment shipment tracking and top-down construction expenditure modeling were triangulated to reconcile volume estimates.
Across the analysis window, forecasts incorporate product type segmentation by tower, crawler, truck-mounted, and rough-terrain configurations; load capacity tiers spanning under 10 tons through above 50 tons; and application verticals including construction, heavy lifting, mining, and shipbuilding. CAGRs were derived from regression analysis of historical shipment patterns against infrastructure investment flows and urban densification indices. Intelligent system penetration rates and electrification retrofit adoption curves served as industry-specific forecast modifiers.
Underlying assumptions cover sustained infrastructure investment in China's Beijing-Shanghai corridor and India's Mumbai-Delhi axis, with deviation risk concentrated in steel input price volatility and regulatory timeline compression for software-integrated control systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Crane Rental Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
CNC Machine Market
Construction Equipment
Roadheaders Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Trenchers Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Baler Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Shot Blasting Machine Market