
 Global Lactose-Free Infant Formula Market | 2026-2036
Global Lactose-Free Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lactose-Free Infant Formula Market Foresight
Market Context
Specialty pharmacy distribution is reconfiguring as hospital procurement committees and pediatric clinic networks consolidate purchasing authority across North America and Western Europe. Nestlé leverages its backward integration into whey protein hydrolysate supply chains to secure raw material consistency for lactose-free lines. Danone anchors its competitive position through dedicated neonatal unit partnerships in France, Belgium, and the Netherlands. Abbott differentiates via extensive clinical validation programs that support reimbursement eligibility in managed care systems.
Technical Definition and Segments
Global lactose-free infant formula comprises cow's milk-based or plant-derived nutritional products enzymatically treated to reduce lactose below 0.1 grams per 100 milliliters, delivering comparable caloric density and protein bioavailability to standard infant formula for feeding infants from birth through twelve months. The powdered segment occupies the largest volume share due to extended shelf stability and lower logistics costs, though ready-to-feed formats command premium pricing in hospital and neonatal unit channels where sterility assurance outweighs cost considerations. Digestive support applications represent the fastest-growing category as pediatricians increasingly prescribe lactose-free formulations for transient lactase deficiency rather than switching to soy-based alternatives.
Regulatory Frame and Outlook
The FDA enforces infant formula quality standards under the Federal Food, Drug, and Cosmetic Act, while EMA-aligned national regulators across Germany, France, and Italy mandate novel protein hydrolysate notifications before market entry. China's NMPA and SAMR impose parallel registration requirements for imported formulas, including mandatory clinical trials conducted within mainland populations. Stakeholders must monitor evolving amino acid fortification standards and cross-border e-commerce duty structures as primary determinants of regional profitability.
Market Dynamics
Pediatric nutritionists are expanding lactose-free formula recommendations as first-line intervention for infant digestive distress, while regulatory tightening on dairy processing equipment under the EU F-Gas Regulation and REACH framework compresses manufacturing flexibility across European supply chains.
Growth Catalysts
- Cross-border e-commerce liberalization:China's SAMR has streamlined import registration pathways for specialty infant formulas, enabling direct-to-consumer channels that bypass traditional retail markups and accelerate premium product penetration in tier-one cities.
- Clinical validation protocols:Managed care systems in the United States now reimburse lactose-free formulations when supported by documented lactase deficiency diagnostics, converting prescription volume into sustainable recurring revenue for manufacturers with FDA-cleared clinical data packages.
- Enzymatic hydrolysis advances:Immobilized lactase reactor technology reduces processing costs by enabling continuous-flow lactose reduction rather than batch methods, improving yield consistency for industrial-scale formula production.
Market Restraints
- Whey protein concentrate volatility:New Zealand and Australian dairy cooperative pricing cycles expose formula margins to input cost swings that standard infant formula producers buffer through commodity hedging unavailable at lactose-free production scale.
- Regulatory fragmentation:China's NMPA mandates mainland-conducted clinical trials for novel protein hydrolysates, creating 18-24 month registration delays that lock out innovative formulations while local competitors advance through abbreviated domestic pathways.
- Plant-based substitution threat:Extensively hydrolyzed rice and oat protein formulas are capturing parental preference among families seeking vegan-compatible alternatives, compressing addressable market for dairy-derived lactose-free options.
Strategic Opportunities
- Neonatal intensive care unit penetration:Ready-to-feed sterile formats remain underdeployed in Brazilian and Mexican hospital systems, where ANVISA registration pathways favor established multinationals with existing pediatric nutrition portfolios.
- Amino acid fortification standards evolution:EFSA and Codex Alimentarius committees are reviewing taurine and carnitine minimum thresholds, creating first-mover advantage for manufacturers with pre-positioned enhanced formulations awaiting regulatory ratification.
- Subscription direct-to-home models:Urban Chinese parents are consolidating formula purchases through cross-border platform subscriptions that guarantee supply continuity and reduce per-unit logistics costs for imported premium lines.
Industry Challenges
- Specialized pediatric nutritionist workforce scarcity:Clinical education programs in lactase deficiency diagnostics remain concentrated in Western European and North American medical centers, limiting prescriptive authority expansion in high-growth Asian markets.
- Legacy ERP integration friction:Manufacturers retrofitting lactose-specific batch tracking and allergen segregation protocols into existing dairy processing software encounter data architecture constraints that delay compliance certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lactose-Free Infant Formula Market |
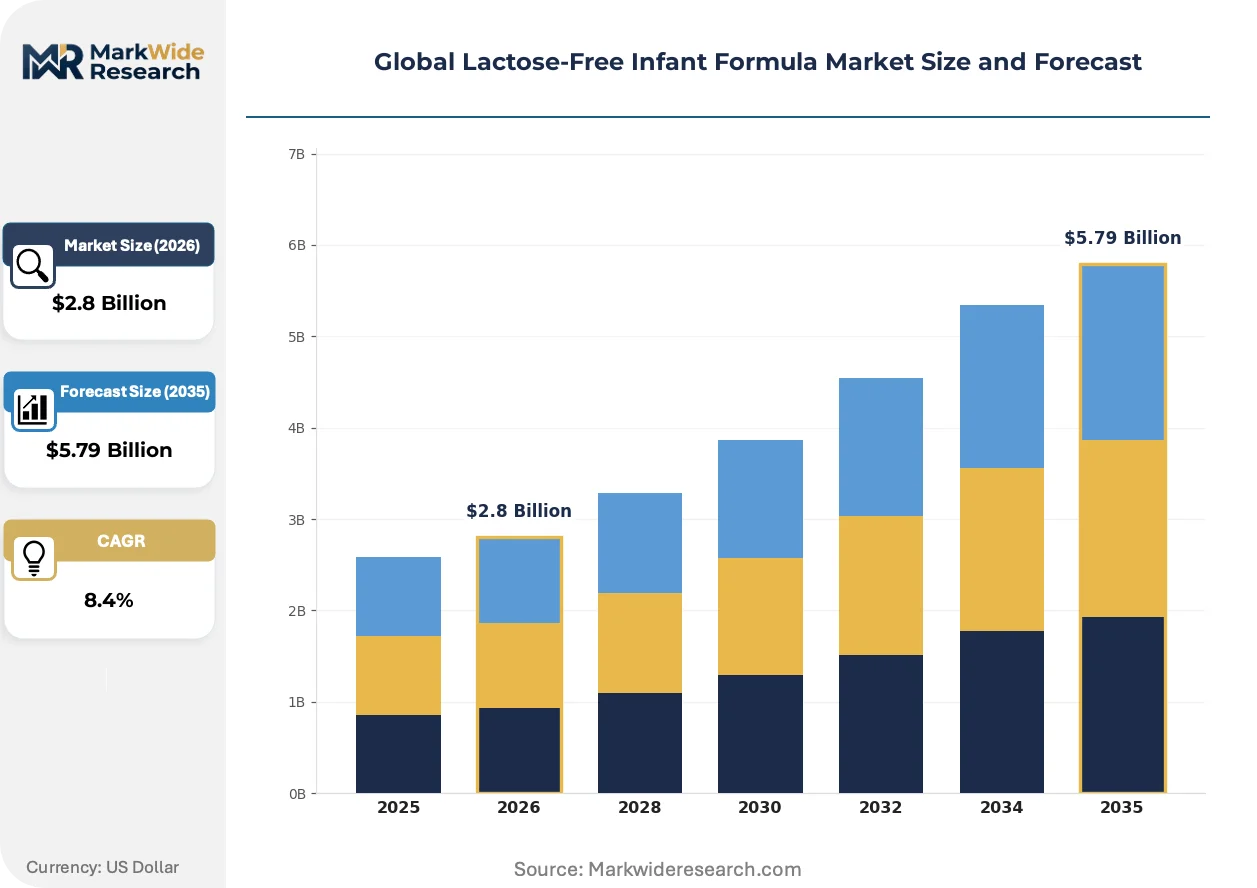
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Ready-to-Feed, Concentrated Liquid, Organic Blend Application: Preterm Infants, Colic Relief, Allergy Management, Digestive Support Distribution Channel: Pharmacies, E-Commerce, Specialty Stores, Hospitals End User: Pediatric Clinics, Family Care Centers, Neonatal Units, Pediatric Nutritionists |
| Companies Covered | Nestlé, Abbott, Danone, Reckitt Benckiser Group, Nutricia, Valio, Dana Dairy Group, Perrigo Company, HiPP International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lactose-Free Infant Formula Market Shifts & Advancements
Enzymatic processing technologies and sterile packaging formats are converging to reshape competitive positioning in hospital and retail channels, while regulatory divergence between major markets forces parallel development tracks for identical core formulations.
Immobilized lactase membrane reactor technology enables continuous-flow lactose hydrolysis with enzyme recovery rates exceeding 95%. Neonatal intensive care units in France, Belgium, and the Netherlands are adopting this processing method for in-house ready-to-feed preparation. The technology is hybridizing sterile liquid production economics by collapsing the cost gap between centralized manufacturing and point-of-care compounding.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in dairy spray-drying operations, forcing capital expenditure into ammonia-based cooling retrofits or geographic production relocation. German and Italian formula processors face the steepest compliance timelines with 2027 reduction targets. Powdered formula margins are compressing as manufacturers absorb equipment amortization before passing costs through contract renegotiations with hospital procurement committees.
Chinese urban parents are consolidating purchasing decisions through pediatric clinic network recommendations rather than independent retail research, concentrating influence with hospital-affiliated nutritionists in Shanghai, Beijing, and Guangzhou. Cross-border e-commerce platforms are capturing this trust transfer by embedding clinic partnership verification badges into product listings. The shift is visible most acutely in premium segment volume, where subscription attach rates now exceed 40% for NMPA-registered European imports.
Global Lactose-Free Infant Formula Market Segmentation
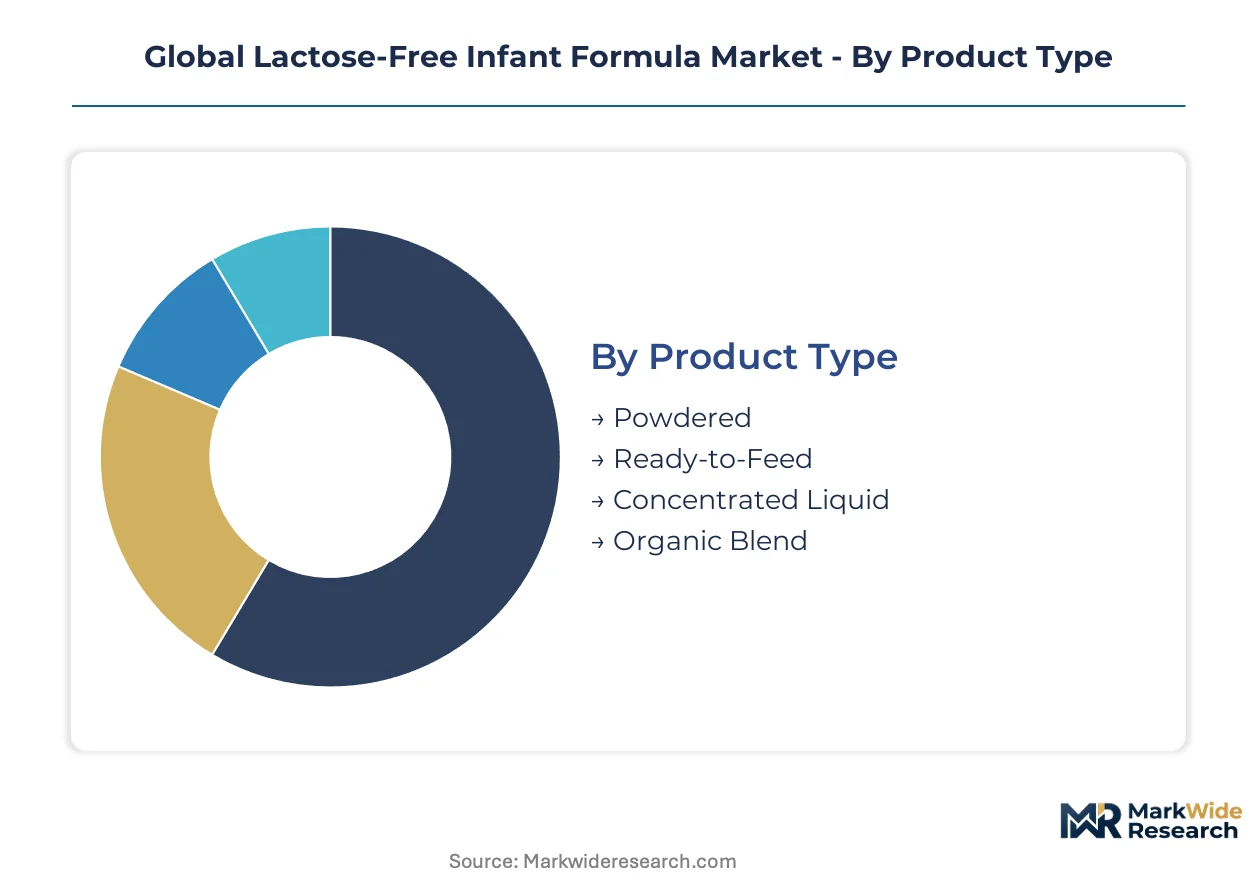
Segmentation in the lactose-free infant formula market reveals how formulation format, clinical application, and channel structure determine pricing power and regulatory exposure. Manufacturers configure production lines and certification investments around specific segment requirements rather than pursuing horizontal coverage.
Product Type:
Mature formats dominate volume, while emerging formats capture margin expansion through sterility premiums and convenience positioning.
- Powdered:Dehydrated formula requiring reconstitution with water delivers extended shelf stability and reduced logistics costs through ambient temperature distribution. Demand concentrates in retail pharmacy and e-commerce channels across Germany, France, and Italy where cost-conscious parents prioritize bulk purchasing and home storage flexibility.
- Ready-to-Feed:Sterile liquid formulations packaged in single-serve bottles or tetra-paks eliminate preparation error and contamination risk. Neonatal units in Belgian and Dutch hospital systems specify this format exclusively for premature infant feeding where immune vulnerability demands aseptic assurance.
- Concentrated Liquid:Partially diluted formulations requiring water addition before use occupy a narrowing middle ground between powder economy and ready-to-feed convenience.
- Organic Blend:Certified organic lactose-free formulations command certification premiums in urban Chinese markets where cross-border e-commerce platforms highlight EU organic logos.
Powdered formats handle the majority of throughput; ready-to-feed is the fastest mover on share as hospital procurement consolidates around sterility standards.
Application:
Volume flows through established digestive indications, while emerging clinical use cases reshape prescriptive authority and reimbursement pathways.
- Preterm Infants:Specialized formulations with elevated protein density and modified fat profiles address the accelerated metabolic demands of infants born before 37 weeks gestation. Neonatal intensive care units in France and the Netherlands mandate lactose-free options for preterm populations with immature lactase expression.
- Colic Relief:Transient lactase deficiency drives parental trial of lactose-free alternatives before extensive medical workup. Pediatricians in North American managed care systems increasingly prescribe these formulations as first-line intervention for inconsolable crying episodes.
- Allergy Management:Lactose-free cow's milk protein serves infants with confirmed lactose intolerance distinct from protein allergy requiring hydrolysate or amino acid formulas.
- Digestive Support:General gastrointestinal distress indications capture volume from parents seeking formula switches without clinical diagnosis.
Colic relief handles the majority of throughput; preterm infant applications are expanding most quickly as neonatal survival rates climb and specialized nutrition protocols standardize.
Distribution Channel:
Channel selection determines margin structure, with cost tiers separating institutional procurement from premium direct-to-consumer positioning.
- Pharmacies:Licensed retail dispensaries provide parental confidence through professional consultation access and cold-chain integrity verification. German and Italian pharmacy networks maintain exclusive distribution rights for certain hydrolysate formulations under national reimbursement schemes.
- E-Commerce:Cross-border platforms and domestic marketplaces consolidate purchasing for urban Chinese parents seeking European-imported certifications. SAMR registration requirements and subscription models are restructuring this channel toward recurring revenue relationships.
- Specialty Stores:Mother-and-baby retailers with certified nutrition staff capture premium positioning through in-person education and sampling programs.
- Hospitals:Institutional procurement committees negotiate multi-year supply contracts with sterility documentation requirements and volume discounts.
Pharmacies handle the majority of throughput; e-commerce is climbing the fastest as platform infrastructure matures and import registration accelerates.
End User:
Customer type segmentation concentrates influence with credentialed prescriber networks rather than individual consumer choice.
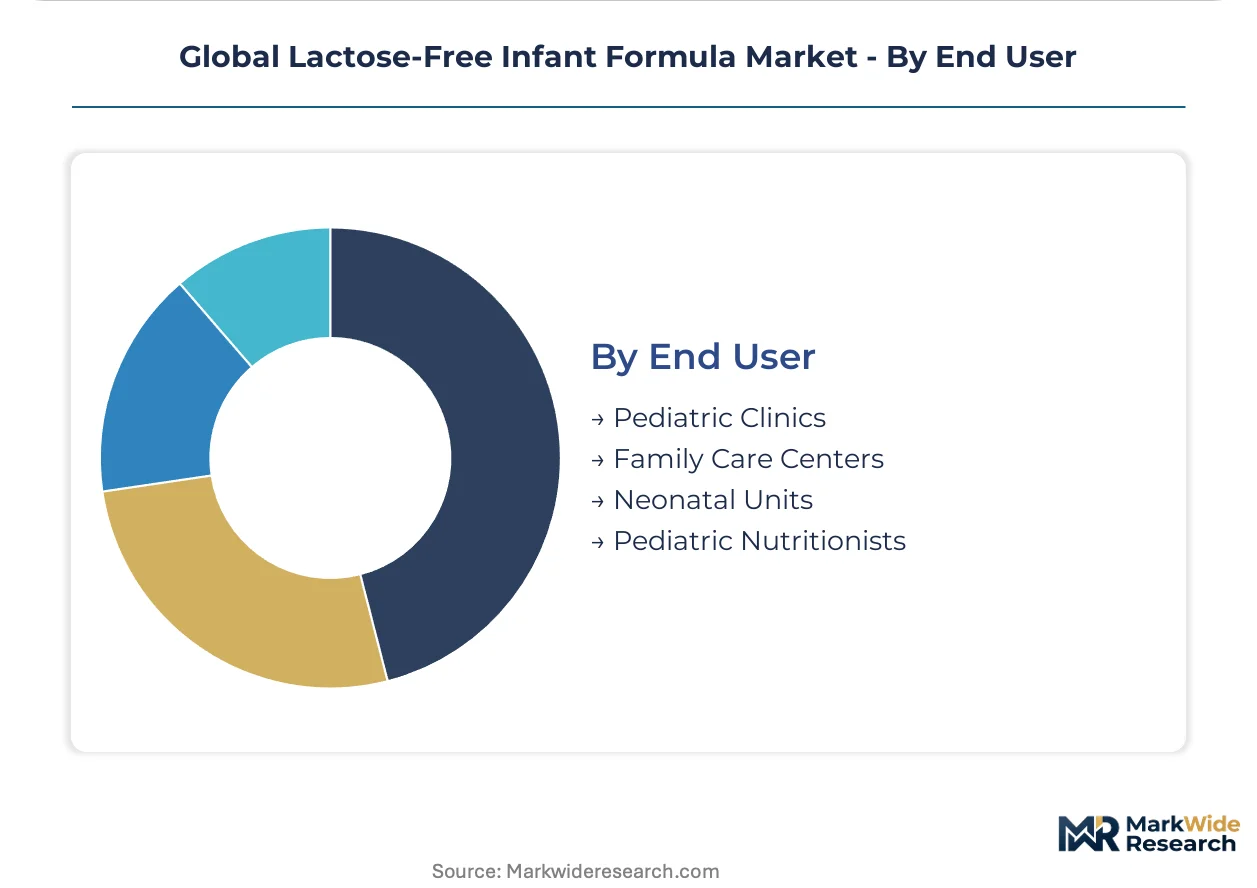
- Pediatric Clinics:Outpatient medical practices with affiliated nutritionists drive formula selection through diagnostic authority and sample distribution. Shanghai and Beijing clinic networks increasingly consolidate parental trust and channel it toward specific NMPA-registered brands.
- Family Care Centers:Primary care access points handle routine infant wellness visits where formula switching decisions originate.
- Neonatal Units:Hospital-based intensive care settings specify ready-to-feed sterile formats with batch traceability and infection control documentation.
- Pediatric Nutritionists:Specialized clinical dietitians with lactase deficiency diagnostic training represent a scarce workforce concentrated in Western European and North American medical centers.
Pediatric clinics handle the majority of throughput; neonatal units are gaining share fastest as hospital procurement authority centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Chinese tier-one cities where cross-border e-commerce platforms command 40-60% markups over European retail, while US hospital procurement committees extract volume discounts that compress margins for sterile ready-to-feed formats.
China
Urban middle-class parents in Shanghai, Beijing, and Guangzhou drive premium lactose-free formula adoption through pediatric clinic network recommendations rather than independent retail research. SAMR has streamlined import registration pathways for specialty infant formulas, enabling direct-to-consumer channels that bypass traditional retail markups. Cross-border e-commerce platforms now embed clinic partnership verification badges into product listings, with subscription attach rates exceeding 40% for NMPA-registered European imports.
United States
Managed care systems reimburse lactose-free formulations when supported by documented lactase deficiency diagnostics, converting prescription volume into sustainable recurring revenue. FDA enforces infant formula quality standards under the Federal Food, Drug, and Cosmetic Act with extensive clinical validation requirements. Hospital procurement committees and pediatric clinic networks across the Northeast and California are consolidating purchasing authority, negotiating multi-year supply contracts with sterility documentation requirements.
Germany
Pharmacy networks maintain exclusive distribution rights for certain hydrolysate formulations under national reimbursement schemes, anchoring volume in licensed retail dispensaries. EMA-aligned national regulators mandate novel protein hydrolysate notifications before market entry, creating compliance complexity for new entrants. The EU F-Gas Regulation is forcing capital expenditure into ammonia-based cooling retrofits for dairy spray-drying operations, with German processors facing steep 2027 reduction targets that compress powdered formula margins.
France
Neonatal intensive care units mandate lactose-free options for preterm populations with immature lactase expression, driving ready-to-feed sterile format specification. ANSM oversees pediatric nutrition product registration with stringent clinical trial requirements for novel formulations. Paris and Lyon hospital systems are adopting immobilized lactase membrane reactor technology for in-house ready-to-feed preparation, collapsing the cost gap between centralized manufacturing and point-of-care compounding.
Brazil
ANVISA registration pathways favor established multinationals with existing pediatric nutrition portfolios, creating barriers for new entrants in neonatal intensive care channels. Ready-to-feed sterile formats remain underdeployed in São Paulo and Rio de Janeiro hospital systems relative to North American and Western European benchmarks. Pediatric nutritionist workforce scarcity limits prescriptive authority expansion outside major metropolitan medical centers.
Global Lactose-Free Infant Formula Market Competitive Landscape
Vertically integrated multinationals and specialized pediatric nutrition houses split the market between scale-driven commodity production and clinically validated premium positioning. The vendor base concentrates around three archetypes: dairy processors with backward integration into whey protein hydrolysate supply chains, pharmaceutical-format specialists with sterile liquid manufacturing capabilities, and regional organic certification players capturing cross-border e-commerce premiums. Dominant competitive moves include neonatal unit partnership lock-ins through multi-year supply contracts and enzymatic processing technology licensing to secure yield consistency.
Among Swiss-anchored nutrition conglomerates, Nestlé occupies a position exemplifying dairy supply chain control, while Abbott represents the clinical validation archetype with extensive FDA-cleared data packages. Danone anchors the European neonatal partnership model through dedicated unit relationships in France, Belgium, and the Netherlands.
| Leading Market Players |
|---|
| Nestlé |
| Abbott |
| Danone |
| Reckitt Benckiser Group |
| Nutricia |
| Valio |
| Dana Dairy Group |
| Perrigo Company |
| HiPP International |
| Others |
Supply & Pricing Matrix
Rotterdam-to-Shanghai container freight corridors transmit cost volatility from European dairy processing hubs into Chinese premium tier markups, compressing margins for powder formats while amplifying price differentiation for sterile ready-to-feed lines. This logistics tension concentrates pricing power with multinational processors controlling backward integration into whey protein hydrolysate supply chains.
Pricing Analysis
The customization-premium spread between standard powdered formulations and clinic-configured ready-to-feed orders reaches its widest point in neonatal intensive care procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from New Zealand and Australian dairy cooperative pricing cycles that expose formula margins to input cost swings. Hospital procurement committees demonstrate lowest price sensitivity due to sterility assurance requirements, while retail pharmacy channels face highest sensitivity from cost-conscious parents in Germany and Italy.
Supply Chain Analysis
EU REACH chemical restrictions and F-Gas refrigeration phase-downs function as de facto export controls on European dairy processing technology transfers. New Zealand, Australia, and Germany anchor global whey protein concentrate supply. Raw material flows draw from lactase enzyme production, sterile packaging substrates, and ammonia-based cooling system retrofits. Single-source vulnerability concentrates in New Zealand dairy cooperative pricing cycles. Distribution runs through hospital procurement committees in France and Belgium, cross-border e-commerce platforms in China, and licensed pharmacy networks in Germany and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to Chinese birth rate stabilization and urban middle-class purchasing power normalization. The cyclical driver is cross-border e-commerce platform maturation enabling premium import penetration.
For Market Incumbents: Insulate margin position through captive supply of whey protein hydrolysate and accelerated NMPA registration for enhanced amino acid formulations. Plant-based substitution threats from rice and oat protein alternatives demand counter-positioning through clinical validation investments. Lock in neonatal unit partnerships across Brazilian and Mexican hospital systems before ANVISA registration windows narrow.
For New Entrants and Emerging Players: Brazilian neonatal intensive care channels represent the most penetrable entry point given underdeployed ready-to-feed sterile formats and ANVISA pathways favoring established portfolios. Subscription direct-to-home models for urban Chinese parents offer second white-space targeting through clinic partnership verification badges. Go-to-market execution should anchor in pediatric clinic network recommendations rather than independent retail presence.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic processing specialists with immobilized lactase membrane reactor capabilities and sterile liquid manufacturing assets. Long-term viability over the next decade rests on regulatory ratification of evolving amino acid fortification standards. The signal to watch is EFSA and Codex Alimentarius committee movement on taurine and carnitine minimum thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Neonatal Unit Partnership Lock-in | Multi-year supply contracts with French and Belgian hospital procurement committees secure recurring revenue. |
| Enzymatic Processing Technology Licensing | Immobilized lactase reactor deployment reduces processing costs for industrial-scale formula production. |
| NMPA Registration Acceleration | Mainland-conducted clinical trials unlock premium segment access in Shanghai and Beijing tier-one cities. |
| Subscription Direct-to-Home Model | Cross-border platform subscriptions reduce per-unit logistics costs for imported European formulations. |
| Amino Acid Fortification Pre-positioning | Enhanced taurine and carnitine formulations await EFSA ratification for first-mover advantage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric nutritionists, hospital procurement managers, dairy processing plant directors, and cross-border e-commerce platform category buyers. Secondary validation drew from NMPA registration databases, EFSA scientific opinions, FDA infant formula quality standards, and customs trade records. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Calibration anchored segment-level projections to historical volume trajectories and regulatory milestone timelines across the modeling period. Segmentation dimensions included product format, clinical application, distribution channel, and end-user type. CAGRs were derived from slope analysis of normalized growth curves. Forecast inputs incorporated enzymatic processing cost curves and cross-border e-commerce duty structure evolution.
Practitioners should monitor Chinese birth rate trends, EU F-Gas compliance timelines, and plant-based formula substitution rates for early signals. Forecasts reflect assumptions on regulatory harmonization and logistics cost stabilization. Material shifts in NMPA registration requirements or New Zealand dairy cooperative pricing cycles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Kids Food and Beverages Market