
 Food Allergy and Intolerance Products Market | 2026-2036
Food Allergy and Intolerance Products Market Size, Share, and Industry Trends Forecast 2026-2036
Food Allergy and Intolerance Products Market Analysis
The capital-intensity divergence between dedicated allergen-free manufacturing lines and shared-facility co-packing is redrawing competitive boundaries in this sector. Nestlé S.A. leverages its in-house clinical nutrition research infrastructure to sustain premium positioning in hypoallergenic infant formulas. General Mills Inc. anchors its North American presence through dedicated gluten-free production facilities that eliminate cross-contamination risk. Danone S.A. competes via specialized fermentation capabilities that yield dairy-free alternatives with comparable protein profiles.
Food allergy and intolerance products encompass formulated foods and beverages engineered to exclude specific immunogenic proteins—gluten, casein, lactoglobulin, ovomucoid, or tree nut allergens—while maintaining nutritional equivalence through alternative protein sources, hydrolyzed fractions, or enzymatic processing. These products serve clinical dietary management, preventive health consumption, and lifestyle preference segments across retail and institutional channels. Gluten-free formulations command the largest revenue pool due to celiac disease prevalence and broader consumer trial, though nut-free products represent the fastest-growing category as anaphylaxis awareness intensifies in school and childcare settings. The formulation dimension shows frozen ready-meals capturing margin concentration through convenience positioning, while liquid formulations such as hypoallergenic infant formulas sustain premium pricing through medical channel access.
The FDA enforces Food Allergen Labeling and Consumer Protection Act standards that mandate explicit declaration of major allergens, directly shaping product reformulation cycles and facility certification requirements. EFSA evaluates novel protein sources for allergenic potential under Novel Food regulations, creating pre-market approval barriers that favor established players with regulatory affairs capacity. Health Canada maintains distinct precautionary allergen labeling guidelines that influence cross-border product standardization decisions. Stakeholders must monitor evolving thresholds for precautionary labeling and invest in analytical validation capabilities as regulatory divergence between jurisdictions complicates unified portfolio strategies.
Market Dynamics
Cross-contamination detection thresholds mandated by the FDA and EFSA are forcing manufacturers to segregate production lines entirely, elevating capital requirements and compressing margins for mid-scale operators unable to absorb dedicated facility costs.
Growth Catalysts
- Celiac Disease Screening Expansion:National health systems in Italy and Australia have widened diagnostic protocols, creating new patient populations requiring lifelong gluten-free dietary management.
- EU Food Information for Consumers Regulation:Mandatory 14-allergen labeling across member states has standardized product reformulation cycles and expanded retail shelf space for compliant formulations.
- Anaphylaxis Protocol Mandates:School districts across Canada and the United Kingdom now require epinephrine accessibility and allergen-free meal options, institutionalizing demand for nut-free and multi-allergen-exclusion products.
Market Restraints
- Specialty Ingredient Concentration:Supply of certified gluten-free oats and hypoallergenic rice protein concentrates depends on a limited processor base in the northern Great Plains and Canadian prairies.
- EFSA Novel Food Approval Timelines:Pre-market safety assessments for emerging protein sources such as insect-derived fractions or precision-fermented dairy analogs extend 18-24 months.
- Substitution Risk from Whole-Food Diets:Clean-label consumer segments increasingly bypass formulated products for naturally allergen-free whole foods prepared at home.
Strategic Opportunities
- Pediatric Oral Immunotherapy Adjunct Nutrition:Clinics in Germany and the Netherlands seek palatable, precisely dosed food matrices to support desensitization protocols for milk and egg allergies.
- E-Commerce Direct-to-Consumer Subscription Models:Specialized platforms bypass conventional retail slotting fees and build recurring revenue through personalized allergen-profile matching.
- Precision Fermentation Scale-Up:Convergence of synthetic biology and food-grade bioreactor engineering enables animal-free protein production without allergenic epitopes present in conventional dairy.
Industry Challenges
- Allergen Analytical Validation Capacity:Commercial laboratories face backlogs in ELISA and mass-spectrometry confirmation testing required for precautionary label substantiation.
- Legacy Equipment Retrofit Costs:Existing baked-goods and confectionery lines require complete dismantling and stainless-steel replacement to achieve allergen-free certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Allergy and Intolerance Products Market |
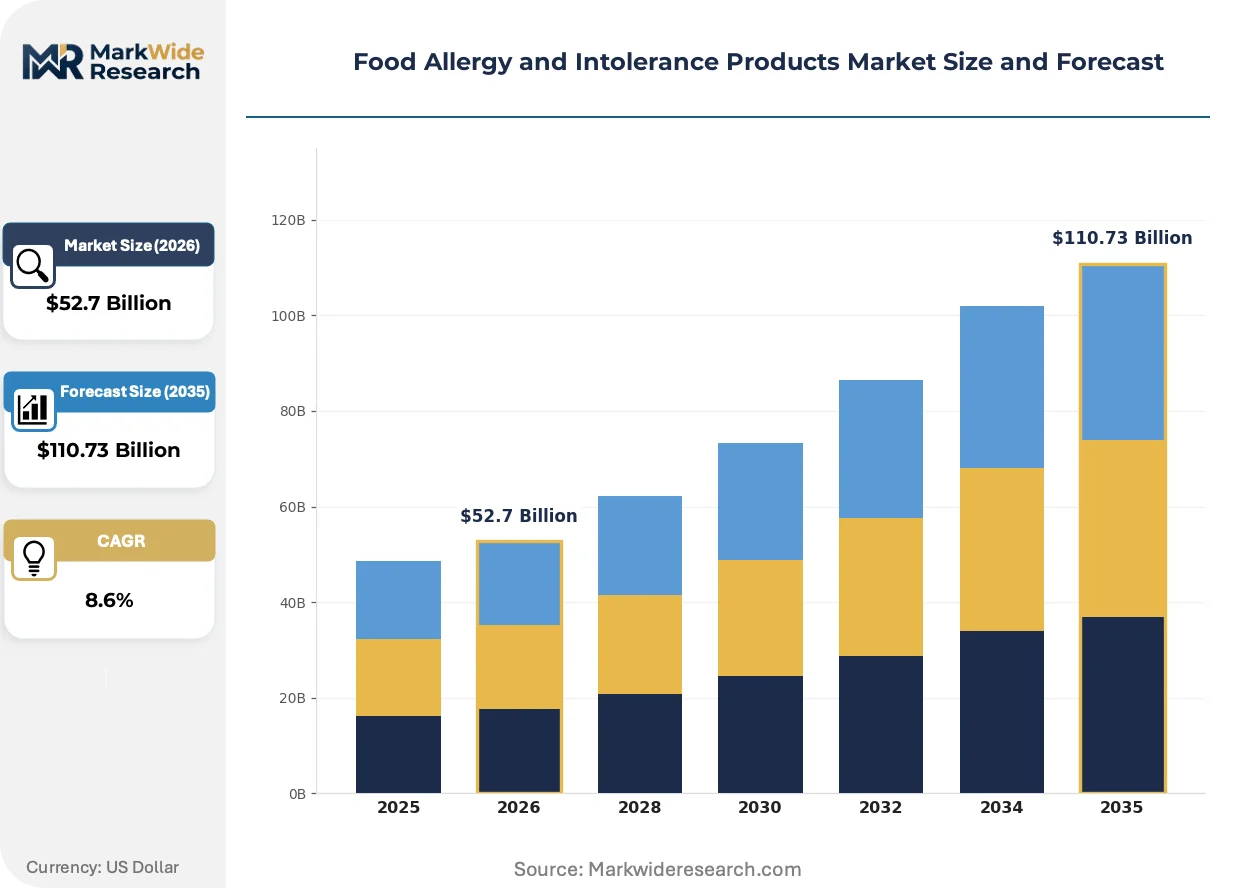
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Egg-Free Formulation: Ready-to-Eat, Frozen, Dried, Liquid End User: Children, Adults, Athletes, Families Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | The Hain Celestial Group, Inc., Conagra Brands, Inc., Nestlé S.A., Mondelez International, Inc., Arla Foods amba, Danone S.A., Abbott Laboratories, Kellogg Company, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Allergy and Intolerance Products Market Emerging Trajectories
Enzymatic protein hydrolysis and precision fermentation are redrawing ingredient sourcing maps, while regulatory harmonization efforts struggle to keep pace with novel production modalities.
Enzymatic hydrolysis of allergenic epitopes in whey and casein fractions is fragmenting the infant formula segment. Pediatric nutrition specialists in tertiary care hospitals increasingly specify extensively hydrolyzed or amino-acid-based formulations for cow's milk protein allergy management. This technology compresses the addressable market for partially hydrolyzed products and elevates R&D spend requirements for clinical validation.
EFSA's evolving guidance on precautionary allergen labeling thresholds is reshaping manufacturing protocols across the European marketplace. The regulator's push toward quantitative risk assessment replaces blanket "may contain" statements with measurable cross-contact limits. Frozen ready-meal producers in France and prepared-snack manufacturers in Spain face the steepest reformulation and validation burdens under this transition.
Subscription-based direct distribution is displacing conventional retail stocking for specialized hypoallergenic products. Parents of children with multiple food allergies in urban centers of the United Kingdom and Germany increasingly bypass supermarkets for curated monthly boxes matched to individual diagnostic profiles. This channel shift concentrates customer data with platform operators and erodes brand loyalty built through in-store visibility.
Food Allergy and Intolerance Products Market Segmentation
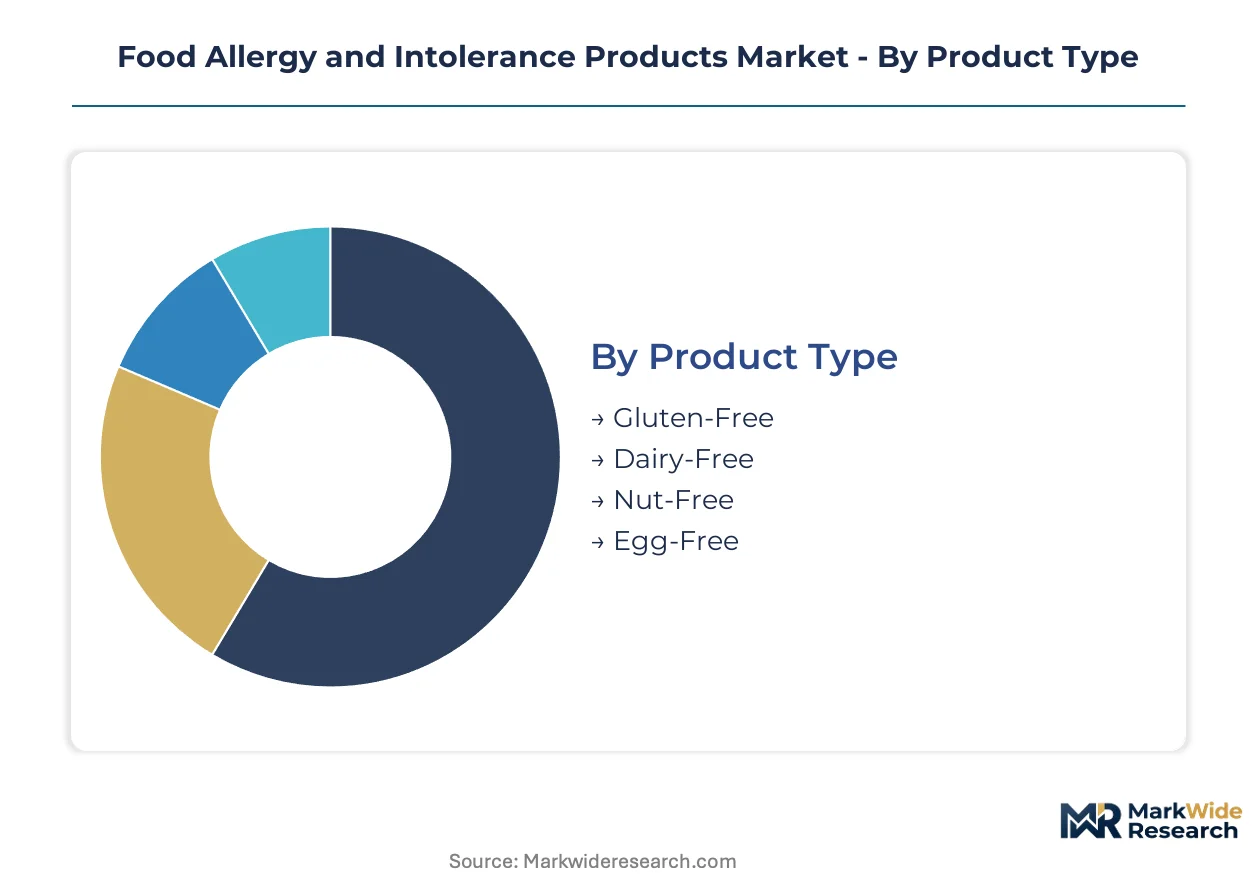
Segmentation in this market determines facility certification requirements, channel access, and pricing power. Product-type distinctions drive manufacturing capital intensity, while formulation choices shape cold-chain logistics and margin profiles across retail and institutional buyers.
Product Type:
Substitution pressure from whole-food alternatives varies sharply across allergen categories, with some segments facing acute displacement risk from naturally free-from ingredients prepared at home.
- Gluten-Free:Formulations exclude wheat, barley, and rye proteins through alternative grain sourcing or enzymatic processing. Demand concentrates in Italy and Australia where expanded celiac screening protocols have created substantial patient populations requiring lifelong dietary management. The segment faces moderate substitution pressure as consumers adopt rice, quinoa, and legume-based whole foods.
- Dairy-Free:Products eliminate casein, lactoglobulin, and whey fractions through plant-based analogs or precision fermentation. Pediatric oral immunotherapy clinics in Germany and the Netherlands drive specialized demand for precisely dosed matrices supporting milk allergy desensitization protocols. Substitution risk runs high from oat, almond, and soy milks prepared domestically.
- Nut-Free:Manufacturing protocols exclude tree nut and peanut proteins with validated analytical thresholds for cross-contamination. School districts across Canada and the United Kingdom mandate allergen-free meal options, institutionalizing demand in childcare and educational settings.
- Egg-Free:Formulations replace ovalbumin and ovomucoid binding functions through aquafaba, starches, or hydrocolloid systems. Bakeries and confectionery producers in France and Spain face reformulation burdens under evolving EFSA precautionary labeling guidance.
Gluten-Free anchors the volume base while Nut-Free gains share at the steepest rate.
Formulation:
Cost tier stratification separates premium-positioned formats from commodity alternatives, with convenience and medical channel access determining pricing architecture.
- Ready-to-Eat:Shelf-stable bars, snacks, and prepared meals require modified atmosphere packaging and validated allergen-free production lines. Urban professionals in the United Kingdom and Germany increasingly subscribe to curated monthly boxes matched to individual diagnostic profiles, bypassing conventional retail slotting fees.
- Frozen:Ready-meals and bakery items maintain texture and nutritional equivalence through blast-freezing and controlled-thaw protocols. Frozen formulations command margin concentration through convenience positioning in French and Spanish retail channels.
- Dried:Dehydrated pasta, grains, and soup mixes offer extended shelf life with minimal cold-chain dependency. Health food stores and specialty shops in Germany stock extensive dried assortments for pantry-stocking consumers.
- Liquid:Hypoallergenic infant formulas and dairy alternatives sustain premium pricing through medical channel access and clinical validation requirements. Pediatric nutrition specialists in tertiary care hospitals specify extensively hydrolyzed or amino-acid-based formulations for cow's milk protein allergy management.
Frozen formulations dominate margin capture while Liquid maintains the highest price realization per unit volume.
End User:
Application-specific requirements create divergent formulation standards, with pediatric and athletic segments demanding enhanced nutritional density and precise allergen thresholds.
- Children:Products meet stringent cross-contamination limits for school and childcare settings where anaphylaxis protocols mandate epinephrine accessibility. Parents in Canada and the United Kingdom drive subscription-based direct distribution, concentrating customer data with platform operators.
- Adults:Self-diagnosed intolerance management and preventive health consumption shape purchasing patterns. Adults exhibit highest substitution rates toward whole-food diets, compressing growth in formulated alternatives.
- Athletes:Performance-oriented formulations deliver protein equivalence through hypoallergenic rice protein concentrates and fermented plant sources. Supply depends on limited processor base in the northern Great Plains and Canadian prairies.
- Families:Multi-allergen-exclusion products accommodate households with divergent dietary restrictions. Family-oriented SKUs require broader certification coverage, elevating production complexity.
Children anchors the volume base while Athletes expands most quickly through sports nutrition channel development.
Distribution Channel:
Geographic concentration of purchasing behavior separates urban subscription adopters from conventional supermarket shoppers, with channel choice correlating to diagnostic severity and product specialization.
- Online:Direct-to-consumer platforms bypass retail slotting fees and build recurring revenue through personalized allergen-profile matching. E-commerce penetration runs highest in urban centers of the United Kingdom and Germany.
- Supermarkets:Mass retail expansion of free-from assortments follows EU Food Information for Consumers Regulation standardization across member states. Retail pharmacies and hospital nutrition services are expanding their free-from product assortments.
- Health Food Stores:Specialty retailers offer curated assortments with staff expertise in allergen management. Health food stores concentrate in Germany, the United Kingdom, and France within the European marketplace.
- Specialty Shops:Dedicated allergen-free bakeries and boutiques serve localized demand with fresh production. Specialty shops face margin compression from dedicated facility costs and limited scale economies.
Supermarkets anchors the volume base while Online climbs the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across patient populations. Self-diagnosed adults in France and Italy exhibit high substitution rates toward whole-food alternatives. Pediatric allergy management in Canada and the United Kingdom shows inelastic demand for certified hypoallergenic formulations.
United States
School district anaphylaxis protocols in California and New York institutionalize demand for nut-free meal options. The FDA enforces Food Allergen Labeling and Consumer Protection Act standards mandating explicit declaration of major allergens. Chicago and Boston metro areas concentrate pediatric nutrition specialists specifying extensively hydrolyzed infant formulas.
Germany
Expanded celiac screening protocols have created substantial patient populations requiring lifelong gluten-free dietary management. EFSA evaluates novel protein sources for allergenic potential under Novel Food regulations. Munich and Frankfurt clusters host precision fermentation startups developing dairy-free protein analogs.
United Kingdom
Urban parents increasingly subscribe to curated monthly boxes matched to individual diagnostic profiles, bypassing conventional retail. The EU Food Information for Consumers Regulation mandates 14-allergen labeling across member states. London concentrates direct-to-consumer platform operators capturing customer data through personalized allergen-profile matching.
Canada
Health Canada maintains distinct precautionary allergen labeling guidelines influencing cross-border product standardization. School districts nationwide require epinephrine accessibility and allergen-free meal options. Toronto and Vancouver anchor retail pharmacy expansion of free-from product assortments.
Australia
National health systems have widened diagnostic protocols creating new patient populations. The TGA regulates novel protein sources for allergenic potential. Melbourne and Sydney clusters concentrate gluten-free manufacturing facilities serving domestic and Asia-Pacific export markets.
Food Allergy and Intolerance Products Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Nestlé S.A. and Danone S.A. leverage clinical nutrition research infrastructure to sustain premium positioning in hypoallergenic infant formulas. Mid-scale operators face margin compression from dedicated facility costs. Competitive moves concentrate on M&A for regulatory affairs capacity and geographic expansion into school nutrition contracts.
Among diversified consumer goods conglomerates, Nestlé S.A., Danone S.A., and General Mills Inc. exemplify distinct strategic archetypes. Nestlé S.A. represents the clinical-validation-driven premium tier. Danone S.A. occupies a position anchored in specialized fermentation capabilities. General Mills Inc. exemplifies the dedicated-facility manufacturing model eliminating cross-contamination risk. These three players collectively illustrate how capital-intensity divergence between integrated manufacturing and shared-facility co-packing redistributes competitive advantage.
| Leading Market Players |
|---|
| The Hain Celestial Group, Inc. |
| Conagra Brands, Inc. |
| Nestlé S.A. |
| Mondelez International, Inc. |
| Arla Foods amba |
| Danone S.A. |
| Abbott Laboratories |
| Kellogg Company |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for certified gluten-free oat and rice protein concentrates lock in supply access and price visibility for infant formula manufacturers facing EFSA Novel Food approval timelines. These contracts tether pricing stability to dedicated facility certification requirements while insulating buyers from spot-market volatility in the northern Great Plains and Canadian prairies processor base.
Pricing Analysis
After-sales nutrition counseling and subscription renewal rates drive lifetime value for direct-to-consumer platforms. Three-tier pricing structure across premium, standard, and economy levels separates extensively hydrolyzed infant formulas from partially hydrolyzed alternatives and commodity gluten-free staples. Price differentiation centers on clinical validation depth and medical channel access. Cost compression in the standard tier intensifies because substitution pressure from whole-food diets compresses margins for formulated alternatives. Self-diagnosed adults exhibit highest price sensitivity; pediatric allergy management shows lowest sensitivity due to anaphylaxis protocol mandates.
Supply Chain Analysis
Canada and the United States anchor certified gluten-free oat milling and hypoallergenic rice protein concentrate processing for global infant formula supply. Manufacturing draws from dedicated allergen-free production lines, stainless-steel equipment retrofits, and validated analytical testing capacity. Single-source vulnerability concentrates in the limited processor base spanning the northern Great Plains and Canadian prairies. Distribution runs through retail pharmacy networks, hospital nutrition services, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in pediatric oral immunotherapy adjunct nutrition, where desensitization protocol expansion in Germany and the Netherlands creates specialized formulation niches underserved by mass-market players.
For Market Incumbents: Compound defensive positioning through backward integration into precision fermentation capabilities and captive supply of allergen-free protein analogs. Nestlé S.A. and Danone S.A. already leverage clinical nutrition research infrastructure; mid-scale operators must match this or cede premium infant formula tiers. Certification investment in EFSA-aligned analytical validation capacity protects against regulatory divergence between jurisdictions. For New Entrants and Emerging Players: EFSA Novel Food fast-track pathways for precision-fermented dairy analogs open white-space entry. Target pediatric oral immunotherapy clinics in Germany and the Netherlands with precisely dosed matrices supporting milk and egg allergy desensitization protocols. Direct-to-consumer subscription models bypass retail slotting fees and build recurring revenue through personalized allergen-profile matching. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation startups with demonstrated scale-up capabilities and regulatory affairs capacity. Long-term viability over the medium-term projection horizon hinges on synthetic biology convergence with food-grade bioreactor engineering. Signal to monitor: EFSA precautionary allergen labeling threshold finalization and its facility certification cost implications.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Synthetic biology convergence enables animal-free protein production without allergenic epitopes present in conventional dairy. |
| Direct-to-Consumer Subscription Launch | Urban parents in the United Kingdom and Germany bypass supermarkets for curated monthly boxes matched to diagnostic profiles. |
| EFSA Novel Food Certification Investment | Pre-market approval barriers favor established players with regulatory affairs capacity over emerging protein sources. |
| Pediatric Oral Immunotherapy Partnership | German and Dutch clinics seek palatable, precisely dosed food matrices supporting milk and egg allergy desensitization. |
| Dedicated Facility Expansion | Segregated production lines eliminate cross-contamination risk and satisfy FDA and EFSA detection threshold mandates. |
Methodological Framework
Desk research of FDA Food Allergen Labeling and Consumer Protection Act filings, EFSA Novel Food submissions, and Health Canada precautionary labeling guidelines preceded structured interviews with pediatric nutrition specialists, regulatory affairs directors at infant formula manufacturers, retail pharmacy category buyers, and precision fermentation startup technical leads. Primary fieldwork combined with secondary validation across EU Food Information for Consumers Regulation compliance databases and celiac disease screening protocol expansions in Italy and Australia. Bottom-up facility capacity modeling and top-down patient population estimates were triangulated.
Variance decomposition across product type, formulation, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from patient population growth trajectories, regulatory standardization timelines, and substitution elasticity estimates for whole-food alternatives. Forecast inputs included EFSA precautionary labeling threshold evolution and precision fermentation cost curve progression.
Underlying assumptions cover sustained celiac disease screening expansion, stable Novel Food approval timelines, and continued anaphylaxis protocol institutionalization, with deviation risk concentrated in regulatory divergence between FDA and EFSA detection thresholds and accelerated substitution toward whole-food diets. Recalibration cycles align with material shifts in precautionary allergen labeling guidance and precision fermentation scale-up milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market