
 Reduced Salt Food Products Market | 2026-2036
Reduced Salt Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Salt Food Products Market Intelligence
A transition from single-source salt substitutes to multi-source ingredient blends is broadening formulation possibilities for food manufacturers. This allows for improved taste profiles in reformulated products. Nestlé S.A. leverages extensive R&D to develop proprietary low-sodium flavor technologies. The Kraft Heinz Company specializes in reformulating its iconic brands within the sauces and frozen meals segments to meet health targets.
Reduced salt food products are consumer packaged goods reformulated to contain significantly less sodium chloride than their standard counterparts. This is often achieved by substituting sodium with potassium chloride or using advanced flavor enhancers like yeast extracts to maintain palatability. The snacks category leads product development, driven by high consumer frequency and impulse purchases. Within applications, the food service sector represents a key growth area as institutional buyers and restaurant chains respond to public health guidelines.
Regulatory frameworks, including voluntary sodium reduction targets from the U.S. FDA and guidance from the EFSA in Europe, establish clear benchmarks for manufacturers. These policies directly influence product reformulation strategies and front-of-pack labeling requirements. Stakeholder success will depend on balancing the technical challenges of salt reduction with evolving consumer taste preferences and clean-label demands.
Market Dynamics
The central dynamic shaping the market is the convergence of public health mandates and evolving consumer preferences. Regulatory pressure from bodies like the WHO is compelling broad-scale product reformulation, while demand for clean-label and palatable healthy options creates a clear commercial incentive for innovation.
Growth Catalysts
- Public Health Initiatives:Government-led campaigns, such as those in the United Kingdom promoting lower sodium consumption, directly stimulate consumer demand and pressure food manufacturers to reformulate popular products.
- Food Service Sector Adoption:Restaurant chains and institutional caterers are increasingly specifying reduced-sodium products to meet both public health guidelines and the wellness demands of their clientele.
- Ingredient Innovation:The development of advanced flavor technologies, including yeast extracts and umami compounds, enables manufacturers to reduce sodium while maintaining acceptable taste profiles in processed foods.
Market Restraints
- Technical Hurdles:Reducing sodium chloride presents significant challenges in food preservation and texture, particularly in baked goods and cured meats where it serves functional roles beyond taste.
- Cost of Substitutes:Key substitutes like potassium chloride are often more expensive than sodium chloride, increasing formulation costs and potentially impacting final product pricing for consumers.
- Consumer Taste Perception:A persistent consumer belief that reduced-salt products have an inferior or altered taste profile acts as a significant barrier to trial and repeat purchases, especially for iconic brands.
Strategic Opportunities
- Clean-Label Formulations:Developing salt reduction solutions using natural ingredients like seaweed or mushroom extracts offers a path to meet the growing consumer demand for products with simple, recognizable ingredient lists.
- Expansion in Emerging Markets:Untapped demand exists in developing nations across Asia and Latin America, where rising health consciousness and disposable incomes create new markets for healthier processed foods.
- Specialty Product Lines:Launching dedicated product lines for specific dietary needs, such as low-sodium options for cardiovascular health, allows for targeted marketing and premium pricing strategies.
Industry Challenges
- Complex Reformulation Cycles:Rebalancing flavor profiles in complex recipes like soups and sauces is a time-intensive R&D challenge, requiring significant investment in sensory science and food technology expertise.
- Ingredient Sourcing Consistency:Securing a stable and consistent supply of specialized salt substitutes and flavor enhancers can be difficult, exposing manufacturers to supply chain volatility and quality control issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Salt Food Products Market |
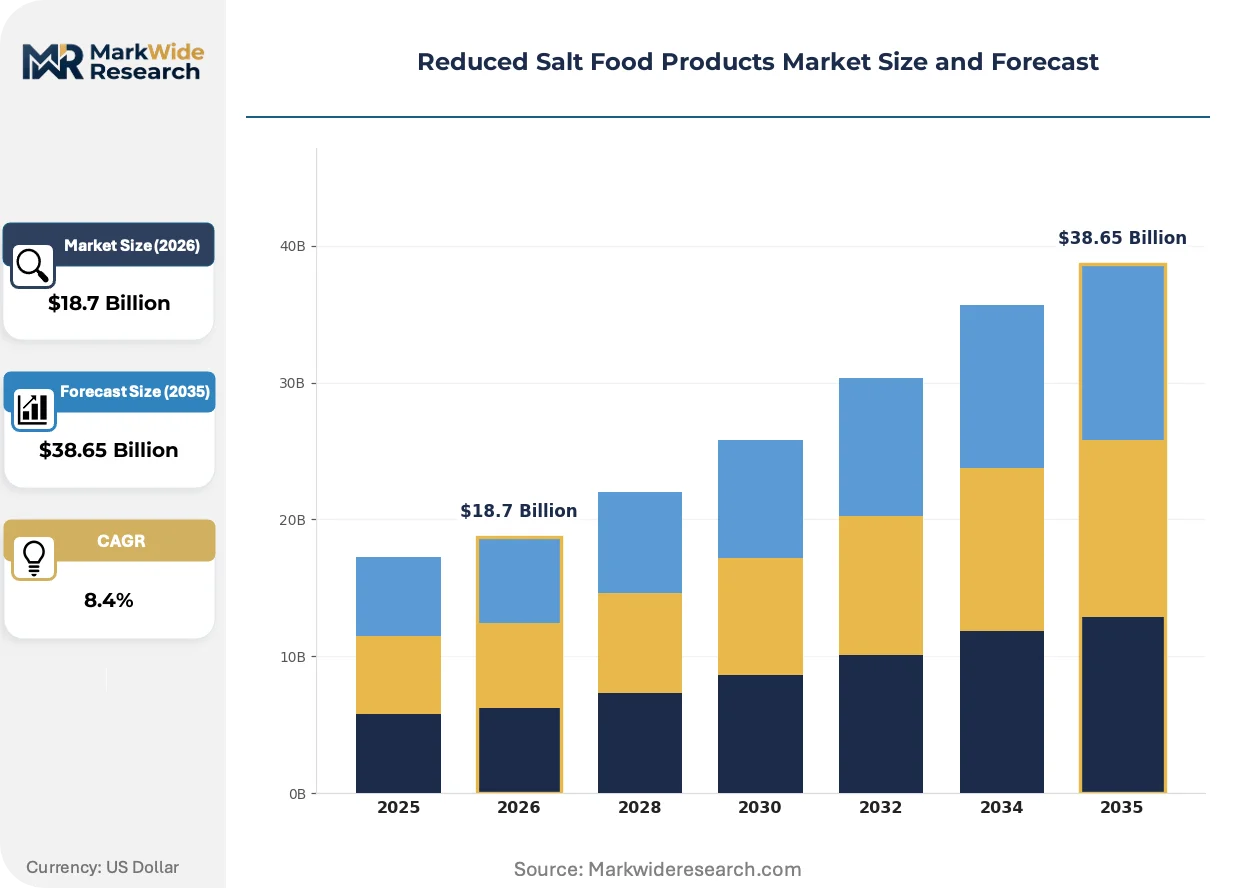
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Sauces, Soups, Frozen Meals Form: Dry, Liquid, Canned, Refrigerated Application: Household, Food Service, Retail, Institutional End User: Health-Conscious Consumers, Seniors, Athletes, Dietary Restricted Individuals |
| Companies Covered | Nestlé S.A., PepsiCo, Inc., General Mills, Inc., The Kraft Heinz Company, Conagra Brands, Inc., Tyson Foods, Inc., Hormel Foods Corporation, Unilever PLC, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Salt Food Products Market Strategic Shifts & Innovations
A fundamental shift from single-ingredient substitution toward holistic, multi-functional ingredient systems is underway. This evolution addresses the complex interplay between taste, texture, preservation, and clean-label demands, moving beyond simple sodium reduction to comprehensive product improvement.
Advanced flavor modulation systems are a key product evolution. These systems combine potassium salts with taste-masking agents and natural umami sources like yeast extracts. Food manufacturers in the competitive snacks and ready-meals categories are adopting these blends to accelerate reformulation timelines and improve sensory outcomes. This integrated approach is unifying the previously distinct goals of sodium reduction and taste parity with original formulations.
Voluntary sodium reduction targets, such as those issued by the U.S. FDA, are creating clear industry benchmarks. These guidelines provide specific goals for hundreds of food categories, compelling manufacturers to invest in reformulation to align with public health objectives. The processed meats and cheese segments are particularly affected, accelerating R&D into alternative curing methods and flavor enhancement techniques.
Consumer scrutiny of front-of-pack labeling is driving a behavioral shift toward ingredient transparency. This trend is disrupting the simple "low sodium" marketing claim, as shoppers now also seek "clean labels" free from chemical-sounding additives. This is most visible in North American and European markets, where brands are reformulating their salt-reduction technologies to use more natural and recognizable ingredients.
Reduced Salt Food Products Market Segmentation
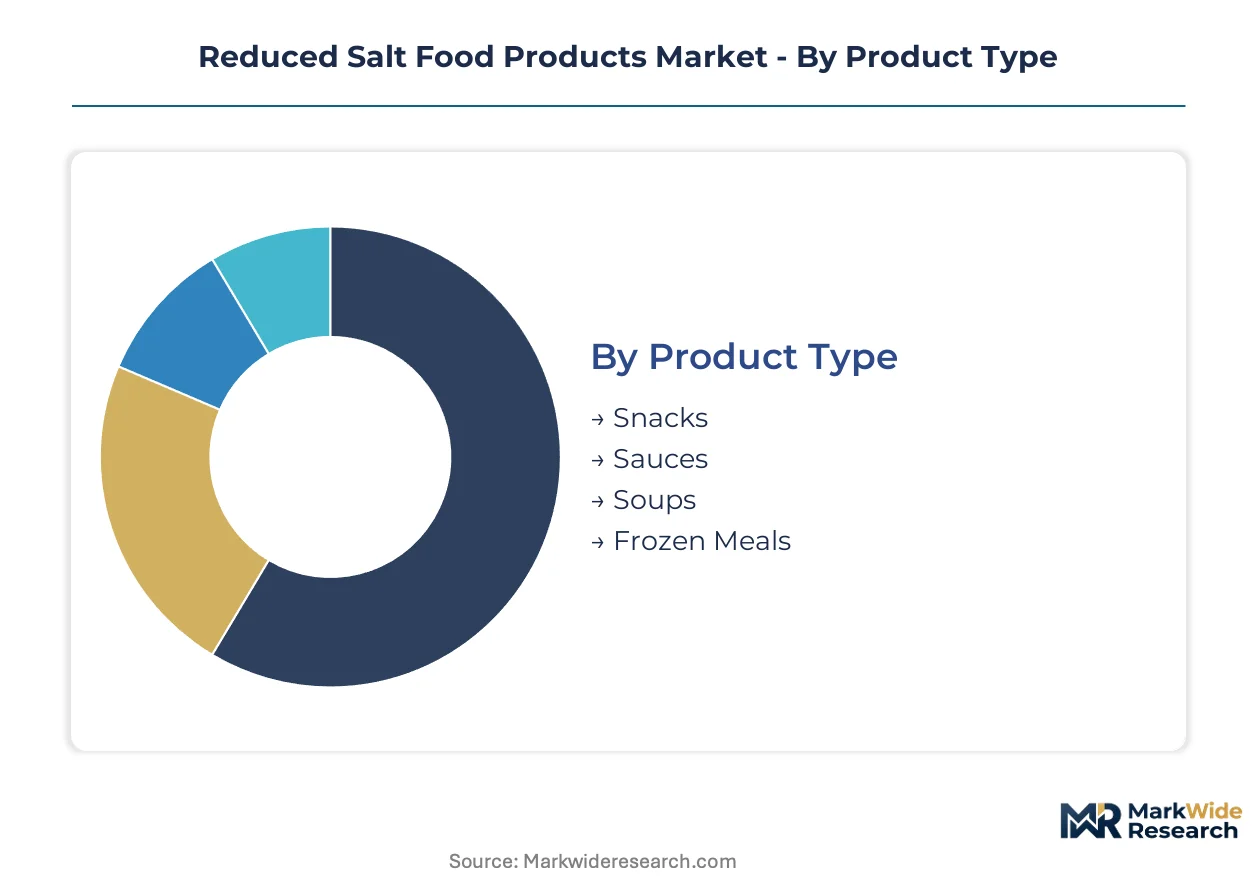
Segmentation analysis provides a granular view of the Reduced Salt Food Products Market, enabling manufacturers and stakeholders to identify specific consumer needs and strategic growth avenues. This detailed breakdown helps in understanding demand drivers across diverse product categories, forms, applications, and end-user demographics. Tailored product development and marketing strategies become possible through this segmentation.
Product Type:
Supply concentration within product type segments reveals where manufacturers prioritize reformulation efforts and R&D investment for reduced-salt offerings.
- Snacks:Reduced-sodium snack products encompass items like chips, crackers, and nuts, reformulated to lower sodium content while preserving crunch and flavor. Consumer demand for healthier on-the-go options drives innovation in this segment, particularly in markets with high snacking frequency like the United States.
- Sauces:This segment includes reduced-salt condiments, dressings, and cooking sauces, where sodium reduction must balance flavor impact and preservation properties. Food service and household consumers increasingly seek lower-sodium sauces, compelling brands to maintain palatability through advanced flavor enhancers.
- Soups:Reduced-sodium soups offer convenient meal solutions, requiring careful reformulation to maintain taste and shelf stability without excessive sodium.
- Frozen Meals:The frozen meals segment provides reduced-salt ready-to-eat options, balancing sodium reduction with texture preservation and flavor integrity for consumer appeal.
Snacks absorb the bulk of installed capacity for reduced-salt reformulation; sauces are expanding most quickly.
Form:
Product form dictates specific processing requirements and packaging considerations for reduced-salt food items across various applications.
- Dry:Dry reduced-salt products include powders, mixes, and dehydrated goods, where sodium often functions as a preservative and flavor enhancer. Manufacturers in the bakery and seasoning sectors focus on dry formulations to extend shelf life and simplify distribution across diverse retail channels.
- Liquid:Liquid reduced-salt products, such as beverages, broths, and dressings, require precise ingredient blending to maintain mouthfeel and flavor without high sodium. The food service sector increasingly demands liquid low-sodium options for use in prepared meals and institutional catering, responding to health guidelines.
- Canned:Reduced-salt canned goods offer extended shelf life and convenience, necessitating reformulation to preserve taste and texture without sodium's traditional role.
- Refrigerated:Refrigerated reduced-salt foods, including deli meats and fresh meals, balance sodium reduction with maintaining freshness and preventing microbial growth.
Demand for liquid forms remains foundational, while refrigerated forms show accelerated growth.
Application:
Volume distribution across application segments highlights where reduced-salt products gain traction with different buyer groups.
- Household:The household application segment targets individual consumers purchasing reduced-salt food products for in-home consumption through retail channels. Health-conscious consumers drive demand for a variety of low-sodium options, influencing product availability and marketing strategies in supermarkets.
- Food Service:The food service application involves supplying reduced-salt ingredients and finished products to restaurants, cafeterias, and catering operations. Institutional buyers and restaurant chains increasingly specify low-sodium items to comply with public health guidelines and meet evolving consumer wellness demands.
- Retail:The retail application involves the sale of reduced-salt products through supermarkets, convenience stores, and online platforms directly to consumers.
- Institutional:Institutional applications include supplying reduced-salt foods to hospitals, schools, and government facilities, driven by dietary guidelines and large-scale procurement.
Market share concentrates in household applications, with food service showing accelerated adoption.
End User:
Understanding end-user segments allows manufacturers to tailor product development and marketing messages to specific dietary needs and health objectives.
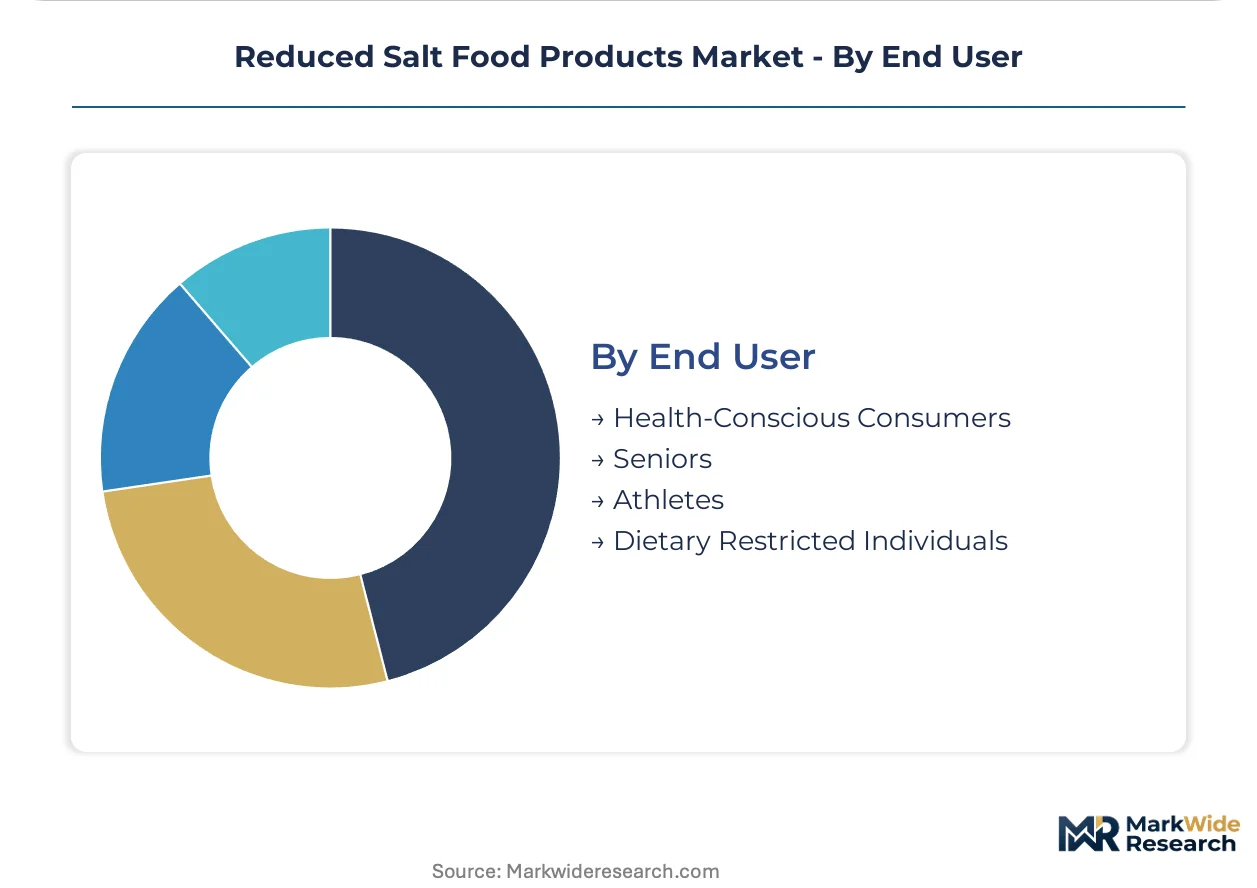
- Health-Conscious Consumers:This segment includes individuals actively seeking healthier food choices, often driven by general wellness goals and preventative health measures. A broad demographic of health-conscious consumers consistently seeks reduced-salt options, influencing product innovation across multiple food categories.
- Dietary Restricted Individuals:This segment comprises individuals with specific medical conditions, such as hypertension or kidney disease, requiring strict sodium intake limitations. Healthcare professionals often recommend reduced-sodium diets for these individuals, driving demand for specialized and clearly labeled products.
- Seniors:The seniors segment seeks reduced-salt products to manage age-related health conditions and adhere to dietary recommendations for cardiovascular health.
- Athletes:Athletes sometimes choose reduced-salt options as part of a balanced diet, though their primary focus may be on other nutritional aspects like protein or hydration.
The largest consumer base resides with health-conscious consumers, while dietary restricted individuals represent a niche with specific requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for reduced salt food products is strong in developed economies. Consumers increasingly prioritize health and wellness, driving manufacturers to reformulate. Public health initiatives further accelerate this market shift.
United Kingdom
Government-led campaigns promoting lower sodium consumption significantly drive demand for reduced-salt options. UK's Public Health England (PHE) sets voluntary sodium reduction targets for various food categories. Consumers increasingly seek healthier alternatives in their daily diets. Food manufacturers in London and the Southeast actively invest in R&D for low-sodium product lines.
United States
Rising consumer awareness of cardiovascular health and hypertension prevalence fuel demand for reduced-salt foods. The U.S. FDA has issued voluntary sodium reduction targets, influencing food manufacturers nationwide to reformulate. Major food processing hubs in the Midwest, particularly around Chicago, are centers for product innovation.
Germany
Health-conscious consumers actively seeking healthier food options drive demand for reduced-salt products across the retail sector. The German Federal Ministry of Food and Agriculture (BMEL) supports initiatives for sodium reduction in processed foods. This policy framework encourages manufacturers to innovate. Food science institutes in cities like Munich and Berlin collaborate with industry to develop advanced salt substitutes.
Japan
An aging population with specific dietary needs fuels demand for low-sodium convenience foods. The Ministry of Health, Labour and Welfare (MHLW) provides dietary guidelines emphasizing reduced sodium intake for public health. This creates an impetus for healthier alternatives. Food technology companies in Tokyo and Osaka focus on umami-rich ingredients to maintain palatability.
Brazil
Growing middle-class health consciousness and urbanization increase demand for healthier packaged foods in urban centers. ANVISA (National Health Surveillance Agency) implements food labeling regulations that highlight high sodium content for consumers. This transparency encourages brands to offer lower-sodium options. Food processing plants in São Paulo and Minas Gerais adapt production lines.
Reduced Salt Food Products Market Key Industry Players
Portfolio diversification dominates the current competitive landscape for reduced salt food products. The market exhibits a tiered structure, with large multinational corporations at the top and specialized ingredient providers forming a distinct niche segment. Strategic archetypes include global food conglomerates leveraging extensive R&D capabilities and agile ingredient innovators focusing on advanced flavor solutions. Geographic expansion into new consumer markets and technology licensing for proprietary salt reduction methods are also dominant competitive moves.
On the global scale-driven end, Nestlé S.A., a Swiss-headquartered food and beverage giant, exemplifies a major player with extensive R&D into low-sodium flavor technologies. The Kraft Heinz Company, a US-based food processing company, occupies a position focused on reformulating iconic brands across various categories. Unilever PLC, a British-Dutch multinational consumer goods company, represents another large entity with a broad product portfolio adapting to reduced-salt demands. These companies anchor the market through their wide distribution networks and brand recognition.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo, Inc. |
| General Mills, Inc. |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| Tyson Foods, Inc. |
| Hormel Foods Corporation |
| Unilever PLC |
| Campbell Soup Company |
| Others |
Cost & Logistics Intelligence
Outsourced ingredient manufacturing, particularly for specialized salt substitutes, anchors the supply position for many food manufacturers and directly influences their pricing power in the reduced salt food products market.
Pricing Analysis
Warranty-like assurances for taste parity and functional performance are often bundled into ingredient pricing for advanced salt reduction systems. The dominant pricing model remains per-unit transactional for bulk ingredients, but value-based pricing emerges for proprietary flavor technologies. Price differentiation stems from formulation complexity and certification levels for clean-label ingredients. Pricing pressure stems from the higher cost of substitutes like potassium chloride compared to sodium chloride. Health-conscious consumers show lower price sensitivity for premium, naturally formulated reduced-salt products, while budget-conscious household buyers remain highly sensitive.
Supply Chain Analysis
Direct-to-manufacturer distribution channels handle the supply of specialized salt substitutes and flavor enhancers to food processing plants. Geographic supply concentration for key ingredients like potassium chloride centers in China and Germany, while yeast extract production is global. Raw material dependencies include mineral salts and agricultural feedstocks for yeast. Single-source vulnerability for proprietary flavor systems represents a structural risk. Distribution runs through specialized ingredient distributors and direct sales teams to food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is significantly shaped by the cost of compliance with public health mandates, where voluntary sodium reduction targets from the U.S. FDA create a substantial barrier for non-compliant players.
For Market Incumbents: Lock in long-term supply agreements for advanced salt reduction ingredients to mitigate cost volatility and secure consistent quality. Invest in sensory science R&D to continuously improve taste profiles of reformulated products, countering consumer taste perception threats. Leverage extensive distribution networks to push new reduced-sodium product lines into established retail and food service channels. Deepen vertical integration into flavor technology development to protect proprietary formulations from emerging ingredient innovators.
For New Entrants and Emerging Players: Voluntary sodium reduction targets in the United Kingdom open a window for agile startups specializing in natural, clean-label salt reduction solutions. Target the snacks and sauces segments, which offer high consumer frequency and reformulation opportunities. Focus on developing seaweed or mushroom extract-based alternatives, appealing to growing demand for natural ingredients. A direct-to-consumer online sales model can rapidly establish brand presence and gather early consumer feedback.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized ingredient technology firms and food manufacturers seeking portfolio diversification. The market's long-term viability over a 5-10 year window is robust, driven by public health initiatives and evolving consumer preferences. Acquisition targets should include companies with patented flavor modulation systems or strong intellectual property in natural salt reduction. Widespread adoption of advanced flavor enhancers across mainstream processed food categories is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Proprietary Flavor Technologies | Enhances product palatability, crucial for consumer acceptance of reduced-salt formulations. |
| Expand Clean-Label Ingredient Sourcing | Meets consumer demand for natural, recognizable ingredients in healthier food options. |
| Form Strategic Partnerships with Ingredient Suppliers | Secures consistent supply and co-development opportunities for novel salt substitutes. |
| Target Emerging Markets for Product Launch | Captures growth from rising health consciousness and disposable incomes in developing nations. |
| Optimize Reformulation Cycles with AI/ML | Accelerates R&D timelines, reducing costs and time-to-market for new reduced-sodium products. |
Research Approach
Government reports, academic studies, and corporate financial filings formed the secondary backbone for this analysis. Primary research involved in-depth interviews with food scientists, R&D directors, procurement managers, and marketing executives from leading food manufacturers. This approach combined insights from industry stakeholders with robust secondary validation. Bottom-up and top-down triangulation ensured data consistency and accuracy across all market segments.
Historical trendline analysis provided the foundation for projecting market trajectories across the analysis window. The modeling framework incorporated segmentation dimensions including product type, form, application, and end-user, alongside regional regulatory influences. Compound annual growth rates were derived from a multi-factor regression model. Key forecast inputs included evolving dietary guidelines and consumer preference shifts for healthier options.
Caveats apply where unforeseen shifts in global trade policies or significant breakthroughs in salt substitute technologies could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and sustained consumer health awareness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Food Intolerance Products Market