
 Australia Gluten Free Food Market | 2026-2036
Australia Gluten Free Food Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Gluten Free Food Market Insights
Health-conscious consumers is reorganizing demand patterns across the Australia gluten free food sector, pulling shelf space and formulation investment away from purely clinical positioning. Dr. Schar AG leverages its European manufacturing heritage to anchor premium positioning in Australian supermarkets. Casalare Pty Ltd. specializes in locally milled alternative grains, sustaining regional supply chain advantages against imported competition. Goodman Fielder Pty Limited competes through broad retail distribution, extending conventional bakery reach into gluten free adjacencies.
Gluten free food comprises products formulated without wheat, barley, rye, or their crossbred variants, typically substituting rice flour, tapioca starch, or pulse proteins to achieve comparable texture and shelf stability. The category serves both celiac patients requiring strict elimination and lifestyle buyers seeking perceived digestive or wellness benefits. Breads and snacks command the largest volume pools given their centrality in daily consumption patterns, while pasta and cereals attract premium pricing due to more complex reformulation requirements. Supermarkets dominate distribution throughput, though online retail captures the fastest growth trajectory as subscription models and direct-to-consumer brands bypass traditional slotting fee barriers.
FSANZ mandates strict allergen labelling under the Australia New Zealand Food Standards Code, compelling manufacturers to validate gluten content below detectable thresholds. Coeliac Australia endorsement programs create a parallel voluntary certification layer that influences procurement decisions by institutional buyers and retail category managers. TGA oversight of gluten-free health claims prevents therapeutic overreach in marketing communications. Stakeholders must monitor how evolving FSANZ definition refinements and state-level food service procurement policies reshape competitive access across the eastern seaboard.
Market Dynamics
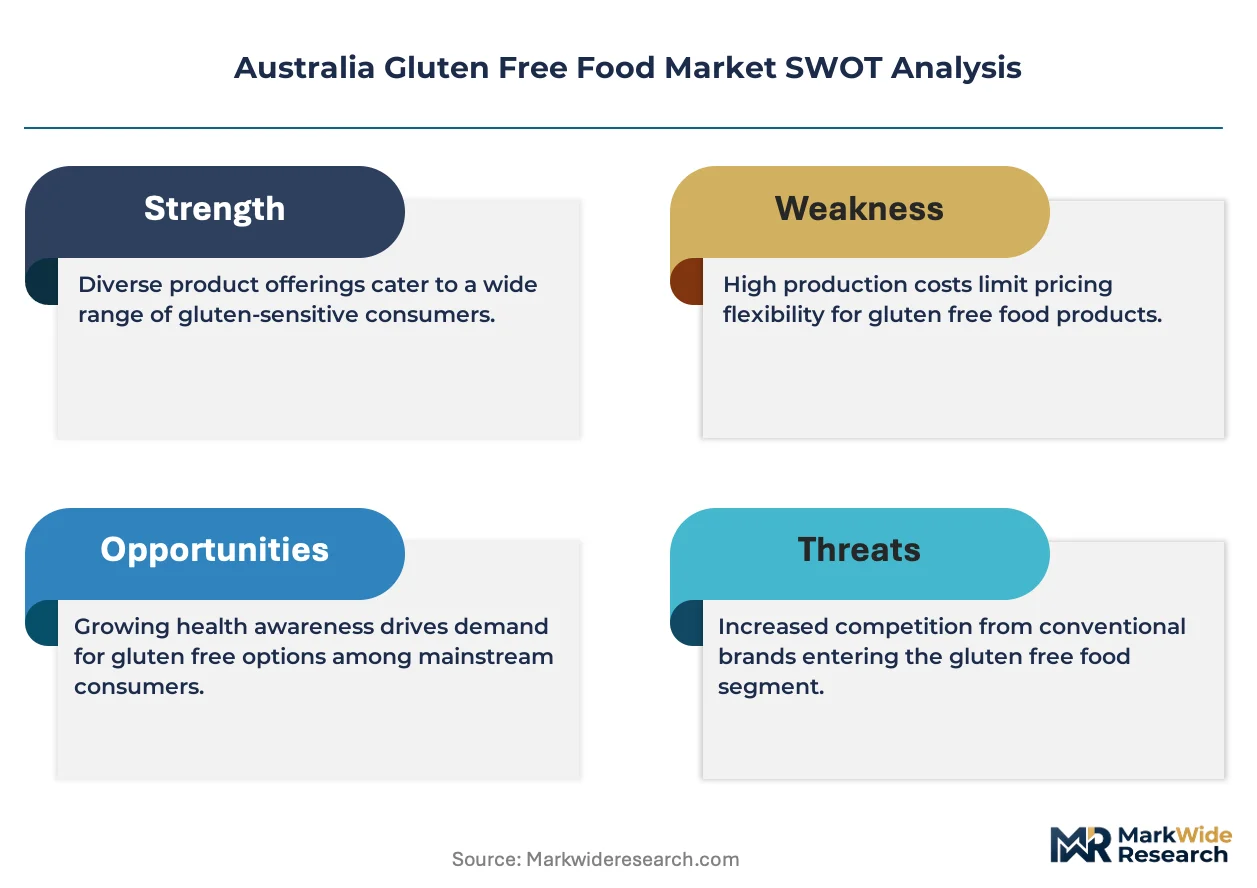
Health-conscious discretionary buyers are fragmenting the Australia gluten free food market away from its historical clinical anchor, forcing manufacturers to reformulate for taste parity rather than strict allergen compliance alone. This demand bifurcation strains legacy production assets and rewards dual-positioned brands.
Growth Catalysts
- FSANZ Allergen Labelling Mandates:Strict thresholds under the Australia New Zealand Food Standards Code compel manufacturers to validate gluten content below detectable limits, accelerating certified product proliferation across retail shelves.
- Pulse Protein Advancement:Australian food technologists are refining lentil and faba bean isolates to replicate wheat gluten's viscoelastic properties, expanding viable formulation bases beyond rice and tapioca.
- Urban Density in New South Wales:Sydney's concentrated premium retail infrastructure supports dedicated gluten free shelf space and category management investment unmatched in regional markets.
Market Restraints
- Input Cost Volatility:Australian quinoa and sorghum prices fluctuate with irrigation water allocation cycles, compressing margins for locally milled alternative grain suppliers.
- Import Dependency:European specialty ingredients dominate high-performance binding agents, exposing domestic manufacturers to freight cost spikes and currency risk.
- Technical Texture Ceilings:Rice flour formulations fail to achieve the crumb structure of wheat bread, limiting repeat purchase rates among non-celiac lifestyle buyers.
Strategic Opportunities
- Queensland and Western Australia:These states show underpenetrated retail gluten free shelf space relative to household income growth, offering first-mover expansion corridors.
- Direct-to-Consumer Subscription:Melbourne-based digital-native brands bypass supermarket slotting fees through recurring delivery models, capturing margin and customer data.
- Coeliac Australia Certification Tailwind:The endorsement program's procurement influence among institutional food service buyers creates a parallel compliance layer beyond FSANZ minimums.
Industry Challenges
- Food Technologist Shortage:Australian universities produce limited gluten free formulation specialists, forcing manufacturers to recruit from European baking institutes at premium compensation.
- Dual Production Line Capex:Segregated facilities for gluten free and conventional products require redundant equipment investments that strain mid-cap balance sheets.
- Extended TGA Health Claim Timelines:Therapeutic Goods Administration review periods for digestive wellness claims delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Gluten Free Food Market |
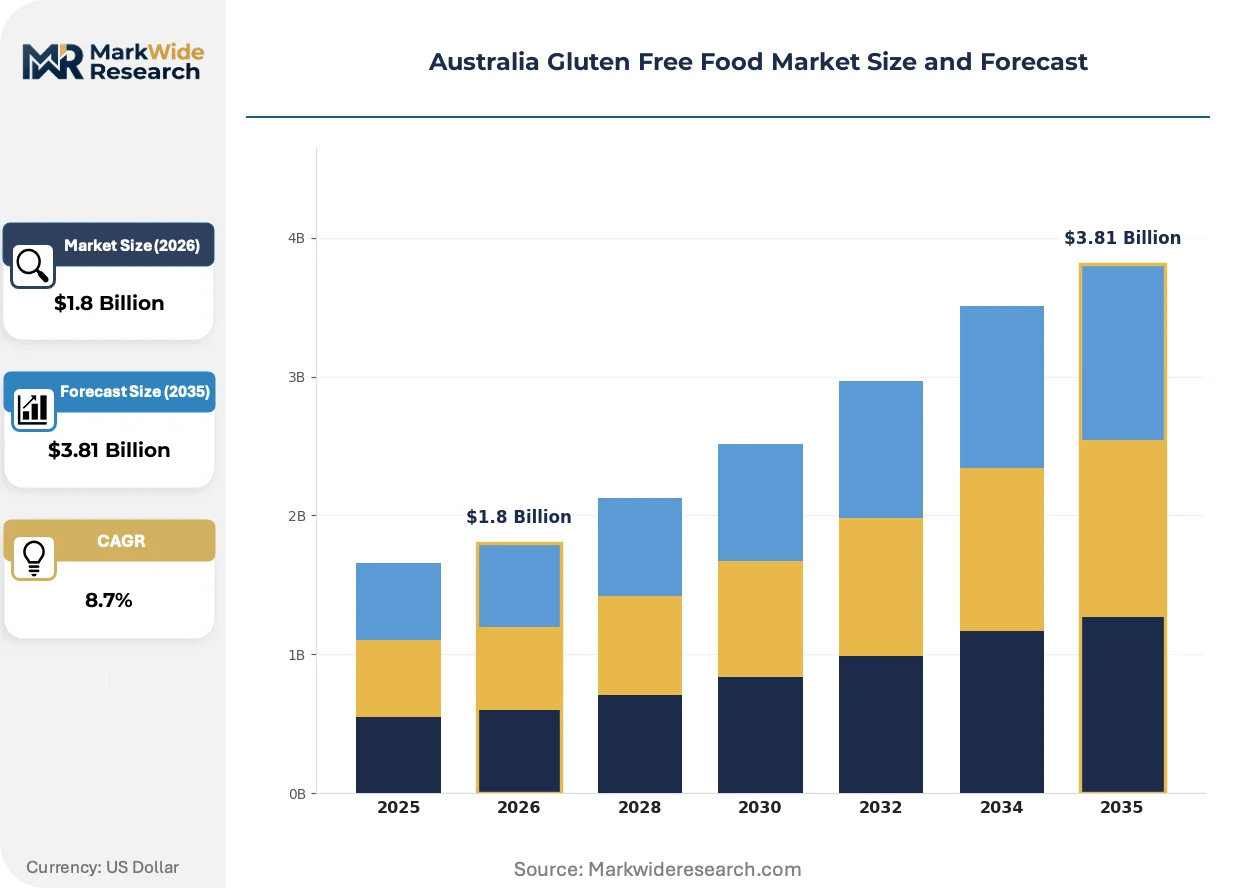
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Snacks, Pasta, Cereals Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Health-Conscious Consumers, Celiac Patients, Food Bloggers, Athletes Packaging Type: Box, Bag, Jar, Pouch |
| Companies Covered | Dr. Schar AG, Casalare Pty Ltd., Deeks Health Foods, Choices Gluten & Wheat Free Pty Limited, The Sanitarium Health and Wellbeing Company, Arnott's Group, Genius Foods, Goodman Fielder Pty Limited, ORGRAN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Gluten Free Food Market Trends and Innovations
Ingredient science and channel architecture are converging to reshape how Australian consumers access and perceive gluten free nutrition. Three developments warrant particular attention from stakeholders mapping competitive position.
Enzymatic gluten degradation technology is fragmenting the market's technical foundations. Australian ingredient suppliers now license transglutaminase and protease systems that modify protein structures in alternative grains to mimic wheat functionality. Artisan bakeries in Melbourne and Sydney are piloting these enzymatic treatments at small batch scale, compressing the texture gap that has historically limited category expansion beyond medical necessity. The technology is fragmenting premium positioning by enabling mid-tier brands to achieve sensory parity with heritage European imports.
FSANZ definition refinements under Standard 1.2.8 are tightening the analytical methods permitted for gluten quantification. Manufacturers must now deploy ELISA and mass spectrometry protocols that detect hordein and secalin fragments previously escaping assay capture. Small domestic mills lacking in-house laboratory capacity face outsourcing costs that favor integrated processors with captive testing infrastructure. Victoria-based contract manufacturers are responding by consolidating testing services and offering certified production runs to external brand owners.
Subscription-based replenishment is displacing conventional supermarket stock-up behavior among Australian metropolitan households. Direct-to-consumer platforms in Brisbane and Perth leverage consumption data to personalize product assortments and delivery cadences, capturing loyalty through convenience rather than shelf visibility. This channel shift is most pronounced among millennial parents managing multiple dietary restrictions within single households, who prioritize time efficiency over in-store browsing.
Australia Gluten Free Food Market Segmentation
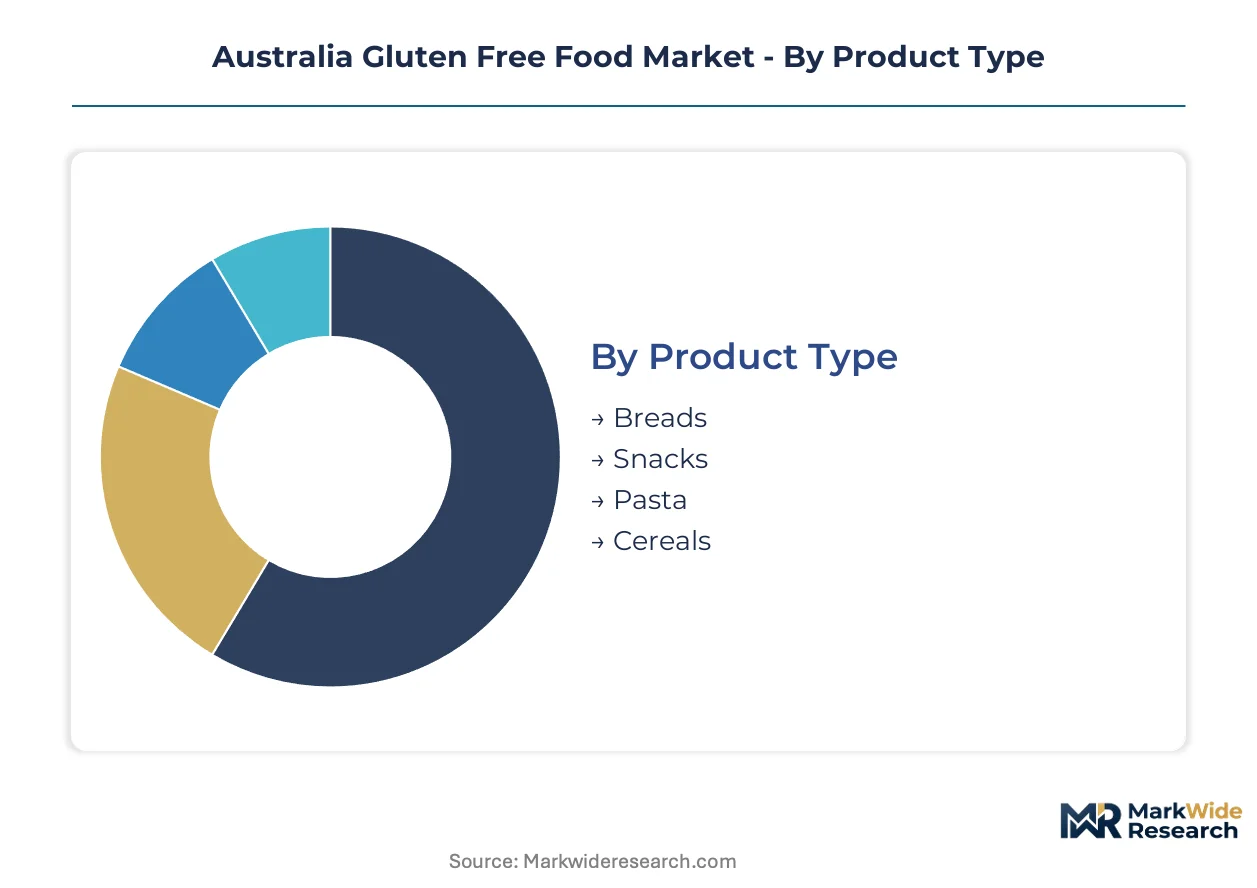
Segmentation in the Australian gluten free food sector reveals how formulation complexity and channel access stratify profit pools. Manufacturers must align production assets against specific demand pockets rather than treating the category as monolithic.
Product Type:
Substitution pressure varies sharply across product formats, with wheat-alternative staples facing the most intense competitive threat from conventional baked goods.
- Breads:Formulations rely on xanthan gum and hydrocolloid systems to compensate for gluten's absence, achieving crumb structure through modified starch blends. New South Wales households drive the largest volume concentration, though repeat purchase rates lag among non-celiac lifestyle buyers due to texture limitations.
- Snacks:Extruded and baked formats using rice flour, cassava starch, or pulse protein bases dominate shelf-stable offerings. Victoria's premium retail infrastructure supports the steepest innovation cadence, with Melbourne-based brands pushing savory flavor profiles beyond traditional sweet positioning.
- Pasta:Brown rice and legume-based extrusions require higher capital investment in die technology. Queensland's underpenetrated retail landscape limits immediate expansion potential relative to southern states.
- Cereals:Cold breakfast formats utilizing puffed ancient grains compete against conventional oat and wheat offerings. FSANZ allergen labelling mandates add compliance costs that favor larger manufacturers with captive testing facilities.
Breads anchors the volume base while snacks gains share at the steepest rate.
Distribution Channel:
Channel economics determine margin capture, with slotting fee structures and inventory carrying costs creating divergent profitability profiles across access points.
- Supermarkets:Coles and Woolworths command the dominant throughput, with dedicated shelf space expanding in Sydney and Melbourne metropolitan stores. Category management investments by national retailers favor suppliers with broad SKU ranges and consistent FSANZ-compliant documentation.
- Health Food Stores:Independent retailers in Brisbane and Perth concentrate on certified organic and additive-free positioning. These outlets serve as launch platforms for emerging brands before supermarket scale-up.
- Online Retail:Subscription models and direct-to-consumer platforms bypass traditional distribution markups. Melbourne-based digital-native brands leverage consumption data to personalize replenishment cadences for multi-restriction households.
- Specialty Stores:Coeliac Australia-endorsed retail points concentrate in Victoria and New South Wales urban centers. Procurement decisions at these outlets prioritize certification compliance over price competitiveness.
Supermarkets anchors the volume base while online retail expands most quickly.
End User:
User motivation splits the market between strict elimination requirements and discretionary wellness positioning, with formulation standards diverging accordingly.
- Health-Conscious Consumers:Discretionary buyers seeking perceived digestive benefits or general wellness drive the fastest category expansion. These purchasers prioritize taste parity over strict allergen thresholds, pressuring manufacturers to improve sensory performance.
- Celiac Patients:Medically diagnosed consumers require absolute gluten elimination validated through Coeliac Australia certification. This segment concentrates in Victoria and New South Wales where diagnostic infrastructure and specialist gastroenterology services are most accessible.
- Food Bloggers:Content creators influence trial and awareness through recipe development and product reviews. Their audience reach disproportionately impacts emerging brand discovery in metropolitan Australian markets.
- Athletes:Sports nutrition positioning leverages gluten free claims as proxies for clean-label or performance-oriented formulations. Queensland and Western Australia show emerging demand correlation with endurance sports participation rates.
Celiac patients anchors the volume base while health-conscious consumers climbs the fastest.
Packaging Type:
Packaging selection reflects shelf-life requirements, portion control preferences, and sustainability positioning across consumer touchpoints.
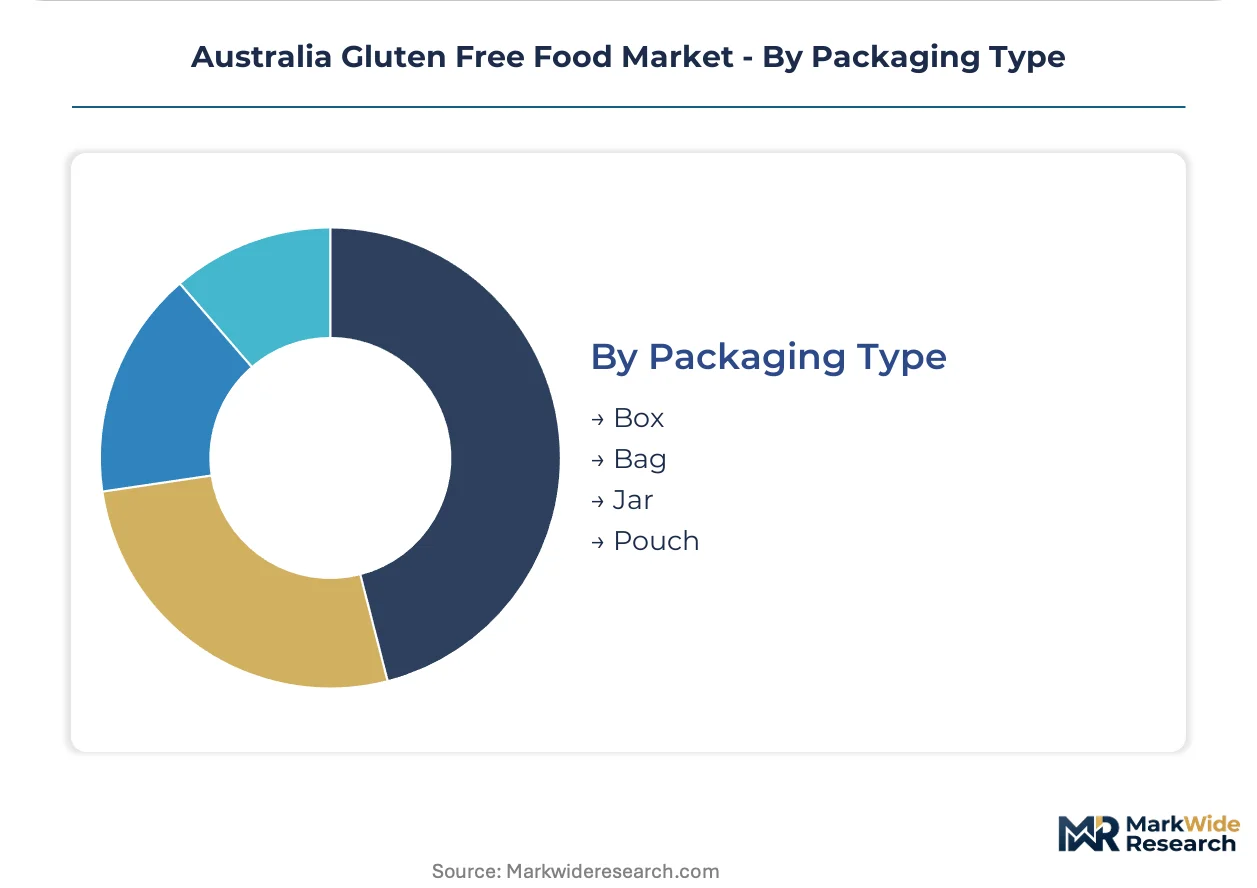
- Box:Cereals and dry pasta formats utilize folding carton structures with barrier coatings. Victorian packaging converters supply the majority of domestic demand, reducing lead times for Melbourne-based food manufacturers.
- Bag:Flexible films dominate bread and snack formats, with modified atmosphere technologies extending shelf stability. Import dependency for high-performance barrier films exposes domestic brands to freight cost volatility.
- Jar:Glass containers concentrate in premium spreads and wet prepared foods. Higher unit economics limit penetration to specialty retail channels in Sydney and Melbourne.
- Pouch:Stand-up flexible formats gain traction in single-serve and on-the-go positioning. Queensland manufacturers pilot recyclable mono-material structures to preempt pending state-level packaging regulations.
Bag anchors the volume base while pouch shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European specialty ingredient suppliers dominate high-performance binding agent exports to Australian manufacturers, creating freight cost exposure along the Rotterdam-Sydney corridor. This trade dependency shapes regional distribution strategies and inventory holding patterns across Australian states.
New South Wales
Sydney's concentrated premium retail infrastructure supports dedicated gluten free shelf space unmatched elsewhere. FSANZ allergen labelling mandates under the Australia New Zealand Food Standards Code drive compliance investment by Coles and Woolworths headquarters operations. Parramatta-based contract manufacturers consolidate testing services for smaller brand owners lacking captive laboratory capacity.
Victoria
Melbourne households generate the steepest innovation cadence in savory snack flavor profiles. Coeliac Australia certification programs influence procurement decisions by institutional food service buyers concentrated in the metropolitan area. Victorian packaging converters supply folding carton structures to domestic cereal manufacturers, reducing lead times against interstate competitors.
Queensland
Brisbane shows underpenetrated retail gluten free shelf space relative to household income growth trajectories. State-level food service procurement policies create compliance layers beyond federal FSANZ minimums for hospital and education sector suppliers. Gold Coast manufacturers pilot recyclable mono-material pouch structures to preempt pending packaging regulations.
Western Australia
Perth's isolation from eastern manufacturing clusters drives direct-to-consumer subscription model adoption. TGA oversight of gluten-free health claims affects product launch timelines for brands targeting sports nutrition positioning. Fremantle-based digital-native brands leverage consumption data to personalize replenishment for multi-restriction households.
South Australia
Adelaide's lower commercial rent structures attract emerging brands seeking production facility establishment. Irrigation water allocation cycles for local quinoa and sorghum suppliers create input cost volatility compressing margins. The Barossa Valley food manufacturing corridor hosts specialist mills refining lentil and faba bean isolates for pasta extrusion applications.
Australia Gluten Free Food Market Competitive Landscape
Player mix skews toward mid-cap domestic specialists with regional supply chain advantages against European imports. Market structure exhibits moderate consolidation around integrated processors with captive testing infrastructure, while fragmented artisan bakeries occupy premium positioning. Two strategic archetypes dominate: heritage European exporters leveraging manufacturing scale, and Australian本土 mills exploiting local grain sourcing relationships. Competitive moves concentrate on geographic expansion into underpenetrated states and portfolio diversification beyond bread into snack and pasta adjacencies.
Within the European heritage tier, Dr. Schar AG anchors premium supermarket positioning through its AG corporate structure. Among Australian-based specialists, Casalare Pty Ltd. occupies a position exemplifying regional supply chain focus, while Goodman Fielder Pty Limited represents the diversified food conglomerate archetype extending conventional bakery reach. These three entities collectively illustrate the competitive tension between imported scale and domestic sourcing agility that defines procurement decisions by major retailers.
| Leading Market Players |
|---|
| Dr. Schar AG |
| Casalare Pty Ltd. |
| Deeks Health Foods |
| Choices Gluten & Wheat Free Pty Limited |
| The Sanitarium Health and Wellbeing Company |
| Arnott's Group |
| Genius Foods |
| Goodman Fielder Pty Limited |
| ORGRAN |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at European binding agent plants shapes both import price floors and domestic manufacturer margins, compressing mid-tier Australian brands between heritage premium positioning and local grain cost volatility.
Pricing Analysis
Enzymatic treatment pricing gaps separate heritage European imports from next-generation Australian formulations using licensed transglutaminase systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by Coeliac Australia certification status and sensory performance tier. Cost compression in the standard tier intensifies because pulse protein advancement reduces formulation cost gaps. Health-conscious discretionary buyers show highest price sensitivity, while diagnosed celiac patients accept premium positioning for certified assurance.
Supply Chain Analysis
Italy and Germany anchor high-performance hydrocolloid and modified starch exports to Australian gluten free manufacturers. Domestic production draws from Queensland sorghum and South Australian lentil isolates, yet rests on European xanthan gum and specialty enzyme imports. Single-source vulnerability concentrates in the Rotterdam-Sydney freight corridor where container cost spikes transmit directly to ingredient landed costs. Distribution runs through Coles and Woolworths headquarters procurement in Sydney, with direct-to-consumer platforms capturing margin bypass in Melbourne and Perth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against conventional bakery adjacencies as Goodman Fielder and Arnott's extend gluten-free SKU ranges through existing retail relationships.
For Market Incumbents: Secure Coeliac Australia certification lock-in through exclusive institutional food service contracts in Victoria and New South Wales hospitals. Deepen backward integration into South Australian pulse protein milling to offset European hydrocolloid import dependency. Anchor premium positioning against enzymatic texture parity threats from mid-tier domestic competitors.
For New Entrants and Emerging Players: Anchor in Queensland's underpenetrated retail shelf space where household income growth outpaces dedicated gluten free category development. Target direct-to-consumer subscription models in Perth to bypass eastern seaboard slotting fee barriers. Leverage recyclable mono-material pouch pilot programs as sustainability differentiation against established bag-format incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Melbourne-based digital-native brands with personalized replenishment algorithms for multi-restriction households. Acquisition targets should exhibit captive testing infrastructure under FSANZ Standard 1.2.8 and consolidated contract manufacturing relationships. Watch for enzymatic gluten degradation technology licensing deals as inflection signals for texture parity disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Coeliac Australia Certification Investment | Endorsement unlocks institutional procurement in Victorian hospital systems. |
| Pulse Protein Backward Integration | Captive lentil and faba bean milling reduces European hydrocolloid exposure. |
| Direct-to-Consumer Platform Launch | Subscription models bypass Coles and Woolworths slotting fee structures. |
| Enzymatic Texture Technology Licensing | Transglutaminase systems compress sensory gaps against heritage imports. |
| Recyclable Packaging Transition | Mono-material pouch structures preempt Queensland state-level regulations. |
Research Methodology
The analysis maps breads, snacks, pasta, and cereals segments, each validated through food technologists at contract manufacturers, category buyers at Coles and Woolworths, supply planners at alternative grain mills, and regulatory affairs specialists at FSANZ. Primary interview data triangulates against FSANZ allergen labelling guidance documents, Coeliac Australia certification databases, Australia New Zealand Food Standards Code amendments, and customs import records for European specialty ingredients. Bottom-up production capacity estimates and top-down retail audit data converge through iterative stakeholder cross-checking.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, distribution channel, end user motivation, and packaging format dimensions. CAGRs derive from trend extrapolation of certified product proliferation rates and urban density correlation analysis. Forecast inputs include irrigation water allocation cycle impacts on local grain prices and TGA health claim review timeline assumptions.
Material uncertainties — FSANZ definition refinements, state-level food service procurement policy shifts, and enzymatic technology licensing cost trajectories — sit outside the modeled envelope. Forecasts reflect assumptions about discretionary buyer retention and European freight cost stability. Recalibration cycles align with material shifts in FSANZ analytical method updates and Coeliac Australia endorsement program revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
North America Gluten-Free Food and Beverage Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Food Allergy and Intolerance Products Market