
 Australia Gluten-Free Foods and Beverages Market | 2026-2036
Australia Gluten-Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Gluten-Free Foods and Beverages Market Outlook
Australian specialty grain millers is restructuring supply chains to secure dedicated gluten-free processing facilities across Queensland and South Australia. Arnott's Group leverages its nationwide biscuit distribution network to place certified gluten-free lines in mainstream supermarkets. Genius Foods Ltd anchors its competitive position through deep specialization in free-from bakery formats. The Sanitarium Health and Wellbeing Company differentiates via health-focused branding that resonates with wellness-oriented Australian consumers.
Gluten-free foods and beverages comprise edible products formulated without wheat, barley, rye, or their crossbred derivatives, typically substituting rice, corn, quinoa, or buckwheat flour to achieve equivalent texture and shelf stability through modified starch systems and hydrocolloid binding agents. These products serve individuals with celiac disease, non-celiac gluten sensitivity, and voluntary lifestyle adopters seeking digestive wellness. The breads and snacks categories dominate current shelf space and consumer familiarity, while pasta represents a faster-growing segment as manufacturing techniques improve al dente texture. Supermarkets control the bulk of volume flow, though online retail channels capture disproportionate growth from subscription-based repeat purchasers in remote and regional areas.
FSANZ governs gluten-free labeling claims through Standard 1.2.8, mandating that products labeled "gluten free" contain no detectable gluten, while the Coeliac Australia endorsement program provides third-party certification that shapes consumer trust and retail listing decisions. ACCC compliance monitoring enforces against misleading health claims, pressing manufacturers toward substantiated ingredient sourcing transparency. Stakeholders must track evolving FSANZ threshold revisions and anticipate how Coeliac Australia's certification expansion into food service channels will reshape competitive access across restaurants and institutional catering contracts.
Market Dynamics
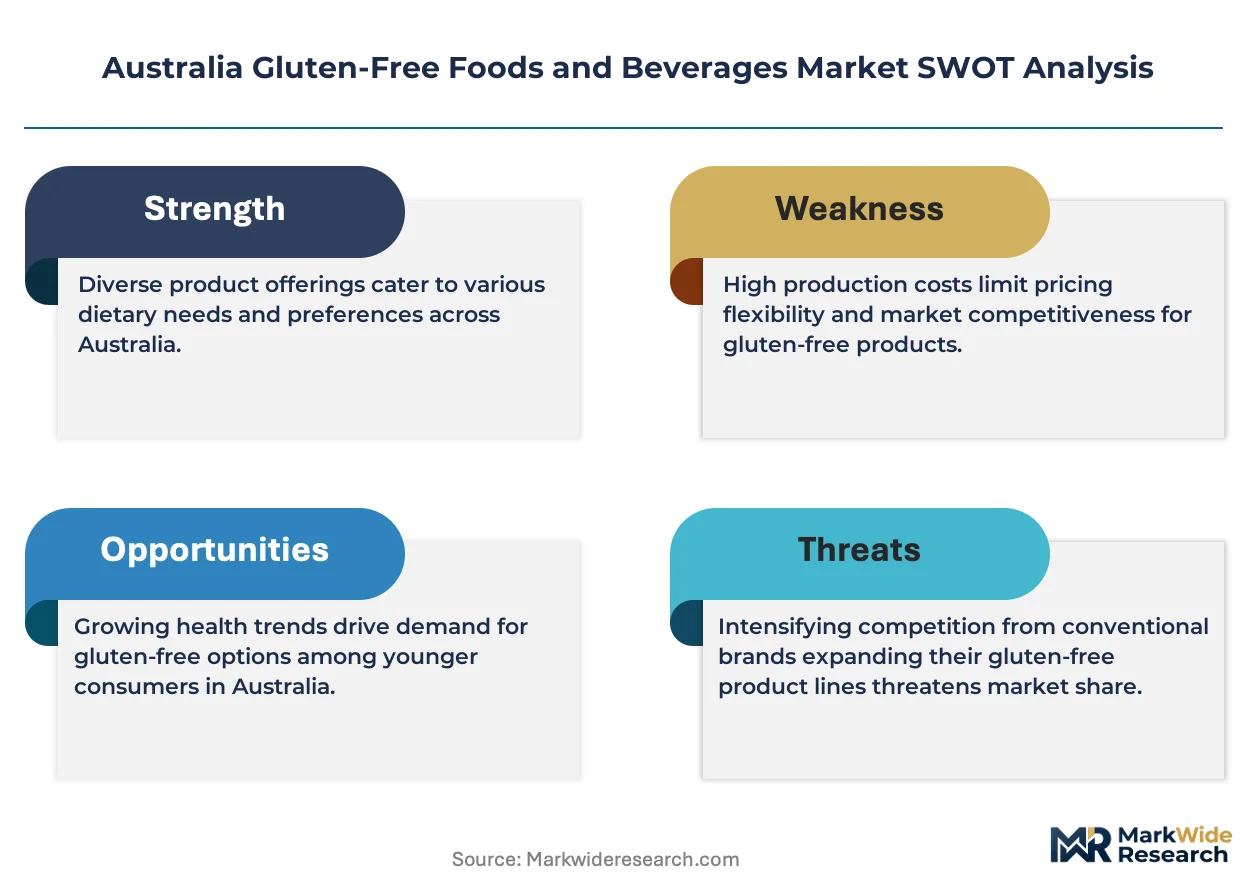
FSANZ threshold revisions for gluten detection are compressing formulation timelines while forcing dedicated facility investments across Australian manufacturing. Specialty grain millers now face capital allocation decisions between multi-purpose plants and segregated gluten-free infrastructure.
Growth Catalysts
- Coeliac Australia Certification:Third-party endorsement programs expand retail listing access and institutional catering contracts. Consumer trust in verified products drives repeat purchase behavior in supermarket channels.
- New South Wales Demand Concentration:Urban supermarket chains in Sydney and surrounding regions stock the widest certified product ranges. Household penetration rates exceed other states due to higher diagnostic awareness.
- Rice and Quinoa Flour Substitution:Modified starch systems and hydrocolloid binding agents achieve equivalent texture to wheat-based formulations. Processing advances reduce sensory gaps that previously limited category acceptance.
Market Restraints
- Input Cost Volatility:Sorghum and buckwheat prices fluctuate with Australian drought cycles and global specialty grain supply. Formulation cost premiums persist versus conventional wheat-based alternatives.
- Queensland Processing Concentration:Limited dedicated gluten-free milling capacity in northern states forces long-haul distribution to major demand centers. Supply chain mileage adds spoilage risk and working capital burden.
- FSANZ Compliance Friction:Mandatory labeling audits and detectable gluten thresholds require specialized testing infrastructure. Smaller manufacturers face disproportionate compliance cost absorption.
Strategic Opportunities
- Food Service Channel Expansion:Coeliac Australia certification extension into restaurant and institutional catering contracts creates new volume pools. Untapped demand exists in hospital and aged-care procurement.
- Victoria Manufacturing Cluster:Melbourne-area production hubs can serve both domestic eastern seaboard and export markets. Existing pharmaceutical-grade food processing infrastructure offers conversion potential.
- Subscription-Based Online Retail:Remote and regional Australian households seek automated replenishment for specialty dietary products. Direct-to-consumer platforms capture loyalty through personalized nutrition profiling.
Industry Challenges
- Cross-Contamination Control:Segregated production lines and cleaning validation protocols demand capital-intensive facility redesign. Existing multi-purpose plants face extended downtime during format switches.
- Al Dente Texture Achievement:Pasta manufacturing techniques require ongoing R&D investment to match wheat-based mouthfeel. Consumer acceptance thresholds for gluten-free pasta remain higher than for bread or snack categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Gluten-Free Foods and Beverages Market |
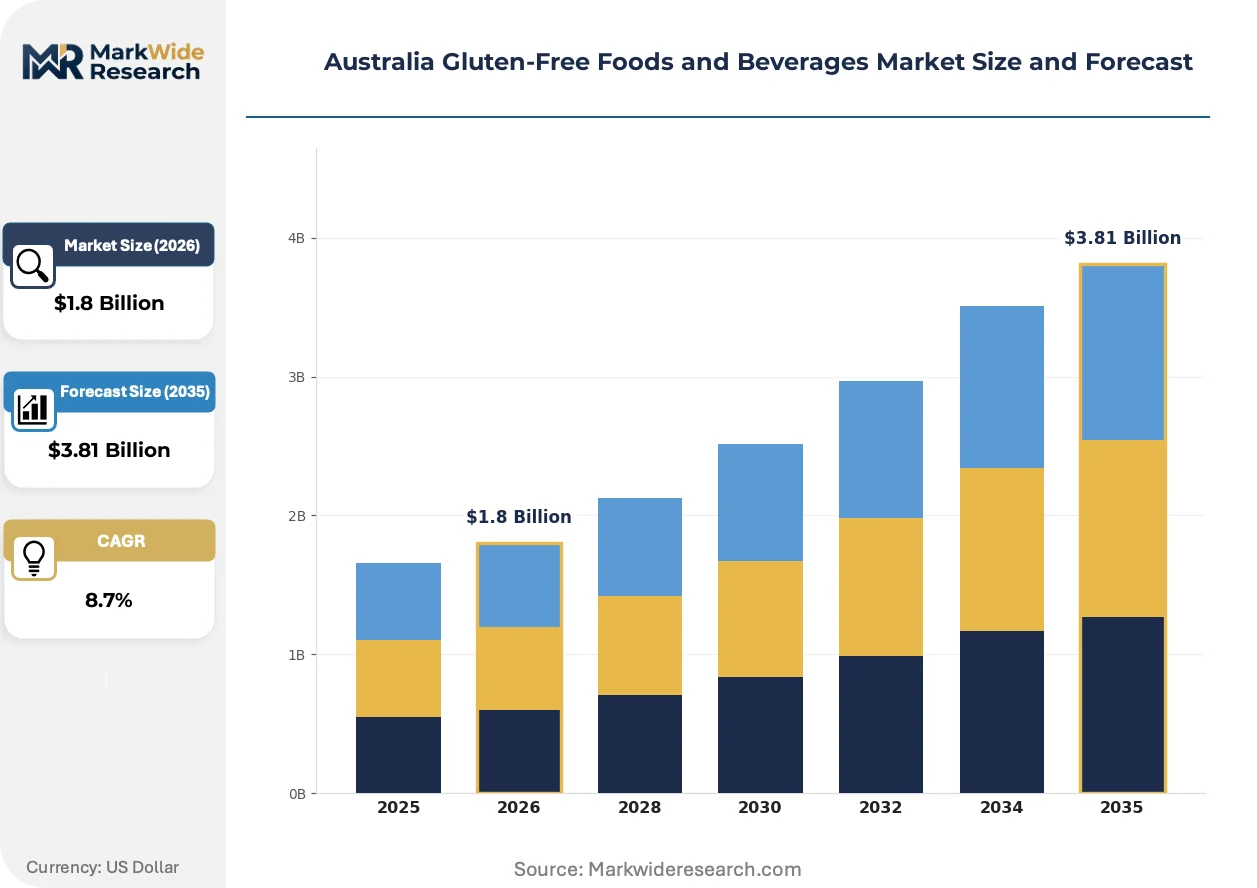
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Snacks, Cereals, Pasta Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Cafes, Institutions Ingredient Source: Rice, Corn, Quinoa, Buckwheat |
| Companies Covered | Arnott's Group, Genius Foods Ltd, The Sanitarium Health and Wellbeing Company, Kellogg Company, Unilever, General Mills Inc., Bob's Red Mill Natural Foods, Freedom Nutritional Products Limited, Dr. Schar AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Gluten-Free Foods and Beverages Market Strategic Shifts
Ingredient science and certification protocols are restructuring competitive access across Australian retail and food service channels. Manufacturers now compete on traceability transparency rather than formulation alone.
Modified starch systems incorporating tapioca and potato derivatives are rewriting texture benchmarks for gluten-free bread and pastry applications. Arnott's Group and specialty bakers accelerate adoption to close sensory gaps with conventional products. This convergence is compressing the premium price differential between certified and mainstream bakery lines.
FSANZ Standard 1.2.8 enforcement through ACCC compliance monitoring tightens substantiation requirements for gluten-free claims. Manufacturers must document ingredient sourcing and testing protocols to avoid misleading health claim penalties. The breads and snacks categories face the steepest audit intensity due to higher consumer exposure and complaint volume.
Wellness-oriented Australian consumers now prioritize digestive health claims over simple allergen avoidance. Supermarket buyers in New South Wales and Victoria demand expanded free-from product ranges spanning bakery, pasta, and beverage formats. This preference rotation is forcing distributors to consolidate supplier relationships with full-category specialists rather than single-format vendors.
Australia Gluten-Free Foods and Beverages Market Segmentation
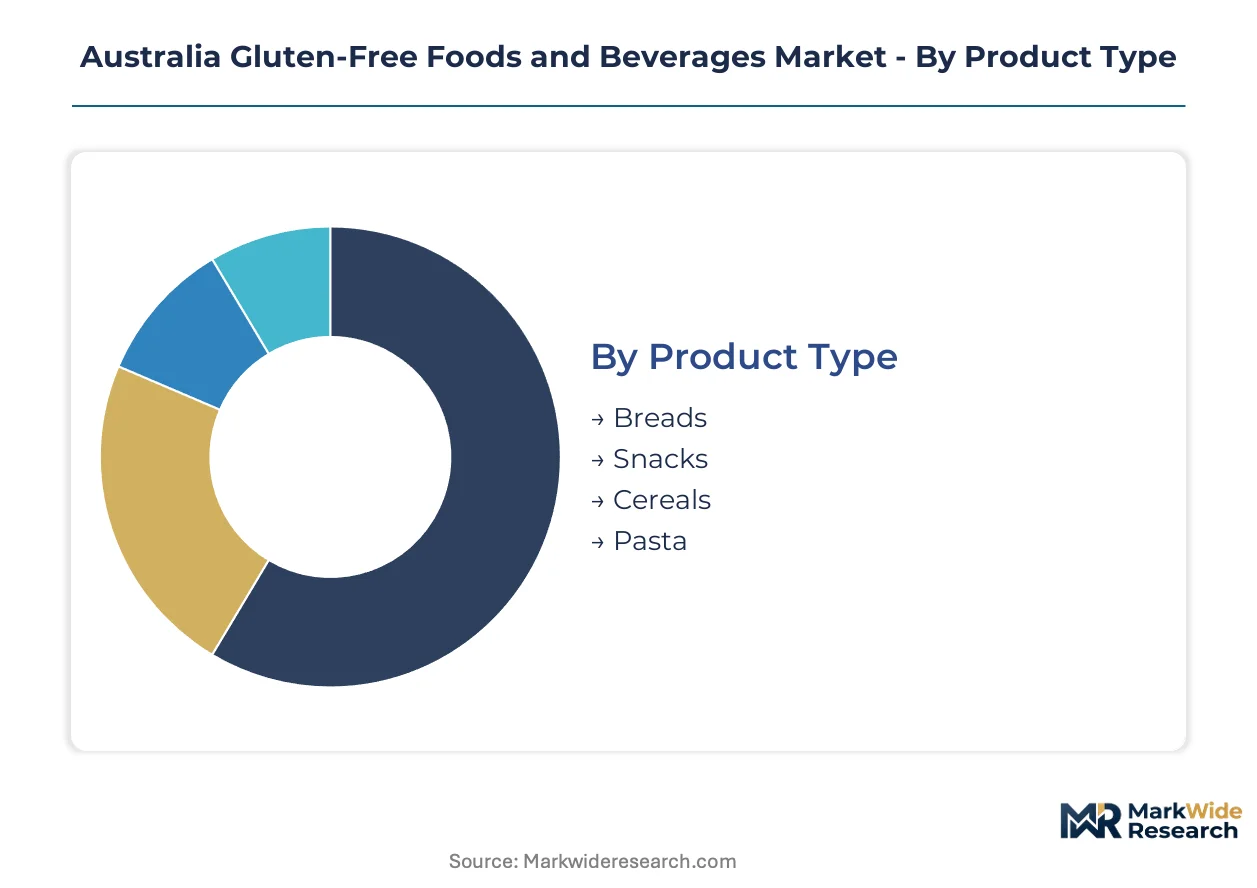
Product differentiation across Australia's gluten-free market follows distinct consumption occasions and ingredient sourcing strategies. Manufacturers align formulation investments with channel-specific margin structures and end-user certification requirements.
Product Type:
Reformulation cycles for texture-matched alternatives drive capital allocation toward segments with the steepest sensory improvement curves.
- Breads:Modified starch systems and hydrocolloid binding agents replicate wheat-based crumb structures. New South Wales and Victoria supermarkets stock the widest certified ranges, with Coeliac Australia endorsement shaping retail listing decisions.
- Snacks:Arnott's Group leverages nationwide biscuit distribution networks for certified gluten-free placement. Health-focused branding resonates with wellness-oriented consumers seeking digestive benefits beyond allergen avoidance.
- Cereals:Sanitarium Health and Wellbeing Company anchors positioning through breakfast-format specialization.
- Pasta:Al dente texture achievement requires ongoing R&D investment to match wheat-based mouthfeel acceptance thresholds.
Breads sits at the top of the volume ranking, with Pasta climbing the fastest.
Distribution Channel:
Channel economics vary sharply between high-frequency replenishment models and low-velocity specialty procurement.
- Supermarkets:Control bulk volume flow through Coles and Woolworths certified product ranges. Urban chains in Sydney and Melbourne demand expanded free-from portfolios spanning bakery, pasta, and beverage formats.
- Online Retail:Subscription-based platforms capture disproportionate growth from remote and regional Australian households. Direct-to-consumer loyalty programs leverage personalized nutrition profiling for automated replenishment.
- Health Food Stores:Independent retailers concentrate in metropolitan wellness corridors with higher diagnostic awareness.
- Specialty Stores:Dedicated gluten-free boutiques serve celiac disease households with cross-contamination control guarantees.
Supermarkets dominate current volume, with Online Retail expanding most quickly.
End User:
Procurement specifications diverge between retail household purchasing and institutional contract requirements.
- Households:Weekly grocery purchases of certified items expand among celiac disease and gluten sensitivity diagnoses. FSANZ Standard 1.2.8 compliance underpins consumer trust in detectable gluten thresholds.
- Restaurants:Coeliac Australia certification extension into food service channels creates new volume pools. Untapped demand exists in menu transparency for dining-out occasions.
- Cafes:Melbourne and Sydney specialty coffee culture drives grab-and-go bakery format adoption.
- Institutions:Hospital and aged-care procurement contracts require segregated supply chain documentation.
Households command the largest share, with Restaurants gaining share fastest.
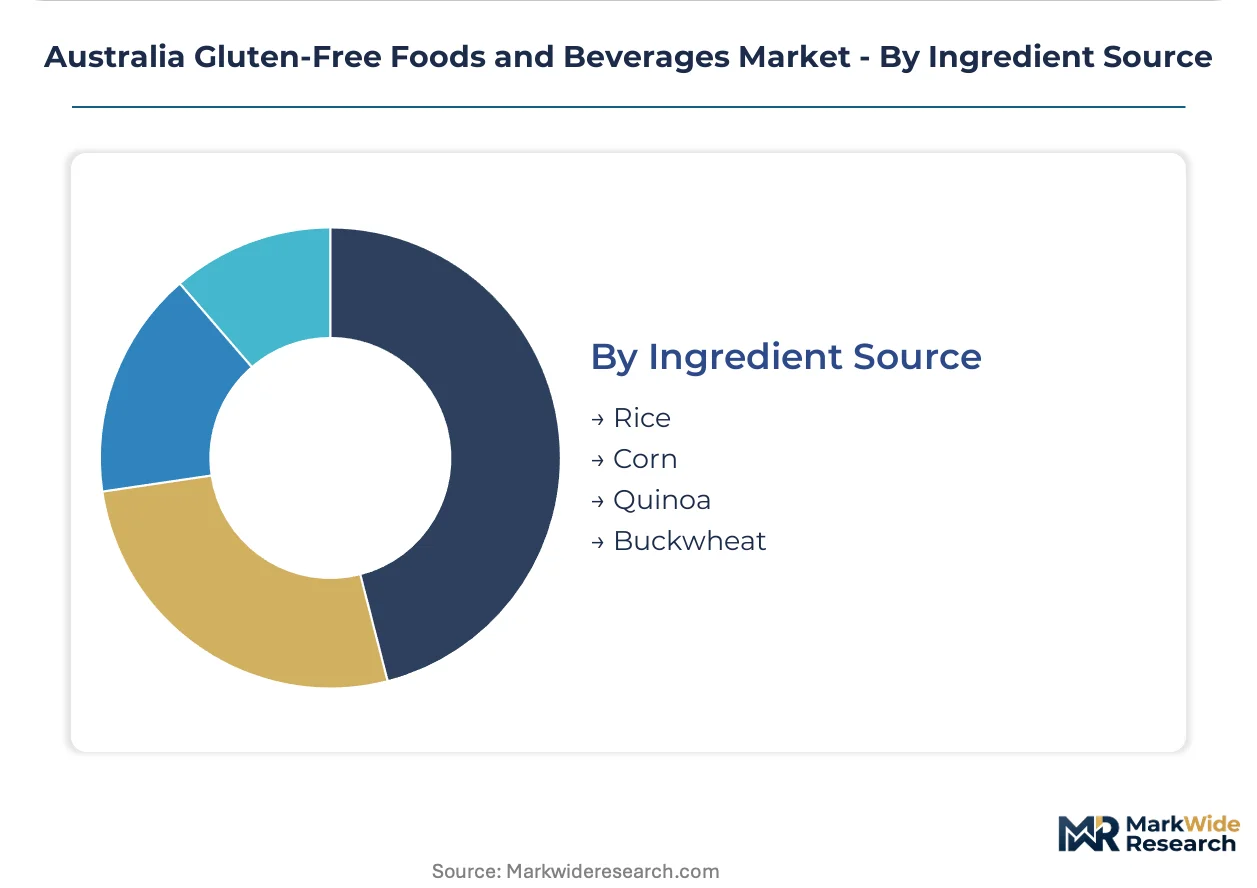
Ingredient Source:
Raw material sourcing strategies respond to Australian drought cycles and global specialty grain supply fluctuations.
- Rice:Australian specialty grain millers secure dedicated processing facilities for segregated gluten-free infrastructure. Queensland and South Australia milling capacity reduces long-haul distribution mileage to eastern seaboard demand centers.
- Quinoa:Premium positioning supports health-focused branding with complete protein nutritional claims. Import dependency creates working capital burden from currency and shipping cost volatility.
- Corn:Domestic supply chain integration offers cost stability relative to imported alternatives.
- Buckwheat:Drought-exposed pricing fluctuates with Australian growing season outcomes.
Rice leads ingredient utilization, with Quinoa showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSANZ threshold revisions create compliance-cost arbitrage between states with established gluten-free infrastructure and those still building dedicated capacity. Manufacturers face location decisions weighted against testing-lab proximity and distribution mileage to eastern seaboard demand centers.
New South Wales
Sydney households drive the highest certified product penetration rates nationwide through elevated diagnostic awareness. FSANZ Standard 1.2.8 enforcement through the NSW Food Authority shapes retail listing requirements for supermarket chains. Parramatta and Western Sydney distribution hubs concentrate Coeliac Australia-endorsed inventory for national dispatch.
Victoria
Melbourne's specialty coffee culture accelerates grab-and-go bakery format adoption among wellness-oriented consumers. The Victorian Department of Health and Human Services coordinates with FSANZ on allergen labeling audits for local manufacturers. Melbourne-area production clusters leverage existing pharmaceutical-grade food processing infrastructure for gluten-free conversion.
Queensland
Brisbane and Gold Coast urban centers exhibit rising celiac disease diagnosis rates driving weekly grocery basket expansion. Queensland Health enforces FSANZ compliance through regional food safety inspections. Limited dedicated milling capacity in northern states forces long-haul distribution to eastern seaboard demand centers, adding spoilage risk.
South Australia
Adelaide specialty grain millers secure segregated gluten-free processing facilities to reduce supply chain mileage. Primary Industries and Regions SA coordinates drought-response programs affecting sorghum and buckwheat input costs. Barossa Valley and Adelaide Plains agricultural zones anchor domestic rice and corn supply chain integration.
Western Australia
Perth metropolitan households in remote isolation drive disproportionate online retail subscription growth for automated replenishment. The Western Australian Department of Health applies FSANZ detectable gluten thresholds through imported product inspection regimes. Fremantle port infrastructure handles quinoa import volumes facing currency and shipping cost volatility.
Australia Gluten-Free Foods and Beverages Market Competitive Environment
New South Wales and Victoria producers anchor the premium-tier certification vector; Queensland and South Australia specialists hold emerging capacity expansion positions. Market structure tilts toward consolidated supermarket channel access controlled by nationwide distribution networks, with fragmentation persisting in online direct-to-consumer niches. Three archetypes dominate: legacy FMCG conglomerates leveraging existing biscuit and cereal infrastructure, pure-play free-from specialists commanding health-food-store placement, and import-dependent international brands filling pasta and specialty grain gaps. Dominant competitive moves center on Coeliac Australia certification acquisition for institutional catering contracts and backward integration into dedicated gluten-free milling capacity.
Within the legacy FMCG tier, Arnott's Group and The Sanitarium Health and Wellbeing Company exemplify nationwide distribution leverage. Arnott's Group occupies a position shaped by biscuit-format specialization and supermarket channel density. The Sanitarium Health and Wellbeing Company sits within health-focused branding archetypes resonating with wellness-oriented Australian consumers. Genius Foods Ltd represents pure-play free-from specialization, anchoring competitive positioning through bakery-format depth rather than portfolio breadth. These three patterns illustrate how certification access and channel control separate viable scale positions from marginal regional presence.
| Leading Market Players |
|---|
| Arnott's Group |
| Genius Foods Ltd |
| The Sanitarium Health and Wellbeing Company |
| Kellogg Company |
| Unilever |
| General Mills Inc. |
| Bob's Red Mill Natural Foods |
| Freedom Nutritional Products Limited |
| Dr. Schar AG |
| Others |
Value Chain & Pricing Dynamics
Sorghum and buckwheat input costs fluctuate with Australian drought cycles, cascading through three-tier pricing structures that separate Coeliac Australia-certified premium lines from standard supermarket tiers and economy private-label alternatives. Retailer markup compression in New South Wales and Victoria supermarket chains intensifies margin pressure on manufacturers lacking dedicated gluten-free milling infrastructure.
Pricing Analysis
Distributor margin layers in Australian gluten-free foods compress between specialty grain millers and supermarket chains, with Coles and Woolworths extracting listing fees that erode manufacturer profitability. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with Coeliac Australia-endorsed products commanding shelf-space premiums. Cost compression in mid-tier bread and snack categories intensifies because modified starch system investments raise formulation expenses without proportional price recovery. Remote Western Australian households exhibit highest price sensitivity due to freight surcharges, while Sydney wellness-oriented consumers show lowest sensitivity to certification-driven premiums.
Supply Chain Analysis
Dual-sourcing requirements from Queensland and South Australia specialty grain millers reduce single-facility dependency risks for eastern seaboard manufacturers. Geographic supply concentration centers on Australian domestic rice and corn production, with quinoa imports from South America and buckwheat from drought-exposed local growing regions. Raw material dependencies include modified starch systems, hydrocolloid binding agents, and segregated gluten-free processing infrastructure. Single-source vulnerability persists in pharmaceutical-grade food processing equipment for Melbourne-area conversion projects. Distribution runs through Parramatta and Western Sydney hubs for national dispatch to supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian gluten-free manufacturers can expand margins through backward integration into dedicated milling capacity, capturing premium-tier pricing power as FSANZ compliance thresholds tighten detectable gluten standards.
For Market Incumbents: Deploy Coeliac Australia certification extension as a defensive lever against emerging pure-play free-from specialists. Secure segregated gluten-free processing facilities in Victoria manufacturing clusters before Queensland capacity shortages force long-haul distribution penalties. Channel control through Arnott's Group-style nationwide biscuit distribution networks limits retail listing access for insurgent brands. For New Entrants and Emerging Players: Remote Western Australian households represent an underserved buyer archetype seeking subscription-based automated replenishment for specialty dietary products. Food service channel penetration in hospital and aged-care procurement contracts offers white-space volume pools with less entrenched incumbent presence. Direct-to-consumer platforms leveraging personalized nutrition profiling provide the most penetrable go-to-market angle against supermarket channel consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented online direct-to-consumer niches lack scale-efficient fulfillment infrastructure. Long-term viability in this market hinges on captive supply of segregated gluten-free milling capacity across eastern seaboard production hubs. Acquisition target archetypes include Queensland and South Australia specialty grain millers with dedicated facility investments. The signal to watch is FSANZ threshold revision timing that accelerates compliance-cost absorption disparities between integrated and non-integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dedicated Milling | Captures margin from Queensland and South Australia specialty grain infrastructure investments. |
| Coeliac Australia Certification Extension | Unlocks institutional catering contracts in hospital and aged-care procurement channels. |
| Subscription-Based Direct-to-Consumer Launch | Addresses Western Australian remote household demand with automated replenishment loyalty. |
| Modified Starch System R&D Investment | Closes sensory gaps with wheat-based formulations in bread and pasta texture benchmarks. |
| Food Service Channel Expansion | Penetrates untapped restaurant menu transparency demand in Sydney and Melbourne urban centers. |
Study Parameters
Direct dialogue with FSANZ regulatory affairs specialists, Coeliac Australia certification officers, supermarket category buyers at Coles and Woolworths, and specialty grain miller operations directors grounded qualitative findings in enforcement and procurement realities. Secondary validation drew from FSANZ Standard 1.2.8 documentation, ACCC compliance monitoring records, Australian Bureau of Agricultural and Resource Economics drought-impact assessments, and Nielsen retail audit data. Bottom-up volume modeling from individual SKU velocities and top-down market sizing from household penetration diagnostics were triangulated to constrain estimation variance.
Bottom-up demand modeling tracked certified product velocities across supermarket channels, online subscription platforms, and health food store independents, while top-down analysis calibrated against celiac disease diagnosis rates and gluten sensitivity prevalence surveys. Segmentation dimensions included product type, distribution channel, end user procurement specifications, and ingredient source sourcing strategies. CAGRs were derived from trend extrapolation of weekly grocery purchase expansion patterns and institutional catering contract growth trajectories. Forecast inputs incorporated FSANZ threshold revision schedules and Coeliac Australia certification expansion timelines.
Underlying measurement precision varies by segment; supermarket channel volume flows carry tighter precision than online direct-to-consumer niches due to Nielsen retail audit coverage gaps. Forecasts reflect assumptions regarding FSANZ enforcement intensity, drought cycle recurrence in sorghum and buckwheat growing regions, and Coeliac Australia certification program expansion pace. Deviation in FSANZ detectable gluten threshold timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Europe Gluten-Free Oats Market