
 Allergen Free Food Products Market | 2026-2036
Allergen Free Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Allergen Free Food Products Market Analysis
The EU Green Deal is rebalancing ingredient sourcing priorities across European food manufacturing. Nestlé leverages its R&D network to reformulate legacy brands with allergen-free credentials. Dr. Schär specializes in certified gluten-free bakery products and dominates Central European retail placement. The Hain Celestial Group anchors its portfolio in organic and free-from positioning across North American natural channels.
Allergen free food products are formulated to exclude specific proteins—gluten, dairy, nuts, eggs, or soy—using alternative flours, plant-based milks, and controlled manufacturing environments with dedicated production lines and validated cleaning protocols to prevent cross-contact. Their primary purpose is to provide safe nutrition for individuals with IgE-mediated allergies, celiac disease, or non-allergic food hypersensitivities while expanding choice for health-motivated purchasers. Gluten-free formulations retain the largest revenue share within the product type dimension, though dairy-free alternatives are accelerating fastest as oat and pea protein technologies mature. Online retail captures the fastest growth among distribution channels, while supermarkets still hold the deepest margin pools through private-label expansion and slotting fee structures.
The FDA enforces Food Allergen Labeling and Consumer Protection Act requirements for major allergen disclosure, while the EMA coordinates with EFSA on novel protein safety assessments for ingredient substitutions. Health Canada maintains strict precautionary allergen labeling guidelines that influence exporter compliance burdens. Stakeholders must monitor evolving threshold science for allergen action levels, as regulatory bodies weigh quantitative risk assessment against current precautionary labeling practices.
Market Dynamics
The EU's FIC Regulation is tightening cross-border labeling enforcement, forcing manufacturers to revalidate supply chains and reformulate legacy products to maintain market access across member states.
Growth Catalysts
- Pediatric nutrition procurement:Institutional cafeterias in Germany and France are expanding allergen-free SKU procurement for school feeding programs, creating contracted demand pools.
- EMA-EFSA coordination:Streamlined novel protein safety assessments for oat and pea protein substitutions are compressing ingredient approval timelines.
- Retail shelf expansion:German retail chains are dedicating expanding linear footage to certified allergen-free products, normalizing premium positioning.
Market Restraints
- Input cost volatility:Oat protein isolate and tapioca flour prices fluctuate with Nordic and Southeast Asian harvest cycles, squeezing margin predictability.
- Supply concentration risk:Dedicated allergen-free production lines cluster in Central European contract manufacturing facilities, creating single-source vulnerability.
- Regulatory friction:Health Canada's precautionary allergen labeling guidelines impose exporter compliance burdens that delay North American market entry.
Strategic Opportunities
- E-commerce channel innovation:Direct-to-consumer subscription models for allergen-free pantry staples are capturing repeat purchase loyalty in urban UK households.
- EU Green Deal tailwind:Sustainable ingredient sourcing mandates favor domestic European pulse protein cultivation over imported soy.
- Convergence of proteomics and AI:In-silico allergenicity prediction tools are accelerating safe novel protein identification for bakery applications.
Industry Challenges
- Validated cleaning protocols:Preventing cross-contact on shared equipment demands documented ATP testing and allergen-specific ELISA verification that extends changeover downtime.
- Certification timeline compression:Third-party gluten-free and allergen-free audits face backlogs at accredited bodies, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergen Free Food Products Market |
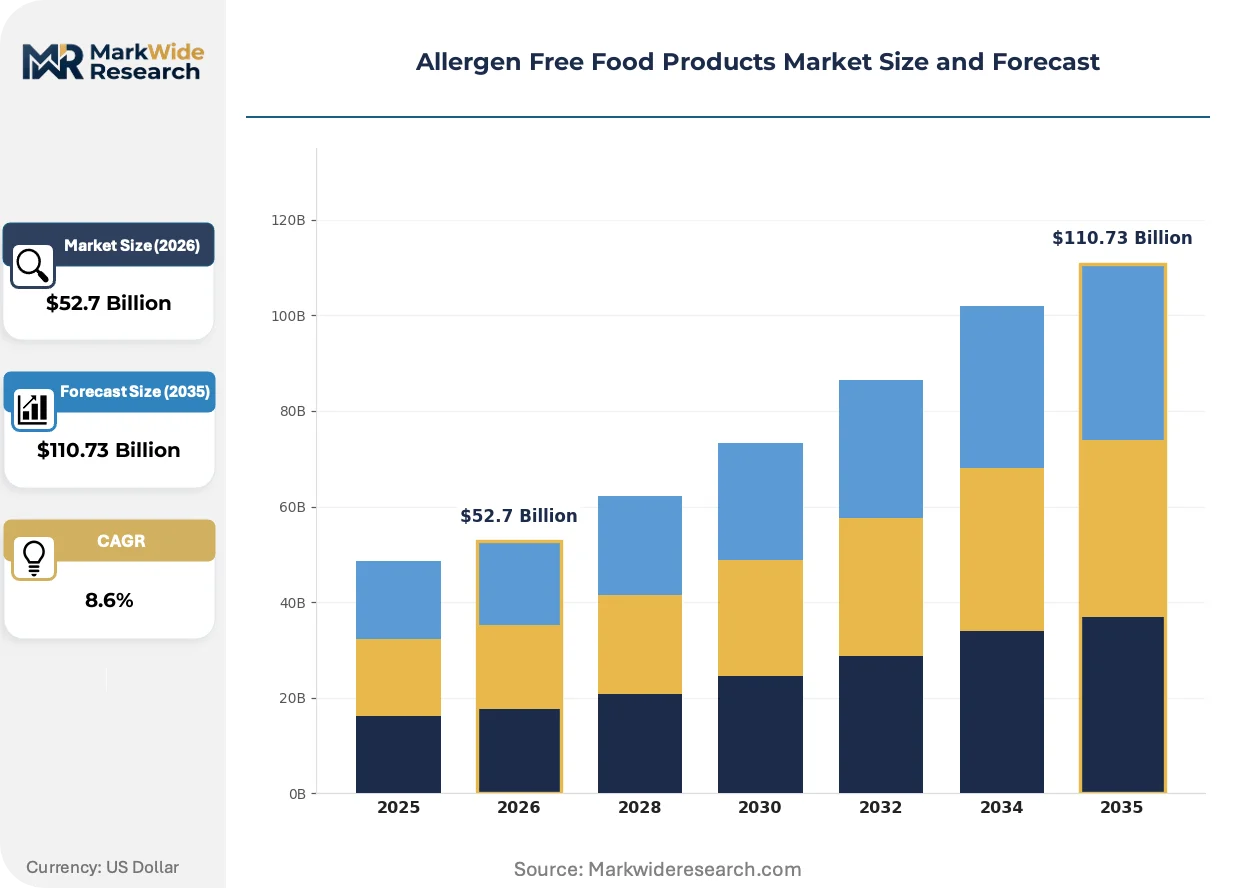
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Egg-Free Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Customer Type: Individuals with Allergies, Health-Conscious Consumers, Parents, Dietary Restriction Adherents Packaging Type: Single-Serve, Bulk Packaging, Resealable Bags, Eco-Friendly Packaging |
| Companies Covered | Nestlé, Danone, General Mills, Kraft Heinz Company, Abbott Laboratories, Kellogg Co, Dr. Schär, The Hain Celestial Group, Boulder Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergen Free Food Products Market Emerging Trajectories
Reformulation science is advancing alongside digital traceability tools, creating new competitive axes beyond ingredient exclusion toward verified supply chain transparency and personalized nutrition matching.
Precision fermentation for dairy protein analogs is electrifying product development pipelines in the allergen-free sector. Specialty food manufacturers in Denmark and the Netherlands are integrating these ingredients at pilot scale. The technology is electrifying R&D resource allocation, compressing timelines for clean-label dairy alternatives that bypass traditional allergen risk entirely.
REACH regulatory expansion into food contact materials is reshaping packaging selection for allergen-free products. Manufacturers must now validate that barrier films and coatings do not introduce novel protein contaminants. The bakery segment is responding fastest, with German and Austrian producers switching to cellulose-based alternatives ahead of enforcement deadlines.
Subscription-based pantry replenishment is fragmenting traditional supermarket dominance for allergen-free staples. Urban households with diagnosed celiac disease or pediatric allergies are bypassing retail discovery friction through curated monthly boxes. This pattern is most visible in London, Amsterdam, and Stockholm, where direct-to-consumer brands capture recurring revenue through diagnostic-test partnerships.
Allergen Free Food Products Market Segmentation
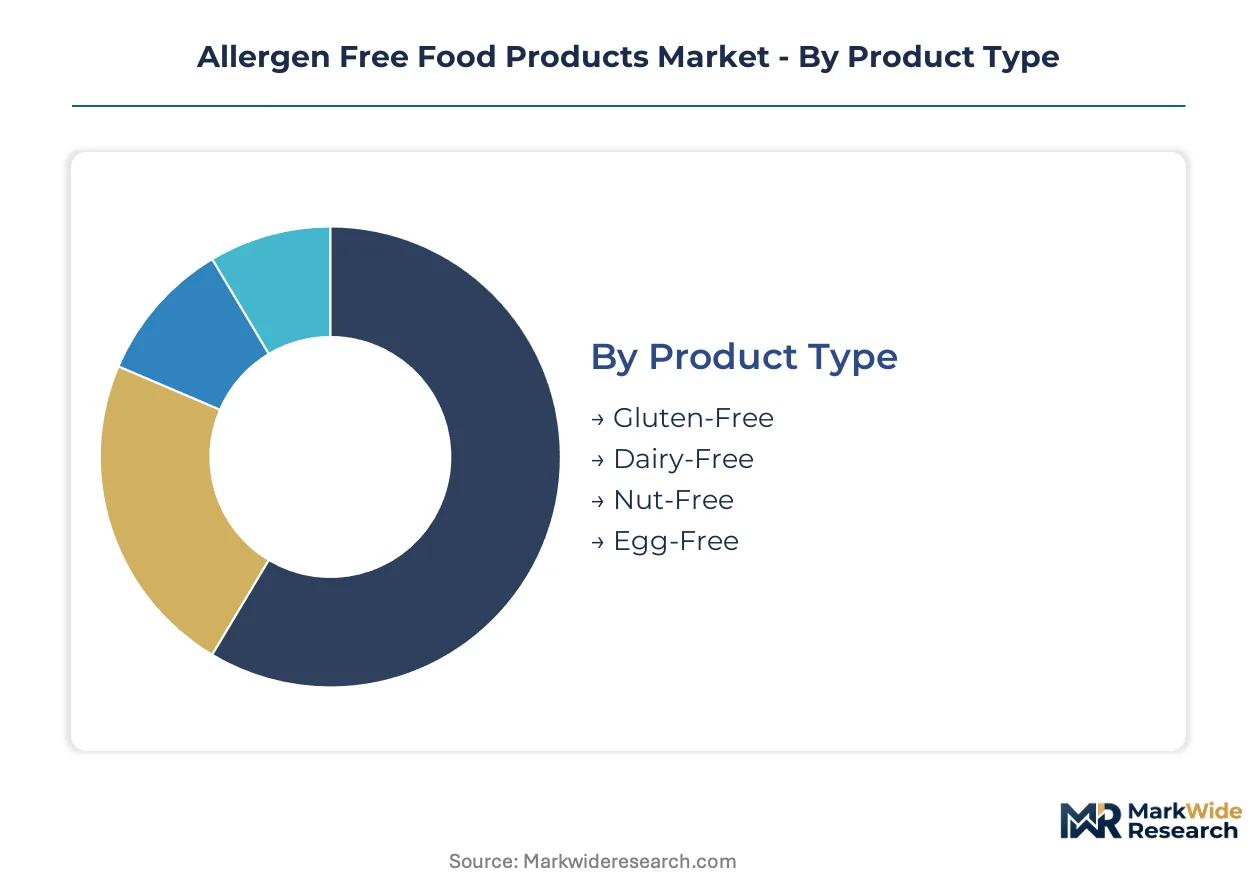
Allergen-free food products serve distinct consumption occasions and purchasing behaviors that demand targeted formulation, channel placement, and messaging strategies. Segmentation reveals where premium pricing power concentrates versus where volume scale accumulates.
Product Type:
Standalone allergen-free products dominate retail shelf space, while embedded allergen-free ingredients penetrate conventional formulations through reformulation partnerships.
- Gluten-Free:Formulations replace wheat with rice flour, tapioca starch, or certified oat derivatives in bakery and pasta applications. German retail chains dedicate expanding linear footage to certified gluten-free SKUs, normalizing premium positioning through third-party audit verification.
- Dairy-Free:Plant-based milks and fermented alternatives leverage oat and pea protein technologies that bypass traditional allergen risk entirely. Danish and Dutch manufacturers are integrating precision fermentation ingredients at pilot scale, compressing development timelines for clean-label positioning.
- Nut-Free:Controlled manufacturing environments with validated cleaning protocols prevent cross-contact in shared bakery facilities. Seed-based alternatives (sunflower, pumpkin) substitute for texture and protein content in snack bars and spreads.
- Egg-Free:Aquafaba, flax gel, and commercial egg replacers provide binding and leavening in bakery and confectionery segments. Industrial foodservice accounts in institutional cafeterias drive contracted procurement volumes.
Gluten-free leads volumes today; dairy-free is gaining share fastest.
Distribution Channel:
Channel selection determines margin capture, with direct relationships yielding recurring revenue pools and intermediaries demanding slotting fee concessions.
- Online Retail:Direct-to-consumer subscription models for pantry staples capture repeat purchase loyalty in urban UK households. Diagnostic-test partnerships enable curated monthly boxes that bypass retail discovery friction.
- Supermarkets:Private-label expansion and slotting fee structures concentrate margin pools, though shelf space competition intensifies. German chains are expanding dedicated allergen-free sections.
- Health Food Stores:Staff expertise and certified product curation support premium pricing for novel protein introductions. These channels anchor brand credibility before mainstream retail expansion.
- Specialty Shops:Celiac-focused bakeries and allergen-free boutiques provide immediate consumption validation and community trust transfer. Limited footprint constrains volume scale.
Supermarkets anchor current revenue; online retail climbs the fastest.
Customer Type:
Medical necessity versus lifestyle motivation splits pricing tolerance and purchase frequency patterns across buyer segments.
- Individuals with Allergies:IgE-mediated allergy and celiac disease diagnoses create non-discretionary demand with zero substitution tolerance. EMA-EFSA coordination on novel protein safety assessments accelerates ingredient approval timelines for this cohort.
- Health-Conscious Consumers:Free-from positioning appeals to perceived wellness benefits beyond clinical necessity. This segment exhibits higher price elasticity and brand switching behavior.
- Parents:Pediatric nutrition programs in institutional cafeterias in France and Germany expand contracted demand pools for school feeding programs. Safety verification outweighs cost considerations in purchase decisions.
- Dietary Restriction Adherents:Vegan, paleo, and elimination diet followers adopt allergen-free products as compatible inputs. Cross-category purchasing expands basket size for compatible brands.
Individuals with allergies dominate current spend; parents represent the steepest expansion trajectory.
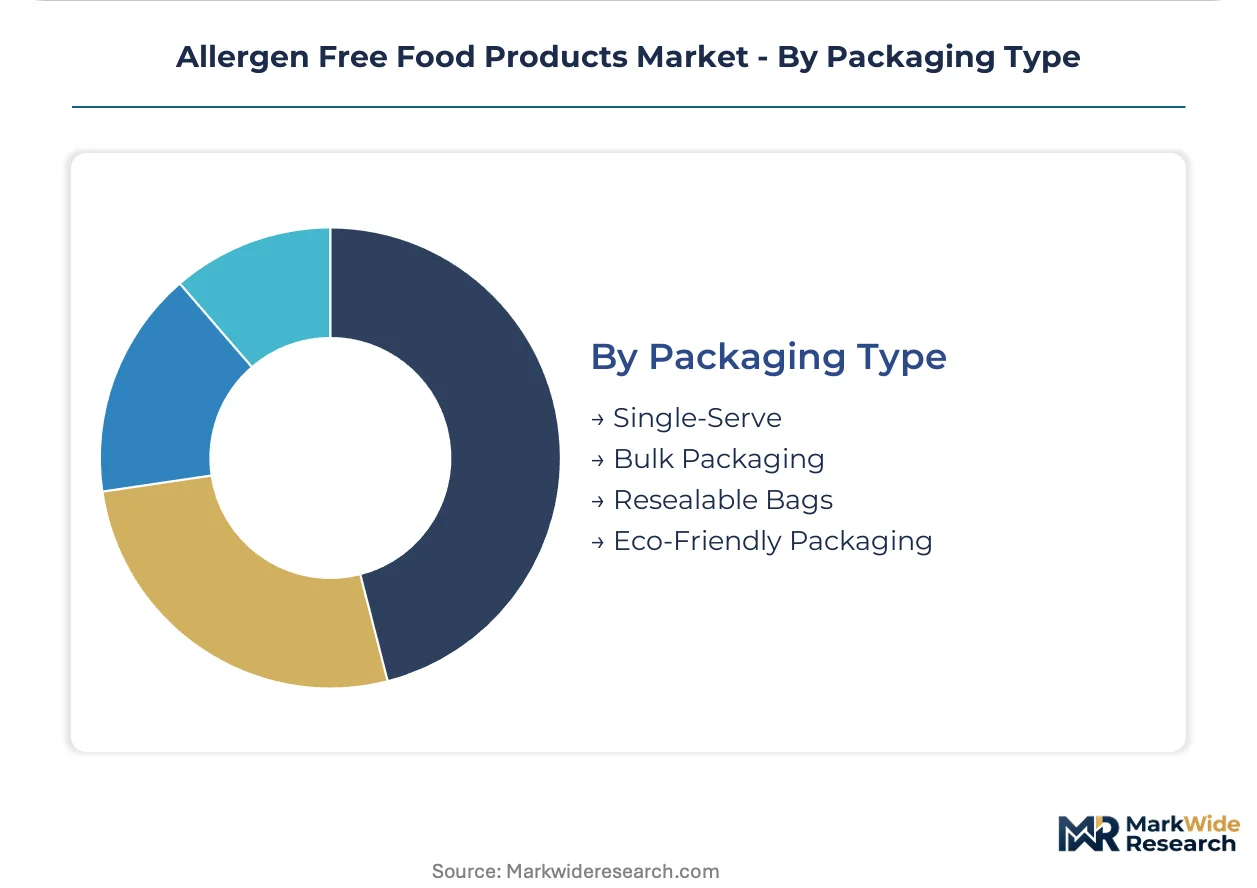
Packaging Type:
Packaging functionality intersects with regulatory compliance as REACH expansion into food contact materials reshapes barrier film selection.
- Single-Serve:Portion-controlled formats support on-the-go consumption and trial conversion in convenience channels. Higher unit costs limit household pantry penetration.
- Bulk Packaging:Foodservice and institutional procurement favor cost-efficient formats for cafeteria and bakery operations. German and Austrian producers are switching to cellulose-based alternatives ahead of enforcement deadlines.
- Resealable Bags:Extended freshness protection reduces waste in multi-use pantry staples. Zip-lock mechanisms add material cost that challenges economy-tier positioning.
- Eco-Friendly Packaging:EU Green Deal sustainable sourcing mandates favor domestic European materials over imported alternatives. Validation that barrier films do not introduce novel protein contaminants adds compliance burden.
Bulk packaging leads foodservice volumes; eco-friendly formats are expanding most quickly in retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food technologists and certified allergen management professionals concentrate in Germany, Switzerland, and the Netherlands, anchoring European formulation expertise for this sector.
Germany
Pediatric nutrition procurement in institutional cafeterias and expanding retail shelf space for certified SKUs drive demand. The country's national food regulator enforces strict cross-border labeling under EU FIC Regulation mandates. Berlin and Munich host dedicated allergen-free production facilities with validated cleaning protocols.
United States
Direct-to-consumer subscription models and diagnostic-test partnerships capture recurring revenue in urban households. The FDA enforces Food Allergen Labeling and Consumer Protection Act requirements for major allergen disclosure. Greater Boston and the Pacific Northwest cluster precision fermentation startups for dairy protein analogs.
France
School feeding program contracts and health-conscious consumer adoption expand volume scale. ANSM coordinates with EFSA on novel protein safety assessments for ingredient substitutions. The Île-de-France region anchors reformulation R&D for legacy brand portfolios.
United Kingdom
Urban household subscription penetration and curated monthly box services bypass retail friction. The country's food standards agency aligns with EU precautionary labeling guidelines post-Brexit. London concentrates e-commerce platform development for allergen-free pantry staples.
Canada
Exporter compliance burdens delay market entry while domestic health-conscious adoption rises. Health Canada maintains strict precautionary allergen labeling guidelines influencing formulation decisions. Toronto and Vancouver host contract manufacturing facilities serving North American distribution.
Allergen Free Food Products Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the allergen-free food products sector. The market structure shows moderate consolidation with multinational food conglomerates occupying premium shelf positions alongside specialized regional bakeries. Three strategic archetypes dominate: diversified nutrition conglomerates with reformulated legacy portfolios, certified gluten-free specialists with dedicated production assets, and organic free-from purists anchored in natural channels. Competitive moves concentrate on portfolio diversification through novel protein integration and strategic partnerships with diagnostic service providers.
Among diversified nutrition conglomerates, Nestlé and Danone occupy positions exemplifying scale-driven reformulation capabilities. Dr. Schär represents the certified specialist archetype with concentrated Central European retail placement. The Hain Celestial Group anchors the organic free-from positioning vector across North American natural channels.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| General Mills |
| Kraft Heinz Company |
| Abbott Laboratories |
| Kellogg Co |
| Dr. Schär |
| The Hain Celestial Group |
| Boulder Brands |
| Others |
Supply Flow & Price Mechanics
Specialized food technologists and certified allergen management professionals concentrated in Germany, Switzerland, and the Netherlands create labor-cost differentials that widen pricing-tier spreads between premium certified products and economy-tier alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the allergen-free food products sector, with differentiation driven by third-party certification grade and dedicated production line validation. Premium tiers command substantial markups for gluten-free and allergen-free audits from accredited bodies, while economy positioning relies on shared equipment with documented cleaning protocols. Cost compression in the standard tier is intensifying because oat protein isolate and tapioca flour prices fluctuate with Nordic and Southeast Asian harvest cycles. Health-conscious consumers exhibit the highest price elasticity and brand switching behavior, whereas parents of children with diagnosed allergies demonstrate the least price sensitivity.
Supply Chain Analysis
Direct-to-consumer subscription channels handle recurring household demand in urban UK and German markets, while supermarkets and institutional cafeterias manage bulk procurement through contracted offtake agreements. Geographic supply concentration centers on Germany, Austria, and the Netherlands for dedicated allergen-free production facilities with validated cleaning protocols. Raw material dependencies draw from Nordic oat cultivation, Southeast Asian tapioca flour processing, and domestic European pulse protein cultivation favored by EU Green Deal mandates. Single-source vulnerability constitutes the primary structural risk, as dedicated production lines cluster in Central European contract manufacturing facilities. Distribution runs through retail chains expanding dedicated shelf space, health food stores anchoring brand credibility, and e-commerce platforms capturing subscription loyalty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU FIC Regulation's tightening cross-border labeling enforcement compounds demand for validated supply chains and certified formulations, creating sustained procurement pressure across institutional and retail channels.
For Market Incumbents: To counter input cost volatility in oat protein isolate and tapioca flour, Nestlé and Danone should deepen backward integration into domestic European pulse protein cultivation while expanding dedicated production capacity in Germany and Austria. Certification investment at accredited audit bodies accelerates product launch timelines and defends shelf position against private-label expansion. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models targeting urban UK households with diagnostic-test partnerships, bypassing retail slotting fee barriers. The pediatric nutrition procurement channel in German and French institutional cafeterias offers the most penetrable white-space, with contracted demand pools and safety-verification premiums that outweigh cost competition. For Investors and Strategic Acquirers: Diversified nutrition conglomerates with reformulated legacy portfolios represent the most active acquirer category in this space, consolidating certified gluten-free specialists to capture Central European retail placement. Acquisition targets should display dedicated production assets with validated cleaning protocols and third-party audit relationships. Watch for threshold science developments in allergen action levels as the inflection signal for regulatory shift toward quantitative risk assessment.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Integration | Danish and Dutch manufacturers compress development timelines for clean-label dairy alternatives using EMA-EFSA coordinated safety assessments. |
| Diagnostic-Test Partnerships | Direct-to-consumer brands in London and Amsterdam capture recurring revenue through curated monthly boxes matched to patient profiles. |
| EU Green Deal Sourcing Transition | Domestic European pulse protein cultivation displaces imported soy under sustainable sourcing mandates. |
| Third-Party Certification Investment | Dr. Schär maintains Central European retail dominance through gluten-free audit verification ahead of competitor backlogs. |
| E-Commerce Platform Development | Urban subscription penetration fragments traditional supermarket dominance for allergen-free pantry staples. |
Methodological Framework
Coverage spans Germany, France, the United Kingdom, the United States, and Canada, with primary inputs from each market combining structured interviews with food technologists, regulatory affairs specialists, retail category buyers, and institutional procurement managers with secondary validation. Secondary sources include EU FIC Regulation enforcement records, FDA Food Allergen Labeling and Consumer Protection Act guidance documents, EMA-EFSA coordination protocols, Health Canada precautionary labeling guidelines, and retail audit data from Nielsen and Circana. Bottom-up demand modeling triangulates against top-down market sizing across product type, distribution channel, and customer type dimensions.
Granularity-level modeling extends to gluten-free, dairy-free, nut-free, and egg-free product categories; online retail, supermarkets, health food stores, and specialty shops; and individuals with allergies, health-conscious consumers, parents, and dietary restriction adherents. CAGRs derive from segment-level growth trajectories anchored in pediatric nutrition procurement expansion, retail shelf space allocation trends, and subscription model penetration rates. Forecast inputs incorporate EMA-EFSA novel protein safety assessment timelines, REACH regulatory expansion into food contact materials, and precision fermentation scale-up curves.
Inputs from regulatory filing databases and retail audit panels were available through the study window; gaps in real-time oat protein isolate and tapioca flour price series introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding EU FIC Regulation enforcement consistency, threshold science advancement timelines, and dedicated production facility expansion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Dyspepsia Market