
 Lacrimal Duct Stent Tube Market | 2026-2036
Lacrimal Duct Stent Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Lacrimal Duct Stent Tube Market Analysis
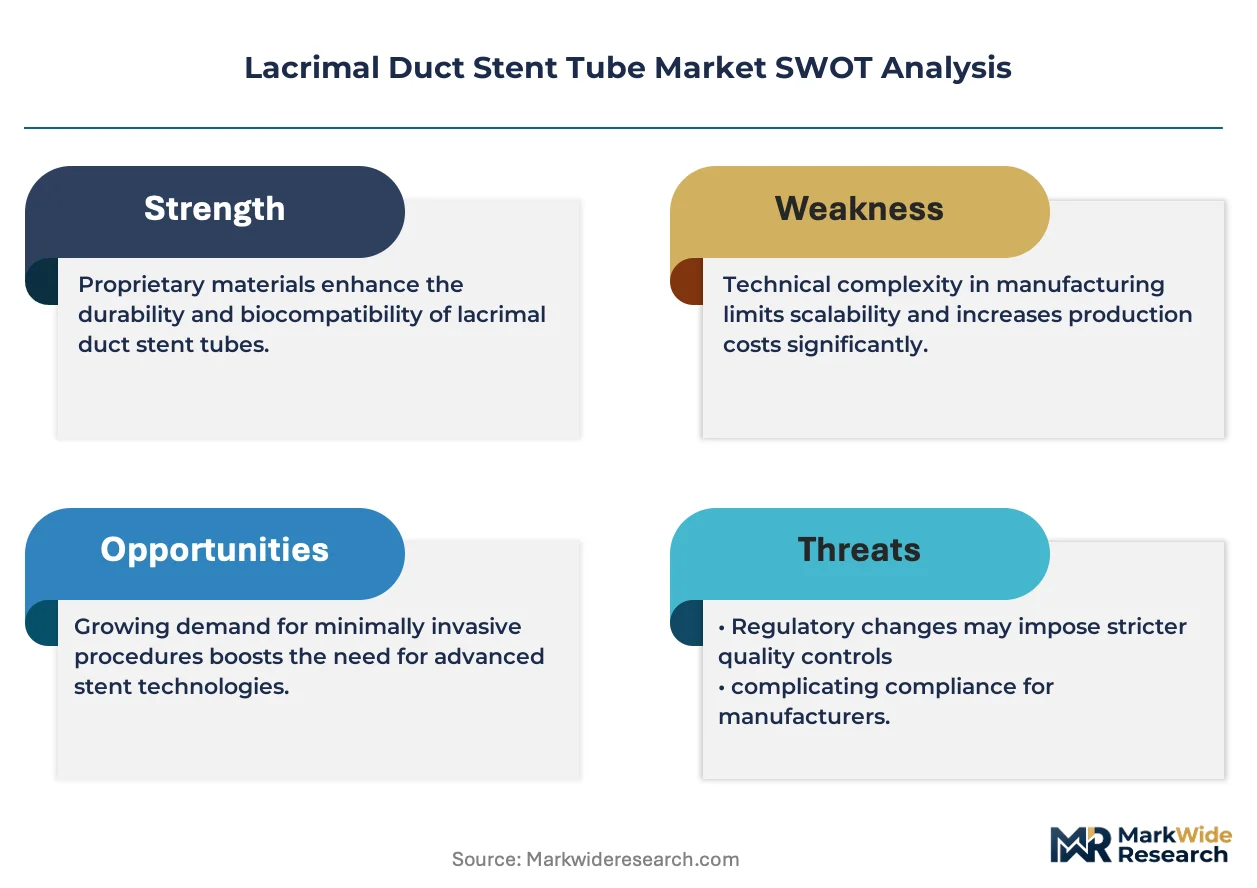
Biocompatibility-grade silicone specifications are redrawing procurement criteria for lacrimal duct stent tubes. Medtronic leverages its vertical integration in polymer sourcing to sustain cost advantages across hospital networks. ZEISS (FCI Ophthalmics) anchors its position through specialized distribution in European ophthalmology clinics. Kaneka Pharma America LLC competes on Japanese manufacturing standards that dominate premium-tier contract negotiations.
A lacrimal duct stent tube is a tubular implant, typically extruded from medical-grade silicone or thermoplastic polymers with outer diameters ranging from 0.64 mm to 1.14 mm, designed to maintain patency within the nasolacrimal drainage system following probing or dacryocystorhinostomy. Silicone stent variants dominate current volume due to established flexibility and tissue tolerance, while retrievable stent designs capture accelerated interest as clinicians prioritize reduced follow-up intervention. Chronic dacryocystitis applications generate stable hospital demand, though epiphora management in ambulatory settings represents the fastest-growing procedure category.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern commercial entry, with both frameworks elevating biocompatibility testing burdens for new polymer formulations. Japan's PMDA enforces JIS-standard compliance that filters out non-specialized suppliers. Stakeholders must monitor evolving MDR clinical evidence requirements and PMDA QMS inspections to anticipate which manufacturing configurations will retain market access.
Market Dynamics
Retrievable stent designs are compressing the traditional silicone monostent paradigm as ambulatory surgical centers demand reduced follow-up intervention burdens and streamlined procedural workflows.
Growth Catalysts
- EU MDR clinical evidence requirements:Elevated biocompatibility testing standards are filtering out marginal suppliers and consolidating procurement among certified manufacturers serving European ophthalmology clinics.
- Japan's aging demographic profile:Epiphora intervention volumes in Tokyo and Osaka medical districts are expanding addressable procedure counts for premium-tier stent suppliers.
- Thermoplastic polymer extrusion:Next-generation materials with enhanced tensile memory are opening design space for self-retaining stent architectures that reduce suture dependency.
Market Restraints
- Medical-grade silicone feedstock volatility:Petrochemical-derived silicone precursor costs fluctuate with energy markets, squeezing margin structures for non-vertically integrated extrusion houses.
- PMDA QMS inspection density:Japan's pharmaceutical and medical device agency enforces rigorous facility audits that extend commercialization timelines for foreign entrants lacking local manufacturing presence.
- Laser dacryocystorhinosty substitution:Endonasal laser techniques achieving comparable patency rates without permanent implantation threaten stent volume in select tertiary hospital settings.
Strategic Opportunities
- Indian ambulatory surgery center expansion:Underpenetrated tier-2 cities in Maharashtra and Tamil Nadu present first-mover positioning for distributors establishing catheterization-trained ophthalmology networks.
- FDA 510(k) abbreviated pathway:Predicate device referencing for incremental design modifications accelerates clearance timelines relative to de novo submissions, rewarding iterative innovation cycles.
- Telemedicine-integrated follow-up protocols:Remote patency assessment via high-resolution endoscopic imaging is enabling geographic extension of stent monitoring beyond traditional urban hospital catchments.
Industry Challenges
- Micro-extrusion technician scarcity:Precision polymer processing expertise concentrates in legacy medical device manufacturing clusters, constraining capacity expansion for emerging market entrants.
- ISO 10993 biocompatibility testing backlogs:Contract laboratory queue delays for cytotoxicity and sensitization studies extend product development cycles unpredictably.
- Legacy hospital inventory system integration:Ambulatory surgical center procurement platforms require EDI-compatible catalog management that smaller stent manufacturers lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lacrimal Duct Stent Tube Market |
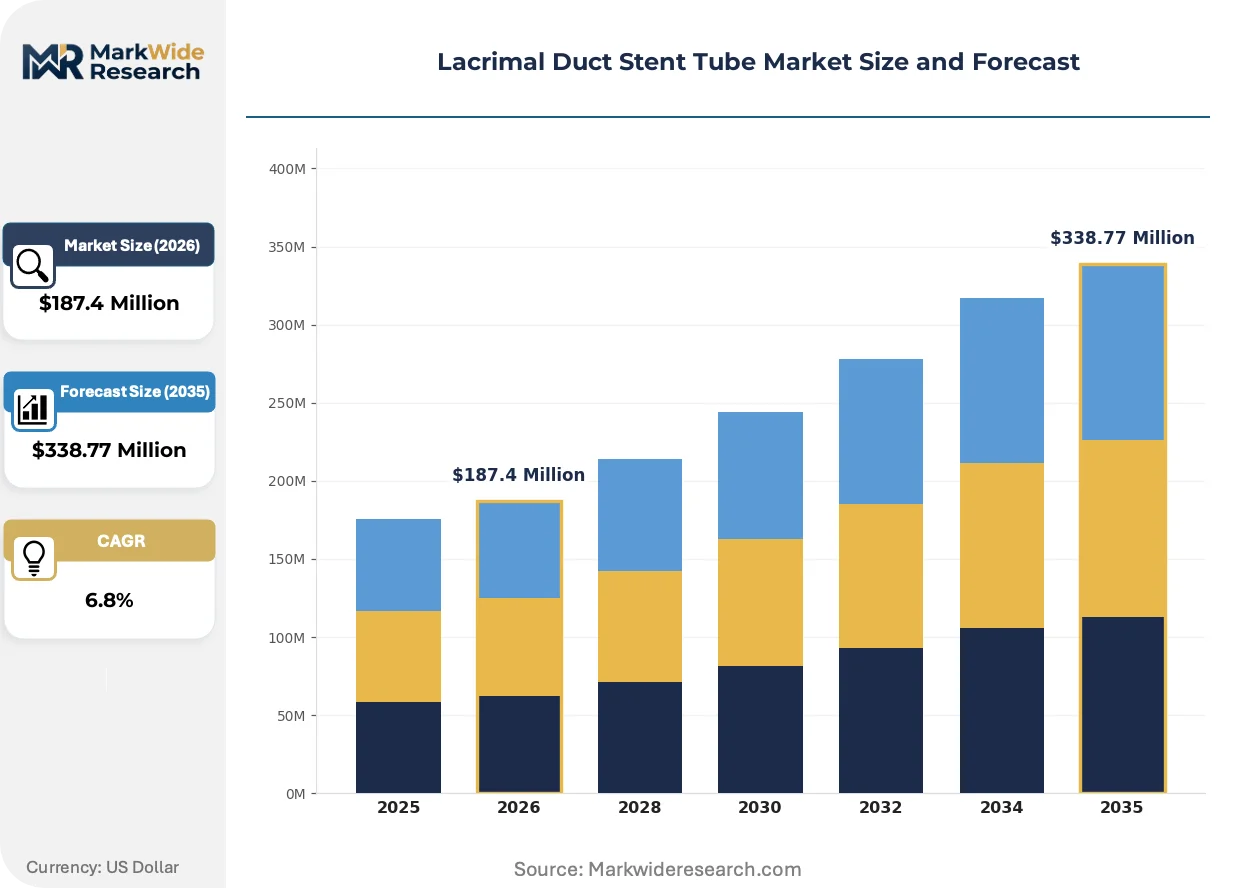
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Stent, Malleable Stent, Rigid Stent, Retrievable Stent Application: Chronic Dacryocystitis, Epiphora, Lacrimal Drainage, Others End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Research Laboratories Material: Polyethylene, Silicone, Stainless Steel, Others |
| Companies Covered | Medtronic, Becton Dickinson and Company, ZEISS (FCI Ophthalmics), Aurolab, Kaneka Pharma America LLC, Bess Medizintechnik GmbH, Gunther Weiss Scientific Glassblowing Co., Beaver-Visitec International, Inc, Agfa Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lacrimal Duct Stent Tube Market Emerging Trajectories
Material science advances and regulatory framework evolution are simultaneously expanding design possibilities and compressing commercialization pathways for lacrimal drainage implants.
Bioresorbable polymer formulations are bifurcating the stent landscape between permanent silicone implants and transient scaffolds that eliminate retrieval procedures. Academic medical centers in Germany and the United States are piloting polycaprolactone-based architectures with 90-day resorption profiles. This technology is bifurcating patient selection criteria and creating parallel reimbursement coding requirements.
CE marking under the EU MDR now mandates clinical performance data for Class IIa implantable devices, replacing the previous equivalence-based clearance model. German notified bodies are applying heightened scrutiny to silicone leachate profiles. European ophthalmology clinics are consolidating supplier relationships to reduce audit exposure, favoring manufacturers with established technical documentation libraries.
Hospital procurement departments are unbundling stent supply from procedural service contracts, shifting toward direct manufacturer purchasing through GPO-negotiated tiers. This disintermediation pressures traditional distributor margins while rewarding suppliers with sterile packaging capabilities and lot-level traceability systems. The United States exhibits the most pronounced contract restructuring as IDN consolidation accelerates.
Lacrimal Duct Stent Tube Market Segmentation
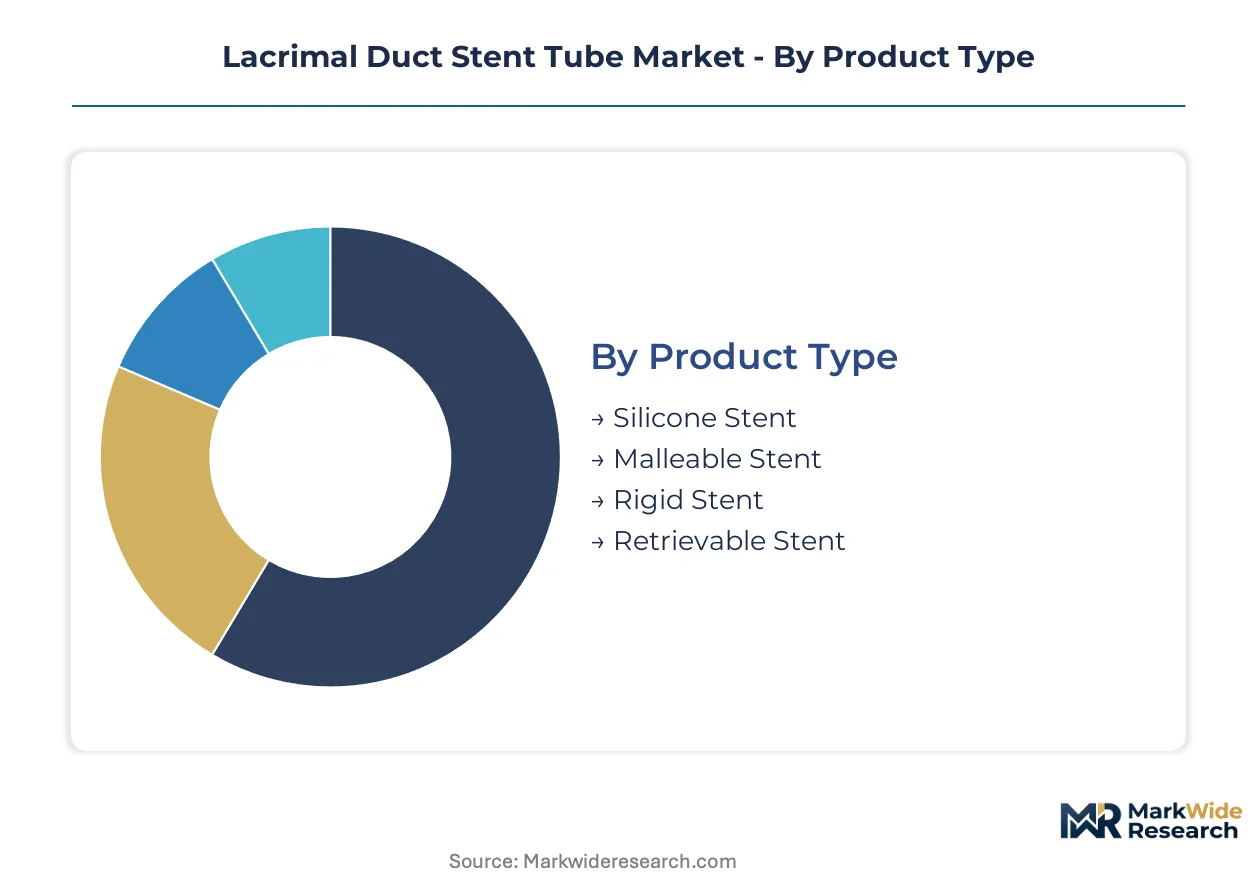
Lacrimal duct stent tube procurement varies sharply across clinical settings, with material specifications and retrieval protocols driving reimbursement coding. Manufacturers configure product portfolios around regulatory clearance pathways and procedural venue requirements rather than undifferentiated volume distribution.
Product Type:
FDA 510(k) clearance timelines diverge substantially between permanent implant and retrievable device categories, reshaping manufacturer R&D allocation.
- Silicone Stent:Extruded from medical-grade polydimethylsiloxane with Shore A durometer specifications between 40 and 60, these tubes dominate hospital procurement tenders in Germany and the United States. Chronic dacryocystitis cases in tertiary ophthalmology departments sustain stable reorder volumes despite longer procedure times.
- Retrievable Stent:Incorporating suture retrieval loops or magnetic extraction features, these designs reduce mandatory follow-up visits. Ambulatory surgical centers in Tokyo and Dallas medical districts are expanding adoption fastest as outpatient efficiency metrics tighten.
- Malleable Stent:Nitinol-core variants permit intraoperative curvature adjustment without kinking.
- Rigid Stent:Polypropylene constructs serve pediatric probing procedures requiring dimensional stability.
Established volume favors silicone stent; emerging adoption favors retrievable stent.
Application:
Procedure reimbursement rates determine stent selection economics across intervention categories.
- Epiphora:Excessive tearing interventions in aging populations drive silicone stent placement in Japanese and German outpatient settings. Medicare Advantage plans and German statutory health insurance apply distinct prior authorization thresholds that segment pricing tiers.
- Chronic Dacryocystitis:Recurrent infection management requires longer indwelling periods and biocompatibility-grade silicone with documented leachate profiles. Hospital infection control committees in the United States mandate lot-level traceability for these implants.
- Lacrimal Drainage:Post-surgical patency maintenance following dacryocystorhinostomy.
- Others:Traumatic canalicular repair and congenital anomaly correction.
Hospital procurement concentrates on chronic dacryocystitis; ambulatory expansion is climbing the fastest.
End User:
Capital equipment integration requirements separate institutional tiers in supply chain access.
- Ambulatory Surgical Centers:Streamlined inventory systems and GPO-negotiated tiers favor manufacturers with EDI-compatible catalog management. Texas and Florida ASC networks are consolidating ophthalmology service lines around single-source stent contracts.
- Hospitals:Academic medical centers in Massachusetts and Bavaria maintain diversified supplier rosters to satisfy institutional review board documentation requirements for research cohorts.
- Ophthalmology Clinics:Private practice settings with in-office procedural capability.
- Research Laboratories:Preclinical and biocompatibility study procurement.
Contract concentration favors ambulatory surgical centers; research volume remains fragmented.
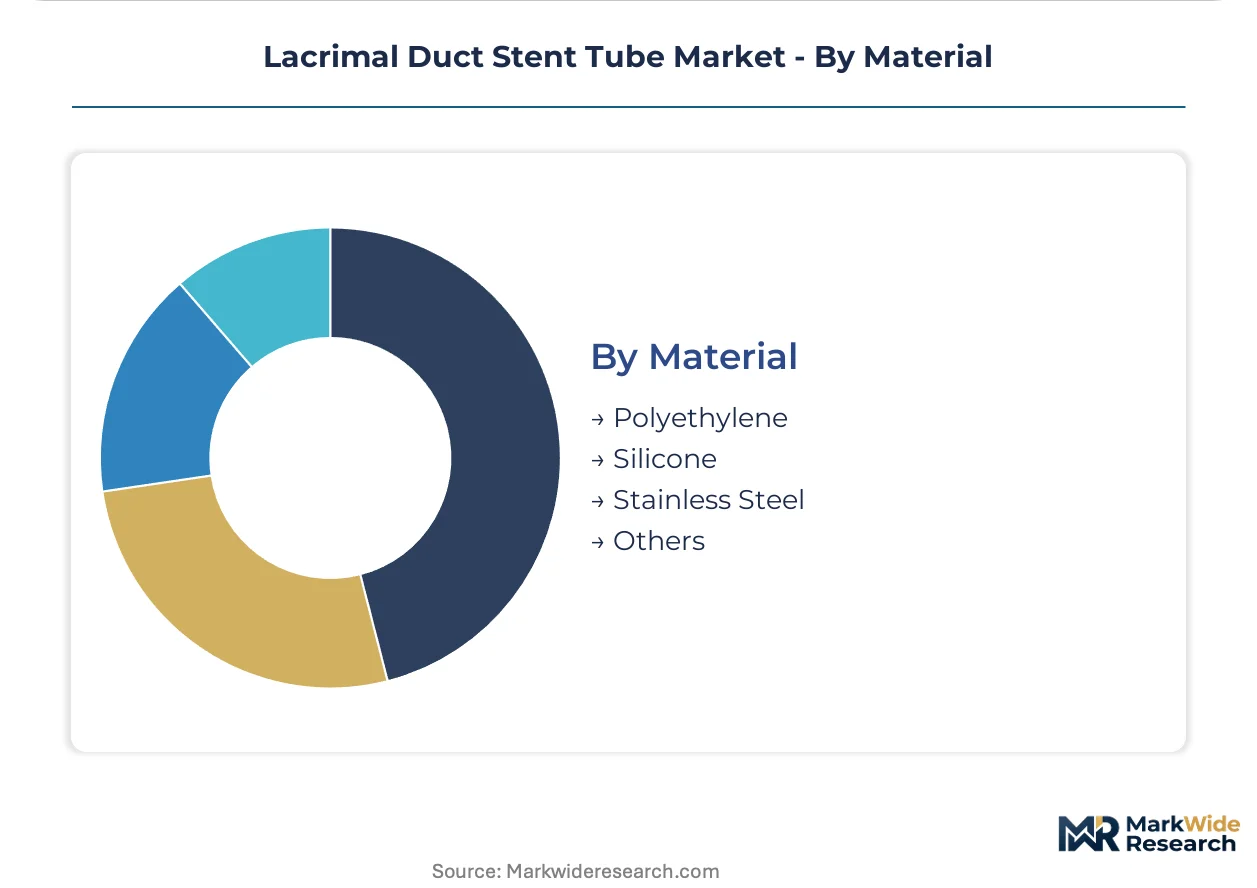
Material:
Polymer feedstock sourcing strategies determine margin resilience against petrochemical volatility.
- Silicone:Platinum-cured elastomer with ISO 10993-5 cytotoxicity clearance dominates premium-tier contract negotiations. Medtronic's captive polymer sourcing insulates against precursor cost swings that squeeze non-vertically integrated competitors.
- Polyethylene:High-density variants offer cost positioning for high-volume tenders in Indian and Brazilian public hospital systems where procurement budgets constrain silicone adoption.
- Stainless Steel:Reserved for specialized traumatic repair applications requiring radiopacity.
- Others:Polycaprolactone bioresorbable formulations in German and US academic pilot programs.
Silicone commands procurement preference; polyethylene is gaining share fastest in cost-constrained tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a modest export surplus in medical-grade silicone extrusions while importing finished stent assemblies from German and Japanese precision manufacturers. Germany and Japan dominate high-value contract manufacturing, whereas India and Brazil concentrate on cost-optimized polyethylene variants for public procurement tenders.
United States
Medicare Advantage prior authorization thresholds for epiphora interventions are expanding ambulatory surgical center volumes in Texas and Florida. FDA 510(k) clearance pathways reward predicate device referencing for iterative stent designs. Dallas-Fort Worth ASC networks are consolidating ophthalmology service lines around single-source contracts with EDI-compatible suppliers.
Germany
Statutory health insurance reimbursement rates for dacryocystorhinostomy procedures sustain hospital demand for biocompatibility-grade silicone stents. CE marking under EU MDR mandates clinical performance data for Class IIa implantable devices, elevating documentation burdens. Bavarian academic medical centers in Munich and Erlangen are piloting polycaprolactone bioresorbable formulations with 90-day resorption profiles.
Japan
Tokyo and Osaka medical districts are experiencing expanded epiphora intervention volumes driven by accelerating demographic aging. PMDA enforces JIS-standard compliance and rigorous QMS facility audits that filter out non-specialized foreign suppliers. Kanto region ophthalmology clinics prioritize premium-tier stent procurement from domestic manufacturing standards-compliant suppliers.
India
Tier-2 cities in Maharashtra and Tamil Nadu present underpenetrated positioning for distributors establishing catheterization-trained ophthalmology networks. CDSCO import licensing requirements for implantable silicone devices constrain rapid market entry for non-local manufacturers. Mumbai-Pune corridor ASC expansion is absorbing cost-optimized polyethylene stent variants for high-volume public hospital tenders.
Brazil
Public procurement budgets in São Paulo and Minas Gerais state hospital systems constrain silicone adoption in favor of high-density polyethylene alternatives. ANVISA medical device registration timelines extend commercialization schedules for foreign entrants lacking local regulatory representation. Southeastern Brazil ophthalmology service networks are consolidating around distributors with sterile packaging and lot-level traceability capabilities.
Lacrimal Duct Stent Tube Market Vendor Landscape
Listed leaders compete with private specialists across polymer sourcing and regulatory documentation capabilities. The vendor base spans vertically integrated polymer extruders, specialized ophthalmology distributors, and regional fabrication houses serving cost-constrained tenders. Three archetypes dominate: captive silicone suppliers with backward integration into medical-grade feedstock, precision extrusion specialists with ISO 10993 testing libraries, and regional assemblers leveraging polyethylene cost positioning. Competitive moves concentrate on M&A for sterile packaging capabilities and strategic partnerships with GPO-negotiated tier systems.
Among diversified medical technology conglomerates, Medtronic exemplifies the captive polymer sourcing archetype through upstream control over silicone precursor supply chains. ZEISS (FCI Ophthalmics) occupies a position within the precision distribution tier, anchoring European ophthalmology clinic relationships through specialized technical documentation libraries. Kaneka Pharma America LLC represents Japanese manufacturing standards compliance, sitting within the premium-tier contract negotiation segment where PMDA QMS certification filters competitor entry.
| Leading Market Players |
|---|
| Medtronic |
| Becton Dickinson and Company |
| ZEISS (FCI Ophthalmics) |
| Aurolab |
| Kaneka Pharma America LLC |
| Bess Medizintechnik GmbH |
| Gunther Weiss Scientific Glassblowing Co. |
| Beaver-Visitec International, Inc |
| Agfa Healthcare |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance pathways and CE marking under EU MDR simultaneously gate supply qualification and stratify price tiers across the lacrimal duct stent tube market. Manufacturers bearing these certification burdens command premium positioning in hospital procurement tenders, while uncertified competitors face exclusion from German statutory health insurance and Medicare Advantage reimbursement networks.
Pricing Analysis
Ambulatory surgical center buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the lacrimal duct stent tube market. Price differentiation stems from ISO 10993-5 cytotoxicity certification grade and silicone Shore A durometer specifications, with platinum-cured elastomer variants commanding substantial premiums over high-density polyethylene alternatives. Pricing pressure intensifies in Indian and Brazilian public hospital tenders as procurement budgets constrain silicone adoption. Cost-conscious buyers in tier-2 Maharashtra cities exhibit highest price sensitivity, while Japanese Kanto region ophthalmology clinics demonstrate lowest sensitivity due to JIS-standard compliance requirements.
Supply Chain Analysis
Medical-grade silicone precursor availability concentrates in the United States, Germany, and Japan, creating feedstock dependencies for extrusion houses serving global ophthalmology markets. Raw material sourcing draws from petrochemical-derived polydimethylsiloxane, platinum catalyst systems, and specialized Shore A durometer additives. Single-source vulnerability in platinum-cured elastomer supply exposes margin structures to energy market volatility. Distribution runs through GPO-negotiated tier systems and EDI-compatible catalog management platforms serving ambulatory surgical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser dacryocystorhinosty techniques achieving comparable patency rates without permanent implantation threaten incumbent stent volumes, forcing substitution defense strategies across manufacturer portfolios.
For Market Incumbents: Fortify backward integration into medical-grade silicone precursor supply chains to insulate margin structures from petrochemical volatility. Deepen ISO 10993 biocompatibility testing libraries to accelerate predicate device referencing for iterative retrievable stent designs, countering laser substitution threats in tertiary hospital settings. For New Entrants and Emerging Players: Anchor in tier-2 Indian cities across Maharashtra and Tamil Nadu where catheterization-trained ophthalmology networks remain underpenetrated. Target cost-optimized polyethylene stent variants for high-volume public hospital tenders, leveraging CDSCO import licensing navigation as a differentiated go-to-market capability. For Investors and Strategic Acquirers: EU MDR clinical evidence requirements for Class IIa implantable devices reshape the acquisition landscape toward manufacturers with established technical documentation libraries. Long-term viability centers on sterile packaging capabilities and lot-level traceability systems serving IDN consolidation trends. Monitor PMDA QMS inspection density as an inflection indicator for Japanese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical performance data mandates elevate documentation burdens for German notified body submissions. |
| Backward Integration | Captive silicone precursor supply insulates Medtronic against petrochemical cost swings squeezing competitors. |
| Hospital System Partnership | Single-source contracts with Dallas-Fort Worth ASC networks consolidate procurement around EDI-compatible suppliers. |
| Reimbursement Strategy | Medicare Advantage prior authorization thresholds for epiphora interventions expand Texas and Florida ambulatory volumes. |
| Software Companion Development | Telemedicine-integrated follow-up protocols via high-resolution endoscopic imaging extend stent monitoring beyond urban catchments. |
Methodological Framework
Operator-level perspectives from ophthalmic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this study. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, PMDA submission records, and hospital procurement databases. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation ensured cross-verification across the analysis window.
Sensitivity analysis framed the quantitative approach across material type, retrieval mechanism, application indication, and end-user facility tier segmentation dimensions. CAGRs derived from logistic diffusion curves fitted to ambulatory surgical center expansion trajectories and aging demographic epiphora intervention rates. Procedure reimbursement coding evolution and regulatory clearance timeline assumptions fed directly into adoption slope parameters.
Decision-makers should treat outputs as directional under stable FDA and CE marking pathway assumptions; material deviation in EU MDR clinical evidence requirements or PMDA QMS inspection protocols would warrant model refresh. Practitioners should keep alternative scenarios live as laser dacryocystorhinosty patency data and bioresorbable polymer resorption profiles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Fracture Fixation Products Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Radial Compression Devices Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Laryngoscopes Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Brazil Drug Delivery Devices Market