
 Global Pressure Relief Devices Market | 2026-2036
Global Pressure Relief Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pressure Relief Devices Market Foresight
Market Context
Preventive maintenance contracts for hospital-grade mattress systems is expanding beyond equipment sales into recurring revenue streams. Stryker leverages its direct-to-facility service networks to lock in multi-year agreements across integrated health systems. Hill-Rom sustains brand loyalty through predictive analytics platforms that monitor mattress inflation cycles and flag replacement needs before failure. Medtronic competes by bundling pressure relief surfaces with its broader patient monitoring portfolios, creating stickier institutional relationships.
Technical Definition and Segment Structure
Pressure relief devices are engineered safety mechanisms designed to vent excess pressure from vessels, pipelines, and process equipment by lifting a disc or piston against a calibrated spring or bellows assembly at predetermined set pressures, thereby preventing catastrophic rupture in industrial containment systems. Spring-loaded mechanical valves dominate installed bases across petrochemical plants due to decades of field-proven reliability and minimal external power dependencies, though electro-pneumatic actuation is displacing legacy designs in remote monitoring applications where real-time pressure telemetry reduces manual inspection rounds. Vacuum breakers capture expanding margin pools in pharmaceutical manufacturing as sterile bioprocessing vessels require precise negative pressure protection during cooling phases, while rupture discs anchor demand in oil and gas processing where zero-leakage isolation precedes scheduled maintenance turnarounds.
Regulatory Framework and Outlook
The FDA regulates powered pressure-reducing mattresses for medical use under 510(k) premarket notification requirements, while the EPA's Clean Air Act mandates leak detection and repair protocols for pressure relief valves in chemical processing facilities. ASME Boiler and Pressure Vessel Code Section VIII governs set pressure tolerances and capacity certification for industrial safety valves across North American jurisdictions, with notified bodies in Germany enforcing CE marking under the Pressure Equipment Directive for European market access. Stakeholders must monitor how digital health integration requirements reshape service component pricing and how carbon border adjustments alter sourcing economics for cast valve bodies.
Market Dynamics
Hospital procurement teams are consolidating vendor relationships for powered pressure-reducing surfaces around predictive maintenance platforms, compressing supplier margins while locking in multi-year service contracts that bundle hardware, telemetry, and replacement cycles into single agreements.
Growth Catalysts
- Germany's expanded statutory health insurance reimbursement:Broader eligibility criteria for pressure ulcer prevention devices accelerates hospital procurement volumes across acute care facilities.
- Electro-pneumatic actuation:Remote monitoring capabilities reduce manual inspection rounds in petrochemical installations, displacing spring-loaded mechanical valves in telemetry-critical applications.
- Pharmaceutical sterile bioprocessing expansion:Vacuum breakers capture margin pools as cooling-phase negative pressure protection becomes mandatory in biologics manufacturing.
Market Restraints
- Cast valve body sourcing volatility:Carbon border adjustments threaten input cost stability for European valve manufacturers dependent on foundry imports.
- FDA 510(k) pathway tightening:Premarket validation requirements for powered pressure-reducing surfaces extend approval timelines and elevate documentation burdens.
- Rupture disc substitution pressure:Zero-leakage isolation demands in oil and gas maintenance turnarounds limit recurring revenue potential versus serviceable valve designs.
Strategic Opportunities
- India's hospital infrastructure buildout:Underpenetrated acute care bed capacity creates first-mover advantage for alternating pressure mattress suppliers establishing local service networks.
- Digital health integration mandates:Mattress inflation cycle telemetry bundled with electronic health record systems opens software licensing revenue streams.
- CE marking under Pressure Equipment Directive:Notified body certification in Germany enables passporting across European Economic Area procurement tenders.
Industry Challenges
- Predictive analytics talent scarcity:Mattress sensor data interpretation and replacement forecasting algorithms require specialized biomedical engineering and data science competencies.
- Legacy pneumatic system integration:Electro-pneumatic valve retrofits face interoperability friction with existing plant control architectures in petrochemical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pressure Relief Devices Market |
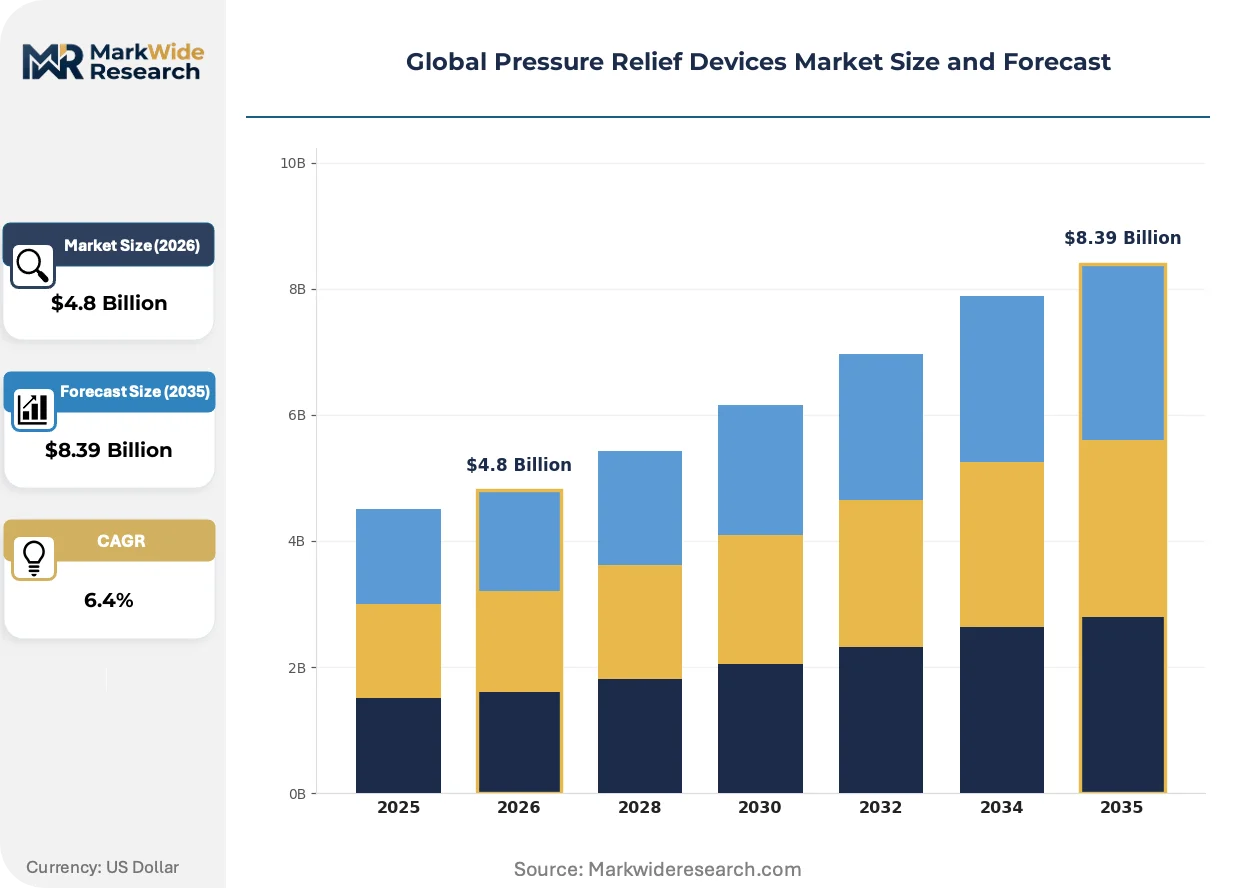
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pressure Relief Valves, Vacuum Breakers, Rupture Discs, Safety Valves, Pilot-Operated Valves Technology: Mechanical, Pneumatic, Hydraulic, Electro-Pneumatic, Spring-Loaded, Balanced Bellows Application: Oil & Gas Processing, Chemical Synthesis, Power Generation, Food Processing, Water Treatment, Pharmaceutical Manufacturing End User Industry: Petrochemical Plants, Energy Producers, Water Utilities, Food Manufacturers, Drug Formulators, Manufacturing Facilities |
| Companies Covered | Invacare Corporation, Talley Group Ltd, Stryker, Smith+Nephew, 3M, Hill-Rom, Medtronic, Essity Health & Medical, Arjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pressure Relief Devices Market Shifts & Advancements
Sensor-embedded mattress systems and electro-pneumatic valve architectures are converging around predictive maintenance business models, shifting competitive advantage from hardware durability toward data-driven service continuity guarantees.
Capacitive pressure mapping arrays embedded in alternating pressure mattresses are modularizing hospital procurement decisions. Acute care facilities in the United States adopt these sensor layers as upgradeable subcomponents rather than full mattress replacements. This modularity is compressing capital expenditure cycles and enabling mid-contract technology refreshes without equipment write-offs.
The FDA's updated 510(k) premarket notification framework for powered pressure-reducing surfaces is elevating clinical validation requirements. Manufacturers must now submit comparative effectiveness data against predicate devices, extending review timelines. Powered mattress segments with shorter product lifecycles face disproportionate compliance cost absorption relative to mechanical valve categories.
Acute care procurement teams are unbundling mattress hardware from preventive maintenance contracts. German hospital groups now separately tender inflation pump replacement schedules and sensor calibration services. This disintermediation of service components concentrates pricing pressure on original equipment suppliers while opening third-party maintenance markets.
Global Pressure Relief Devices Market Segmentation
Pressure relief devices serve divergent containment scenarios across medical and industrial domains, forcing suppliers to calibrate engineering specifications against regulatory regimes that vary sharply by end-use. Segmentation clarity enables procurement teams to match valve technologies to pressure ranges, media compatibility, and maintenance accessibility requirements.
Device Type:
Standardization dominates high-volume categories where ASME certification streamlines procurement, while custom-engineered solutions capture premium margins in exotic material applications.
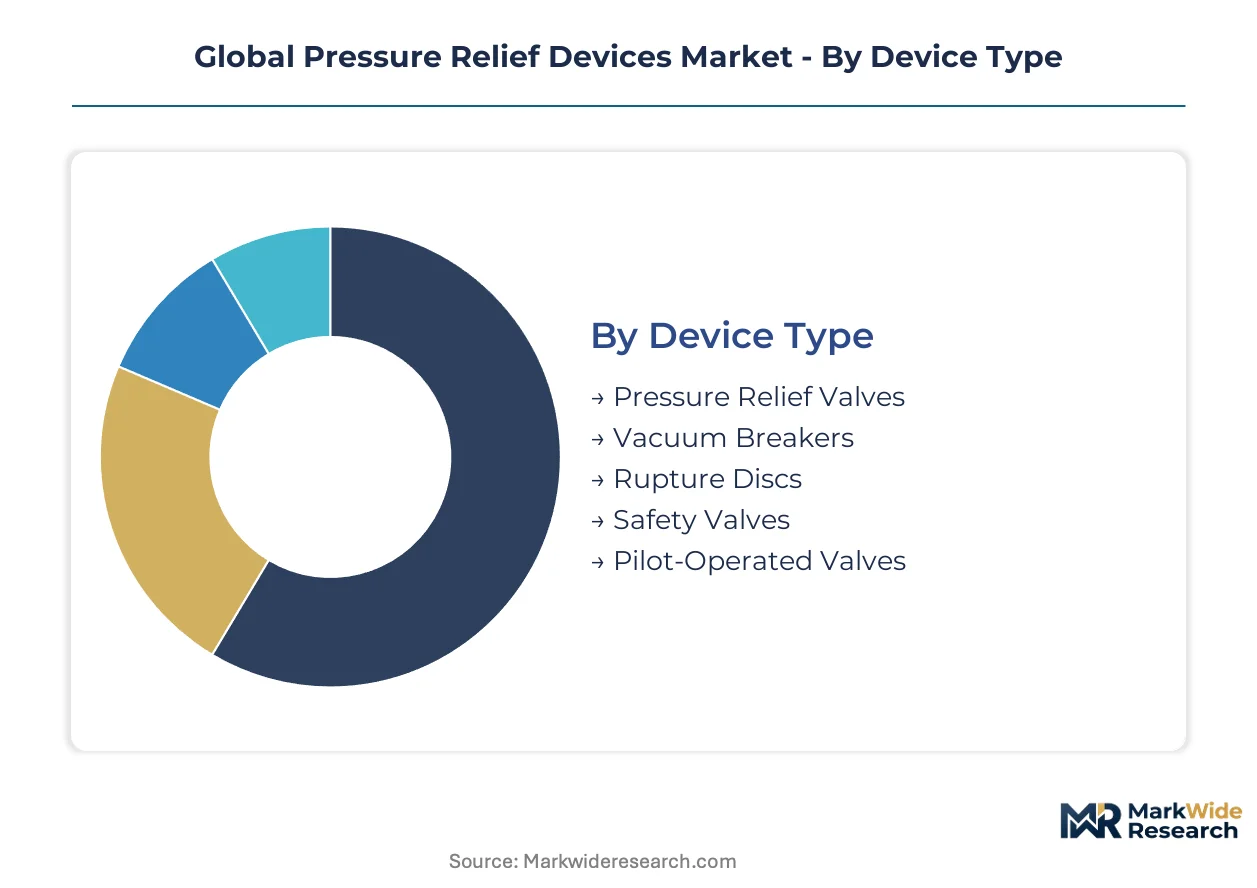
- Pressure Relief Valves:Spring-loaded or pilot-actuated mechanisms vent excess pressure through liftable discs against calibrated set points. Petrochemical plants in Germany specify these for routine overpressure protection where periodic recertification aligns with scheduled turnaround cycles.
- Vacuum Breakers:These devices admit atmospheric air to prevent vessel collapse during cooling or drainage phases. Pharmaceutical manufacturers in Switzerland deploy stainless steel variants for sterile bioprocessing where negative pressure protection is mandatory during autoclave cool-down sequences.
- Rupture Discs:Non-reclosing metal or graphite membranes provide instantaneous full-bore relief. Oil and gas processors in Norway favor these for zero-leakage isolation ahead of maintenance on toxic or flammable systems.
- Safety Valves:Code-certified devices with rapid opening characteristics protect boilers and compressed air systems. Power generation utilities in Japan specify JIS-compliant models for steam drum protection.
- Pilot-Operated Valves:Main valve actuation via pressure-sensing pilots enables near-zero operating pressure differentials. Liquefied natural gas terminals in Qatar deploy these for tight shutoff on cryogenic storage spheres.
Most installed capacity flows through Pressure Relief Valves. Expansion is steepest in Vacuum Breakers.
Technology:
Actuation method determines maintenance burden, response speed, and compatibility with plant control architectures across process industries.
- Mechanical:Direct-acting mechanisms without external power dependencies dominate legacy installations. Chemical plants in Belgium retain these for simplicity in corrosive environments where electronics degrade.
- Pneumatic:Instrument air-driven actuation enables remote set pressure adjustment. Offshore platforms in Brazil specify these for subsea wellhead protection where electrical ignition risks are prohibitive.
- Hydraulic:Fluid-pressure amplification delivers high seating forces for tight shutoff. Hydroelectric dam operators in Canada deploy these for penstock surge protection.
- Electro-Pneumatic:Solenoid-controlled pilot circuits integrate with distributed control systems for real-time telemetry. Refineries in the Netherlands are retrofitting these to reduce manual inspection rounds.
- Spring-Loaded:Helical compression springs provide consistent set pressure across temperature variations. Petrochemical complexes in Saudi Arabia standardize on these for decades of field-proven reliability.
- Balanced Bellows:Metallic bellows isolate spring and bonnet from process media, enabling use on corrosive or viscous fluids. Specialty chemical producers in India specify these for phosgene handling systems.
Spring-Loaded mechanisms anchor current installed bases. Electro-Pneumatic architectures are climbing the fastest as digitalization mandates spread.
Application:
Process severity and regulatory scrutiny intensity create tiered specification requirements across industrial verticals.
- Oil & Gas Processing:High-pressure separators, flare headers, and storage vessels require API-certified relief capacity. Upstream operators in Angola specify these for well testing equipment exposed to sour gas.
- Chemical Synthesis:Batch reactors and distillation columns need materials matched to aggressive media. Chlor-alkali producers in Germany deploy titanium-bodied valves for wet chlorine service.
- Power Generation:Boiler safety valves and turbine bypass systems protect steam circuits. Combined cycle plants in South Korea specify these for heat recovery steam generator protection.
- Food Processing:Sanitary designs with polished surfaces prevent microbial harborage. Dairy processors in New Zealand deploy these for pasteurizer overpressure protection.
- Water Treatment:Membrane filtration and disinfection systems require corrosion-resistant venting. Desalination plants in Israel specify these for reverse osmosis train protection.
- Pharmaceutical Manufacturing:Bioreactors and sterile hold vessels demand surface finishes and materials certificates. mRNA vaccine producers in the United States deploy these for single-use bag protection.
Oil and Gas Processing commands the largest valve count. Pharmaceutical Manufacturing is gaining share fastest on biologics capacity expansion.
End User Industry:
Procurement sophistication varies from centralized engineering standards at multinational energy firms to fragmented maintenance-driven purchasing at municipal utilities.
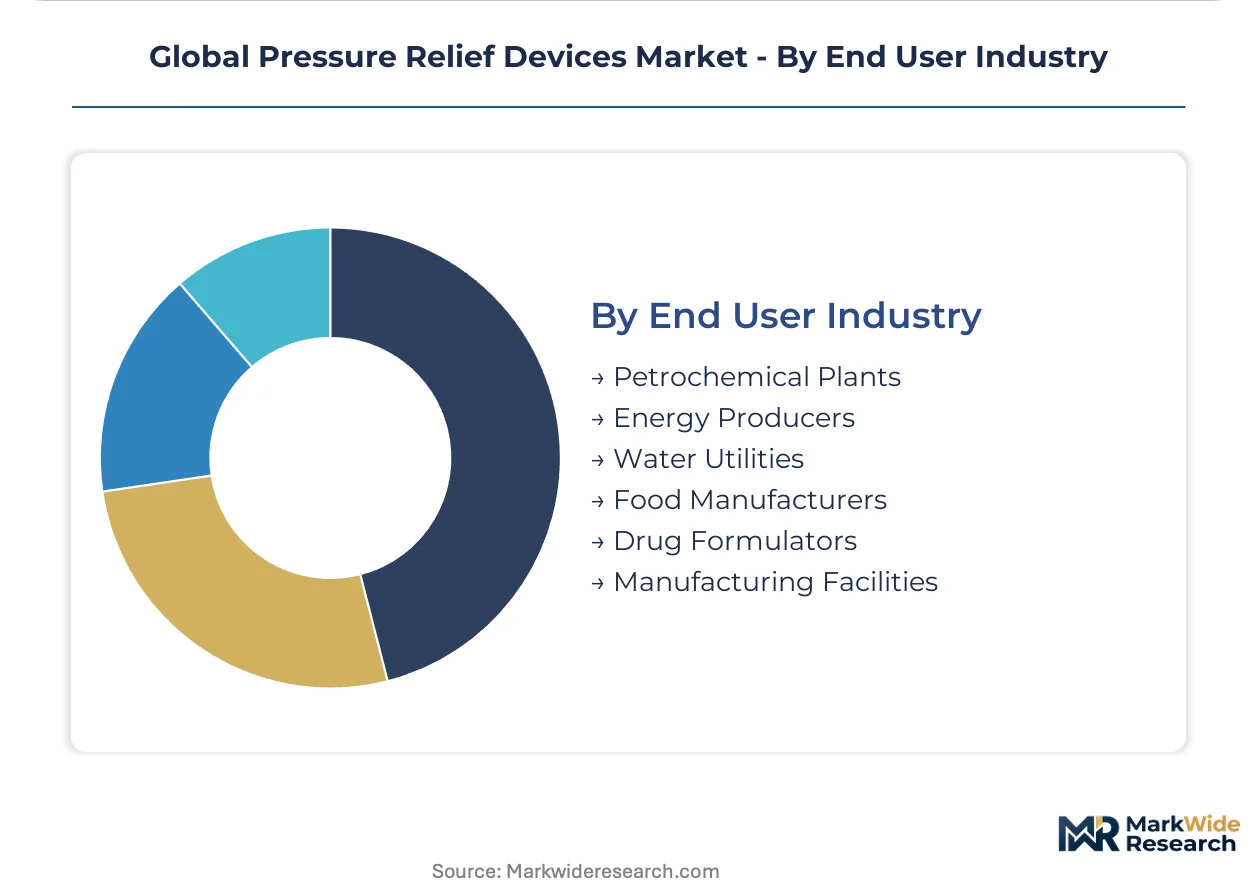
- Petrochemical Plants:Integrated operators maintain corporate engineering specifications that limit approved vendor lists. crackers in Texas enforce these for furnace coil protection.
- Energy Producers:Utility procurement departments bundle valve purchases with long-term service agreements. Wind farm operators in Denmark specify these for hydraulic power unit protection.
- Water Utilities:Municipal purchasing departments prioritize lifecycle cost over initial capital expenditure. Treatment works in England deploy these for digester gas relief.
- Food Manufacturers:Quality departments drive specifications emphasizing cleanability and traceability. Chocolate processors in Switzerland specify these for tempering vessel protection.
- Drug Formulators:Validation protocols extend procurement cycles but lock in premium suppliers. Sterile injectable facilities in Ireland enforce these for lyophilizer chamber protection.
- Manufacturing Facilities:General industrial users rely on distributor recommendations for compressed air system protection. Automotive stamping plants in Mexico specify these for press hydraulic reservoir relief.
Petrochemical Plants represent the deepest specification expertise. Drug Formulators are expanding procurement fastest on biologics manufacturing buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance reimbursement expansion outpaces US hospital procurement growth, while India's acute care bed buildout creates first-mover opportunities for alternating pressure mattress suppliers.
United States
Acute care facilities in Texas and Florida drive alternating pressure mattress procurement as chronic wound prevalence rises among aging populations. The FDA's tightened 510(k) premarket pathway extends validation timelines for powered pressure-reducing surfaces. Sensor-embedded mattress systems from manufacturers in the Minneapolis medical device cluster face compressed capital expenditure cycles as procurement teams unbundle hardware from service contracts.
Germany
Statutory health insurance reimbursement broadens eligibility for pressure ulcer prevention devices across Bavaria and North Rhine-Westphalia hospital networks. The Pressure Equipment Directive enforces CE marking through notified bodies in Berlin and Hamburg, enabling passporting across European Economic Area tenders. Predictive maintenance platforms from Baden-Württemberg engineering firms lock in multi-year service agreements with integrated health systems.
India
Underpenetrated acute care capacity in Maharashtra and Karnataka creates procurement momentum for hospital-grade mattress systems. The country's national medical device regulator enforces quality standards for powered pressure-reducing imports. Local service network establishment by Tamil Nadu-based distributors determines vendor selection in Delhi-NCR tertiary hospitals.
Japan
JIS-compliant safety valve specifications govern petrochemical installations in the Chubu industrial corridor around Nagoya. METI digitalization mandates accelerate electro-pneumatic valve retrofits in Kansai region refineries. Vacuum breaker demand from Osaka pharmaceutical manufacturers rises on biologics sterile processing expansion.
Netherlands
Rotterdam refinery operators retrofit spring-loaded mechanical valves with electro-pneumatic architectures to reduce manual inspection rounds. REACH chemical safety protocols influence materials selection for pressure relief devices in Antwerp-connected chemical clusters. Eindhoven region engineering consultancies specialize in predictive analytics integration for plant control system interoperability.
Global Pressure Relief Devices Market Competitive Landscape
Top-tier vendors anchor multi-year hospital service contracts, while mid-scale specialists compete on modular sensor subcomponents and third-party maintenance pricing. The market structures around three strategic archetypes: integrated health system partners bundling telemetry with hardware, predictive analytics platform developers monetizing mattress inflation cycle data, and industrial valve specialists pivoting toward pharmaceutical sterile processing applications. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion through local service network establishment in underpenetrated acute care markets.
Among US-based medical device incumbents, Stryker and Hill-Rom exemplify the integrated health system partner archetype through direct-to-facility service networks, while Medtronic occupies a position bridging patient monitoring portfolios with pressure relief surface bundling. On the industrial valve vector, Talley Group Ltd represents European engineering heritage in pressure management solutions.
| Leading Market Players |
|---|
| Invacare Corporation |
| Talley Group Ltd |
| Stryker |
| Smith+Nephew |
| 3M |
| Hill-Rom |
| Medtronic |
| Essity Health & Medical |
| Arjo |
| Others |
Supply & Pricing Matrix
Biomedical engineering talent clusters in the Minneapolis-St. Paul medical device corridor compress R&D cost differentials between premium sensor-embedded mattress tiers and standard alternating pressure systems. German statutory reimbursement floors sustain pricing spreads across European markets while Indian acute care procurement gravitates toward economy-tier imports.
Pricing Analysis
Capacity additions in Tamil Nadu and Maharashtra are reshaping price floors for hospital-grade mattress systems across South Asian procurement tenders. Three-tier pricing structure across premium sensor-embedded, standard alternating pressure, and economy static foam levels dominates acute care contracting. FDA 510(k) validation burdens concentrate pricing pressure on powered pressure-reducing surfaces while mechanical valve categories absorb cost compression more gradually. Price-sensitive municipal water utilities in England and India drive economy-tier valve volumes; least-sensitive pharmaceutical formulators in Switzerland and Ireland sustain premium margins for sterile-grade vacuum breakers.
Supply Chain Analysis
Cast valve body supply rests on foundry networks in Germany, India, and China with divergent carbon intensity profiles. Stainless steel billet and graphite membrane inputs feed specialty chemical and oil and gas processing demand. Carbon border adjustment exposure threatens European valve manufacturer cost stability. Distribution runs through authorized distributor networks for industrial valves and direct-to-facility service agreements for hospital mattress systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pressure Relief Devices Market compounds steadily on aging population chronic wound prevalence and biologics manufacturing sterile processing mandates. Hospital procurement consolidation and predictive maintenance platform adoption create durable recurring revenue streams.
For Market Incumbents: Acquire predictive analytics software capabilities to defend against modular sensor subcomponent suppliers disintermediating service contracts. Secure multi-year agreements with integrated health systems in Germany and the United States. Backward integration into capacitive pressure mapping array manufacturing protects margin pools from third-party module vendors.
For New Entrants and Emerging Players: Tier-two city hospital groups in India represent the most penetrable buyer archetype for alternating pressure mattress suppliers establishing local service networks. Target electro-pneumatic valve retrofits in Netherlands and Japanese refineries facing METI digitalization mandates. Partner with Eindhoven or Baden-Württemberg engineering consultancies for control system interoperability credentials.
For Investors and Strategic Acquirers: Valuations sit cheapest among industrial valve specialists pivoting toward pharmaceutical sterile processing applications without established biologics customer relationships. Five-to-ten year viability hinges on CE marking completion and FDA 510(k) pathway navigation. Watch Germany's statutory reimbursement expansion rate as inflection indicator for hospital mattress procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Stryker and Hill-Rom monetize mattress inflation telemetry through multi-year service contracts locking in integrated health systems. |
| CE Marking Under Pressure Equipment Directive | Notified body certification in Berlin enables valve manufacturers to passport across European Economic Area procurement tenders. |
| Electro-Pneumatic Valve Retrofit Programs | Rotterdam and Kansai region refineries reduce manual inspection rounds through distributed control system integration. |
| Sensor-Embedded Mattress Modularity | Acute care facilities in Texas adopt upgradeable capacitive pressure mapping arrays without full equipment replacement. |
| Local Service Network Establishment | Tamil Nadu-based distributors determine vendor selection in Delhi-NCR tertiary hospitals for powered pressure-reducing imports. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Middle East, with primary inputs from each region's dominant procurement clusters. Hospital purchasing committees, biomedical engineers, petrochemical plant maintenance directors, and GPO contracts managers contributed interview data. Secondary validation drew from FDA 510(k) filings, EPA Clean Air Act enforcement records, ASME Boiler and Pressure Vessel Code documentation, and German statutory health insurance reimbursement schedules. Bottom-up unit economics and top-down macroeconomic indicators were triangulated.
Granularity-level modeling distinguished device type, actuation technology, application severity, and end-user procurement sophistication across the projection horizon. Segment-specific CAGRs were derived from installed base turnover rates and replacement cycle compression. Forecast inputs incorporated chronic wound prevalence trajectories, biologics manufacturing capacity buildouts, and digital health integration mandate timelines.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-time electro-pneumatic valve retrofit completion rates introduce uncertainty bands around telemetry adoption curves. Forecasts reflect documented assumptions regarding reimbursement policy stability and carbon border adjustment implementation scope. Regulatory pathway delays, foundry supply disruptions, and predictive analytics talent scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laparoscopic Devices Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Walking Aids Market
Medical Devices
Enteral Stents Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Artificial Eye Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Removable Partial Dentures Market