
 MRI Safe Biopsy Needle Market | 2026-2036
MRI Safe Biopsy Needle Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Safe Biopsy Needle Market Foresight
The EU Medical Device Regulation is rebalancing the cost-of-entry calculus for manufacturers seeking European market access, forcing upgrades in biocompatibility documentation and post-market surveillance infrastructure. Hologic sustains leadership through dedicated women's health imaging channels that bundle biopsy systems with needle consumables. Cook Medical anchors its position via deep specialization in interventional radiology workflows across major academic medical centers. BD leverages its scale in automated manufacturing to compete on unit economics for high-volume disposable needle contracts.
An MRI safe biopsy needle consists of non-ferromagnetic materials—typically titanium alloys, specialized polymers, or ceramic composites—engineered to eliminate projectile risk and image artifact during 1.5T to 3T magnetic resonance imaging procedures, enabling real-time tissue sampling under direct MRI visualization without patient transfer. Vacuum-assisted needles dominate procedural throughput in breast imaging suites due to superior specimen volume and reduced sampling error, while core needles retain primacy in prostate and lung applications where access trajectory constraints favor smaller gauge profiles. Stainless steel alternatives face accelerating displacement from composite and ceramic architectures as institutions prioritize full compatibility with next-generation 7T research scanners.
FDA 510(k) clearance pathways govern US commercialization, requiring electromagnetic compatibility validation and material certification that extend development timelines by twelve to eighteen months relative to conventional biopsy instruments. The EU AI Act and MDR framework collectively reshape clinical evidence requirements, compelling manufacturers to demonstrate algorithm-assisted needle placement accuracy where software interfaces with MRI navigation systems. Stakeholders must monitor evolving reimbursement parity between MRI-guided and ultrasound-guided biopsy procedures, as institutional purchasing decisions increasingly hinge on per-procedure cost equivalence rather than technical superiority alone.
Market Dynamics
Magnetic field strength escalation in diagnostic imaging—particularly the clinical migration from 3T to 7T scanners—is forcing material recertification across the installed base of biopsy instruments, compressing product lifecycles and accelerating R&D burn rates for non-ferromagnetic architectures.
Growth Catalysts
- EU MDR material traceability mandates:Implantable instrument documentation requirements are filtering out marginal suppliers and consolidating procurement toward certified manufacturers with established post-market surveillance infrastructure.
- Vacuum-assisted breast biopsy throughput:Women's health imaging suites in the United States prioritize specimen volume efficiency, driving replacement cycles for legacy core needle systems.
- Japan's dense MRI installation base:Tokyo and Osaka metropolitan hospital clusters generate concentrated demand for compatible disposable instruments that eliminate patient transfer protocols.
Market Restraints
- Titanium alloy input cost volatility:Aerospace and medical device demand competition for Grade 5 titanium creates margin pressure on needle manufacturers without backward integration into raw material sourcing.
- Supply concentration in German precision machining:Single-source dependencies for ceramic composite fabrication create vulnerability to regional energy cost fluctuations.
- FDA electromagnetic compatibility validation timelines:The twelve-to-eighteen month clearance extension relative to conventional instruments delays revenue recognition for new product launches.
Strategic Opportunities
- Underpenetrated lung biopsy applications:Smaller gauge ceramic core needles address trajectory constraints in thoracic interventions where 7T scanner compatibility remains unaddressed.
- Algorithm-assisted needle placement:The EU AI Act creates regulatory tailwinds for navigation software integration with MRI guidance systems in academic medical centers.
- Direct-to-hospital distribution platforms:Disintermediation of traditional surgical supply distributors enables margin capture and real-time consumption data feedback.
Industry Challenges
- Specialized polymer engineering talent scarcity:Ceramic-to-polymer bonding expertise for 7T-compatible instrument architecture concentrates in a limited pool of interventional radiology device veterans.
- Legacy PACS integration complexity:MRI navigation system software interfaces require costly customization to communicate with existing hospital imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Safe Biopsy Needle Market |
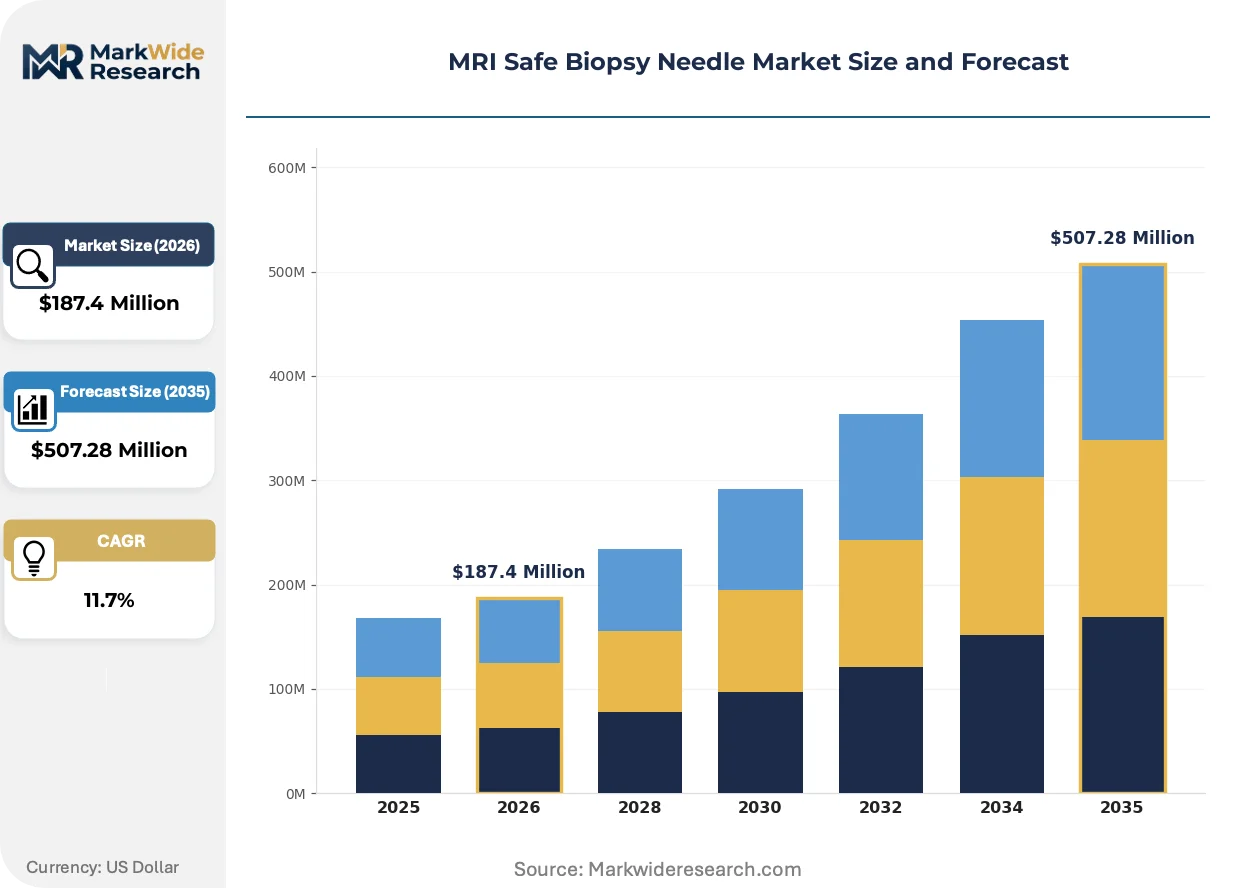
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Needles, Core Needles, Vacuum-Assisted Needles, Specialty Needles Application: Breast Biopsy, Prostate Biopsy, Lung Biopsy, Liver Biopsy End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Clinics Material: Stainless Steel, Plastics, Composites, Ceramic |
| Companies Covered | Olympus, Hologic, Argon Medical Devices, Somatex Medical Technologies, BD, Sterylab, Boston Scientific Corporation, Medtronic, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Safe Biopsy Needle Market Shifts & Advancements
Real-time MRI visualization during tissue extraction is compressing the gap between diagnostic imaging and interventional procedure, eliminating workflow friction that previously required patient transfer between magnet and biopsy suite.
Ceramic composite needle architectures is converging with vacuum-assisted biopsy mechanisms to enable simultaneous 7T compatibility and superior specimen yield. Academic medical centers in Germany and Japan are piloting these hybrid systems ahead of broader commercial deployment. The convergence is compressing the addressable market for pure titanium alternatives that exhibit residual artifact at higher field strengths.
The EU AI Act and MDR framework collectively mandate algorithmic transparency for navigation-assisted placement systems. Manufacturers must now submit clinical evidence demonstrating accuracy improvements over freehand techniques. Breast imaging suites in France and the Netherlands face the steepest compliance burden as early adopters of software-integrated MRI guidance.
Hospital procurement committees now bundle needle contracts with MRI system service agreements, consolidating vendor relationships and compressing switching flexibility. This behavior concentrates purchasing power within integrated delivery networks in the United States and hospital groups in England. The shift is most visible in high-volume breast imaging centers where per-procedure cost equivalence with ultrasound-guided alternatives determines contract awards.
MRI Safe Biopsy Needle Market Segmentation
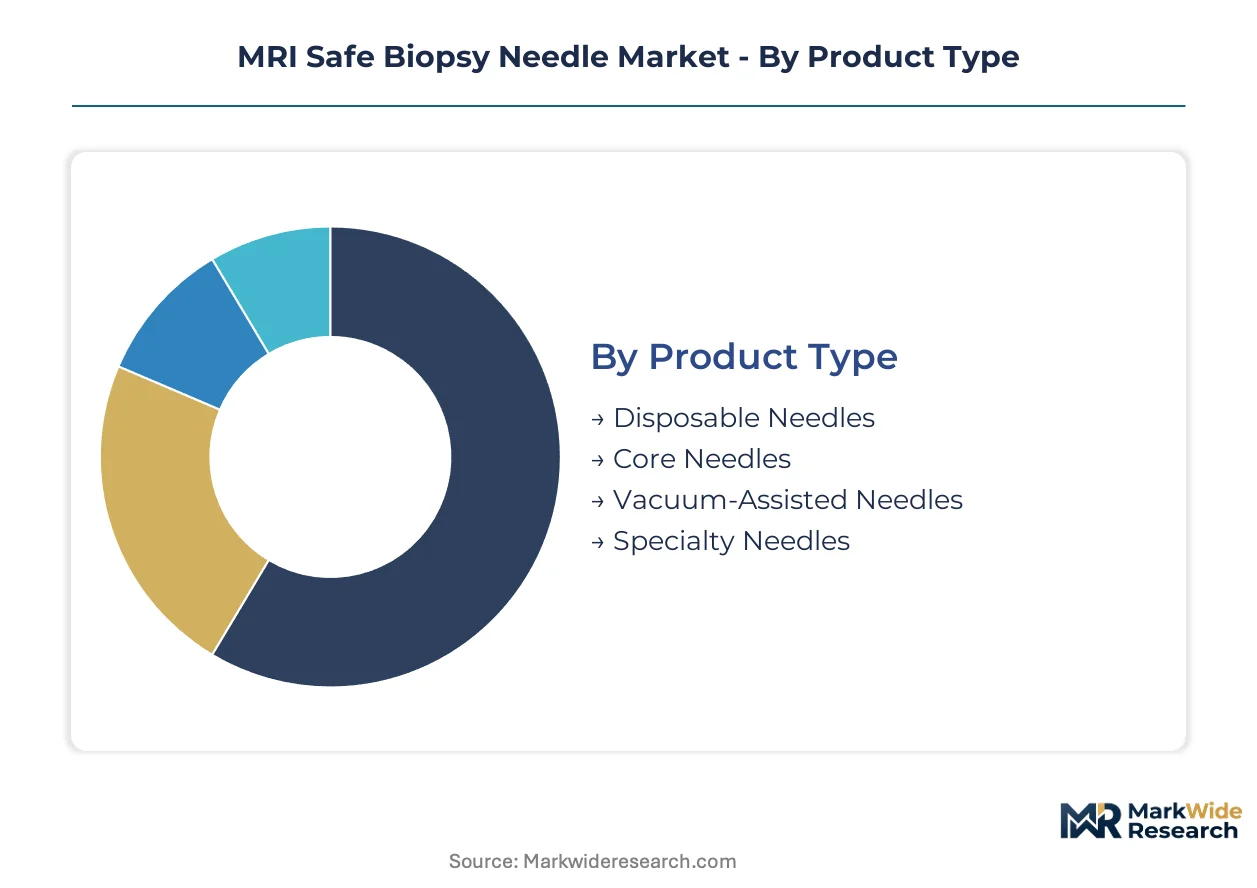
Material architecture and field strength compatibility dictate procurement patterns across hospital systems. Product lifecycle compression at 7T scanner installations forces premature replacement of legacy needle inventories.
Product Type:
Supply concentration for vacuum-assisted mechanisms clusters among German precision machining centers and Japanese ceramic composite foundries.
- Vacuum-Assisted Needles:Integrated suction mechanisms extract larger tissue volumes per pass, reducing sampling error in breast imaging suites. United States women's health centers prioritize these systems for throughput efficiency in high-volume screening programs.
- Core Needles:Hollow cylindrical designs with cutting notches capture cylindrical tissue specimens for histopathological analysis. Prostate biopsy applications in German academic medical centers favor 18-gauge profiles for transperineal access trajectories.
- Disposable Needles:Single-use titanium or polymer instruments eliminate sterilization logistics and cross-contamination protocols.
- Specialty Needles:Custom-configured lengths and tip geometries address pediatric or anatomically constrained interventions.
Vacuum-assisted configurations absorb the bulk of installed capacity; specialty needles are expanding most quickly.
Application:
Cost tier stratification separates premium MRI-guided procedures from standard ultrasound alternatives in hospital budgeting frameworks.
- Breast Biopsy:Vacuum-assisted systems dominate screening-detected lesion workups, with specimen radiography confirming adequate sampling. Dense breast tissue populations in Japan drive preference for MRI guidance over mammography-directed alternatives.
- Prostate Biopsy:Transperineal approaches under direct MRI visualization reduce infection rates versus transrectal ultrasound methods. French urology departments are consolidating procurement around MRI-compatible core needle platforms.
- Lung Biopsy:Smaller gauge instruments navigate pleural trajectory constraints where respiratory motion complicates target acquisition.
- Liver Biopsy:Coaxial introducer systems enable multiple passes through a single pleural or peritoneal access point.
Breast applications command the highest procedure volumes; lung biopsy represents the steepest expansion trajectory.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating needle contracts across multiple sites.
- Hospitals:Academic medical centers in Germany and Japan maintain dedicated MRI interventional suites with captive needle inventories. Capital equipment bundling with MRI service agreements compresses vendor switching flexibility.
- Diagnostic Centers:Independent imaging facilities in the United States face reimbursement parity constraints between MRI-guided and ultrasound-guided alternatives.
- Research Laboratories:7T scanner installations require experimental needle prototypes not yet cleared for clinical use.
- Outpatient Clinics:Lower procedural volumes favor disposable core needles over capital-intensive vacuum-assisted systems.
Hospitals dominate current procurement volume; diagnostic centers are gaining share fastest.
Material:
Margin profiles diverge sharply between commodity titanium feedstock and engineered ceramic composites requiring specialized bonding expertise.
- Composites:Polymer-ceramic hybrid architectures eliminate ferromagnetic signal voids at 3T and 7T field strengths. Tokyo metropolitan hospital clusters are piloting these configurations ahead of broader commercial deployment.
- Ceramic:Aluminum oxide or zirconia compositions achieve full electromagnetic transparency with superior hardness for cutting edge retention. Single-source dependencies in German fabrication create supply vulnerability to regional energy cost fluctuations.
- Titanium Alloys:Grade 5 titanium maintains structural integrity with paramagnetic properties suitable for 1.5T to 3T environments.
- Plastics:PEEK and similar high-performance polymers serve as hub and handle components rather than primary cannula materials.
- Stainless Steel:Conventional ferromagnetic compositions face accelerating displacement from MRI-compatible alternatives.
Composites and ceramics together absorb the bulk of R&D investment; ceramic configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical device manufacturing in Penang and Shenzhen have concentrated precision machining capacity for MRI-compatible instruments. Tax incentives in these zones attract component suppliers for ceramic composite fabrication. Industrial clusters in Germany and Japan retain dominance in high-field-strength certification expertise.
United States
FDA electromagnetic compatibility validation timelines extend commercialization cycles for new needle architectures. The 21st Century Cures Act provisions accelerate breakthrough device designation pathways for algorithm-assisted placement systems. Boston and Minneapolis metropolitan medical device corridors host dedicated MRI interventional radiology research programs at academic medical centers.
Germany
Baden-Württemberg precision machining clusters supply ceramic composite components for 7T-compatible needle prototypes. EU MDR material traceability mandates force documentation upgrades across the supplier base. Stuttgart and Tübingen university hospital networks pilot vacuum-assisted hybrid systems ahead of broader EU deployment.
Japan
Tokyo and Osaka metropolitan hospital clusters maintain the densest MRI installation base per capita globally. PMDA streamlined review pathways for combination devices reduce clearance friction for navigation-integrated systems. Kobe medical device manufacturing zones specialize in titanium alloy processing for disposable needle production.
United Kingdom
NHS England procurement frameworks bundle needle contracts with MRI service agreements across integrated care systems. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR timelines for certain device categories. Cambridge and Oxford research hospital networks drive early adoption of experimental 7T-compatible ceramic architectures.
France
ANSM oversight of high-risk implantable instruments enforces stringent biocompatibility documentation for ceramic-to-polymer bonding. The EU AI Act creates compliance burdens for software-integrated MRI navigation systems in Paris and Lyon academic centers. Île-de-France hospital groups consolidate purchasing power through centralized procurement platforms.
MRI Safe Biopsy Needle Market Competitive Landscape
United States producers anchor one tier; German and Japanese specialists hold differentiated positions in high-field-strength materials. The vendor base stratifies across three tiers: diversified medical technology conglomerates with imaging system integration capabilities, mid-scale interventional radiology specialists with deep workflow expertise, and regional disposable instrument fabricators competing on unit economics. Dominant competitive moves include backward integration into ceramic composite supply chains and strategic partnerships with MRI system OEMs for bundled service contracts.
Within the imaging-integrated tier, Hologic and Boston Scientific Corporation exemplify archetypes combining dedicated women's health channels with procedural workflow bundling. Cook Medical occupies a position among interventional radiology specialists with concentrated presence in academic medical center procurement networks. BD represents the scale-driven archetype leveraging automated manufacturing infrastructure for high-volume disposable needle contracts across integrated delivery networks.
| Leading Market Players |
|---|
| Olympus |
| Hologic |
| Argon Medical Devices |
| Somatex Medical Technologies |
| BD |
| Sterylab |
| Boston Scientific Corporation |
| Medtronic |
| Cook Medical |
| Others |
Supply & Pricing Matrix
Grade 5 titanium spot price volatility cascades through three distinct pricing tiers, compressing margins for manufacturers without captive feedstock arrangements while amplifying procurement power for integrated players serving academic medical centers.
Pricing Analysis
Lead-time-driven premiums dominate contract negotiations, with hospitals paying surcharges for expedited delivery of 7T-compatible ceramic composite needles while spot inventory of legacy titanium configurations trades at discounts. Pricing stratifies across premium, standard, and economy tiers based on field strength certification level and volume commitment scale. Cost compression in the standard tier is intensifying because German precision machining centers face energy cost escalation. Integrated delivery networks exhibit the highest price sensitivity, whereas Japanese metropolitan hospital clusters prioritize electromagnetic compatibility over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Tokyo, and Minneapolis anchor hub-and-spoke patterns that feed hospital procurement networks. Manufacturing concentration clusters in Germany, Japan, and the United States, with ceramic composite fabrication drawing from Baden-Württemberg precision machining and Kobe titanium processing. Raw material dependencies rest on aerospace-grade titanium feedstock, aluminum oxide ceramic precursors, and specialized polymer bonding agents. Single-source vulnerability in German ceramic-to-polymer bonding expertise creates structural risk. Distribution runs through GPO contracts and direct-to-hospital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MRI safe biopsy needle market reads as a cost-of-compliance story where EU MDR material traceability mandates erect barrier-to-entry moats that favor incumbent manufacturers with established post-market surveillance infrastructure.
For Market Incumbents: Deploy backward integration into ceramic composite supply chains to neutralize single-source dependencies in German fabrication. Anchor procurement relationships through MRI service agreement bundling that compresses hospital switching flexibility. Counter margin pressure from titanium alloy input cost volatility by securing long-term offtake arrangements with aerospace-grade feedstock suppliers. For New Entrants and Emerging Players: Launch via direct-to-hospital distribution platforms that disintermediate traditional surgical supply intermediaries and capture real-time consumption data. Target lung biopsy applications where 7T scanner compatibility remains underserved by existing ceramic core needle configurations. Prioritize algorithm-assisted needle placement software integration to align with EU AI Act compliance requirements. For Investors and Strategic Acquirers: The window for entry favors mid-scale interventional radiology specialists with deep workflow expertise in academic medical center networks. Long-term viability hinges on consolidation plays that combine ceramic composite engineering capability with established hospital procurement channels. Watch PMDA streamlined review pathway expansion as the signal indicating favorable regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Composite Backward Integration | Captures margin from German precision machining concentration and neutralizes energy cost volatility exposure. |
| EU MDR Certification Investment | Secures market access moat through material traceability documentation and post-market surveillance infrastructure. |
| Algorithm-Assisted Placement Software | Aligns with EU AI Act transparency mandates for navigation systems in academic medical centers. |
| Direct-to-Hospital Distribution Platform | Disintermediates surgical supply distributors and enables real-time consumption data feedback loops. |
| 7T Scanner Compatibility R&D | Addresses premature replacement cycles as magnetic field strength escalation compresses product lifecycles. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records, complemented by interviews with interventional radiologists, biomedical engineers, GPO contracts managers, and hospital purchasing committee members. Secondary validation drew from PMDA submission summaries, CMS Medicare reimbursement data, and academic medical center capital expenditure disclosures. Bottom-up instrument shipment analysis and top-down imaging procedure volume estimates were triangulated.
Historical adoption curves for vacuum-assisted versus core needle configurations were cross-referenced against expert panel input on 7T scanner deployment timelines. Segmentation modeling spanned material architecture, field strength compatibility, application type, and end-user purchasing authority across the projection horizon. CAGRs were derived from procedure volume elasticity to MRI installation base expansion and replacement cycle compression factors.
Regulatory timeline delays, raw material price spikes, and reimbursement parity shifts between MRI-guided and ultrasound-guided alternatives are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Global Concussion Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Spain Contraceptive Devices Market