
 C-Arms Devices Market | 2026-2036
C-Arms Devices Market Size, Share, and Industry Trends Forecast 2026-2036
C-Arms Devices Market Outlook
Ambulatory surgical centers is realigning procurement patterns across the C-Arms Devices landscape as outpatient volumes shift from inpatient settings. Siemens Healthineers leverages its fluoroscopy R&D pipeline to sustain technology leadership in image-guided surgery. GE Healthcare anchors its position through deep installed-base relationships and service contract density in North American hospital networks.
C-Arms devices are X-ray imaging systems built on a C-shaped gantry arm that rotates around the patient table, typically operating at 50-120 kVp with flat-panel detectors replacing legacy image intensifiers in newer configurations; they deliver real-time intraoperative fluoroscopy for surgical navigation and interventional procedures. Mobile C-Arms now dominate volume shipments as facilities prioritize fleet flexibility and room turnover efficiency over fixed-room installations. Digital technology leads replacement demand as analog systems face obsolescence and higher maintenance burdens, while fluoroscopy capabilities command premium positioning in cardiovascular and orthopedic application segments.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU MDR framework imposes stricter clinical evidence and post-market surveillance obligations on manufacturers selling into European member states. Japan's PMDA maintains distinct pharmaceutical and medical device approval pathways that extend time-to-market for foreign vendors. Stakeholders must weigh regulatory compliance costs against the margin structure of premium digital platforms when allocating R&D budgets across geographic portfolios.
Market Dynamics
Mobile C-Arms are displacing fixed-room installations as ambulatory surgical centers prioritize fleet flexibility and same-day discharge workflows. EU MDR recertification timelines are compressing vendor R&D budgets toward clinical evidence generation rather than hardware innovation.
Growth Catalysts
- Outpatient procedural migration:Ambulatory surgical centers in the United States are expanding mobile C-Arm fleets to capture orthopedic and pain-management volumes shifting from hospital inpatient settings.
- Digital detector replacement cycles:Flat-panel detector technology is rendering analog image intensifier systems obsolete, forcing replacement purchases across aging installed bases in Germany and Japan.
- FDA 510(k) pathway efficiency:The premarket notification framework accelerates clearance timelines for iterative device modifications, enabling faster commercialization of software-enhanced imaging platforms.
Market Restraints
- Xenon short-arc lamp supply concentration:Sourcing of high-intensity discharge lamps for fluoroscopy tubes concentrates among limited specialty manufacturers, creating input cost volatility and extended lead times.
- EU MDR clinical evidence burdens:The recast Medical Device Regulation imposes stricter post-market surveillance and clinical evaluation requirements, extending time-to-market for European launches by 12-18 months.
- Interventional MRI substitution threat:Real-time magnetic resonance imaging for soft-tissue visualization is capturing complex neurosurgical and cardiac procedures previously dependent on C-Arm fluoroscopy.
Strategic Opportunities
- India's underserved tier-2 cities:Diagnostic imaging penetration remains below 15% in secondary urban centers, creating whitespace for mobile C-Arm deployment in multi-specialty clinics.
- AI-enhanced surgical navigation convergence:Integration of machine learning-based anatomical recognition with live fluoroscopy is unifying preoperative planning and intraoperative guidance into single-platform workflows.
- Japan's PMDA fast-track pathway:The Sakigake designation system offers priority review for breakthrough devices, creating regulatory tailwinds for vendors with novel detector materials or radiation dose reduction technologies.
Industry Challenges
- Clinical engineering talent scarcity:Maintenance of hybrid digital-analog systems requires specialized biomedical technician skills that hospital systems struggle to retain against industrial imaging sectors.
- Legacy DICOM integration friction:New flat-panel systems face interoperability challenges with hospital PACS architectures built around older image intensifier data formats, complicating enterprise-wide deployment.
- Radiation physicist certification bottlenecks:Qualified medical physicists for acceptance testing and annual compliance surveys are concentrated in academic medical centers, delaying installation timelines at community facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C-Arms Devices Market |
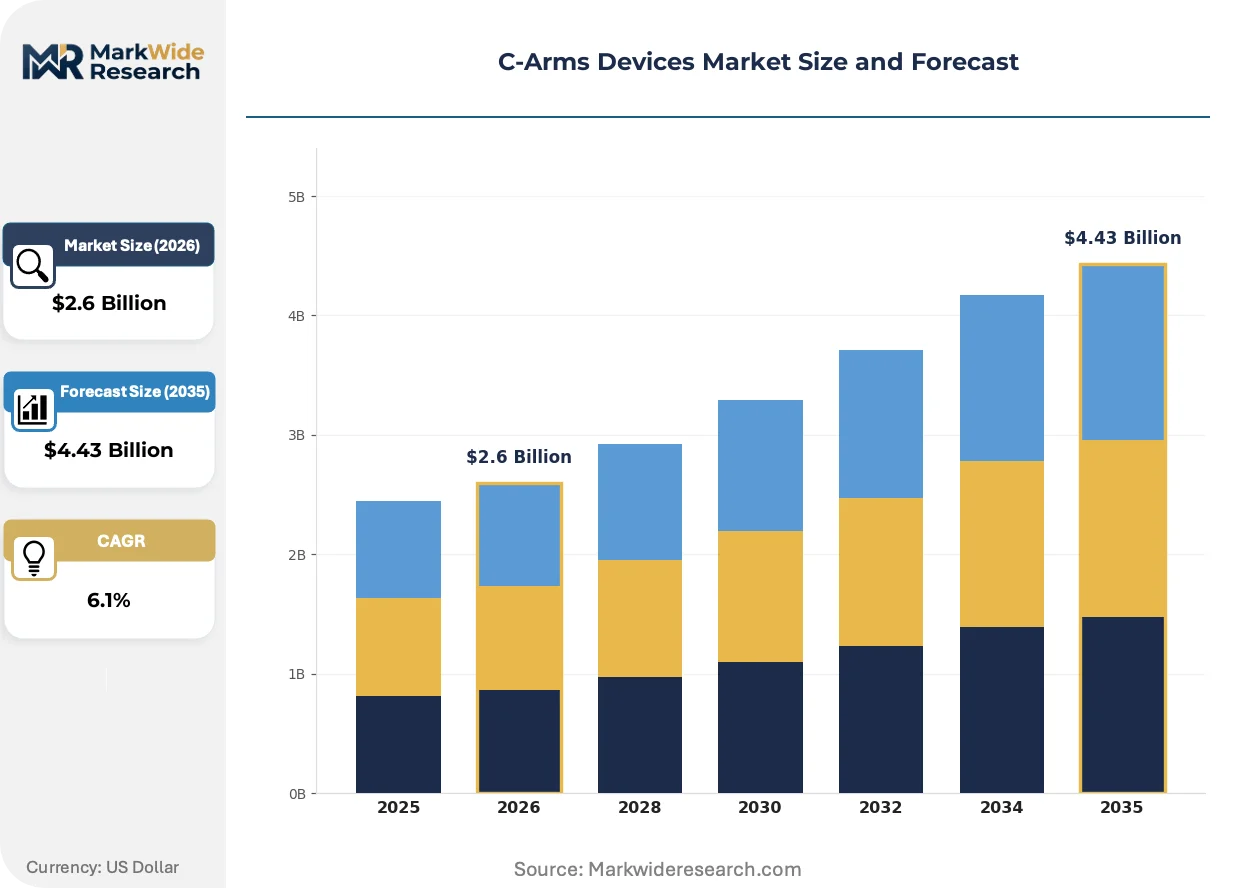
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.43 Billion |
| CAGR (2026 – 2036) | 6.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Mobile, Mini C-Arms, Handheld End User: Hospitals, Surgical Centers, Imaging Clinics, Emergency Departments Technology: Digital, Analog, Fluoroscopy, Image Intensification Application: Orthopedic Surgery, Pain Management, Cardiovascular Procedures, Neurological Applications |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Ziehm Imaging, Canon Medical Systems, Fujifilm, Hologic, Shimadzu Corporation, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C-Arms Devices Market Strategic Shifts
Real-time 3D imaging capabilities are compressing the distinction between diagnostic CT and intraoperative fluoroscopy. Vendors are racing to embed artificial intelligence directly at the detector level rather than in downstream workstations.
CMOS flat-panel detector technology is unifying low-dose fluoroscopy with high-resolution radiography into single hardware configurations. Ambulatory surgical centers are adopting these hybrid-capability systems to maximize room utilization across diverse procedure types. The technology is compressing capital equipment budgets by eliminating redundant dedicated systems.
Japan's PMDA has tightened radiation dose reporting requirements for interventional fluoroscopy systems under revised ministerial ordinances. Manufacturers must now submit comprehensive dose-area product validation data for all new device registrations. Cardiovascular application segments face the steepest compliance burden as electrophysiology procedures attract heightened scrutiny.
Hospital procurement committees are unbundling service contracts from equipment purchases, treating maintenance as competitively bid commodities rather than manufacturer-captive revenue streams. Integrated delivery networks in the United States are driving this disintermediation through centralized capital allocation committees. Orthopedic service lines show the most aggressive contract unbundling as procedure volumes concentrate in high-throughput ambulatory settings.
C-Arms Devices Market Segmentation
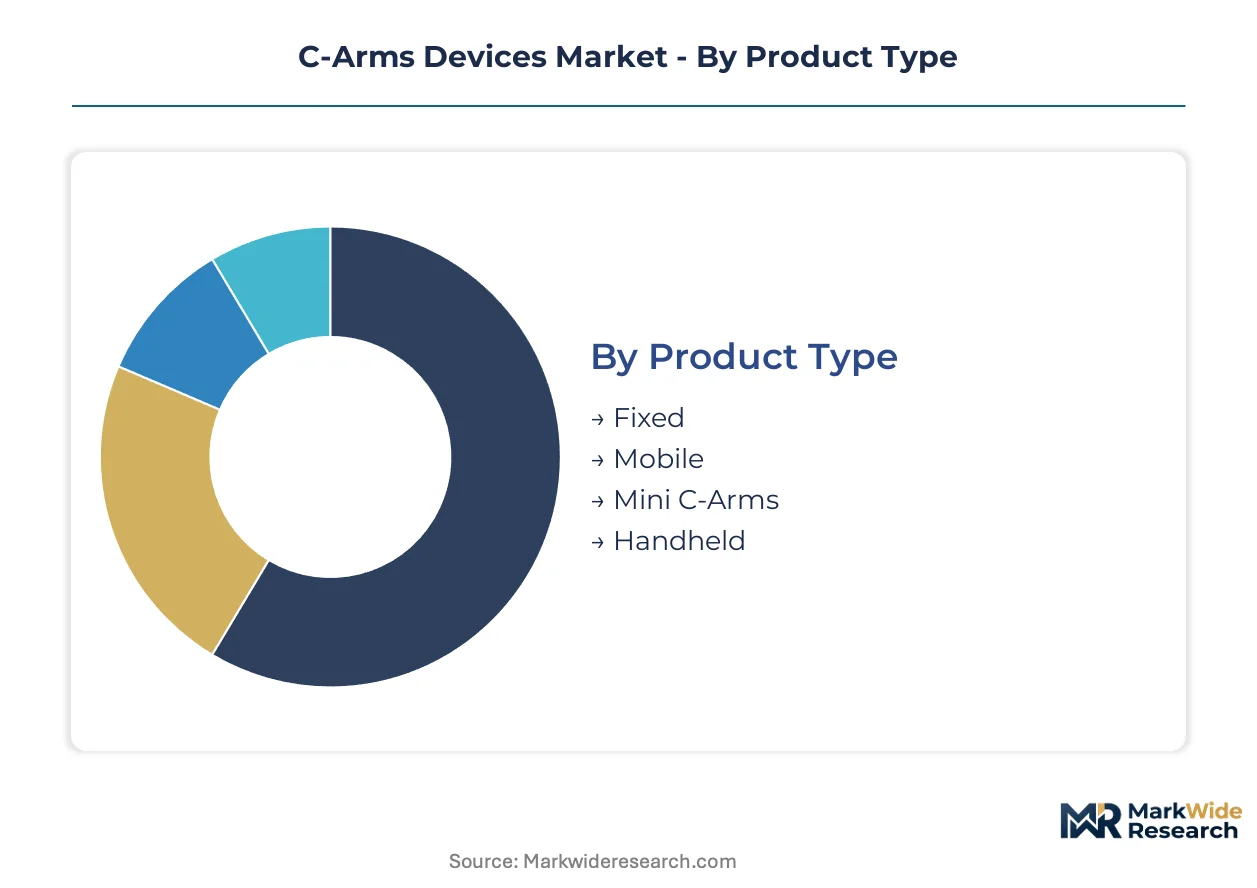
C-Arms devices fragment across four structural dimensions that determine procurement priorities and vendor positioning. Capital allocation, workflow requirements, and regulatory compliance burdens vary sharply across these boundaries.
Product Type:
Capital-intensity separates mobile configurations from fixed-room installations by a factor of three to five in upfront equipment expenditure.
- Fixed:Ceiling-mounted or floor-anchored gantries deliver the highest power output and image resolution for complex cardiac and neurointerventional suites. Demand concentrates in Germany and Japan where hospital infrastructure renewal cycles favor permanent installations over flexible fleet models.
- Mobile:Motorized C-shaped arms on wheeled bases enable room-to-room deployment across surgical suites. Ambulatory surgical centers in the United States are accelerating procurement as outpatient procedural volumes climb and same-day discharge workflows dominate orthopedic and pain-management service lines.
- Mini C-Arms:Compact units with reduced field-of-view target extremity imaging in hand surgery and podiatry clinics. Lower radiation output suits office-based settings with limited shielding infrastructure.
- Handheld:Battery-operated portable units for battlefield medicine and remote emergency response. Japanese manufacturers are advancing detector miniaturization under PMDA fast-track pathways for breakthrough devices.
Mobile systems absorb the bulk of installed capacity; handheld configurations are expanding most quickly.
End User:
Procurement authority and service contract structures diverge sharply between consolidated hospital networks and fragmented outpatient operators.
- Hospitals:Integrated delivery networks leverage centralized capital committees to unbundle equipment purchases from manufacturer-captive service agreements. Orthopedic service lines show the most aggressive contract disintermediation as procedure volumes shift to ambulatory settings.
- Surgical Centers:Freestanding facilities prioritize fleet flexibility and room turnover efficiency over maximum image quality. CMOS flat-panel detector technology is unifying low-dose fluoroscopy with high-resolution radiography to maximize capital utilization across diverse procedure types.
- Imaging Clinics:Dedicated diagnostic operators face compressed reimbursement margins that favor refurbished digital systems over new analog platforms.
- Emergency Departments:Trauma bays require rapid-deployment mobile units with sterile draping protocols for immediate intraoperative use.
Hospitals retain the largest installed base; surgical centers are gaining share fastest in annual procurement volume.
Technology:
Detector architecture determines maintenance burden, radiation dose profiles, and interoperability with hospital PACS infrastructure.
- Digital:Flat-panel CMOS and amorphous silicon detectors deliver real-time imaging with reduced patient dose and eliminate vacuum-tube maintenance. Replacement demand is accelerating as analog image intensifier systems face obsolescence and higher service costs in aging installed bases.
- Analog:Legacy image intensifier tubes persist in budget-constrained facilities but suffer from geometric distortion and limited dynamic range. Germany and Japan show the steepest replacement curves as regulatory pressure mounts for dose reporting compliance.
- Fluoroscopy:Continuous X-ray beam modulation enables real-time surgical navigation. Cardiovascular application segments command premium positioning due to electrophysiology procedure complexity and heightened FDA scrutiny of dose-area product validation.
- Image Intensification:Vacuum-tube technology for low-light amplification is restricted to secondary markets and developing regions with limited digital infrastructure penetration.
Digital platforms dominate new shipments; fluoroscopy capabilities capture the steepest margin premiums.
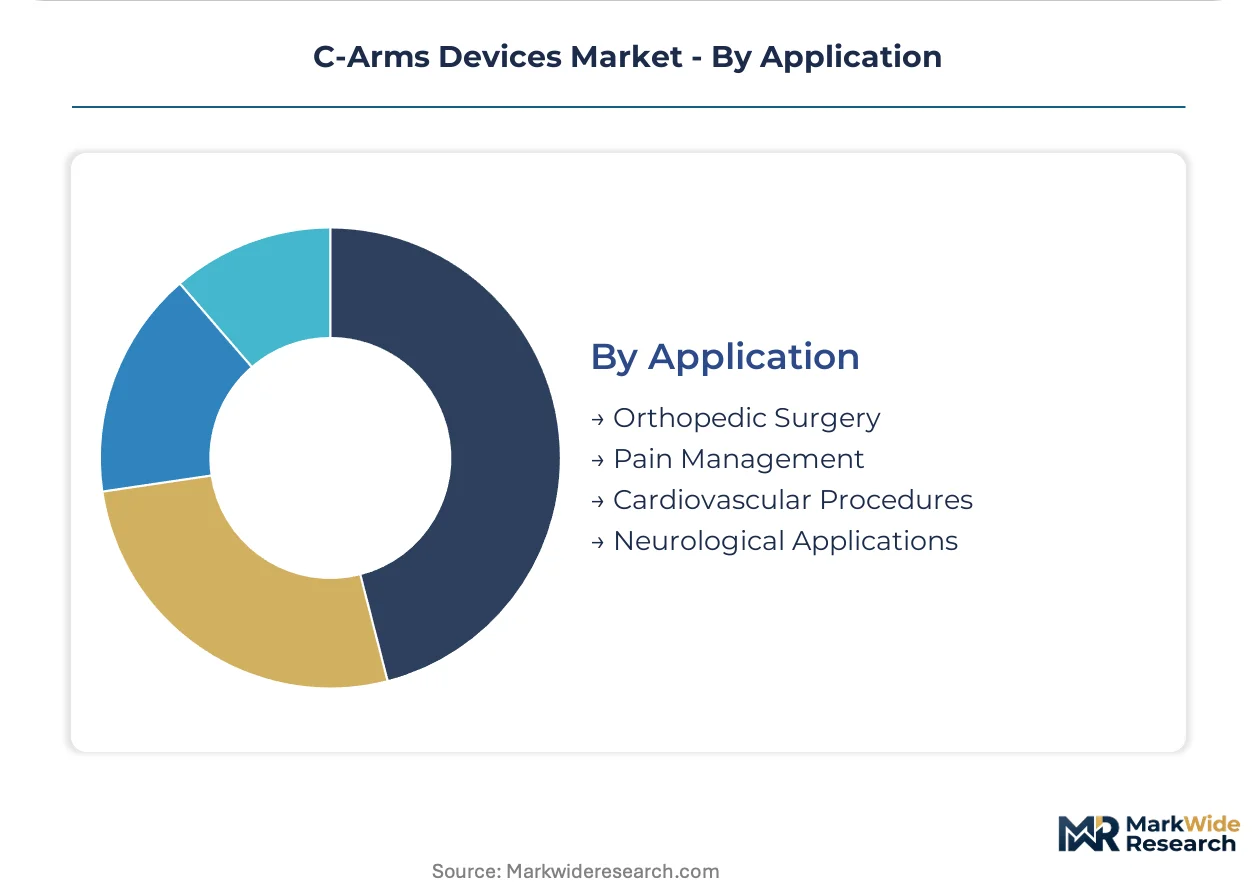
Application:
Procedure reimbursement rates and clinical outcome requirements shape equipment specification priorities across surgical specialties.
- Orthopedic Surgery:Trauma fixation, joint replacement, and spine instrumentation rely on fluoroscopic guidance for hardware placement accuracy. Mobile C-Arms are displacing fixed-room installations as ambulatory surgical centers capture volume from hospital inpatient settings.
- Pain Management:Epidural injections and nerve blocks require low-dose intermittent imaging. Outpatient migration in the United States is driving compact mobile unit procurement with simplified operator interfaces.
- Cardiovascular Procedures:Electrophysiology and interventional cardiology demand the highest frame rates and resolution. Japan's PMDA has tightened radiation dose reporting requirements, imposing comprehensive validation data submission for all new device registrations in this segment.
- Neurological Applications:Cerebrovascular and spinal interventions face substitution pressure from interventional MRI for soft-tissue visualization in complex procedures.
Orthopedic surgery accounts for the largest procedure volume; cardiovascular applications command the highest equipment price points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for C-Arms devices clusters in Germany and Japan, while the United States absorbs the dominant share of installed system consumption. Hospital infrastructure renewal cycles and ambulatory surgical center expansion create divergent demand profiles across major markets.
United States
Ambulatory surgical centers in Florida and Texas are accelerating mobile C-Arm procurement as orthopedic and pain-management volumes migrate from inpatient settings. FDA 510(k) premarket notification pathways enable faster clearance timelines for iterative device modifications. The Southeast corridor from Atlanta to Miami shows concentrated fleet expansion as same-day discharge workflows dominate service line economics.
Germany
Hospital infrastructure renewal cycles in Bavaria and North Rhine-Westphalia favor fixed-room installations with premium digital detector configurations. EU MDR recertification requirements impose stricter clinical evidence obligations, extending time-to-market for European launches. The Munich-Stuttgart industrial corridor hosts concentrated engineering talent for fluoroscopy tube and flat-panel detector development.
Japan
Aging surgical suites in Tokyo and Osaka drive replacement demand as analog image intensifier systems face obsolescence. PMDA tightened radiation dose reporting requirements under revised ministerial ordinances, mandating comprehensive dose-area product validation. The Chubu region around Nagoya anchors domestic manufacturing for miniaturized detector components.
India
Diagnostic imaging penetration remains below 15% in tier-2 cities such as Pune and Jaipur, creating whitespace for mobile C-Arm deployment in multi-specialty clinics. CDSCO medical device regulations are converging toward global standards under revised Medical Device Rules. The Delhi-NCR cluster shows early concentration of refurbished digital system imports serving budget-constrained facilities.
United Kingdom
NHS capital allocation committees are unbundling service contracts from equipment purchases, treating maintenance as competitively bid commodities. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR clinical evidence standards. The Greater Manchester and West Midlands regions show concentrated orthopedic service line expansion driving mobile unit procurement.
C-Arms Devices Market Competitive Environment
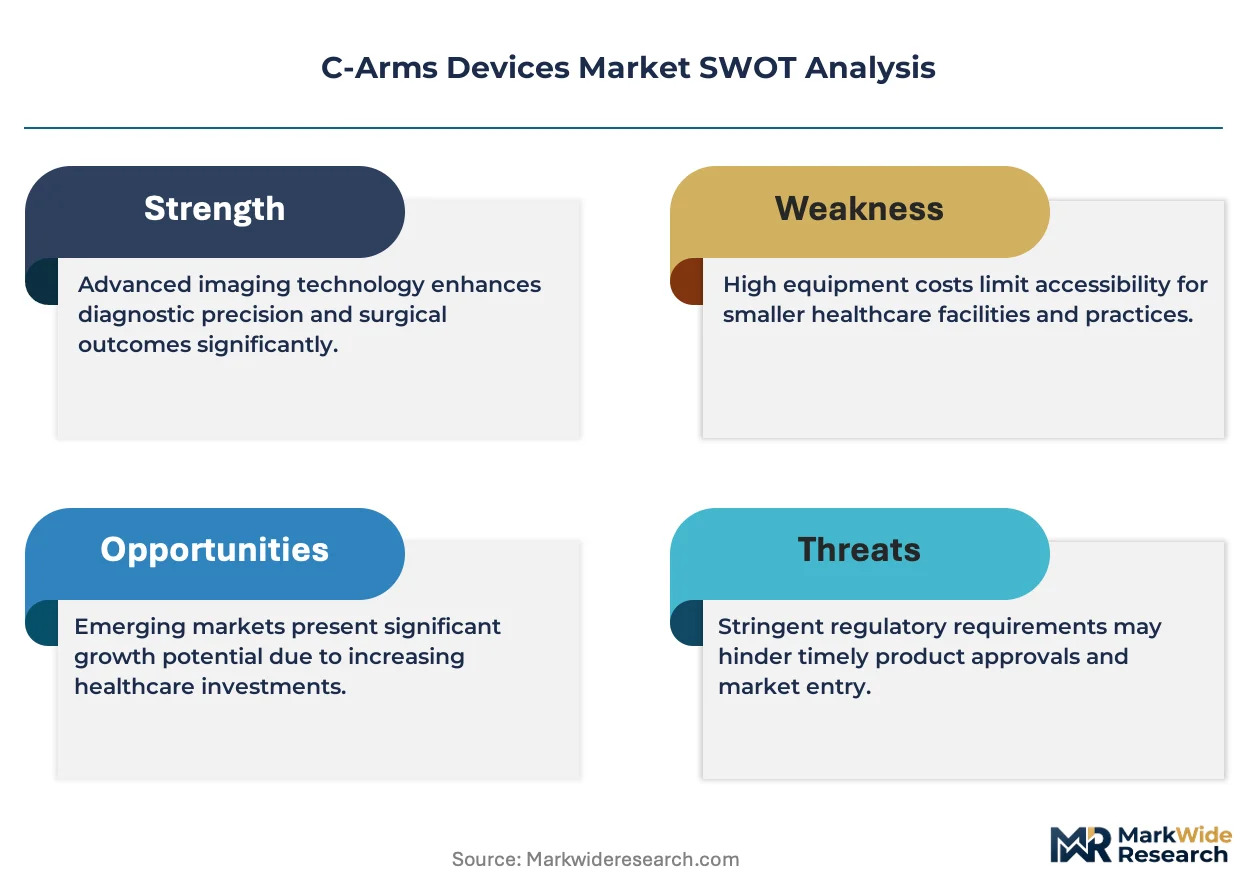
Top-tier vendors anchor the premium digital fluoroscopy segment, while mid-scale specialists and regional fabricators occupy distinct competitive tiers. The vendor base stratifies across three structural archetypes: diversified medical technology conglomerates with deep installed-base relationships, dedicated imaging specialists with focused fluoroscopy R&D pipelines, and emerging regional players leveraging cost-advantaged manufacturing. Competitive positioning depends on regulatory clearance velocity and service contract density rather than hardware differentiation alone. M&A activity concentrates on detector technology acquisitions and software platform integration capabilities.
Among diversified health technology conglomerates, GE Healthcare exemplifies the installed-base defense archetype through dense North American hospital network relationships. Siemens Healthineers occupies a position representing the integrated R&D-to-clinical workflow model, leveraging fluoroscopy technology pipelines for image-guided surgery convergence. Ziehm Imaging anchors the dedicated mobility-specialist tier, exemplifying focused engineering depth in motorized C-arm configurations for ambulatory settings.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Ziehm Imaging |
| Canon Medical Systems |
| Fujifilm |
| Hologic |
| Shimadzu Corporation |
| Konica Minolta |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees unbundling service contracts from equipment purchases are forcing manufacturers to absorb margin compression while maintaining specialized engineering talent for fluoroscopy tube production. This demand-side shift toward competitively bid maintenance commodities concentrates pricing power with buyers who can aggregate fleet volumes across integrated delivery networks.
Pricing Analysis
Short lead-time premiums for xenon short-arc lamps and flat-panel detector modules now dominate procurement negotiations as ambulatory surgical centers prioritize rapid fleet deployment over cost minimization. Three-tier pricing structure across premium digital fluoroscopy, standard CMOS detector configurations, and economy analog platforms separates cardiovascular application segments from orthopedic and pain-management service lines. Pricing pressure stems from EU MDR compliance cost absorption as vendors extend clinical evidence generation timelines without passing full burden to list prices. Surgical centers exhibit the highest price sensitivity as they compete on procedure throughput metrics, while academic medical centers prioritize image resolution specifications over unit economics.
Supply Chain Analysis
Specialized biomedical engineering talent scarcity in Germany and Japan constrains manufacturing scale-up for fluoroscopy tube assemblies and detector calibration facilities. Component sourcing concentrates in the Munich-Stuttgart corridor for high-voltage generator subsystems and the Chubu region around Nagoya for CMOS sensor miniaturization. Raw material dependencies include rare-earth phosphors for scintillator layers, high-purity tungsten for X-ray tube anodes, and precision-machined aluminum for C-arm gantry structures. Single-source vulnerability for xenon short-arc lamp supply creates input cost volatility when specialty manufacturers face production constraints. Distribution runs through manufacturer-direct hospital contracting in North America and regional distributor networks serving fragmented clinic infrastructure in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Xenon short-arc lamp manufacturing capacity constraints prop pricing power for vendors with captive supply relationships or long-term offtake agreements with specialty component producers.
For Market Incumbents: Cement installed-base defense through dense service contract penetration in orthopedic service lines before ambulatory surgical center procurement committees complete vendor rationalization. Accelerate backward integration into flat-panel detector calibration capabilities to reduce exposure to CMOS sensor supply concentration. Prioritize FDA 510(k) pathway efficiency for iterative software enhancements that differentiate premium digital platforms from emerging economy-tier competitors. For New Entrants and Emerging Players: The price-point gap between premium cardiovascular fluoroscopy systems and economy analog configurations creates entry space for mid-tier CMOS hybrid platforms targeting pain-management clinics. India's tier-2 cities offer the most penetrable geography given sub-15% diagnostic imaging penetration and converging CDSCO regulatory standards. Pursue refurbished digital system certification as a go-to-market angle that bypasses capital intensity barriers for budget-constrained multi-specialty clinics. For Investors and Strategic Acquirers: The window for entry favors detector technology specialists with proprietary scintillator formulations or radiation dose reduction algorithms eligible for Japan's PMDA Sakigake fast-track designation. Long-term viability hinges on software-defined imaging convergence rather than hardware commoditization. Monitor interventional MRI substitution rates in neurosurgical applications as the critical inflection signal for C-Arm fluoroscopy demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend European launch timelines by 12-18 months for non-compliant vendors. |
| Hospital System Partnership | Integrated delivery network contracting committees unbundle equipment from service agreements, compressing manufacturer-captive revenue. |
| Software Companion Development | AI-enhanced anatomical recognition integration unifies preoperative planning with intraoperative fluoroscopy guidance workflows. |
| Reimbursement Strategy | Outpatient procedure migration in United States ambulatory surgical centers shifts procurement authority toward fleet-flexibility metrics. |
| FDA Submission | Premarket notification pathway efficiency accelerates commercialization of iterative detector modifications and dose reduction algorithms. |
Study Parameters
FDA 510(k) clearance databases, EU MDR notified body submissions, and hospital procurement contract filings formed the secondary backbone for regulatory pathway and pricing structure validation. Primary interviews with biomedical engineering directors, GPO contracts managers, ambulatory surgical center administrators, and fluoroscopy equipment service technicians combined with secondary triangulation to reconstruct installed-base replacement cycles and fleet deployment patterns. Bottom-up segmentation modeling across product type, end user, technology, and application dimensions anchored volume estimates, while top-down cross-validation against customs trade data and manufacturer revenue disclosures ensured consistency.
Bottom-up demand modeling tracked mobile versus fixed C-Arm configurations across United States, Germany, Japan, India, and United Kingdom markets, while top-down supply-side analysis calibrated production capacity constraints against xenon lamp and detector component lead times. Segmentation dimensions included detector architecture, procedural application, end-user facility type, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis of aging analog installed bases and outpatient procedural migration trends. Industry-specific forecast inputs incorporated PMDA radiation dose reporting compliance burdens and CDSCO regulatory convergence timelines.
Inputs from FDA premarket notification databases and EU MDR clinical evaluation reports were available through the study window; gaps in real-time hospital capital expenditure commitments introduce uncertainty bands around near-term procurement volume estimates. Forecasts reflect assumptions regarding EU MDR recertification timeline adherence and interventional MRI substitution rates in neurological applications. Material deviation in xenon short-arc lamp supply availability or PMDA fast-track designation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Incubator Devices Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Intubation Tubes Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Global Assistive Listening Device Market