
 Toe Fixation System Market | 2026-2036
Toe Fixation System Market Size, Share, and Industry Trends Forecast 2026-2036
Toe Fixation System Market Analytics
3D-printed patient-specific implants and biodegradable magnesium alloys is rewriting surgical planning workflows in toe fixation. Stryker Corporation leverages its additive manufacturing footprint to produce anatomically matched plates and screws. Johnson & Johnson (DePuy Synthes) anchors its position through deep R&D spending on resorbable fixation platforms. Arthrex competes by dominating the minimally invasive hammertoe correction segment with proprietary compression screw systems.
A toe fixation system comprises orthopedic implants—typically screws, plates, pins, or external fixators manufactured from titanium, stainless steel, polymer, or bio-composite materials—designed to stabilize phalangeal and metatarsophalangeal joints following corrective osteotomy or arthrodesis. These devices maintain bone alignment under physiological loads of 200–400 N during gait cycles while permitting controlled micromotion for secondary bone healing. Plates and screws currently occupy the largest revenue pool due to their versatility across hallux valgus and hammertoe indications, while biodegradable solutions represent the fastest-expanding technology segment as surgeons seek to eliminate secondary hardware removal procedures. Titanium-based constructs sustain premium pricing over stainless steel alternatives owing to superior biocompatibility and reduced stress shielding in periprosthetic bone.
The FDA's 510(k) premarket notification framework governs commercial entry in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for implantable devices across European markets. Japan's Pharmaceutical and Medical Devices Agency (PMDA) enforces Japan Industrial Standards (JIS) for metallic implant materials, creating additional compliance layers for foreign manufacturers. Stakeholders must monitor evolving biodegradability standards and reimbursement parity between outpatient and inpatient surgical settings as procedure migration accelerates.
Market Dynamics
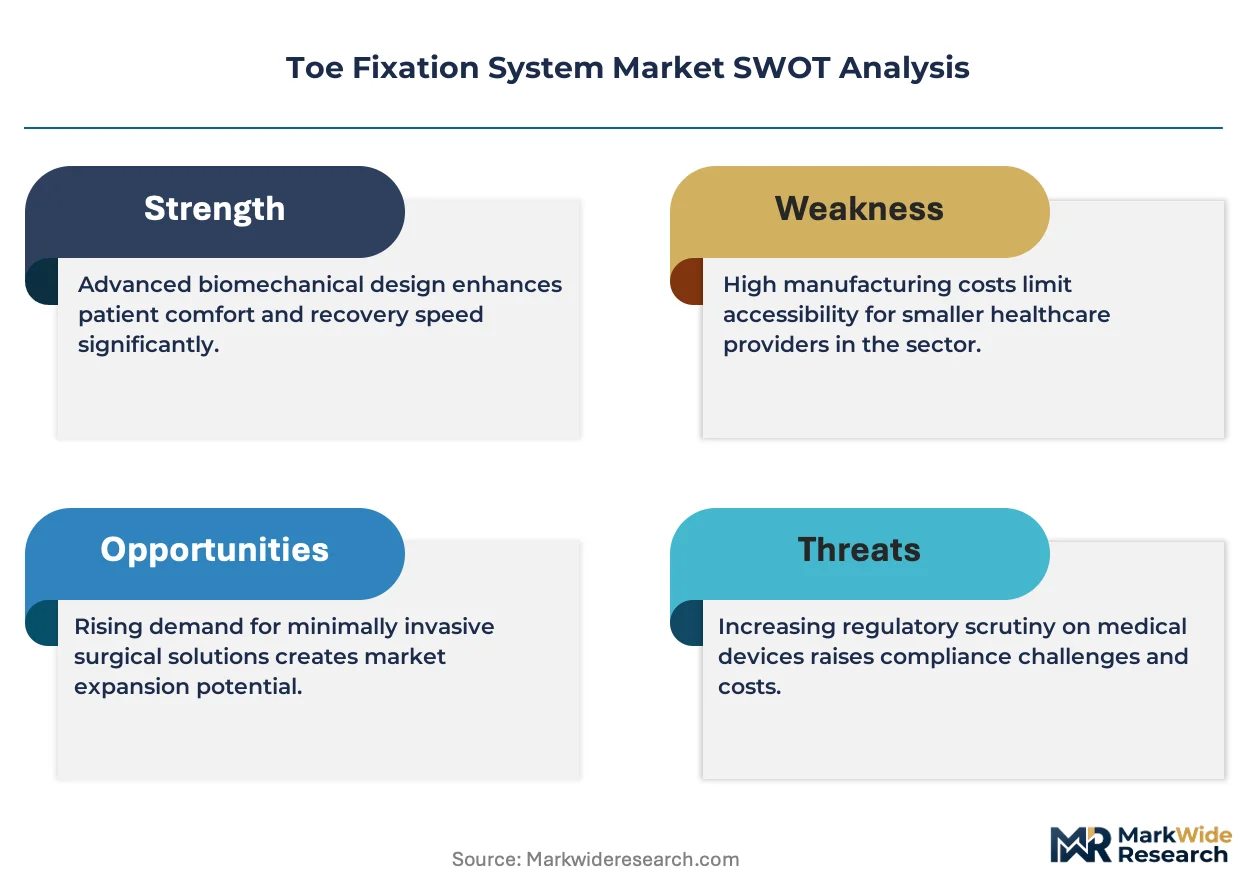
The migration of hallux valgus and hammertoe procedures from inpatient hospitals to ambulatory surgical centers is compressing purchasing cycles and forcing manufacturers to reconfigure kit economics for outpatient reimbursement codes.
Growth Catalysts
- 510(k) Clearance Pathway:The FDA's streamlined premarket notification framework accelerates commercial entry for titanium plate and screw systems, reducing time-to-revenue for orthopedic implant developers.
- Ambulatory Surgical Center Expansion:Outpatient facilities in the United States are capturing an expanding share of toe correction volume, driving demand for compact, single-use fixation kits optimized for same-day discharge protocols.
- Magnesium Alloy Biodegradation:Resorbable fixation platforms eliminate secondary hardware removal surgeries, aligning surgeon preference with patient demand for reduced procedural burden.
Market Restraints
- Titanium Feedstock Concentration:Sponge and mill product supply chains concentrate among a limited set of aerospace-qualified suppliers, exposing implant manufacturers to price volatility and allocation risk.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation imposes stricter post-market surveillance and clinical data requirements for implantable devices, extending certification timelines and elevating compliance costs.
- Stainless Steel Substitution Pressure:Cost-conscious procurement committees in emerging markets favor 316L stainless steel constructs over titanium alternatives, compressing average selling prices in price-sensitive segments.
Strategic Opportunities
- Japan's Aging Demographic:PMDA's alignment with JIS standards for metallic implants creates a defined regulatory pathway for foreign manufacturers targeting the world's oldest population and elevated hallux valgus prevalence.
- 3D-Printed Patient-Specific Implants:Additive manufacturing convergence with preoperative CT planning enables anatomically matched osteotomy plates, commanding premium pricing in complex revision cases.
- Biodegradable Polymer Hybrid Systems:PLLA-TCP composite screws offer intermediate resorption profiles between permanent metal and rapid magnesium dissolution, opening indications in pediatric and high-activity adult populations.
Industry Challenges
- Biomechanical Validation Talent Scarcity:Finite element modeling expertise for phalangeal load distribution remains concentrated among academic medical centers and specialized contract research organizations.
- Supply Chain Reconfiguration Friction:Manufacturers face capital intensity in qualifying secondary forging and machining sources capable of meeting ASTM F136 titanium specifications for implant-grade bar stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toe Fixation System Market |
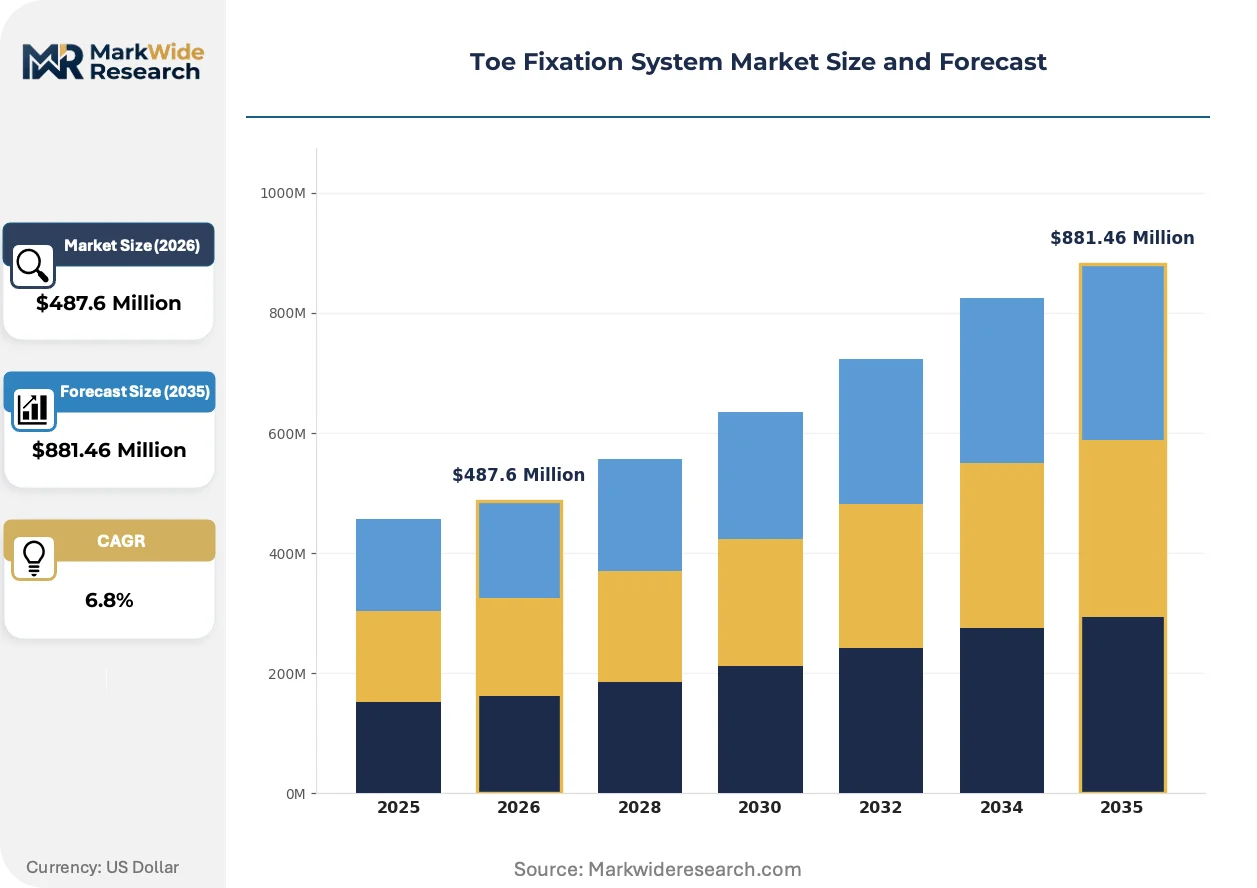
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Plates, External Fixators, Pins Material: Stainless Steel, Titanium, Polymer, Bio-Composite End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Sports Facilities Technology: Minimal Invasive, Traditional Surgery, 3D Printing, Biodegradable Solutions |
| Companies Covered | Johnson & Johnson (DePuy Synthes), Wright Medical Group, Arthrex, Enovis Corp., Acumed, Stryker Corporation, Smith+Nephew, Novastep, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toe Fixation System Market Evolving Landscape
Digital surgical planning and material science advances are converging to compress operative time and expand the addressable patient population beyond traditional deformity thresholds.
Biodegradable magnesium alloy screws with controlled corrosion rates are rendering obsolete the standard practice of scheduled hardware removal surgeries in younger, active patients. Ambulatory surgical centers in Germany and Japan are adopting these systems at accelerating pace as reimbursement frameworks evolve to recognize single-procedure cost advantages. The technology is compressing total episode costs while eliminating revision surgery capacity constraints.
The EU Medical Device Regulation's intensified clinical evidence requirements for implantable devices are forcing manufacturers to maintain larger safety databases and extend post-market surveillance obligations. This regulatory shift elevates barriers for mid-tier competitors lacking dedicated regulatory affairs infrastructure. High-volume hallux valgus plate systems face the steepest compliance cost escalation as notified bodies apply enhanced scrutiny to biomechanical performance claims.
Surgeon buying committees are consolidating vendor relationships around full-procedure kit suppliers capable of delivering plates, screws, and disposable instrumentation through single-source contracts. Independent distributors and specialized orthopedic sales agents are losing share to direct manufacturer representation in major metropolitan markets. The United States exhibits the most pronounced concentration as health system purchasing organizations negotiate enterprise pricing across multiple surgical sites.
Toe Fixation System Market Segmentation
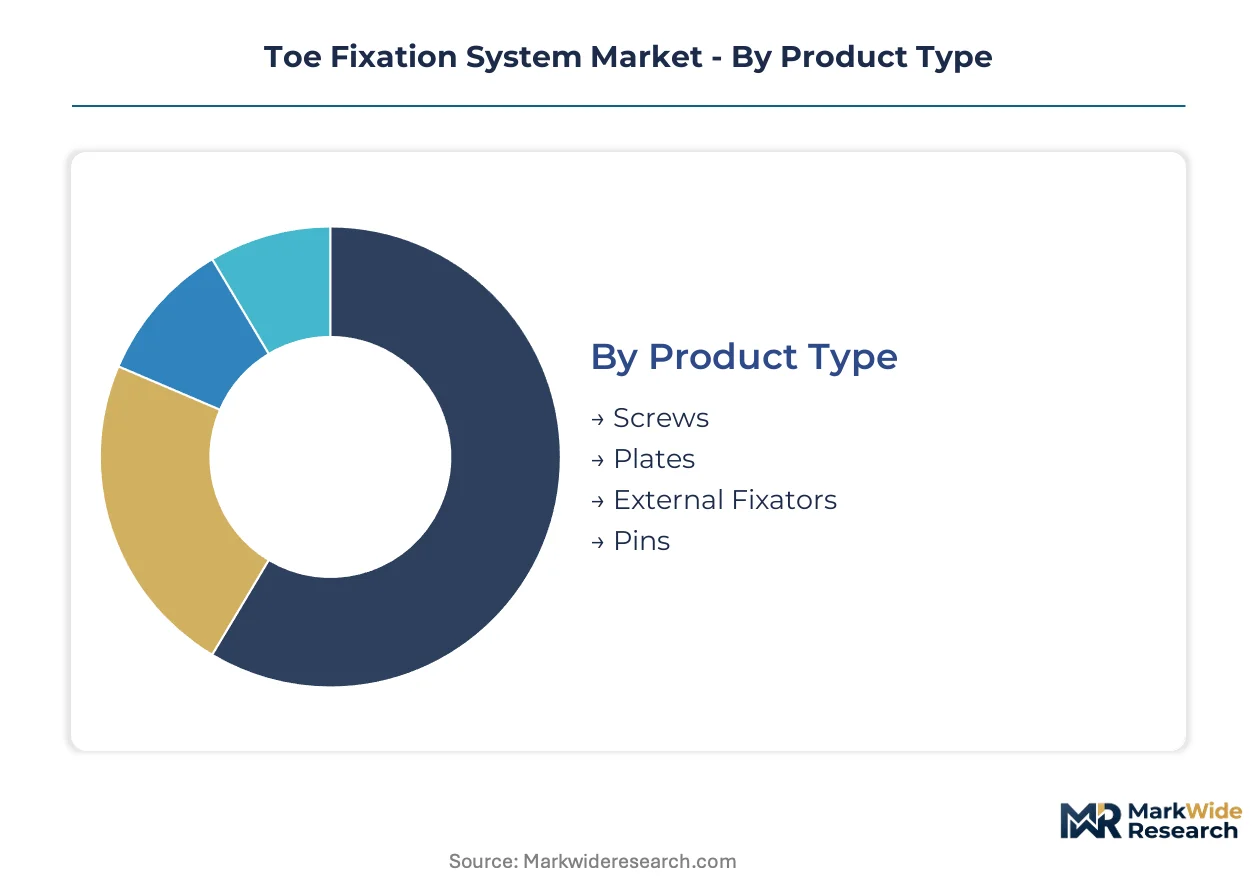
Segmentation in toe fixation systems reveals how material science, surgical setting, and procedural approach reshape procurement patterns. Manufacturers configure kit economics and service models around these divides.
Product Type:
After-sales service intensity varies sharply across implant categories, with revision-prone segments demanding dedicated sales engineering support.
- Plates:Anatomically contoured titanium or stainless steel constructs stabilize metatarsophalangeal joints following corrective osteotomy. Demand concentrates in ambulatory surgical centers across the United States and Germany, where hallux valgus correction volume is migrating from inpatient settings.
- Screws:Compression and cannulated screw systems deliver rigid internal fixation for phalangeal arthrodesis. Japanese orthopedic clinics favor these for hammertoe correction, driven by PMDA-cleared titanium constructs that minimize stress shielding in periprosthetic bone.
- External Fixators:Ring and wire configurations manage complex revision cases and open fractures.
- Pins:Kirschner wires provide provisional stabilization in pediatric and low-load applications.
By volume, screws lead. By growth pace, plates are ahead.
Material:
Cost tier stratification separates premium biocompatible metals from commodity stainless alternatives in procurement committee evaluations.
- Titanium:ASTM F136 implant-grade bar stock delivers superior biocompatibility and osseointegration for permanent fixation. United States hospitals pay premiums for these constructs, particularly in revision cases where stress shielding risks dominate surgeon preference.
- Stainless Steel:316L grade offers cost-effective rigidity for standard hallux valgus procedures. Emerging market procurement in India and Brazil favors these alternatives, compressing average selling prices in price-sensitive segments.
- Polymer:PEEK and UHMWPE components provide radiolucent imaging compatibility.
- Bio-Composite:PLLA-TCP blends target pediatric populations requiring resorbable fixation.
Titanium commands the highest unit economics. Bio-composite materials are climbing the fastest.
End User:
Customer type determines kit configuration complexity, from sterilization protocols to disposable instrumentation requirements.
- Hospitals:Inpatient facilities manage complex deformity corrections and revision surgeries requiring comprehensive implant inventories. German university hospitals anchor demand for 3D-printed patient-specific plates in severe hallux valgus cases.
- Orthopedic Clinics:Specialized foot and ankle centers drive adoption of minimally invasive screw systems. United States-based ambulatory clinics are capturing migration volume from hospital outpatient departments.
- Rehabilitation Centers:Post-operative facilities coordinate hardware removal scheduling.
- Sports Facilities:Athletic medicine programs prioritize rapid return-to-play protocols.
Hospitals retain the largest absolute volume. Orthopedic clinics are expanding most quickly.
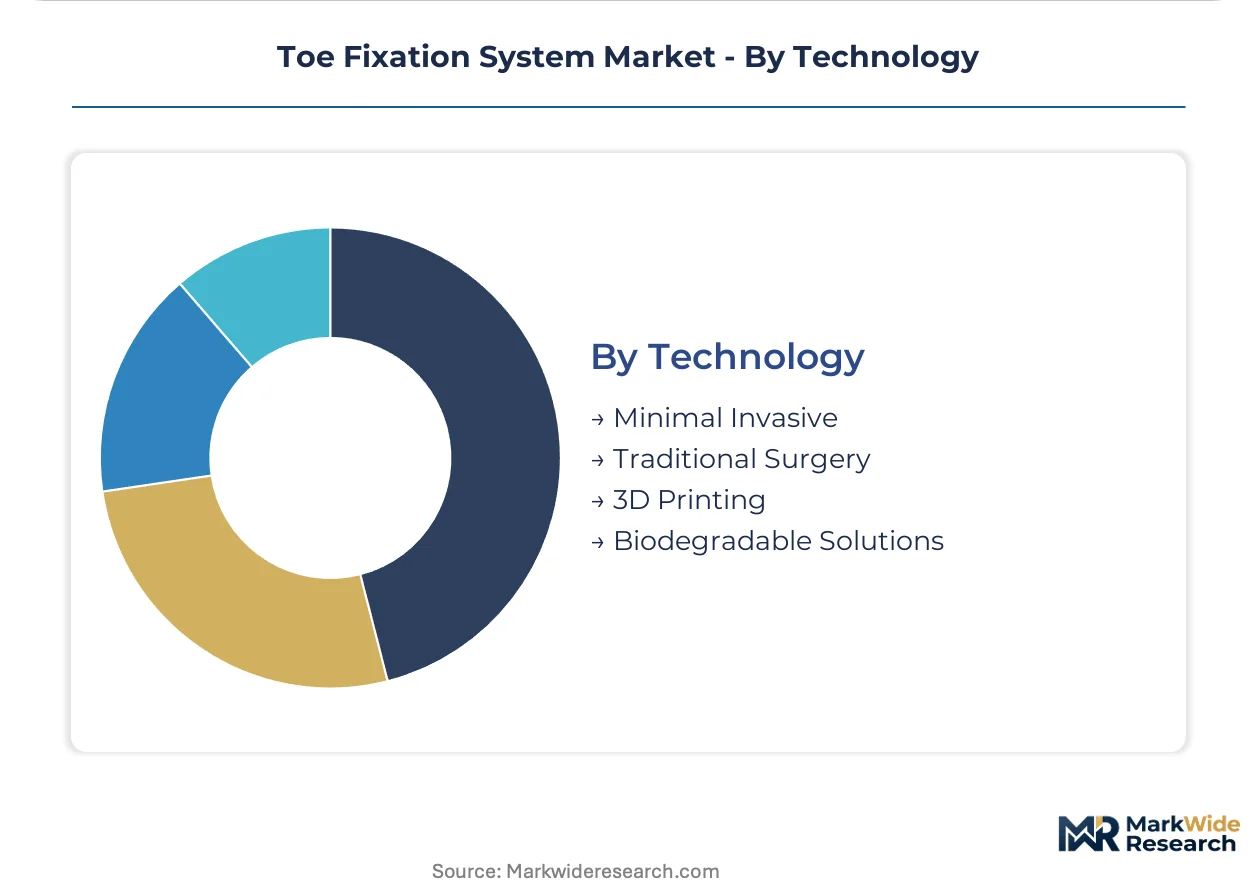
Technology:
Maturity curves separate established open procedures from emerging material platforms still accumulating clinical evidence.
- Traditional Surgery:Open osteotomy and arthrodesis techniques with standard plate-and-screw fixation dominate current procedural volume. Japanese surgical training programs continue emphasizing these approaches for resident certification.
- Biodegradable Solutions:Magnesium alloy screws with controlled corrosion rates eliminate secondary hardware removal. German ambulatory centers are adopting these systems as statutory health insurance frameworks recognize single-procedure cost advantages.
- Minimal Invasive:Percutaneous techniques reduce soft tissue disruption.
- 3D Printing:Additive manufacturing enables patient-specific osteotomy guides and plates.
Traditional surgery holds the volume base. Biodegradable solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic manufacturers export titanium plate systems to United States ambulatory surgical centers, establishing the primary trade-flow corridor in toe fixation devices. Japan's PMDA-cleared constructs feed into Asian markets through Singapore distribution hubs. Cross-border procurement patterns concentrate premium implant sourcing in these three manufacturing-origin countries.
United States
Ambulatory surgical centers in Florida and Texas are capturing hallux valgus procedure volume from hospital outpatient departments. The FDA's 510(k) premarket notification framework accelerates commercial entry for titanium screw systems. Minneapolis and Memphis anchor distribution networks for domestic manufacturers serving these outpatient migration trends.
Germany
University hospitals in Munich and Berlin drive demand for 3D-printed patient-specific osteotomy plates in complex revision cases. The EU Medical Device Regulation imposes stricter clinical evidence requirements for implantable devices, extending certification timelines. Baden-Württemberg's precision machining clusters supply ASTM F136 titanium bar stock to domestic implant fabricators.
Japan
Aging demographics in Tokyo and Osaka elevate hallux valgus prevalence among the world's oldest population. PMDA enforces Japan Industrial Standards for metallic implant materials, creating compliance layers for foreign manufacturers. Nagoya's medical device manufacturing corridor concentrates domestic production of cannulated screw systems for hammertoe correction.
China
Tier-one hospitals in Shanghai and Beijing are adopting minimally invasive fixation techniques for phalangeal arthrodesis. NMPA's medical device registration requirements govern commercial entry for imported titanium constructs. Suzhou's biomedical industrial park hosts domestic manufacturers scaling production of cost-competitive stainless steel alternatives.
Toe Fixation System Market Competitive Landscape
On the supply side, the industry is consolidating around full-procedure kit suppliers capable of delivering plates, screws, and disposable instrumentation through single-source contracts. Three strategic archetypes dominate: diversified orthopedic conglomerates with additive manufacturing footprints, specialized foot-and-ankle device companies with proprietary compression systems, and mid-tier fabricators competing on stainless steel cost economics. M&A activity targets minimally invasive technology portfolios, while direct manufacturer representation displaces independent distributors in major metropolitan markets.
Among diversified orthopedic conglomerates, Stryker Corporation and Johnson & Johnson (DePuy Synthes) exemplify scale-driven archetypes with captive additive manufacturing capabilities. Arthrex occupies a position within the specialized foot-and-ankle tier, representing the minimally invasive fixation segment. These three anchors demonstrate how supply-side configuration separates premium-tier players from cost-competitive alternatives.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| Wright Medical Group |
| Arthrex |
| Enovis Corp. |
| Acumed |
| Stryker Corporation |
| Smith+Nephew |
| Novastep |
| Zimmer Biomet |
| Others |
Value Network & Pricing Analysis
Trans-Pacific air freight lanes from Nagoya to Memphis transmit ASTM F136 titanium bar stock at elevated rates, compressing margins for implant fabricators while amplifying price spreads between premium titanium constructs and standard stainless alternatives. This logistics corridor's cost dynamics concentrate purchasing power among ambulatory surgical center networks that negotiate volume-based kit economics.
Pricing Analysis
Next-generation biodegradable magnesium alloy screws command substantial premiums over conventional titanium plate systems, while legacy stainless steel constructs occupy the economy tier. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM certification grade and after-sales service bundling. Cost compression in the stainless tier is intensifying because procurement committees in emerging markets favor 316L alternatives. Orthopedic clinics demonstrate highest price sensitivity; revision-focused hospitals accept premium positioning.
Supply Chain Analysis
Export-control restrictions on additive manufacturing software and precision forging equipment limit technology transfer to non-allied manufacturing bases. Supply concentrates in Germany's Baden-Württemberg machining clusters, Japan's Nagoya medical device corridor, and United States titanium sponge processing facilities. Raw material flows draw from aerospace-qualified titanium suppliers, magnesium alloy foundries, and polymer composite extruders. Single-source vulnerability pervades implant-grade bar stock qualification. Distribution runs through direct manufacturer representation displacing independent orthopedic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toe fixation system market sits in early-cycle expansion as ambulatory surgical center migration accelerates procedural volume beyond traditional hospital settings. Biodegradable magnesium platforms are penetrating younger patient demographics previously excluded from permanent implant economics.
For Market Incumbents: Insulate titanium plate margins by deepening backward integration into ASTM F136 bar stock forging capacity in Germany or Japan, eliminating aerospace supplier allocation risk. Secure exclusive ambulatory surgical center kit contracts before mid-tier competitors achieve MDR compliance. Threat vectors include resorbable polymer hybrid systems and PMDA-cleared Japanese entrants targeting United States outpatient networks.
For New Entrants and Emerging Players: Build out biodegradable screw manufacturing capabilities targeting German statutory health insurance reimbursement frameworks that recognize single-procedure cost advantages. White-space availability concentrates in pediatric PLLA-TCP composite indications and complex revision cases requiring patient-specific 3D-printed osteotomy plates. Go-to-market execution hinges on surgeon training partnerships with academic medical centers possessing finite element modeling expertise.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to divest non-core foot-and-ankle portfolios lacking additive manufacturing infrastructure. Long-term viability favors platforms with captive biodegradable material science pipelines and direct ambulatory surgical center channel control. Monitor FDA 510(k) clearance velocity for magnesium alloy systems as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Platform Development | Magnesium alloy R&D eliminates secondary hardware removal surgeries, aligning with patient preference for reduced procedural burden. |
| Additive Manufacturing Footprint Expansion | Captive 3D printing enables patient-specific osteotomy plates commanding premium pricing in complex revision cases. |
| Ambulatory Surgical Center Direct Contracts | Single-source kit supply agreements displace independent distributors and lock in outpatient procedure volume migration. |
| EU MDR Certification Infrastructure | Dedicated regulatory affairs capabilities extend competitive moats as clinical evidence requirements escalate for implantable devices. |
| Japan PMDA Alignment Investment | JIS standards compliance opens access to world's oldest population with elevated hallux valgus prevalence. |
Research Methodology
Cross-validation between hospital procurement database analysis and surgeon preference surveys anchors the qualitative findings on biodegradable adoption trajectories. Primary interviews engaged orthopedic surgeons, ambulatory surgical center administrators, biomedical engineers, GPO contracts managers, and regulatory affairs specialists across United States, German, and Japanese markets. Secondary sources incorporated FDA 510(k) filings, PMDA approval records, EU MDR notified body guidance, hospital purchasing committee minutes, and ASTM material standard revisions. Bottom-up procedure volume estimates triangulated against top-down implant manufacturer revenue segmentation.
Calibration against historical titanium plate and screw shipment data validated the projection framework across product type, material grade, end-user facility, and technology maturity dimensions. CAGRs derived from segmented growth rate analysis applied to base-year market sizing, with biomechanical validation timelines and reimbursement code evolution incorporated as scenario variables. Forecast inputs included ambulatory surgical center capacity expansion trajectories, magnesium alloy corrosion rate clinical data accumulation, and 3D-printing cost curve assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by aerospace-qualified titanium suppliers would shift outcomes. Material shifts in FDA biodegradability standards or statutory health insurance reimbursement parity between inpatient and outpatient settings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laryngeal Masks Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Spherical IOL Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Global Casting Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Knee Walkers Market