
 Portable Medical Ventilators Market | 2026-2036
Portable Medical Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Medical Ventilators Market Intelligence
Aftermarket service revenue is reconfiguring margin distribution across the portable ventilator value chain. Medtronic PLC leverages its extensive field service network to capture recurring maintenance contracts. ResMed anchors its profitability through remote monitoring subscriptions that extend patient engagement beyond the initial device sale.
Portable medical ventilators are electromechanical or pneumatic devices that generate controlled airflow to support or replace spontaneous breathing, typically operating at pressure ranges of 5-40 cm H2O and tidal volumes of 50-2000 mL depending on patient classification. These devices serve acute care, sub-acute transition, and chronic home therapy applications where patient mobility or field deployment is essential. Continuous Positive Airway Pressure systems dominate the product type landscape due to their established use in sleep apnea management and lower clinical training requirements. Microprocessor-Controlled technology leads the technology dimension as algorithm-driven adaptive ventilation gains preference over pneumatic alternatives in developed markets.
FDA 510(k) premarket notification and EU MDR conformity assessment govern device approval pathways in the United States and Europe respectively, with both frameworks tightening clinical evidence requirements for software-as-a-medical-device functionalities. China's NMPA implements GB standards for respiratory device safety while accelerating review timelines for innovative emergency equipment. Stakeholders must monitor evolving cybersecurity guidance from FDA and harmonization gaps between MDR and NMPA software validation protocols to sustain multi-regional product strategies.
Market Dynamics
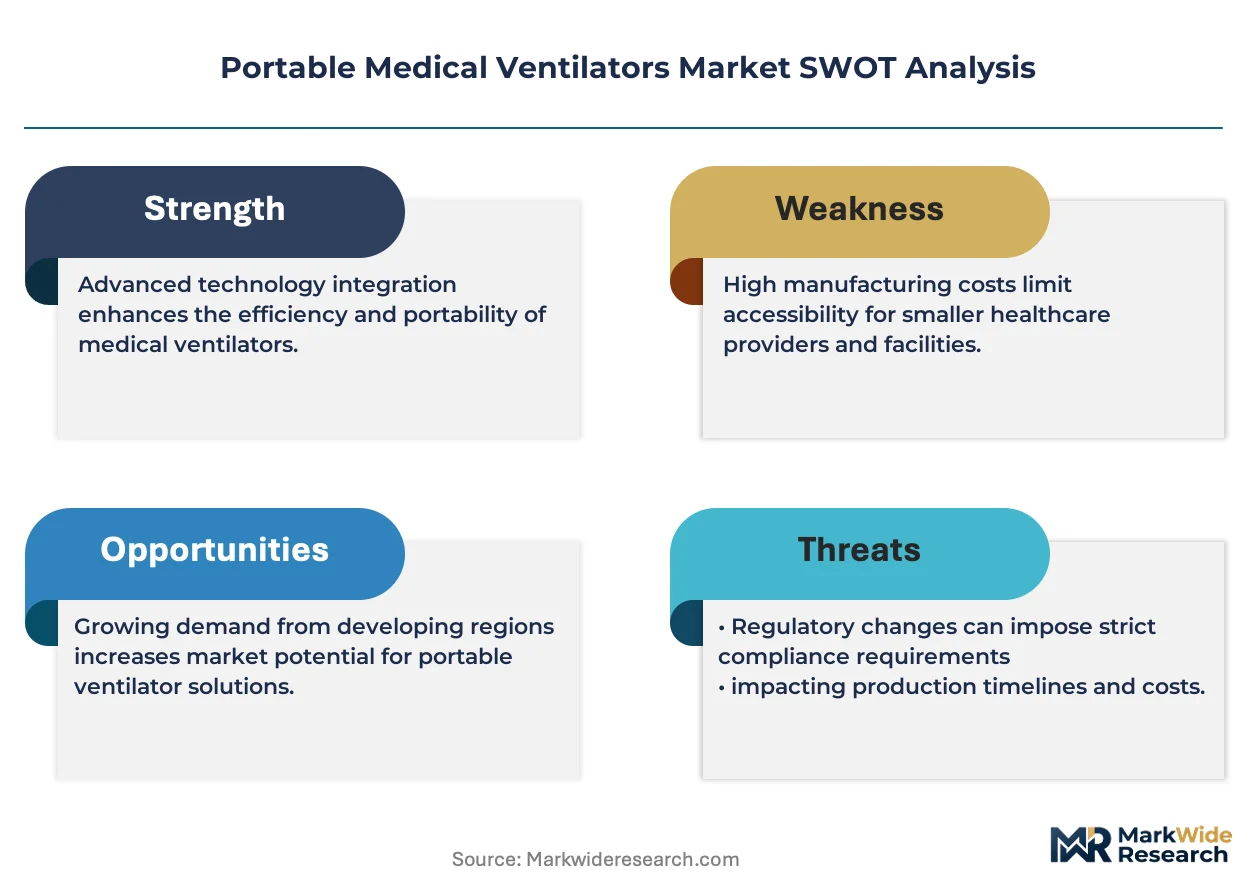
The transition from institutional to residential respiratory care is compressing device form factors while expanding software complexity requirements. Homecare reimbursement pathways are rewriting procurement specifications faster than hardware refresh cycles can accommodate.
Growth Catalysts
- Homecare reimbursement expansion:CMS and private payers in the United States are extending coverage for long-term ventilator rentals outside acute settings. This creates pull-through demand for lighter, battery-operated units.
- EU MDR emergency use provisions:Accelerated conformity assessment pathways for pandemic preparedness stockpiling are shortening time-to-market for manufacturers with established quality management systems.
- Algorithm-driven adaptive ventilation:Microprocessor-controlled systems are capturing preference in developed markets as clinical training requirements drop and patient outcomes improve.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate microcontroller fabrication for respiratory devices, creating single-source vulnerability for precision pressure sensors.
- EU MDR clinical evidence requirements:Tightened post-market surveillance obligations are extending recertification timelines and inflating regulatory compliance costs for software-as-a-medical-device functionalities.
- CPAP substitution in sleep apnea:Continuous Positive Airway Pressure systems face pricing pressure from oral appliance therapy and hypoglossal nerve stimulation implants in mild-to-moderate cases.
Strategic Opportunities
- Rural China penetration:County-level hospital upgrades under the Healthy China 2030 initiative are creating first-time demand for transport-capable ventilators in tier-3 and tier-4 cities.
- Remote monitoring convergence:Integration of cellular telemetry with cloud-based clinical decision support is enabling subscription revenue models that extend patient engagement beyond device sale.
- FEMA stockpiling mandates:United States emergency preparedness programs are creating predictable demand cycles for surge-capable portable units with extended battery autonomy.
Industry Challenges
- Embedded software validation:FDA cybersecurity guidance and EU MDR software lifecycle requirements are forcing manufacturers to restructure quality assurance teams and extend development timelines.
- Biomedical technician scarcity:Homecare deployment models require distributed field service networks, but respiratory device certification programs are not producing sufficient trained personnel for rural coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Medical Ventilators Market |
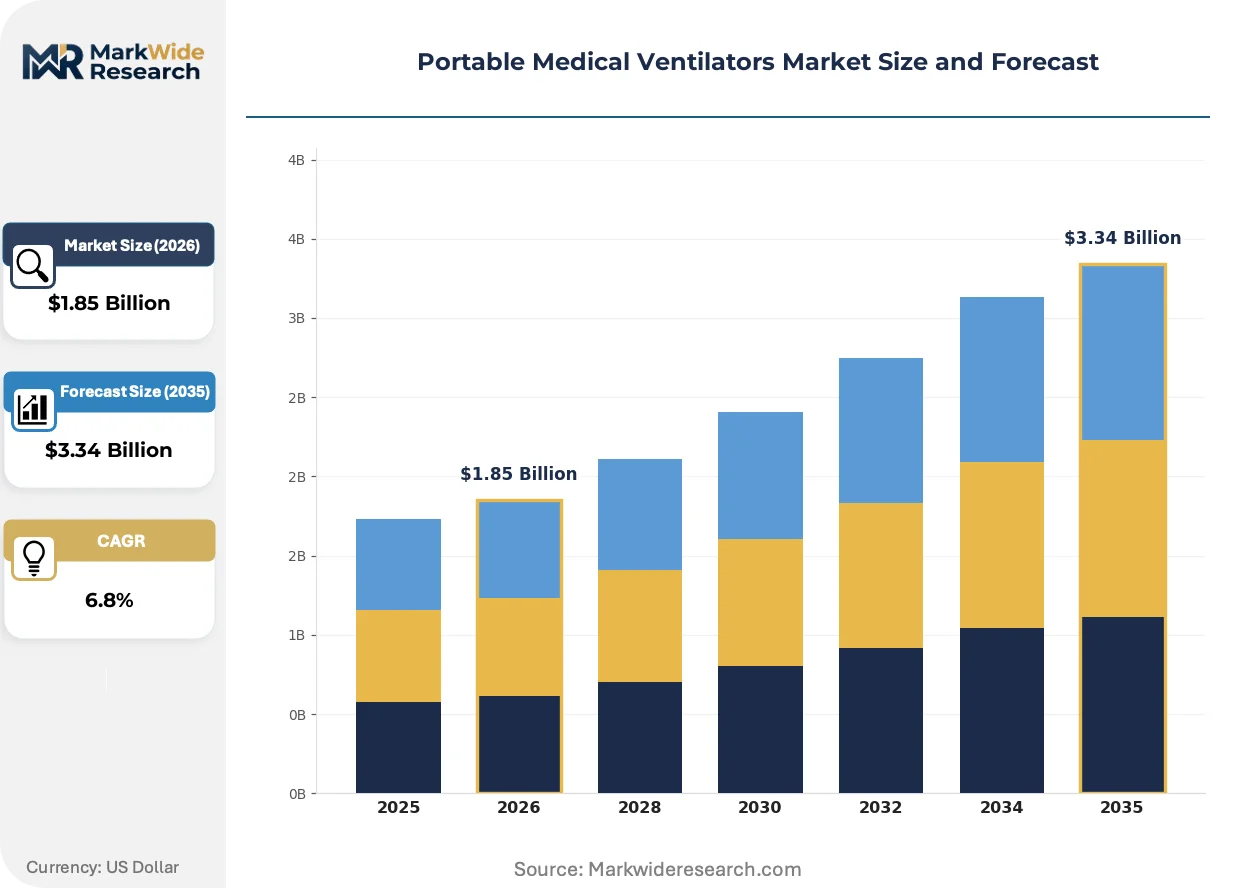
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Positive Airway Pressure, Bi-Level Positive Airway Pressure, Volume Cycle, Pressure Cycle End User: Hospitals, Homecare Settings, Emergency Services, Military Facilities Technology: Microprocessor-Controlled, Pneumatic, Electric, Hybrid Application: Respiratory Disorders, Anesthesia Support, Emergency Resuscitation, Sleep Apnea |
| Companies Covered | Medtronic PLC, ResMed, Drägerwerk AG & Co. KGaA, Vyaire Medical, GE Healthcare, Getinge AB, Hamilton Medical, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Medical Ventilators Market Strategic Shifts & Innovations
Algorithmic control architectures are displacing pneumatic logic across all patient acuity levels. Software-defined functionality is becoming the primary differentiation vector while hardware commoditizes.
Turbine-based blower systems with active noise cancellation are rendering obsolete traditional compressor-driven pneumatic circuits in homecare ventilators. Sleep apnea patients and post-acute transition users are demanding whisper-quiet operation for bedroom compliance. This acoustic performance threshold is rendering obsolete legacy platforms that cannot meet sub-30 dB specifications without mechanical redesign.
EU MDR Annex XVI expansion is capturing previously exempt wellness devices with medical claims under formal conformity assessment. Manufacturers of hybrid consumer-medical products must now maintain technical documentation and clinical evidence portfolios comparable to Class IIa devices. The software-as-a-medical-device category is experiencing the most significant compliance cost inflation as notified bodies apply MDCG guidance strictly.
Hospital procurement departments are unbundling device acquisition from service contracts and remote monitoring subscriptions. IDNs in the United States are negotiating three-year total cost of ownership agreements that separate capital equipment from recurring revenue streams. Germany's university hospitals are piloting this disaggregated purchasing model for homecare discharge planning, forcing manufacturers to restructure sales compensation and channel partnerships.
Portable Medical Ventilators Market Segmentation
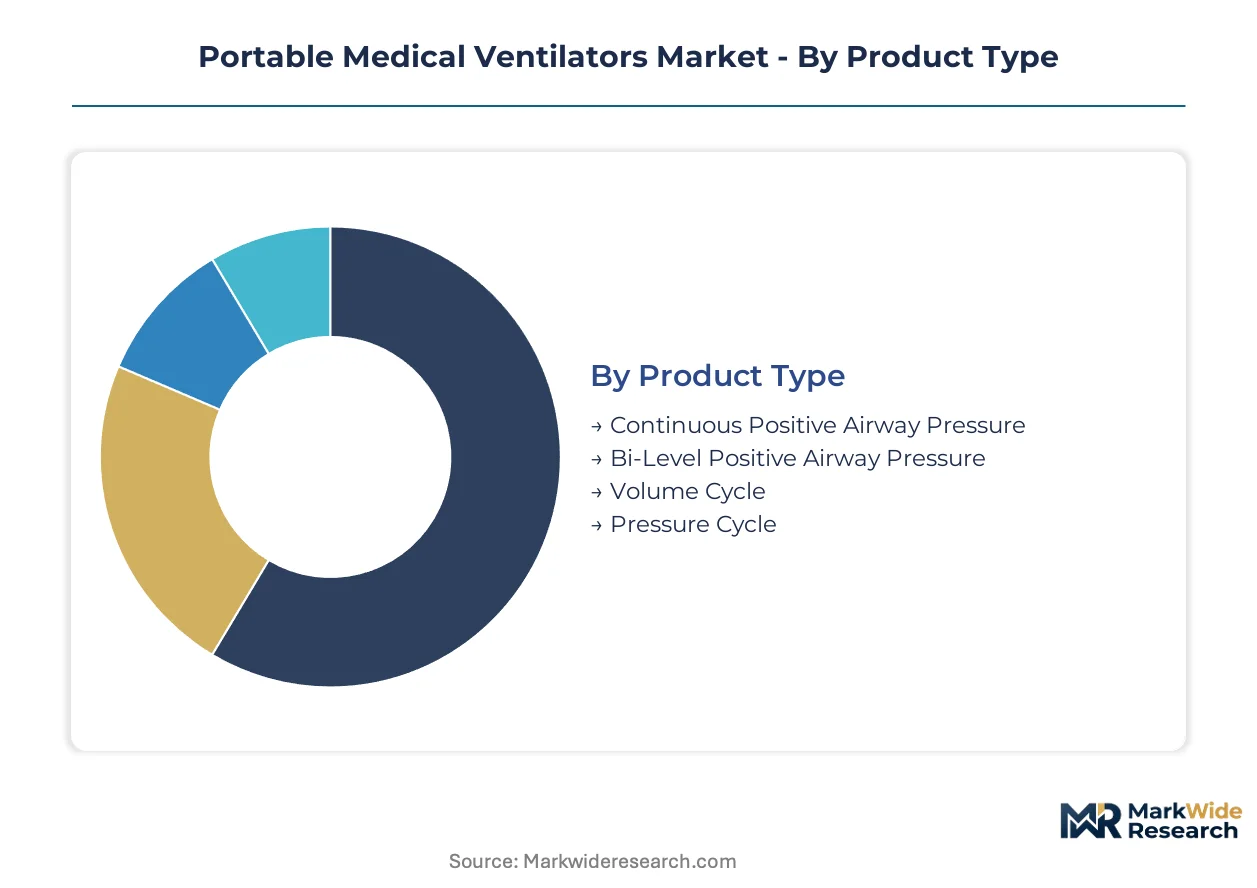
Portable ventilator segmentation reveals divergent engineering priorities across acute versus chronic deployment contexts. Product type and technology choices determine reimbursement eligibility, while end-user specifications dictate battery autonomy and noise thresholds. Manufacturers must align platform architectures with distinct clinical workflows rather than forcing universal designs across incompatible use cases.
Product Type:
The use-case spectrum spans chronic outpatient therapy through critical care transport, with each modality demanding distinct pressure delivery architectures and patient interface compatibility.
- Continuous Positive Airway Pressure:Delivers constant positive pressure throughout the respiratory cycle via turbine-driven blower systems, typically operating at 4-20 cm H2O. Homecare settings in the United States dominate procurement as CMS reimbursement pathways prioritize lower-acuity residential therapy. Sleep apnea patient volumes and lower clinical training requirements sustain preference over alternatives.
- Bi-Level Positive Airway Pressure:Alternates between higher inspiratory and lower expiratory pressure settings, requiring dual-channel pressure regulation and more sophisticated trigger algorithms. Hospital discharge planning and sub-acute transition units favor this modality for COPD patients requiring ventilatory assistance beyond CPAP capabilities. Germany's university hospitals are piloting bundled reimbursement models that separate device acquisition from remote monitoring subscriptions.
- Volume Cycle:Delivers preset tidal volumes regardless of airway resistance changes, utilizing piston or bellows mechanisms with precise displacement control.
- Pressure Cycle:Terminates inspiration at preset pressure thresholds, traditionally employed in emergency field settings where gas consumption efficiency outweighs precision requirements.
Established volume favors Continuous Positive Airway Pressure; emerging adoption favors Bi-Level Positive Airway Pressure.
End User:
Cost tier stratification separates capital-intensive institutional procurement from distributed homecare rental models with recurring service revenue attachment.
- Hospitals:Acute care facilities demand FDA 510(k) cleared devices with comprehensive alarm suites and centralized monitoring integration. China NMPA GB standard compliance is becoming mandatory for imported equipment as county-level hospital upgrades accelerate under Healthy China 2030.
- Homecare Settings:Residential deployment requires sub-30 dB acoustic performance, extended battery autonomy, and cellular telemetry for remote compliance monitoring. CMS and private payer coverage expansion in the United States is compressing form factors while expanding software complexity requirements.
- Emergency Services:Pre-hospital transport prioritizes rapid deployment, ruggedized construction, and compatibility with ambulance power systems.
- Military Facilities:Field medical units require NATO-standard connectors, electromagnetic pulse hardening, and operation across extreme environmental conditions.
Institutional procurement concentrates in Hospitals; margin expansion concentrates in Homecare Settings.
Technology:
Application maturity separates algorithm-driven adaptive systems from legacy pneumatic architectures facing obsolescence in developed markets.
- Microprocessor-Controlled:Adaptive ventilation algorithms adjust pressure support breath-by-breath based on patient effort detection and impedance monitoring. Developed markets show clear preference as clinical training requirements drop and outcomes data accumulates; EU MDR software lifecycle requirements are extending development timelines for this category.
- Pneumatic:Compressed gas-driven logic circuits without electronic control, historically dominant in emergency and military applications.
- Electric:Motor-driven piston or blower systems with basic electronic timing, occupying mid-tier price positioning.
- Hybrid:Combines pneumatic power sources with electronic monitoring and alarm functions, prevalent in transport ventilators requiring gas conservation.
Technology leadership resides with Microprocessor-Controlled; cost-sensitive procurement sustains Electric.
Application:
Customer type differentiation separates chronic disease management platforms from acute intervention devices with divergent service intensity requirements.
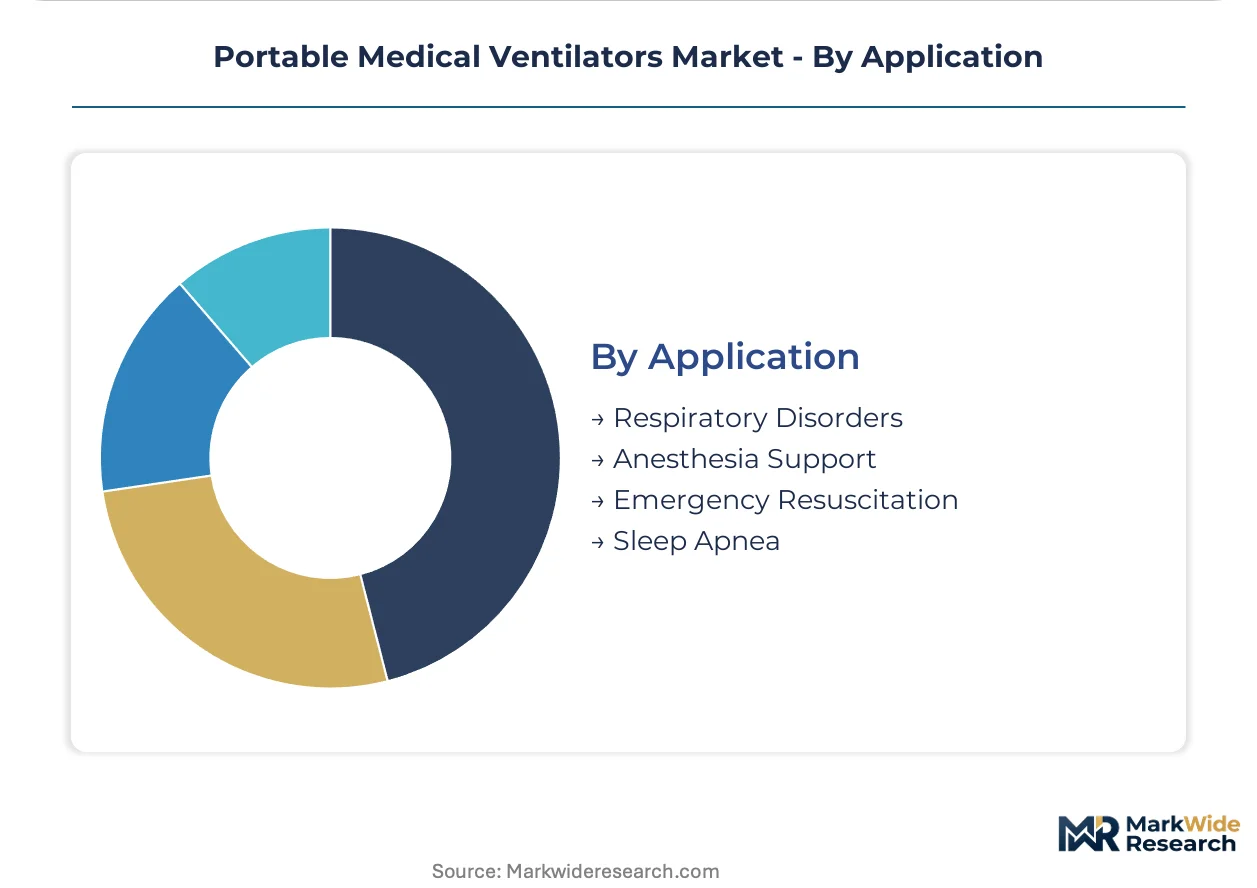
- Respiratory Disorders:Long-term ventilatory support for COPD, ALS, and restrictive lung diseases, typically requiring 16+ hours daily use. Homecare reimbursement pathways in the United States and Germany are rewriting procurement specifications faster than hardware refresh cycles accommodate.
- Sleep Apnea:Nocturnal positive pressure therapy with emphasis on acoustic comfort and mask seal reliability. Oral appliance therapy and hypoglossal nerve stimulation implants are exerting substitution pressure in mild-to-moderate cases.
- Anesthesia Support:Intraoperative ventilation with precise control of respiratory rate, tidal volume, and oxygen concentration.
- Emergency Resuscitation:Rapid deployment ventilation for cardiac arrest and trauma, prioritizing simplicity over sophisticated monitoring.
Patient volume concentrates in Respiratory Disorders; competitive intensity concentrates in Sleep Apnea.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication for precision pressure sensors clusters in Taiwan and South Korea, creating geographic vulnerability for ventilator manufacturers dependent on microcontroller supply chains. Device assembly and regulatory certification concentrate in the United States, Germany, and China as these markets maintain the most stringent quality management requirements.
United States
CMS reimbursement expansion for long-term ventilator rentals outside acute settings is accelerating homecare procurement of lighter, battery-operated units. FDA 510(k) premarket notification pathways are tightening clinical evidence requirements for software-as-a-medical-device functionalities. Minneapolis-based Medtronic PLC leverages its extensive field service network to capture recurring maintenance contracts across the Midwest and Southeast hospital corridors.
Germany
University hospitals are piloting disaggregated purchasing models that separate capital equipment from remote monitoring subscriptions for homecare discharge planning. EU MDR conformity assessment and Annex XVI expansion are capturing previously exempt wellness devices under formal clinical evidence obligations. Lübeck-based Drägerwerk AG & Co. KGaA anchors European manufacturing capacity for transport-capable ventilators serving sub-acute transition units.
China
County-level hospital upgrades under the Healthy China 2030 initiative are creating first-time demand for transport-capable ventilators in tier-3 and tier-4 cities. NMPA implements GB standards for respiratory device safety while accelerating review timelines for innovative emergency equipment. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies domestic manufacturing scale serving both institutional procurement and export markets across Asia-Pacific.
Japan
Aging demographics and chronic respiratory disease prevalence are expanding homecare ventilator penetration beyond traditional hospital-centric models. PMDA maintains alignment with FDA software validation protocols while enforcing JIS standards for electromagnetic compatibility in residential settings. Tokyo and Osaka metropolitan areas concentrate reimbursement decision-making authority and specialist physician networks for adaptive ventilation algorithm adoption.
United Kingdom
NHS procurement frameworks are unbundling device acquisition from service contracts, mirroring the disaggregated purchasing trends visible in German university hospitals. MHRA post-Brexit regulatory autonomy is maintaining EU MDR technical equivalence while streamlining emergency use authorization pathways. London and Southeast England concentrate clinical trial infrastructure for microprocessor-controlled ventilation systems targeting COPD patient populations.
Portable Medical Ventilators Market Key Industry Players
Diversified medical technology conglomerates and specialized respiratory device manufacturers split the market along capability depth versus portfolio breadth vectors. The vendor base organizes into three strategic archetypes: integrated critical care platforms with hospital system relationships, focused respiratory therapy specialists with homecare channel dominance, and emerging Asian manufacturers with cost-optimized production scale. Competitive intensity concentrates on M&A activity targeting remote monitoring software capabilities and strategic partnerships with cloud-based clinical decision support providers.
Among diversified critical care platforms, Medtronic PLC and GE Healthcare exemplify the integrated hospital system archetype with extensive field service networks. ResMed occupies a position within the respiratory therapy specialist tier, anchoring homecare channel penetration through subscription-based remote monitoring models. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the emerging Asian manufacturing archetype with domestic market scale and expanding export certification portfolios.
| Leading Market Players |
|---|
| Medtronic PLC |
| ResMed |
| Drägerwerk AG & Co. KGaA |
| Vyaire Medical |
| GE Healthcare |
| Getinge AB |
| Hamilton Medical |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Koninklijke Philips NV |
| Others |
Cost & Logistics Intelligence
Taipei and Hsinchu semiconductor fabrication clusters anchor microcontroller supply for precision pressure sensors, concentrating upstream bargaining power among ventilator manufacturers who must absorb input cost volatility or pass through to hospital procurement committees and homecare rental providers.
Pricing Analysis
Remote monitoring subscription revenue drives lifetime value capture as manufacturers disaggregate hardware sales from recurring service streams. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) cleared acute care systems from EU MDR Class IIa homecare units and basic transport ventilators. Cost compression in economy tiers intensifies because Shenzhen and other Asian manufacturing hubs optimize for volume scale. Hospital procurement committees exhibit lowest price sensitivity due to bundled reimbursement, while county-level hospitals in tier-3 Chinese cities face acute budget constraints.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates strategic sourcing discussions as ventilator manufacturers diversify microcontroller procurement. Taiwan, South Korea, and Japan concentrate supply for precision pressure sensors, MEMS accelerometers, and lithium-ion battery cells. Raw material dependencies center on rare earth magnets for turbine blowers, medical-grade polymers for patient circuits, and copper windings for motor assemblies. Single-source vulnerability persists for FDA-validated firmware foundries. Distribution runs through authorized medical device distributors with biomedical technician certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR software lifecycle requirements are disrupting competitive positioning as algorithm-driven adaptive ventilation becomes the primary differentiation vector, forcing manufacturers to restructure quality assurance teams or exit premium segments.
For Market Incumbents: Build regulatory certification moats by accelerating FDA 510(k) submissions for software-as-a-medical-device functionalities before tightened clinical evidence requirements take full effect. Deepen backward integration into precision sensor calibration to reduce Taiwan foundry dependency. Capture remote monitoring subscription revenue through cellular telemetry integration to offset hardware margin compression from oral appliance therapy substitution in sleep apnea.
For New Entrants and Emerging Players: Rural China county-level hospital penetration offers white-space opportunity as Healthy China 2030 infrastructure upgrades create first-time demand for transport-capable ventilators without incumbent service network entrenchment. Target COPD patient transition units in German university hospitals piloting disaggregated purchasing models. Partner with cloud-based clinical decision support providers to bypass capital-intensive field service network requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue infrastructure play because homecare reimbursement expansion is structurally shifting procurement from transactional device sales to subscription-based patient management platforms. Acquisition targets should display software-defined functionality depth and established FDA quality management system credentials. Monitor EU MDR notified body capacity constraints as early signal for certification timeline bottlenecks that will favor scaled incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Preempts tightened software validation requirements before FDA cybersecurity guidance finalization. |
| CE Marking Pathway Investment | EU MDR Annex XVI expansion captures wellness devices with medical claims under formal assessment. |
| Hospital System Partnership | IDN three-year total cost of ownership agreements separate capital equipment from recurring revenue streams. |
| Software Companion Development | Cloud-based clinical decision support enables subscription models extending patient engagement beyond device sale. |
| Reimbursement Strategy Alignment | CMS coverage expansion for long-term ventilator rentals outside acute settings accelerates homecare procurement. |
Research Approach
A standing panel of respiratory therapists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers provided ongoing calibration against operating reality. Primary interviews with ventilator manufacturers, field service network operators, and homecare rental providers combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and NMPA GB standard registrations. Bottom-up patient volume modeling and top-down healthcare expenditure triangulation anchored market size estimation.
Scenario-bracketing framed volume and value outputs across the projection horizon, with analytical frameworks modeling product type, technology architecture, end-user setting, and application acuity segmentation dimensions. CAGRs derived from patient epidemiology trends, reimbursement pathway expansion rates, and replacement cycle dynamics. Forecast inputs incorporated semiconductor supply lead time volatility and EU MDR notified body capacity constraints.
Practitioners should monitor FDA cybersecurity guidance finalization, EU MDR software lifecycle enforcement intensity, and Taiwan foundry capacity allocation for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Gel Implants Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Medical Manifolds Market
Medical Devices
Face Mask Device Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Cannula Market
Medical Devices
Thrombectomy System Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Posture Correction Market
Medical Devices
Global Smart Implants Market
Medical Devices
Germany Ophthalmic Devices Market