
 Recanalization System Market | 2026-2036
Recanalization System Market Size, Share, and Industry Trends Forecast 2026-2036
Recanalization System Market Analytics
Next-generation aspiration catheters with larger distal lumen diameters is reorganizing competitive dynamics across the neurovascular intervention space. Medtronic leverages its integrated stroke platform to sustain leadership in thrombectomy device portfolios. Boston Scientific Corporation anchors its position through specialized guidewire and balloon catheter combinations optimized for tortuous anatomy. Penumbra differentiates via dedicated aspiration systems that dominate large-bore catheter segments in comprehensive stroke centers.
A recanalization system comprises interventional devices designed to restore patency in occluded blood vessels through mechanical, aspiration, or combined techniques, typically employing nitinol-based components with trackability specifications below 0.014 inch for distal navigation. These systems serve the primary purpose of reperfusion in acute ischemic stroke, peripheral artery disease, and coronary thrombosis where pharmacological dissolution remains contraindicated or insufficient. Catheters and guidewires together constitute the procedural backbone, with aspiration catheters capturing expanding margin pools as centers shift toward first-line mechanical thrombectomy. Stents retain mature positioning within coronary applications while peripheral vascular deployment modes are gaining traction through minimally invasive delivery protocols that reduce hospitalization duration.
FDA breakthrough device pathways and EMA centralized procedures for class III implantable devices shape market access timelines and clinical evidence requirements for manufacturers seeking commercial authorization. ISO 13485 quality management standards and MDR technical documentation mandates in Europe enforce manufacturing rigor that filters smaller participants from premium product tiers. Stakeholders must monitor evolving reimbursement codes for mechanical thrombectomy across national health systems to anticipate volume shifts between hospital and ambulatory surgical center settings.
Market Dynamics
Aspiration-based mechanical thrombectomy is decomposing the traditional stent-retriever paradigm across comprehensive stroke centers, forcing manufacturers to reconfigure product portfolios around large-bore catheter architectures and integrated suction platforms.
Growth Catalysts
- MDR Technical Documentation Mandates:European manufacturers accelerating ISO 13485 quality upgrades to maintain premium tier positioning, filtering subscale competitors from high-margin catheter segments.
- Specialized Neurovascular Intervention Units:German hospital clusters scaling minimally invasive cerebrovascular procedures, creating concentrated demand pockets for next-generation aspiration systems.
- Nitinol Trackability Specifications:Sub-0.014 inch distal navigation capabilities expanding addressable anatomy in tortuous vessel segments, opening procedural categories previously deemed inaccessible.
Market Restraints
- Nitinol Alloy Supply Concentration:Primary raw material sourcing concentrated among limited specialty metal processors, exposing catheter manufacturers to input cost volatility and delivery timeline risk.
- FDA Breakthrough Device Pathway Friction:Accelerated clinical validation timelines compressing evidence generation budgets while maintaining stringent safety thresholds for Class III implantable devices.
- Pharmacological Thrombolysis Substitution:Tenecteplase and similar lytic agents retaining first-line protocol status in resource-constrained settings, capping mechanical thrombectomy penetration in price-sensitive segments.
Strategic Opportunities
- Peripheral Vascular Deployment Modes:Minimally invasive delivery protocols reducing hospitalization duration in lower-extremity arterial occlusion, expanding recanalization system applicability beyond neurovascular indications.
- Ambulatory Surgical Center Channel Development:Reimbursement code evolution enabling same-day discharge protocols for select peripheral interventions, creating new volume pools outside traditional hospital settings.
- ISO 13485 Quality Certification Arbitrage:Mid-tier manufacturers leveraging manufacturing rigor investments to capture share from non-compliant competitors in European and Asia-Pacific export markets.
Industry Challenges
- Neurointerventionalist Training Pipeline:Specialized procedural expertise required for distal navigation in tortuous cerebrovascular anatomy creating talent scarcity, limiting adoption velocity in secondary stroke centers.
- Legacy Stent-Retriever Inventory Integration:Comprehensive stroke centers managing mixed-platform workflows during aspiration system transition, complicating supply chain rationalization and staff training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recanalization System Market |
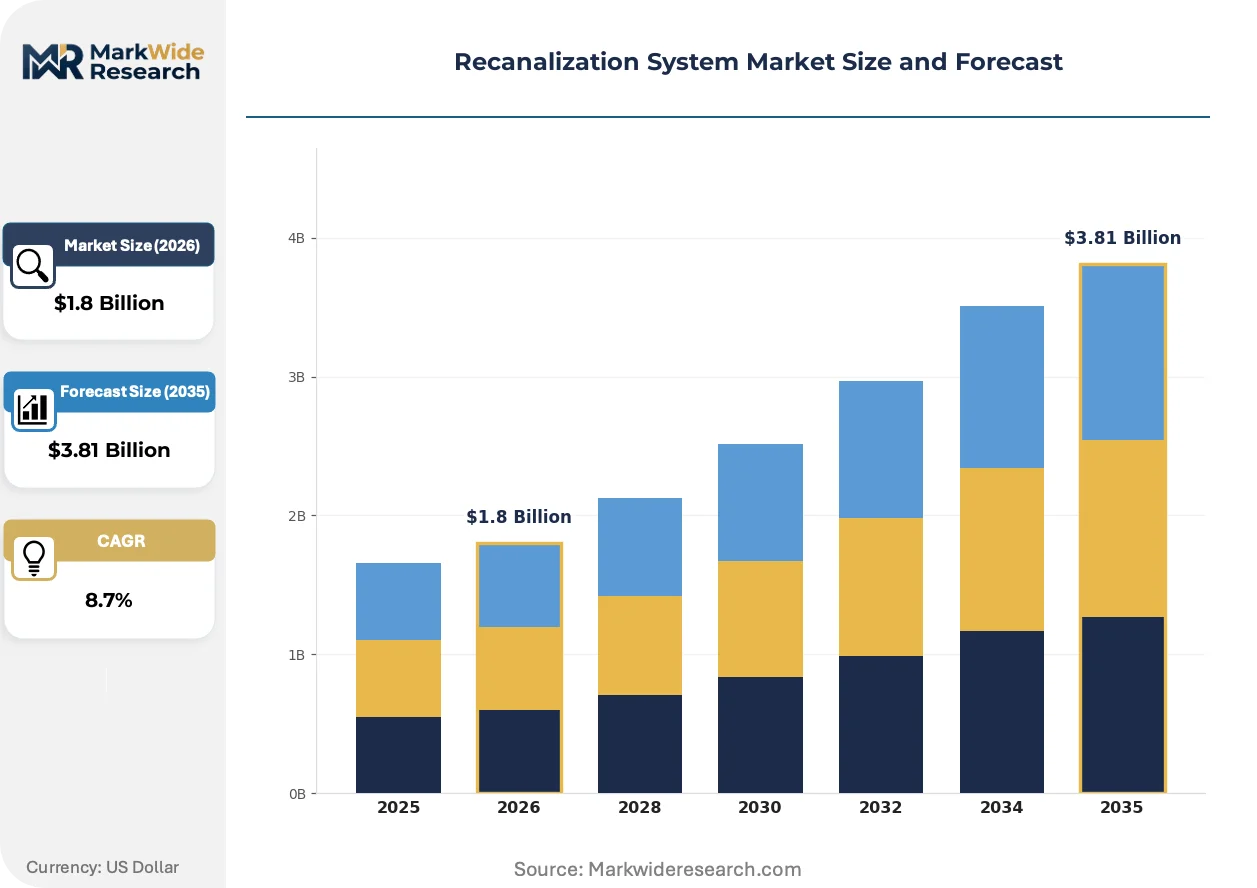
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Balloons, Stents, Guidewires End User: Hospitals, Clinics, Diagnostic Centers, Ambulatory Surgical Centers Delivery Mode: Invasive, Minimally Invasive, Outpatient, Emergency Application: Cerebrovascular, Peripheral Vascular, Coronary, Pulmonary |
| Companies Covered | Medtronic, Boston Scientific Corporation, Stryker Corporation, Abbott Laboratories, Terumo Corporation, Becton Dickinson and Company, Penumbra, Cook Medical, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recanalization System Market Evolving Landscape
Device architecture is fragmenting into modular component ecosystems, with catheter platforms, aspiration pumps, and navigation systems increasingly sourced from specialized suppliers rather than integrated manufacturers.
Large-bore aspiration catheters with expanded distal lumen diameters is decomposing the stent-retriever dominance in acute ischemic stroke intervention. Comprehensive stroke centers in the United States are adopting these platforms as first-line mechanical thrombectomy options. The technology is compressing procedural steps and reducing dependence on retriever-based clot engagement, reshaping competitive positioning around suction performance metrics rather than stent design.
EMA centralized procedures for Class III implantable devices are compressing market access timelines for manufacturers with established quality management systems. European manufacturers investing early in MDR technical documentation are capturing premium positioning ahead of compliance deadlines. Peripheral vascular catheter segments are experiencing the most pronounced regulatory acceleration effects, as these applications face lower clinical evidence burdens than neurovascular indications.
Hospital procurement committees are consolidating vendor relationships around integrated stroke platform suppliers capable of delivering catheter, pump, and monitoring combinations. Single-source contracting is displacing multi-vendor purchasing in comprehensive stroke centers seeking procedural standardization. This concentration pattern is most visible in Germany and the United States, where specialized neurovascular intervention units prioritize supply chain simplification over component-level optimization.
Recanalization System Market Segmentation
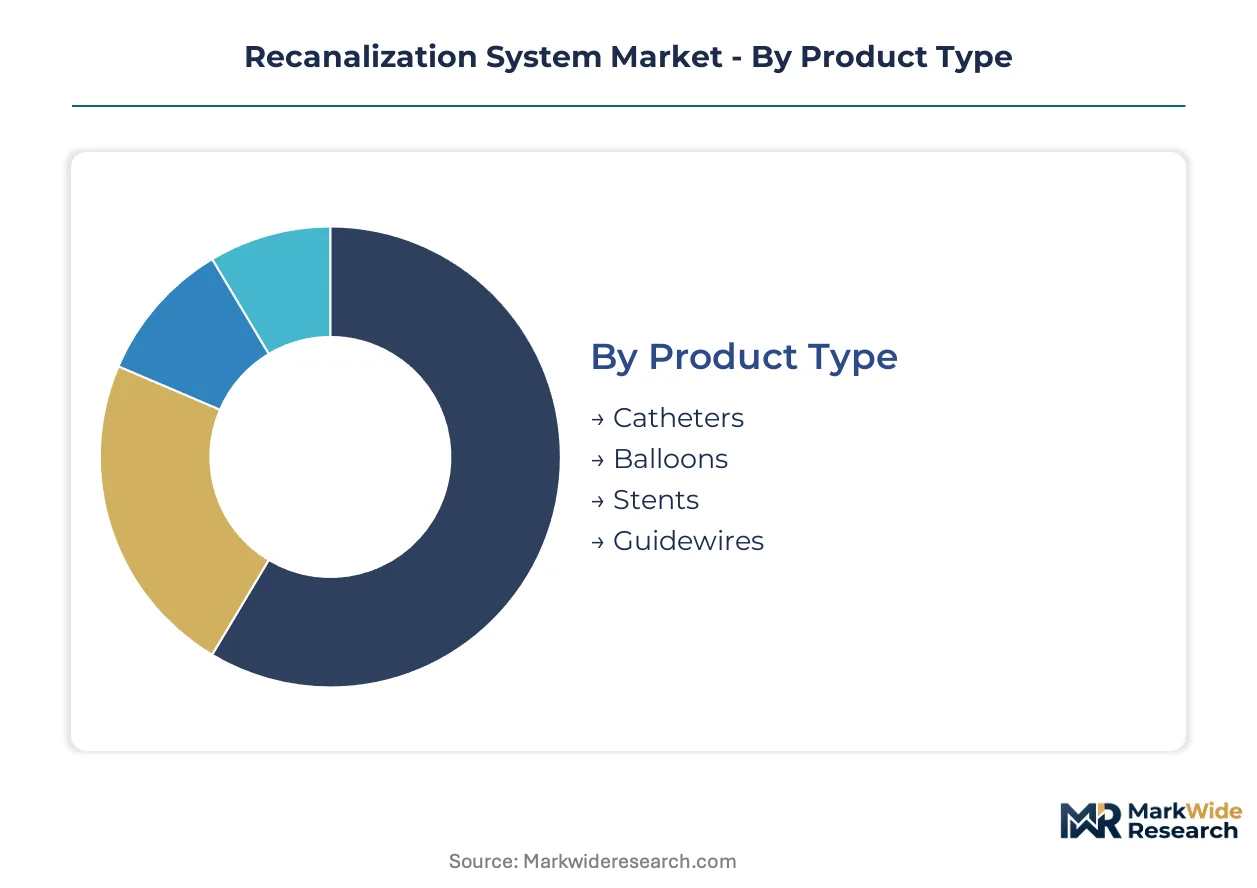
Recanalization system procurement patterns diverge sharply across clinical settings, with comprehensive stroke centers prioritizing integrated aspiration platforms while peripheral intervention sites favor modular component sourcing. Product architecture choices directly determine reimbursement pathways and procedural throughput metrics that shape hospital capital allocation decisions.
Product Type:
Catheter production clusters in Germany and the United States serve domestic comprehensive stroke centers with minimal export dependency, while guidewire manufacturing concentrates in export-oriented Swiss and Japanese precision metalworking hubs.
- Catheters:Large-bore aspiration architectures with distal lumen diameters exceeding 0.060 inch dominate mechanical thrombectomy workflows in United States comprehensive stroke centers. German neurovascular intervention units are scaling procurement of next-generation suction platforms that compress procedural steps and reduce retriever dependence.
- Balloons:Angioplasty balloon catheters with rapid-exchange designs enable single-operator deployment in tortuous peripheral anatomy. Demand concentrates in German hospital clusters scaling minimally invasive lower-extremity arterial procedures where same-day discharge protocols are expanding.
- Stents:Self-expanding nitinol stents retain coronary application dominance while peripheral deployment gains traction through reduced hospitalization protocols.
- Guidewires:Sub-0.014 inch distal navigation specifications from Swiss and Japanese manufacturers enable access to previously unreachable cerebrovascular segments.
Catheters command the established base. The steepest expansion runs through aspiration catheter segments as centers transition from stent-retriever platforms.
End User:
Cost tier stratification separates capital-intensive comprehensive stroke centers from outpatient facilities operating on constrained equipment budgets and simplified reimbursement codes.
- Hospitals:Comprehensive stroke centers in the United States and Germany anchor demand for integrated aspiration platforms combining catheter, pump, and monitoring systems. These facilities prioritize single-source vendor contracts that standardize procedural workflows and reduce supply chain complexity across neurovascular intervention units.
- Clinics:Outpatient cardiology clinics in Germany are expanding peripheral vascular recanalization capacity through mobile C-arm investments and streamlined staff training protocols.
- Diagnostic Centers:Vascular imaging facilities in the United States are adding interventional capabilities to capture downstream procedure revenue.
- Ambulatory Surgical Centers:Same-day discharge reimbursement code evolution in United States markets is enabling peripheral arterial intervention migration outside hospital settings.
Hospitals retain volume concentration. Ambulatory Surgical Centers are climbing the fastest as reimbursement frameworks enable site-of-service shift.
Delivery Mode:
Volume distribution favors minimally invasive protocols that reduce anesthesia requirements and enable faster patient turnover in high-throughput intervention suites.
- Invasive:Open surgical revascularization retains indication in failed endovascular cases and complex anatomical configurations.
- Minimally Invasive:Transfemoral access with 6-8 French sheath compatibility dominates mechanical thrombectomy workflows in United States comprehensive stroke centers. German neurovascular units are standardizing radial access protocols that reduce complication rates and accelerate ambulation.
- Outpatient:Superficial femoral artery interventions with provisional stenting are migrating to ambulatory settings in United States markets with evolved reimbursement codes.
- Emergency:Door-to-device time pressures in United States stroke systems of care are driving 24/7 neurointerventionalist coverage requirements and dedicated aspiration platform availability.
Minimally Invasive protocols command the established base. Outpatient delivery is gaining share fastest as peripheral indications shift to ambulatory settings.
Application:
Customer type differentiation separates high-acuity neurovascular interventions requiring specialized expertise from standardized peripheral procedures suitable for broader operator deployment.
- Cerebrovascular:Acute ischemic stroke intervention demands aspiration platform performance metrics and distal navigation capabilities that open previously inaccessible M2 and M3 segment anatomy. United States comprehensive stroke centers are consolidating vendor relationships around integrated system suppliers.
- Peripheral Vascular:Lower-extremity arterial occlusion treatment is expanding through minimally invasive delivery protocols that reduce hospitalization duration in German hospital clusters.
- Coronary:Stent-retriever and aspiration hybrid approaches retain established positioning in thrombotic coronary events.
- Pulmonary:Massive pulmonary embolism mechanical thrombectomy is emerging as an indication with evolving evidence bases and procedural coding.
Cerebrovascular applications command the established base. Peripheral Vascular interventions are expanding most quickly as ambulatory protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German catheter manufacturers export aspiration platforms to United States comprehensive stroke centers, establishing the dominant transatlantic trade corridor in neurovascular intervention devices.
United States
FDA breakthrough device designations accelerate clinical validation timelines for novel recanalization technologies. Centers for Medicare & Medicaid Services reimbursement codes for mechanical thrombectomy enable 24/7 neurointerventionalist coverage requirements. Comprehensive stroke centers in Texas and Florida are consolidating vendor relationships around integrated aspiration platform suppliers.
Germany
Specialized neurovascular intervention units in Bavaria and North Rhine-Westphalia are scaling minimally invasive cerebrovascular procedures. MDR technical documentation mandates enforce ISO 13485 quality upgrades that filter subscale competitors from premium catheter tiers. Hospital clusters in Baden-Württemberg are standardizing radial access protocols that reduce complication rates and accelerate ambulation.
Japan
PMDA accelerated approval pathways compress market access timelines for manufacturers with established quality management systems. METI industrial policy supports precision metalworking capabilities in guidewire production. Nagoya-based manufacturers supply sub-0.014 inch distal navigation specifications that enable access to previously unreachable cerebrovascular segments.
Switzerland
Swissmedic regulatory frameworks align with EMA centralized procedures for Class III implantable devices. Precision metalworking clusters in the Jura Arc maintain specialized guidewire manufacturing capabilities. Geneva and Basel industrial zones serve export-oriented demand for distal navigation components in tortuous vessel applications.
China
NMPA innovation approval pathways are compressing evidence generation timelines for domestic catheter manufacturers. MIIT industrial upgrading programs support nitinol alloy processing capabilities in Yangtze River Delta medical device zones. Shanghai and Suzhou production clusters are capturing share in mid-tier aspiration catheter segments across Asia-Pacific markets.
Recanalization System Market Competitive Landscape
Listed leaders compete with private specialists across integrated platform versus modular component strategies. The vendor base organizes into three tiers: diversified medical technology conglomerates with stroke platform integration capabilities, mid-scale catheter specialists with ISO 13485 certification arbitrage positions, and regional fabricators serving price-sensitive segments with simplified product architectures. Dominant competitive moves include single-source hospital contracting that displaces multi-vendor purchasing and backward integration into nitinol alloy processing to secure raw material supply.
Within the diversified conglomerate tier, Medtronic and Boston Scientific Corporation exemplify integrated stroke platform strategies that combine catheter, pump, and monitoring systems. Penumbra occupies a specialist position in large-bore aspiration segments. These three anchors represent contrasting archetypes: full-platform integration, guidewire-balloon optimization for tortuous anatomy, and dedicated suction system dominance respectively.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Stryker Corporation |
| Abbott Laboratories |
| Terumo Corporation |
| Becton Dickinson and Company |
| Penumbra |
| Cook Medical |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
ISO 13485 quality management certification gates both supply qualification and price differentiation simultaneously, filtering subscale catheter manufacturers from premium tier positioning while enabling certified producers to command margin premiums across European and United States hospital procurement channels.
Pricing Analysis
Hospital procurement committees anchor contract-based long-term purchasing structures across comprehensive stroke centers. Pricing stratifies across ISO 13485-certified premium tiers, standard MDR-compliant mid-tiers, and economy segments lacking full quality documentation. Cost compression in economy catheter tiers is intensifying because Chinese manufacturers are scaling nitinol processing capabilities. Outpatient cardiology clinics exhibit highest price sensitivity; integrated stroke platform suppliers at comprehensive stroke centers show lowest.
Supply Chain Analysis
Germany and the United States anchor aspiration catheter production for domestic comprehensive stroke centers; Switzerland and Japan supply precision guidewire manufacturing for export markets. Nitinol alloy feedstock draws from limited specialty metal processors in Yangtze River Delta zones and North American specialty foundries. Single-source vulnerability concentrates in superelastic nitinol wire supply for sub-0.014 inch distal navigation specifications. Distribution runs through hospital procurement committees consolidating vendor relationships around integrated platform suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device architecture fragmentation into modular component ecosystems creates multiple entry niches, as aspiration catheters, navigation guidewires, and suction pumps increasingly source from specialized suppliers rather than integrated manufacturers.
For Market Incumbents: Consolidate hospital procurement relationships through single-source contracting that displaces multi-vendor purchasing in comprehensive stroke centers. Capture backward integration into nitinol alloy processing to secure raw material supply against specialty metal processor concentration. Expand ISO 13485-certified production capacity in German manufacturing clusters to defend premium positioning against MDR-filtered competitors. For New Entrants and Emerging Players: Differentiate on radial access catheter compatibility for German neurovascular units standardizing alternative access protocols. Target peripheral vascular deployment modes in United States ambulatory surgical centers where reimbursement code evolution enables same-day discharge protocols. Pursue ISO 13485 certification arbitrage to capture share from non-compliant competitors in Asia-Pacific export markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across large-bore aspiration catheter segments as FDA breakthrough device pathways compress clinical validation timelines and evidence generation budgets. Focus acquisition screening on mid-scale catheter specialists with established MDR technical documentation and captive nitinol supply arrangements. Monitor FDA breakthrough device designation velocity as inflection indicator for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management rigor filters subscale competitors from premium catheter tiers in European markets. |
| Backward Integration into Nitinol Processing | Captive alloy supply secures input cost stability against specialty metal processor concentration risk. |
| Radial Access Protocol Development | German hospital clusters standardizing alternative access create differentiated catheter demand pools. |
| Hospital System Partnership | Single-source contracting with comprehensive stroke centers displaces multi-vendor procurement patterns. |
| Ambulatory Surgical Center Channel Buildout | Reimbursement code evolution in United States enables peripheral intervention migration outside hospitals. |
Research Methodology
Cross-validation between neurointerventionalist interviews and hospital procurement database analysis anchors the qualitative findings. Primary fieldwork engaged stroke center medical directors, GPO contracts managers, biomedical engineers, and catheter manufacturing quality leads. Secondary validation drew from FDA 510(k) filings, EMA centralized procedure documentation, CMS reimbursement code updates, and ISO 13485 certification registries. Bottom-up volume modeling triangulated against top-down spending estimates across the analysis window.
Sensitivity analysis tested forecast outputs against alternative scenarios for nitinol alloy pricing volatility and MDR compliance deadline shifts. The segmentation framework modeled product type, end user facility tier, delivery mode protocol, and application anatomy across the projection horizon. CAGRs derived from logistic diffusion curves fitted to mechanical thrombectomy adoption patterns. Forecast inputs incorporated hospital capital expenditure cycles and neurointerventionalist training pipeline expansion rates.
The analysis sits within stated boundaries; outcomes outside maintained FDA breakthrough device pathway velocity or sustained nitinol supply concentration would require recalibration. Forecasts reflect documented assumptions regarding reimbursement code stability and MDR enforcement rigor. Recalibration cycles align with material shifts in regulatory pathway timelines or hospital procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Telehealth Device Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
Brazil Ultrasound Devices Market