
 Global Advanced Ophthalmology Technologies Market | 2026-2036
Global Advanced Ophthalmology Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Ophthalmology Technologies Market Foresight
Modular platform bundling is broadening buyer choice across ambulatory surgical centers and specialty eye clinics. Alcon leverages integrated cataract-refractive workflows to sustain premium positioning in surgical suites. Carl Zeiss Meditec AG anchors diagnostic imaging through optical coherence tomography ecosystems that span preoperative planning to postoperative monitoring. Bausch + Lomb competes in contact lens therapeutics while extending its surgical consumables footprint through channel density in North American eye care clinics.
Advanced ophthalmology technologies encompass precision instruments and software-driven systems for diagnosing, monitoring, and treating ocular pathologies, typically operating at wavelength-specific resolutions below ten micrometers for retinal layer segmentation. These technologies serve commercial purposes spanning early disease detection, surgical intervention, and refractive correction across outpatient and inpatient settings. Diagnostic devices lead product type revenue due to recurring software upgrades and disposable probe attachments, while optical coherence tomography dominates technology adoption because of its non-invasive cross-sectional imaging capability. Cataract management anchors application demand as the largest volume procedure, though glaucoma detection represents the fastest-growing application segment driven by AI-enhanced screening protocols in primary care referrals.
FDA premarket notification pathways govern Class II ophthalmic laser systems, while the EU MDR requires clinical evidence renewal for legacy CE-marked devices, extending regulatory timelines for manufacturers. Japan's PMDA enforces JIS-quality benchmarks on imported diagnostic equipment, creating compliance differentiation for established suppliers. ISO 13485 certification and FDA Quality System Regulation shape contract manufacturer selection, directly influencing supply base consolidation. Stakeholders must monitor reimbursement code fragmentation across Medicare fee schedules and national health insurance systems to anticipate capital equipment purchasing cycles.
Market Dynamics
Integrated diagnostic-surgical platforms are compressing capital equipment purchasing cycles as ambulatory surgical centers consolidate vendor relationships and demand bundled service contracts that span preoperative imaging through postoperative monitoring.
Growth Catalysts
- Aging Demographics in Japan and Germany:Population cohorts over 65 are expanding cataract procedure volumes and driving replacement demand for diagnostic imaging systems in Tokyo and Munich metropolitan clusters.
- EU MDR Clinical Evidence Requirements:Legacy device renewals are forcing manufacturers to refresh product portfolios, accelerating technology turnover and creating upgrade revenue streams for established suppliers.
- AI-Enhanced Screening Protocols:Machine learning algorithms embedded in optical coherence tomography systems are expanding glaucoma detection into primary care referral networks, opening new patient access points.
Market Restraints
- Specialized Optoelectronics Supply Concentration:Superluminescent diode and swept-source laser components concentrate among German and Japanese component suppliers, creating single-source vulnerability for OCT system manufacturers.
- FDA Premarket Notification Timelines:Class II ophthalmic laser system reviews are extending due to software-as-medical-device guidance complexity, delaying product launches by 8-14 months.
- Pharmacological Substitution for Early Glaucoma:Prostaglandin analog therapies and sustained-release drug delivery implants are displacing selective laser trabeculoplasty in mild-to-moderate cases.
Strategic Opportunities
- Underpenetrated Indian Diagnostic Infrastructure:Tier-2 and Tier-3 cities lack spectral-domain OCT density, creating whitespace for mobile screening units and equipment leasing models.
- Teleophthalmology Platform Integration:Cloud-based image transmission and AI-assisted remote diagnosis are converging with home-based visual field testing, enabling asynchronous care models.
- Japan's JIS Quality Benchmark Differentiation:PMDA enforcement of import standards creates compliance moats for suppliers with established quality management systems and local service infrastructure.
Industry Challenges
- Biomedical Optics Engineering Talent Scarcity:Interferometry system design and adaptive optics expertise concentrate among doctoral-level specialists in Boston, Stuttgart, and Tsukuba research corridors.
- ISO 13485 Certification Timeline Compression:Contract manufacturer qualification for FDA Quality System Regulation compliance is extending supplier onboarding from 12 to 24 months.
- Legacy Equipment Interoperability:DICOM-standard image archives from 2015-2019 system generations resist seamless integration with cloud-based analytics platforms, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Ophthalmology Technologies Market |
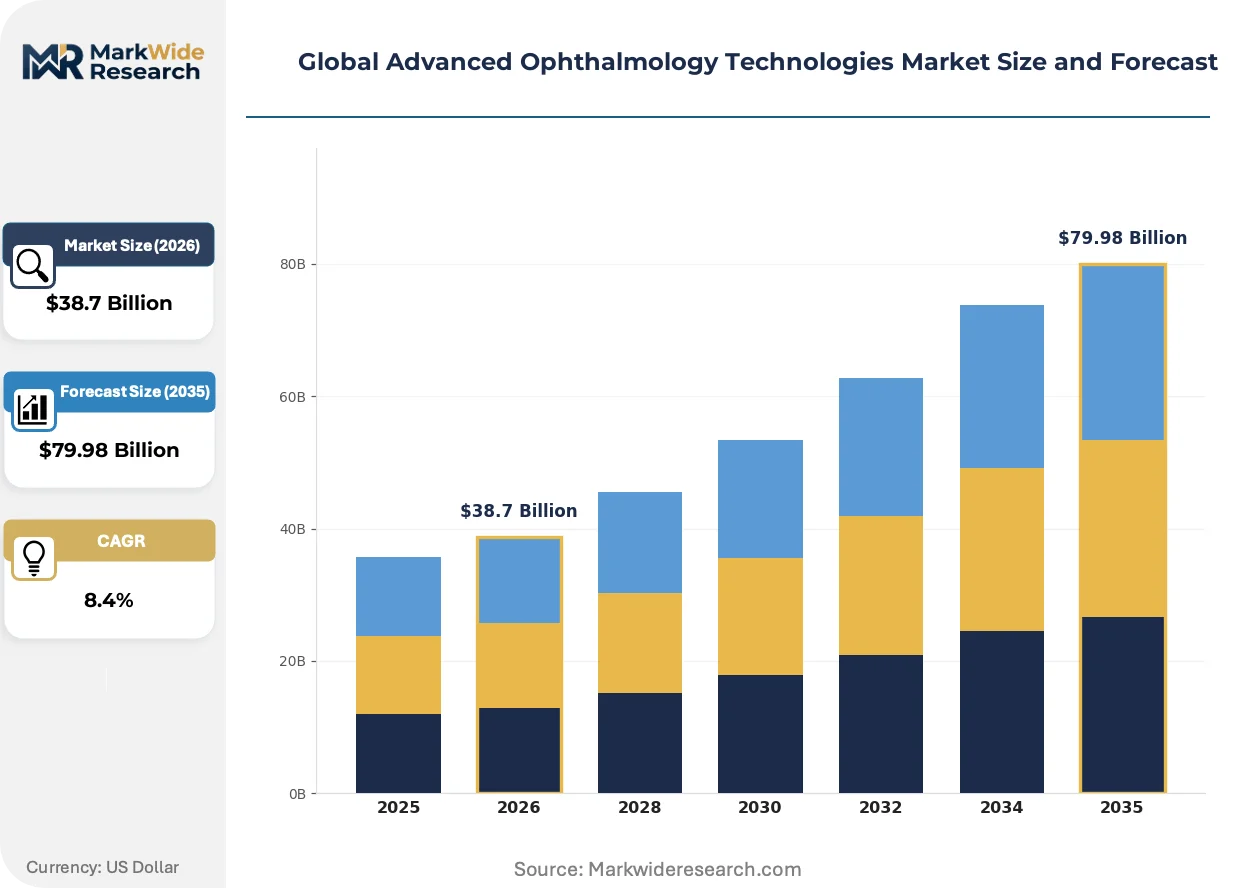
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Surgical Lasers, Imaging Systems, Therapeutic Equipment, Vision Correction Tools Technology: Optical Coherence Tomography, Confocal Microscopy, Fundus Photography, Wavefront Aberrometry, Fluorescein Angiography Application: Cataract Management, Glaucoma Detection, Retinal Disease Diagnosis, Corneal Treatment, Refractive Surgery End User: Eye Care Clinics, Specialty Centers, Research Institutions, Ambulatory Surgical Centers, Optical Laboratories |
| Companies Covered | Alcon, Carl Zeiss Meditec AG, Bausch + Lomb, Teva Pharmaceutical Industries Ltd., CooperVision, NIDEK CO., LTD., TOPCON CORPORATION, Ziemer Ophthalmic Systems AG, Essilor International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Ophthalmology Technologies Market Shifts & Advancements
Software-defined diagnostic workflows are displacing hardware-centric product architectures, enabling continuous feature deployment through subscription models rather than capital replacement cycles.
Swept-source optical coherence tomography is consolidating anterior segment and retinal imaging into single-platform configurations. Ambulatory surgical centers in the United States and Germany are adopting these unified systems to reduce equipment footprint and standardize staff training protocols. This consolidation is compressing the addressable market for standalone anterior segment OCT devices and redirecting R&D investment toward multimodal algorithm development.
Japan's PMDA has tightened JIS-quality benchmark enforcement on imported diagnostic equipment, requiring expanded local clinical validation studies for foreign manufacturers. This regulatory friction is extending registration timelines and elevating compliance costs for suppliers without established Japanese subsidiary infrastructure. European and North American OEMs are responding by acquiring domestic distributors or establishing captive service operations in Osaka and Yokohama.
Equipment-as-a-service contracting is displacing outright capital purchases in North American eye care clinics. Specialty clinics and multi-site ophthalmology groups are negotiating per-procedure leasing arrangements that bundle maintenance, software updates, and disposable probe supplies. This financing shift is most visible in California and Texas markets where private equity-backed practice consolidation has centralized procurement decision-making.
Global Advanced Ophthalmology Technologies Market Segmentation
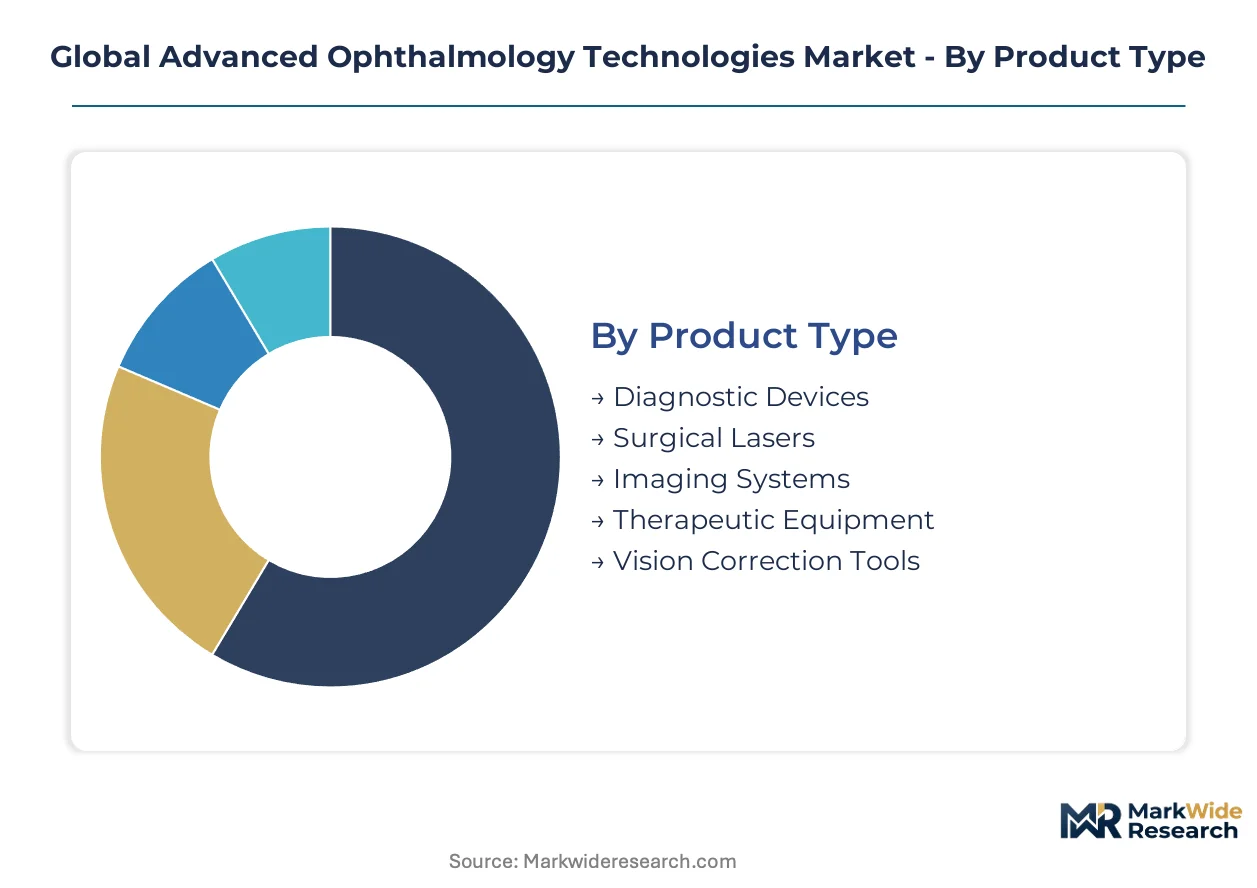
Segmentation in advanced ophthalmology technologies reveals distinct procurement patterns across capital-intensive diagnostic platforms and consumable-driven surgical workflows. Buyers prioritize interoperability, software upgrade paths, and bundled service contracts when selecting equipment categories.
Product Type:
Purchasing cycles vary dramatically between capital equipment with decade-long depreciation schedules and disposable-heavy therapeutic platforms that generate recurring revenue streams.
- Diagnostic Devices:Non-invasive imaging platforms with modular probe architectures dominate procurement budgets in United States and German eye care networks. Recurring software licensing and disposable tip attachments create predictable revenue streams for vendors serving high-throughput screening programs.
- Surgical Lasers:Femtosecond and excimer laser systems deliver tissue-specific photodisruption at sub-micron precision for corneal and capsular procedures. Tokyo metropolitan clusters and Munich surgical centers are replacing legacy platforms with integrated femtosecond-cataract systems to consolidate operating room footprint.
- Imaging Systems:Wide-field fundus cameras and adaptive optics platforms support posterior segment visualization.
- Therapeutic Equipment:Sustained-release drug delivery implants and selective laser trabeculoplasty devices compete for glaucoma treatment share.
- Vision Correction Tools:Phakic intraocular lenses and corneal inlays address presbyopia and high myopia corrections.
Volume sits with Diagnostic Devices; growth tilts toward Surgical Lasers.
Technology:
Resolution specifications and imaging depth determine platform selection for anterior versus posterior segment applications.
- Optical Coherence Tomography:Swept-source configurations now achieve micron-level axial resolution across 12mm imaging depth, unifying retinal and anterior segment diagnostics. United States ambulatory surgical centers are standardizing on single-platform OCT systems to reduce capital expenditure and simplify technician training protocols.
- Confocal Microscopy:In vivo cellular imaging of corneal layers enables early detection of infectious keratitis and dystrophic changes. German university hospitals deploy these systems for refractive surgery candidacy assessment and post-LASIK ectasia monitoring.
- Fundus Photography:Ultra-widefield systems capture peripheral retinal pathology without pharmacologic dilation.
- Wavefront Aberrometry:Hartmann-Shack sensor arrays measure higher-order optical aberrations for customized laser ablation profiles.
- Fluorescein Angiography:Dye-based vascular perfusion imaging remains essential for neovascular macular disease characterization.
Deployment concentrates in Optical Coherence Tomography; Confocal Microscopy is climbing the fastest among specialty referral centers.
Application:
Procedure volume and reimbursement stability shape capital allocation across disease-specific technology investments.
- Cataract Management:Phacoemulsification platforms with integrated femtosecond laser capsulotomy represent the highest-volume surgical application globally. Japan's aging demographic expansion in Osaka and Yokohama metropolitan areas sustains replacement demand for premium intraocular lens-compatible systems.
- Glaucoma Detection:AI-enhanced visual field algorithms and OCT-based nerve fiber layer analysis are expanding screening into United States primary care referral networks. Early-stage detection protocols are creating new patient access points before specialist referral becomes necessary.
- Retinal Disease Diagnosis:Age-related macular degeneration and diabetic retinopathy monitoring drives continuous imaging demand.
- Corneal Treatment:Cross-linking systems and topography-guided ablation address ectasia and irregular astigmatism.
- Refractive Surgery:LASIK and SMILE procedure volumes fluctuate with consumer discretionary spending cycles.
Cataract Management anchors installed base; Glaucoma Detection is gaining share fastest through AI-enabled screening expansion.
End User:
Facility scale and case complexity determine whether buyers prioritize throughput optimization or specialized diagnostic depth.
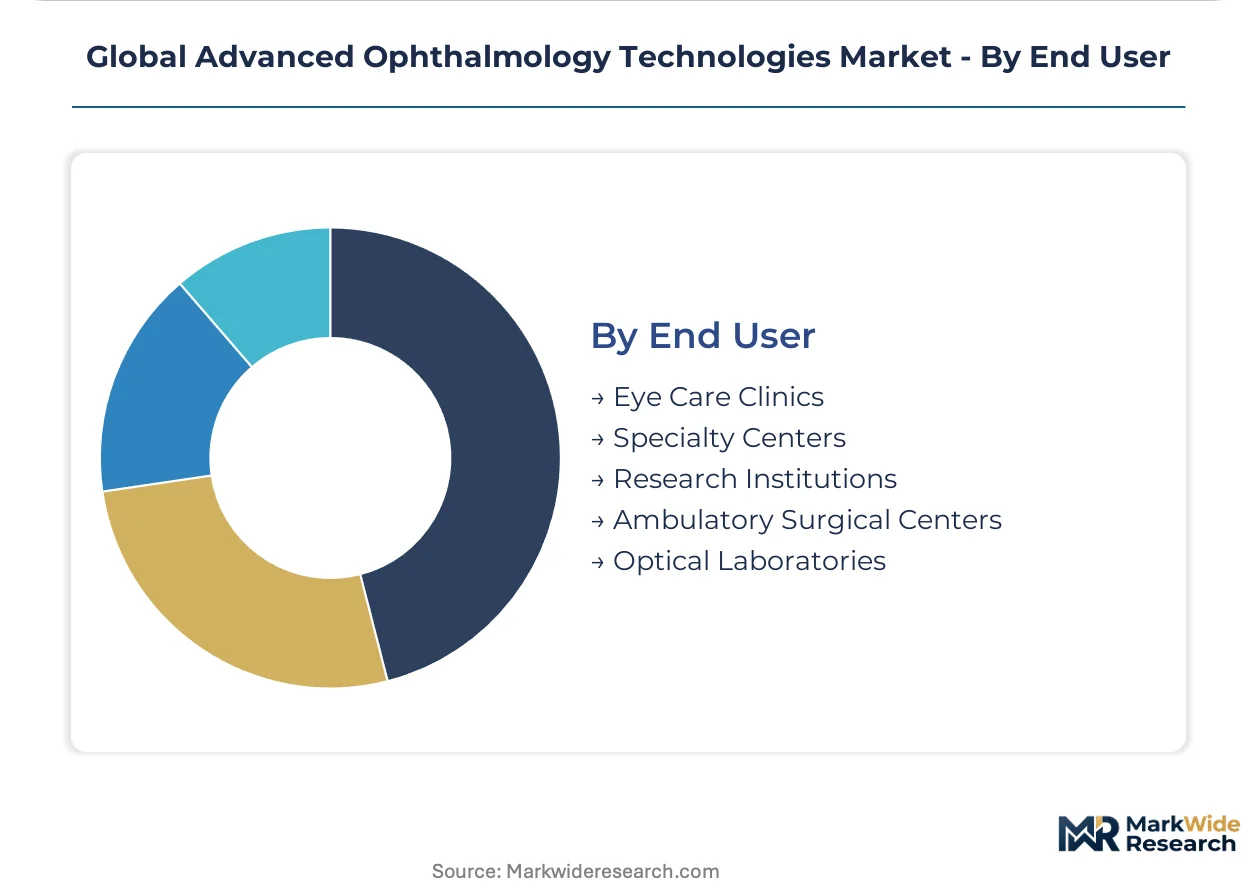
- Eye Care Clinics:Independent and multi-site practices in Texas and California markets are adopting equipment-as-a-service contracting to convert capital expenditures into per-procedure operating costs. Private equity-backed consolidation is centralizing procurement decisions toward standardized vendor relationships.
- Specialty Centers:Retina and cornea-focused institutions require highest-resolution imaging platforms for complex case management. These facilities in Boston and Stuttgart research corridors drive adoption of experimental adaptive optics and OCT angiography configurations.
- Research Institutions:Academic medical centers validate novel biomarkers and algorithmic diagnostic protocols.
- Ambulatory Surgical Centers:Medicare reimbursement stability supports capital investment in integrated diagnostic-surgical platforms.
- Optical Laboratories:Lens manufacturing and surfacing operations utilize wavefront-guided production systems.
Installed base concentrates in Eye Care Clinics; Specialty Centers are expanding most quickly through sub-specialty referral concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States and Germany concentrate manufacturing capacity for precision optoelectronics, while Japan and India absorb expanding diagnostic equipment imports. Consumption gravity shifts toward aging metropolitan clusters in Osaka, Munich, and Dallas-Fort Worth.
United States
Medicare fee schedule stability and private equity-backed clinic consolidation drive capital equipment procurement in Texas and California markets. FDA premarket notification pathways govern Class II ophthalmic laser systems, extending software-as-medical-device review timelines. Dallas-Fort Worth ambulatory surgical centers are standardizing on integrated femtosecond-cataract platforms to compress operating room footprint.
Germany
Engineering-intensive diagnostic imaging demand concentrates in Baden-Württemberg and Bavaria manufacturing corridors. EU MDR clinical evidence requirements force legacy device portfolio refreshes, accelerating technology turnover for established suppliers. Stuttgart metropolitan clusters anchor swept-source laser component production, creating supply concentration for OCT system manufacturers.
Japan
Population cohorts over 65 in Osaka and Yokohama metropolitan areas sustain replacement demand for premium intraocular lens-compatible systems. PMDA enforces JIS-quality benchmarks on imported diagnostic equipment, extending registration timelines for foreign manufacturers without local subsidiary infrastructure. Tokyo academic medical centers validate novel OCT angiography configurations for sub-specialty referral networks.
India
Tier-2 and Tier-3 cities lack spectral-domain OCT density, creating whitespace for mobile screening units and equipment leasing models. CDSCO medical device registration pathways are harmonizing with IMDRF standards, streamlining import clearance for established suppliers. Maharashtra and Karnataka eye care networks are piloting cloud-based image transmission for asynchronous teleophthalmology care models.
United Kingdom
NHS England procurement frameworks prioritize interoperability standards for diagnostic imaging platforms across London and Southeast hospital networks. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while introducing UKCA conformity assessment requirements. Greater Manchester and Birmingham specialty centers are consolidating vendor relationships toward bundled service contracts spanning preoperative imaging through postoperative monitoring.
Global Advanced Ophthalmology Technologies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across diagnostic imaging and surgical laser segments. Market structure tilts toward consolidated tier-one suppliers with captive optoelectronics supply chains and fragmented regional service providers. Three archetypes dominate: integrated platform vendors bundling hardware-software-service workflows, component specialists supplying superluminescent diodes and swept-source lasers, and regional distributors with localized regulatory compliance capabilities. Competitive moves concentrate on strategic partnerships for AI algorithm licensing and backward integration into precision optics manufacturing.
Among Swiss and German precision engineering groups, Alcon and Carl Zeiss Meditec AG occupy positions anchoring integrated diagnostic-surgical platform supply. Japanese equipment specialists represented by NIDEK CO., LTD. and TOPCON CORPORATION exemplify regional compliance differentiation through PMDA-validated quality systems. These named entities represent archetype diversity rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Alcon |
| Carl Zeiss Meditec AG |
| Bausch + Lomb |
| Teva Pharmaceutical Industries Ltd. |
| CooperVision |
| NIDEK CO., LTD. |
| TOPCON CORPORATION |
| Ziemer Ophthalmic Systems AG |
| Essilor International S.A. |
| Others |
Supply & Pricing Matrix
EU MDR clinical evidence renewal mandates gate qualified supply access and premium-tier pricing power for ophthalmic diagnostic platforms, forcing manufacturers to absorb compliance costs or cede position to JIS-certified Japanese competitors.
Pricing Analysis
Cost-down pressure on mid-tier diagnostic equipment accelerates as ambulatory surgical centers consolidate procurement toward bundled per-procedure contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates by software upgrade entitlements and disposable probe compatibility. Price differentiation traces to ISO 13485 certification grade and captive service infrastructure density. Eye care clinics in Texas and California markets exhibit highest price sensitivity, while specialty centers in Boston and Stuttgart research corridors prioritize resolution specifications over acquisition cost.
Supply Chain Analysis
Japan's tightened JIS-quality benchmark enforcement reshapes sourcing patterns for imported diagnostic equipment, compelling foreign manufacturers to establish captive service operations in Osaka and Yokohama. Superluminescent diode and swept-source laser components concentrate among German and Japanese suppliers, creating single-source vulnerability for OCT system manufacturers. Raw material dependencies center on precision optics substrates, rare-earth doped fibers, and high-speed analog-to-digital converters. Distribution runs through regional distributors with localized PMDA compliance capabilities and hospital system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swept-source optical coherence tomography is displacing legacy spectral-domain configurations across ambulatory surgical centers, compressing replacement cycles and redirecting R&D investment toward multimodal algorithm development.
For Market Incumbents: Deploy AI algorithm licensing partnerships to defend diagnostic platform attach rates against pure-play software entrants. Deepen backward integration into superluminescent diode production to reduce German and Japanese component supplier dependency. Accelerate JIS-quality benchmark certification investment to preempt PMDA registration timeline extension for legacy device renewals. For New Entrants and Emerging Players: CDSCO harmonization with IMDRF standards in India opens a window for mobile screening unit deployment across Tier-2 and Tier-3 cities lacking spectral-domain OCT density. Target equipment-as-a-service contracting models to bypass capital expenditure barriers among private equity-backed clinic consolidations. Pursue cloud-based image transmission integration with Maharashtra and Karnataka eye care networks piloting asynchronous teleophthalmology protocols. For Investors and Strategic Acquirers: FDA premarket notification timeline extension for Class II ophthalmic laser systems is the leading indicator that software-as-medical-device complexity will elevate compliance moats for established suppliers. Focus acquisition screening on component specialists with swept-source laser expertise and regional distributors holding PMDA-validated quality systems. Monitor EU MDR legacy device renewal failure rates as inflection signal for portfolio consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing Partnership | Carl Zeiss Meditec AG and Alcon secure diagnostic platform differentiation through embedded machine learning workflows. |
| JIS-Quality Benchmark Certification | Foreign manufacturers establish compliance moats against PMDA registration timeline extension in Japanese metropolitan clusters. |
| Equipment-as-a-Service Contracting | Private equity-backed Texas and California clinics convert capital expenditures to per-procedure operating costs. |
| Backward Integration into Optoelectronics | OCT system manufacturers reduce single-source vulnerability to German and Japanese superluminescent diode suppliers. |
| Teleophthalmology Platform Integration | Cloud-based image transmission enables Maharashtra and Karnataka networks to pilot asynchronous care models. |
Research Methodology
FDA 510(k) premarket notifications, EU MDR clinical evidence databases, and PMDA registration filings formed the secondary backbone, cross-referenced with primary interviews across ophthalmic device product managers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure tracking were triangulated against reimbursement code utilization data from Medicare fee schedules and national health insurance systems.
Historical trendline analysis of diagnostic device replacement cycles and surgical laser system depreciation schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology configuration, application area, and end-user facility scale. CAGRs were derived from installed base growth trajectories and procedure volume elasticity to reimbursement stability. Forecast inputs incorporated AI-enhanced screening protocol adoption curves and ambulatory surgical center consolidation patterns.
Caveats apply where FDA software-as-medical-device guidance evolution or EU MDR clinical evidence requirement tightening could materially shift the outlook for Class II ophthalmic laser system approvals. Forecasts reflect assumptions regarding reimbursement code stability and optoelectronics component supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Coloured Contact Lenses Market