
 Laboratory Temperature Control Units Market | 2026-2036
Laboratory Temperature Control Units Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Temperature Control Units Market Analysis
The capital-intensity divergence between full-system manufacturers and component assemblers is redrawing competitive boundaries in laboratory temperature control. Thermo Fisher Scientific leverages its vertically integrated supply chain to dominate high-throughput pharmaceutical installations. JULABO GmbH anchors its position through deep specialization in liquid-cooled circulators for precision thermal management. Peter Huber Kaltemaschinenbau AG differentiates via extreme-temperature cascade systems that sustain premium positioning in material testing applications.
Laboratory temperature control units are electromechanical systems that maintain precise thermal conditions for samples, reagents, and processes, typically achieving setpoint stability within ±0.01°C through PID-controlled compressor or thermoelectric modules. These systems serve as critical infrastructure for reproducibility in pharmaceutical development, clinical diagnostics, and advanced materials characterization. Refrigerators and freezers capture the largest installed base due to ubiquitous biological storage requirements across research laboratories and hospitals. Liquid cooling technology is gaining share in pharmaceutical research applications where rapid heat removal and tight uniformity specifications justify higher capital expenditure. Natural refrigerant architectures are emerging as the fastest-growing technology segment as regulatory pressure on synthetic fluorocarbon alternatives intensifies.
The EPA's AIM Act mandates phased reductions in hydrofluorocarbon production, forcing manufacturers to redesign compressor platforms and accelerating replacement demand from laboratories with aging equipment. ISO 9001 quality management and IEC 61010 safety standards govern product certification, creating compliance barriers that favor established players with dedicated regulatory affairs capabilities. Stakeholders must monitor refrigerant transition timelines and energy efficiency benchmarking to align procurement strategies with tightening operational cost and sustainability requirements.
Market Dynamics
The EPA's AIM Act mandates phased reductions in hydrofluorocarbon production, forcing compressor redesigns and accelerating replacement cycles for laboratory equipment with aging refrigerant architectures. This regulatory pressure is compressing product lifecycles while elevating capital requirements for compliance.
Growth Catalysts
- Biologics cold-chain expansion:Pharmaceutical manufacturers are scaling refrigerated storage infrastructure to support temperature-sensitive monoclonal antibody and cell therapy production, with Germany's precision engineering clusters deepening technical specialization in ultra-low temperature systems.
- F-Gas Regulation:The European Union's phasedown of fluorinated greenhouse gases is creating replacement demand across research institutions with legacy equipment, accelerating procurement of natural refrigerant platforms.
- Liquid cooling adoption:Rapid heat removal requirements in high-throughput pharmaceutical screening are displacing air-cooled alternatives in facilities requiring tight thermal uniformity specifications.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger materials face commodity price swings that compress margin predictability for component assemblers without captive metal sourcing.
- Compressor supply concentration:Precision scroll and reciprocating compressor manufacturing concentrates among German and Japanese suppliers, creating bottleneck risk for system integrators.
- Technical limitation in cascade efficiency:Extreme-temperature systems below -80°C suffer from refrigerant miscibility challenges that limit coefficient of performance and elevate energy consumption.
Strategic Opportunities
- India's pharmaceutical manufacturing expansion:CDSCO licensing requirements for biological product storage are creating demand for validated cold-chain equipment in contract research and manufacturing organizations.
- Service unbundling:Predictive maintenance contracts and remote monitoring subscriptions are emerging as separate revenue streams distinct from capital equipment sales.
- ISO 9001 certification premium:Quality management certification is becoming a procurement gate for multinational pharmaceutical buyers, creating margin differentiation for compliant suppliers.
Industry Challenges
- Refrigerant transition engineering:Redesigning compressor platforms for R-290 propane or CO2 architectures requires thermodynamic expertise that concentrates among aging specialist workforces in Germany and Japan.
- IEC 61010 safety certification timelines:Third-party electrical safety testing for new product platforms extends launch schedules by 6-12 months, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Temperature Control Units Market |
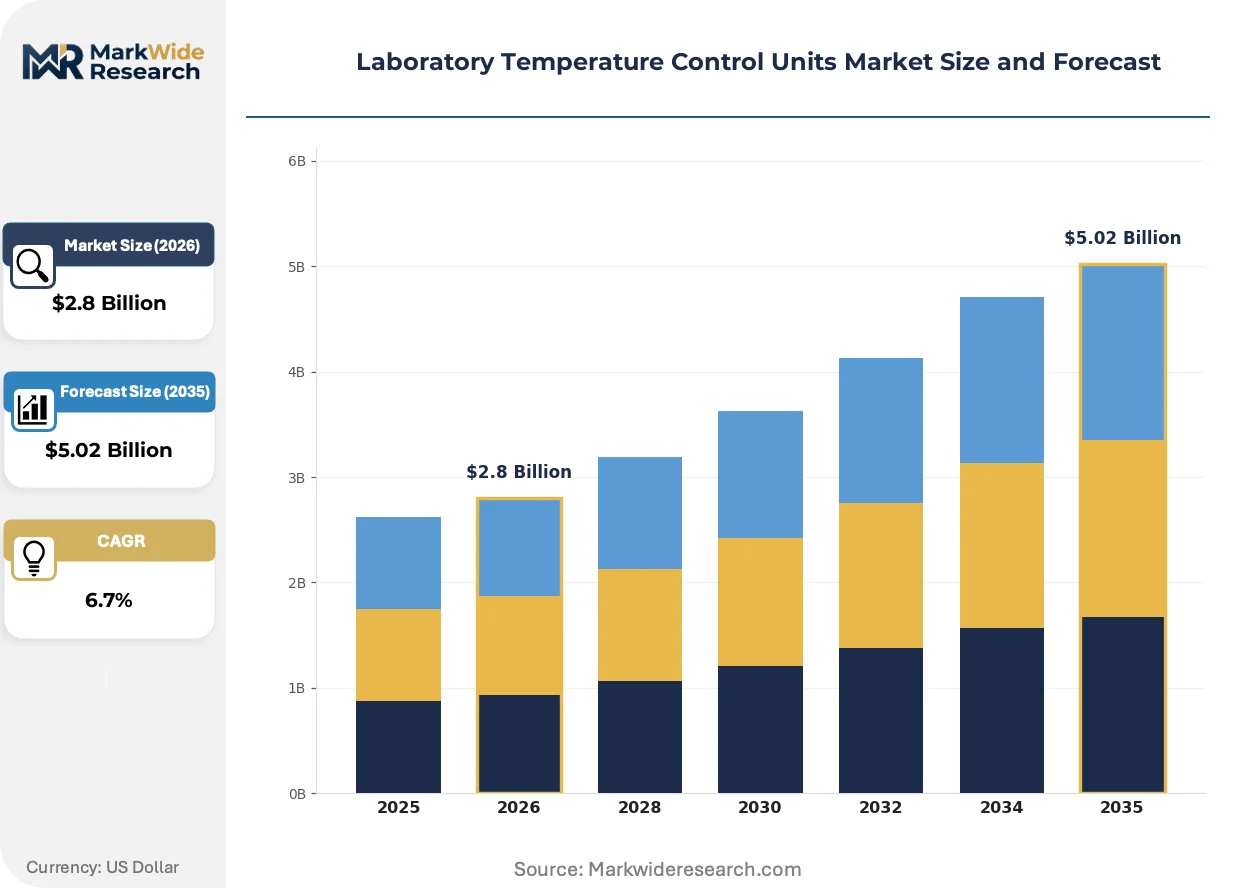
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Thermostats, Incubators Technology: Natural Refrigerants, Cascade Systems, Air Cooling, Liquid Cooling Application: Biological Storage, Chemical Processing, Material Testing, Pharmaceutical Research End User: Research Laboratories, Hospitals, Pharmaceutical Companies, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, LAUDA DR R WOBSER, JULABO GmbH, IKA, Peter Huber Kaltemaschinenbau AG, PolyScience, Delta T Systems, FRYKA-Kältetechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Temperature Control Units Market Emerging Trajectories
Thermoelectric cooling modules and natural refrigerant architectures are actively displacing legacy hydrofluorocarbon-based systems across precision laboratory applications. Equipment manufacturers are reconfiguring supply chains and R&D priorities around these platform shifts.
Modular thermoelectric assemblies are decomposing the traditional compressor-refrigerant paradigm in benchtop and portable temperature control devices. Pharmaceutical quality control laboratories are adopting these solid-state systems for rapid setpoint cycling in stability testing protocols. The technology is decomposing the service revenue model by eliminating compressor maintenance intervals and reducing field technician dependency.
REACH authorization requirements for synthetic refrigerants are compressing the viable product portfolio for European laboratory equipment suppliers. Manufacturers must now submit comprehensive chemical safety dossiers for fluorocarbon alternatives or pivot to natural refrigerant platforms. Biobanking and clinical diagnostics segments are responding fastest, with German and Swiss facilities leading retrofit investments.
Pharmaceutical procurement teams are consolidating supplier relationships around full-lifecycle service accountability rather than discrete equipment transactions. Large contract research organizations are displacing fragmented local vendor networks with preferred provider agreements spanning multiple continents. This concentration is most visible in North America and Western Europe, where Merck KGaA and Thermo Fisher Scientific procurement frameworks are reshaping competitive access.
Laboratory Temperature Control Units Market Segmentation
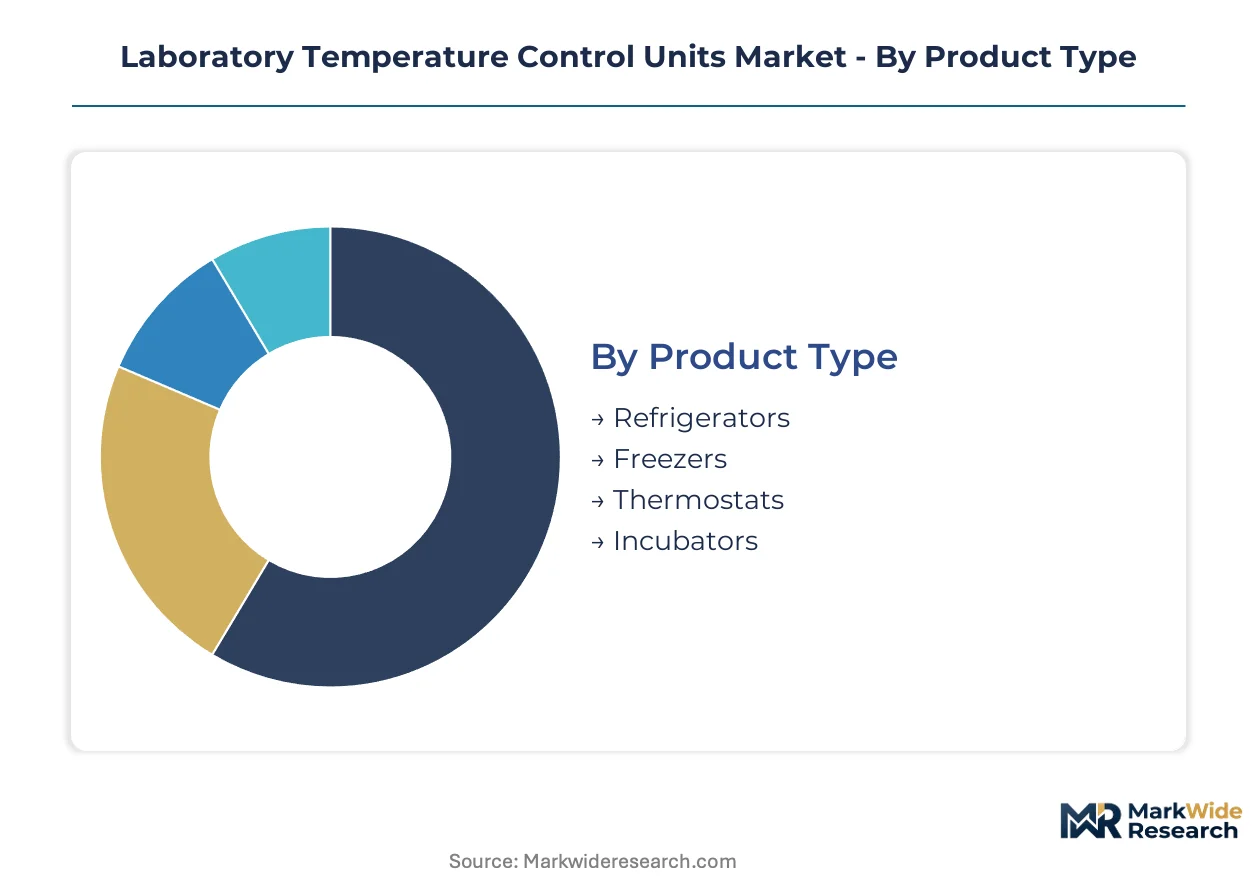
Laboratory temperature control units fragment across four intersecting dimensions that determine procurement priorities and supplier positioning. Product type and technology choices dominate capital allocation decisions, while application specificity and end-user scale shape service requirements and compliance intensity.
Product Type:
Margin pools concentrate in ultra-low temperature systems where engineering complexity sustains premium pricing, while standard refrigeration fights commodity pressure.
- Refrigerators:These units maintain 2°C to 8°C for routine biological sample storage and reagent preservation. Hospital pharmacies and clinical diagnostic laboratories in Germany and Switzerland drive replacement demand as F-Gas Regulation deadlines approach.
- Freezers:Ultra-low temperature variants sustaining -80°C serve biobanking infrastructure and cell therapy manufacturing. The biologics cold-chain expansion across North American pharmaceutical manufacturing sites is accelerating procurement of cascade-compressor platforms with natural refrigerant architectures.
- Thermostats:Precision thermal cycling devices support PCR workflows and enzyme reaction control. Academic research budgets constrain pricing flexibility in this segment.
- Incubators:CO2-controlled environments enable cell culture propagation with humidity and contamination management. Contract research organizations in India are scaling incubator installations to meet CDSCO biological product storage requirements.
The dominant share belongs to refrigerators, while freezers are closing the gap fastest.
Technology:
Technology selection increasingly reflects regulatory compliance timelines rather than pure thermodynamic efficiency, with refrigerant chemistry driving platform transitions.
- Natural Refrigerants:R-290 propane and CO2 architectures eliminate synthetic fluorocarbon regulatory exposure. European REACH authorization requirements are compressing viable portfolios for legacy refrigerant platforms, with German and Swiss facilities leading retrofit investments.
- Cascade Systems:Stacked compressor stages achieve temperatures below -80°C for material testing and cryopreservation. The technical limitation in refrigerant miscibility below this threshold elevates energy consumption and sustains engineering specialization around German precision manufacturing clusters.
- Air Cooling:Convective heat rejection dominates entry-level benchtop equipment. Copper and aluminum input volatility compresses margin predictability for component assemblers without captive metal sourcing.
- Liquid Cooling:Forced circulation through heat exchangers delivers rapid thermal uniformity for high-throughput pharmaceutical screening. Liquid cooling adoption is displacing air-cooled alternatives where tight specifications justify higher capital expenditure.
Natural refrigerants command the steepest expansion trajectory, though cascade systems retain the highest absolute margins.
Application:
Application segmentation tracks the divergence between regulated pharmaceutical environments and exploratory research settings.
- Biological Storage:Temperature-controlled preservation of cell lines, tissues, and blood products demands validated cold-chain documentation. Biobanking and clinical diagnostics segments are responding fastest to refrigerant transition mandates.
- Chemical Processing:Reaction temperature control for synthesis and crystallization operations. Specialty chemical manufacturers prioritize setpoint stability over extreme temperature reach.
- Material Testing:Thermal cycling and environmental simulation for polymer and composite characterization. Peter Huber Kaltemaschinenbau AG anchors positioning here through extreme-temperature cascade specialization.
- Pharmaceutical Research:High-throughput screening and stability testing protocols. Thermo Fisher Scientific leverages vertically integrated supply chains to dominate these pharmaceutical installations.
Biological storage holds the largest installed base, while pharmaceutical research is expanding most quickly.
End User:
End-user scale determines whether procurement emphasizes capital efficiency or full-lifecycle service accountability.
- Research Laboratories:Academic and government facilities with fragmented vendor relationships and maintenance budget constraints. Modular thermoelectric assemblies are decomposing traditional compressor-refrigerant paradigms in this segment.
- Hospitals:Clinical diagnostic and pharmacy operations requiring 24/7 uptime guarantees. ISO 9001 certification is becoming a procurement gate for multinational healthcare buyers.
- Pharmaceutical Companies:Large-scale manufacturing and quality control with consolidated supplier frameworks. Merck KGaA and Thermo Fisher Scientific procurement frameworks are reshaping competitive access in North America and Western Europe.
- Academic Institutions:Teaching and fundamental research with cyclical funding patterns. Predictive maintenance contracts and remote monitoring subscriptions are emerging as separate revenue streams distinct from capital equipment sales.
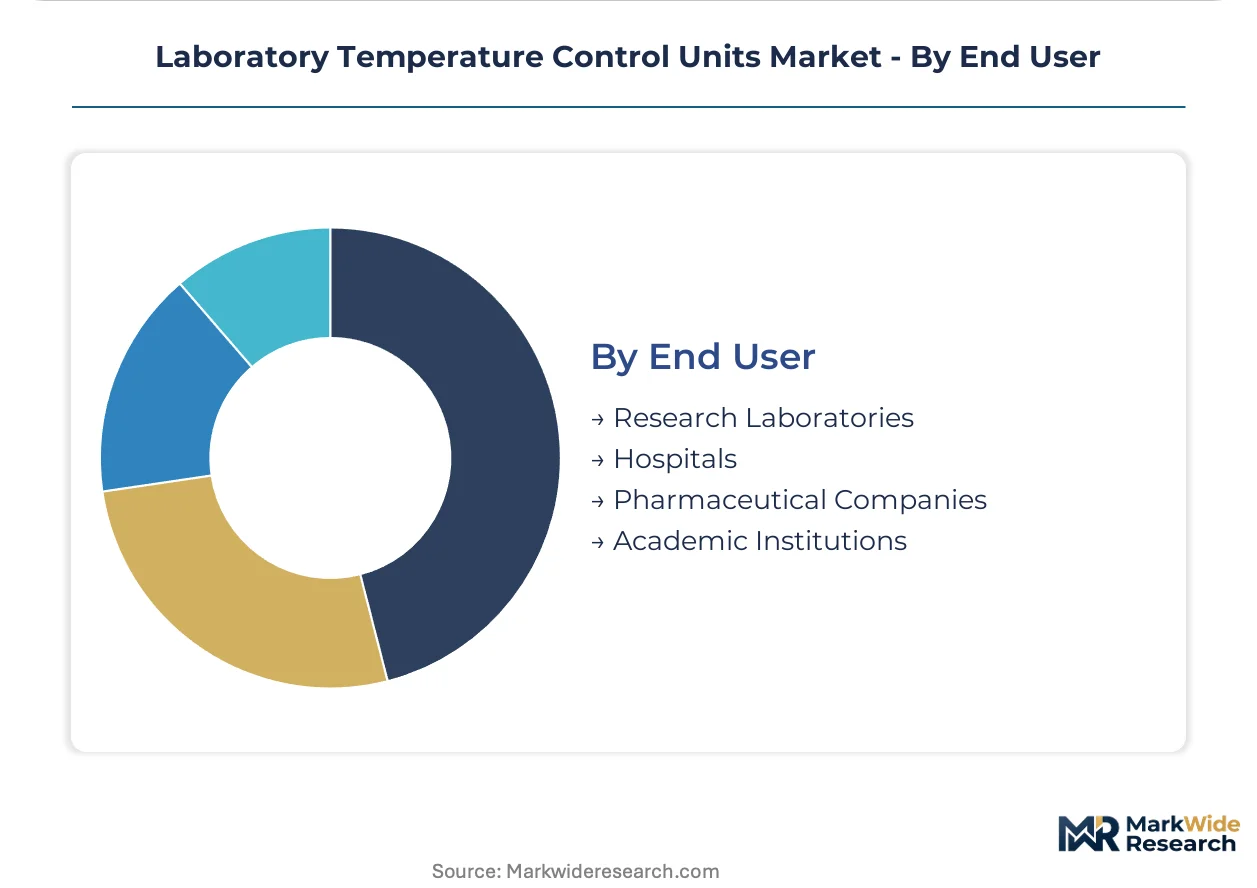
Pharmaceutical companies generate the highest revenue per installation, while research laboratories constitute the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision engineering clusters, while North American pharmaceutical procurement frameworks compress supplier margins through consolidated vendor agreements.
United States
Pharmaceutical cold-chain infrastructure expansion and biobanking facility construction drive equipment procurement. The EPA's AIM Act mandates hydrofluorocarbon phasedowns, accelerating replacement cycles for aging laboratory refrigeration. Greater Boston's biotech corridor concentrates demand for ultra-low temperature cascade systems serving cell therapy manufacturing.
Germany
Precision engineering specialization in liquid-cooled circulators and extreme-temperature platforms sustains export competitiveness. The F-Gas Regulation forces refrigerant platform transitions across research institutions. Stuttgart and Karlsruhe engineering clusters deepen technical capabilities in natural refrigerant compressor architectures.
Switzerland
Clinical diagnostics and biobanking segments prioritize validated cold-chain documentation for biological storage. Swissmedic quality requirements elevate certification barriers for equipment suppliers. Basel's pharmaceutical manufacturing concentration generates premium-tier demand for full-lifecycle service accountability.
India
Contract research organization expansion and CDSCO biological product storage licensing create validated equipment demand. Central Drugs Standard Control Organization requirements reshape procurement specifications for cold-chain infrastructure. Maharashtra's pharmaceutical manufacturing belt scales incubator and refrigerated storage installations.
Japan
Materials testing and advanced characterization applications sustain demand for extreme-temperature thermal cycling platforms. METI energy efficiency benchmarks compress acceptable operating cost parameters for laboratory equipment. Osaka-Kobe industrial corridor maintains specialized compressor manufacturing capabilities for precision temperature control systems.
Laboratory Temperature Control Units Market Vendor Landscape
Concentration sits with vertically integrated full-system manufacturers commanding pharmaceutical procurement frameworks, while component assemblers face margin compression from copper and aluminum input volatility. The vendor base stratifies across three archetypes: diversified life science conglomerates with captive distribution networks, German precision engineering specialists with deep thermodynamic expertise, and regional fabricators serving price-sensitive academic segments. Dominant competitive moves include backward integration into compressor platform development and geographic expansion through preferred provider agreements with multinational contract research organizations.
Within the diversified conglomerate tier, Thermo Fisher Scientific exemplifies scale-driven positioning through vertically integrated supply chain control. Among German precision specialists, JULABO GmbH and Peter Huber Kaltemaschinenbau AG occupy positions anchored in liquid-cooled circulator and extreme-temperature cascade specialization respectively. These archetypes represent divergent strategic bets on whether pharmaceutical procurement consolidation or engineering premiumization offers more durable margin protection.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| LAUDA DR R WOBSER |
| JULABO GmbH |
| IKA |
| Peter Huber Kaltemaschinenbau AG |
| PolyScience |
| Delta T Systems |
| FRYKA-Kältetechnik |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between pharmaceutical manufacturers and German precision engineering suppliers lock in compressor platform allocation and stabilize unit economics across refrigerant transition cycles. These contracts insulate tier-one system integrators from copper and aluminum spot volatility while compressing margin visibility for component assemblers locked into spot procurement.
Pricing Analysis
Configured-to-order pricing commands a 25-40% premium over standard catalog configurations in ultra-low temperature cascade systems. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 certification grade and after-sales service bundling rather than raw thermodynamic performance. Price erosion runs through economy-tier benchtop equipment as modular thermoelectric assemblies displace compressor-refrigerant architectures. Academic research laboratories exhibit highest price sensitivity, while pharmaceutical quality control operations prioritize lifecycle cost over capital outlay.
Supply Chain Analysis
Strategic stockpiling of precision scroll compressors dominates procurement behavior among North American system integrators facing German and Japanese supply concentration. Heat exchanger fabrication draws from German, Japanese, and Chinese metalworking clusters dependent on copper and aluminum coil supply. Single-source vulnerability concentrates in proprietary compressor controller firmware developed by Stuttgart engineering houses. Distribution runs through life science distributor networks and direct OEM procurement teams serving multinational pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural refrigerant platform transitions are reconfiguring the laboratory temperature control ecosystem around interoperability standards for compressor controllers and remote monitoring protocols. This interoperability shift favors suppliers with captive R&D capacity over component assemblers dependent on third-party thermodynamic expertise.
For Market Incumbents: Fortify backward integration into natural refrigerant compressor development to defend against margin compression from German specialist suppliers. Prioritize IEC 61010 pre-certification investments that accelerate product launch timelines relative to competitors navigating extended safety testing cycles. Lock in preferred provider agreements with contract research organizations before procurement consolidation completes across North America and Western Europe. For New Entrants and Emerging Players: Anchor in India's contract research organization expansion, where CDSCO licensing requirements for biological storage create validated equipment demand without entrenched incumbent relationships. Target modular thermoelectric assemblies for academic research segments where elimination of compressor maintenance intervals decomposes traditional service revenue models. Pursue remote monitoring subscription offerings as a capital-light entry vector distinct from equipment manufacturing. For Investors and Strategic Acquirers: The market sits at a refrigerant-mandate implementation phase that favors precision engineering specialists with proprietary thermodynamic expertise over diversified conglomerates with broad life science exposure. Acquisition candidates should demonstrate captive natural refrigerant platform development and established regulatory affairs capabilities spanning EPA AIM Act and EU F-Gas Regulation compliance. Watch refrigerant transition timeline acceleration as the primary inflection signal warranting portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Development | EPA AIM Act compliance secures North American market access for redesigned compressor architectures. |
| Predictive Maintenance Service Unbundling | Remote monitoring subscriptions generate recurring revenue distinct from capital equipment transactions. |
| ISO 9001 Certification Investment | Quality management certification opens procurement gates at Merck KGaA and Thermo Fisher Scientific. |
| India Geographic Expansion | CDSCO licensing requirements reshape cold-chain procurement specifications in Maharashtra's pharmaceutical belt. |
| Thermoelectric Module Integration | Solid-state cooling eliminates compressor maintenance intervals and reduces field technician dependency. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association disclosures, and equipment procurement databases. Primary interviews engaged R&D directors at precision engineering specialists, procurement managers at contract research organizations, and regulatory affairs leads navigating EPA and ECHA compliance timelines. Secondary validation drew from EPA AIM Act implementation notices, EU F-Gas Regulation amendment tracking, and ISO certification registry data. Bottom-up unit economics modeling triangulates against top-down market sizing across product type and technology segmentation.
Segmentation dimensions modeled include product type, cooling technology, application specificity, and end-user scale across the projection horizon. CAGRs derive from installed base replacement cycle analysis and refrigerant mandate compliance timelines. Forecast inputs incorporate compressor platform development lead times, third-party electrical safety certification durations, and pharmaceutical capital expenditure survey data.
Material uncertainties — refrigerant transition timeline delays, copper price volatility spikes, and compressor supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory implementation adherence and supply chain continuity. Revision becomes warranted when natural refrigerant adoption rates diverge materially from mandate-driven projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market