
 Automated Plate Readers Market | 2026-2036
Automated Plate Readers Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Plate Readers Market Outlook
Modular instrument configurations paired with subscription-based software access is broadening procurement options for mid-sized laboratories. Thermo Fisher Scientific leverages its global service infrastructure to sustain instrument placement across pharmaceutical contract research networks. BMG Labtech specializes in application-specific optical modules that differentiate its portfolio in drug discovery screening workflows. Tecan Group controls automated liquid handling integration points that anchor its plate reader positioning within complete workflow solutions.
Automated plate readers are optical detection instruments engineered to measure absorbance, fluorescence, luminescence, and polarization across microplate formats ranging from 6 to 1536 wells, serving as central analytical engines in quantitative biology and diagnostic testing. Their primary commercial purpose centers on accelerating sample throughput while preserving data traceability for regulated research environments. Compact readers capture dominant placement volume in academic and clinical settings where bench space constraints limit instrument footprint, while high-throughput readers command premium positioning in pharmaceutical compound screening where parallel processing of multi-million sample libraries defines operational economics. RFID-enabled tracking modules represent the fastest-expanding technology segment as laboratories prioritize chain-of-custody documentation for audit readiness.
FDA 21 CFR Part 11 electronic records requirements shape software validation protocols and data integrity architectures, directly influencing vendor development roadmaps and buyer upgrade cycles. EU MDR and REACH compliance frameworks govern material biocompatibility and reagent traceability standards for instruments deployed in clinical diagnostic settings across European member states. Stakeholders must monitor evolving harmonization between FDA quality system regulation and EU IVDR requirements to anticipate compliance-driven replacement demand and inform regional product certification strategies.
Market Dynamics
Pharmaceutical contract research networks are consolidating screening operations into centralized facilities, compressing procurement cycles and forcing vendors to bundle hardware with compliance-validated software architectures that satisfy FDA 21 CFR Part 11 audit requirements.
Growth Catalysts
- EU MDR diagnostic infrastructure mandates:Clinical laboratories across Germany, France, and Italy face mandatory replacement timelines for legacy manual systems, creating replacement demand for traceability-enabled automated readers.
- High-throughput compound libraries:Pharmaceutical discovery pipelines now routinely screen multi-million sample sets, making parallel optical detection an operational necessity rather than efficiency preference.
- RFID tracking modules:Chain-of-custody documentation requirements in biobanking networks are accelerating placement of readers with integrated sample tracking capabilities.
Market Restraints
- Precision optical component supply:German and Japanese suppliers dominate photomultiplier tube and laser diode production, creating single-source vulnerability for instrument manufacturers.
- Software validation cost structure:FDA 21 CFR Part 11 compliance documentation adds eighteen to twenty-four months to product release cycles, compressing vendor R&D returns.
- Manual microscopy workflows:Academic pathology laboratories continue using conventional imaging for low-throughput applications, limiting automated reader penetration in education segments.
Strategic Opportunities
- India biobanking expansion:CDSCO-regulated clinical trial infrastructure and government-funded precision medicine initiatives are creating first-mover advantage for vendors establishing local service presence.
- CRISPR screening convergence:Integration of automated plate readers with gene editing validation workflows opens application expansion beyond traditional pharmaceutical screening.
- Subscription software access:Mid-sized biotechnology firms are adopting SaaS-based data analysis packages that reduce upfront capital requirements and accelerate instrument procurement decisions.
Industry Challenges
- Multidisciplinary field service engineering:Maintenance of integrated optical-mechanical-electronic systems requires rare combinations of photonics, fluidics, and software diagnostics expertise that outpaces training pipeline output.
- Legacy LIMS integration:Pharmaceutical quality control laboratories operate decade-old laboratory information management systems that resist API-based connectivity with modern reader data formats, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Plate Readers Market |
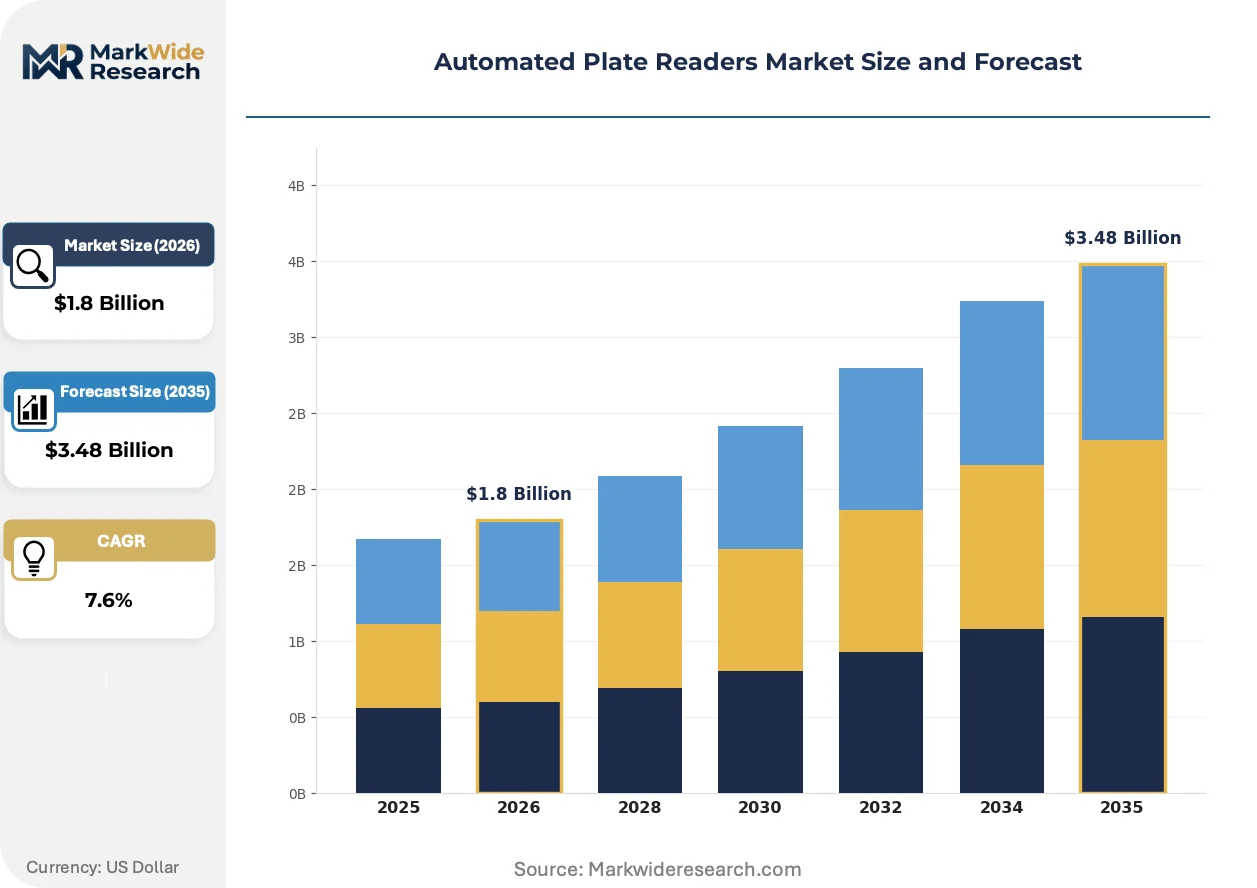
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Readers, High-Throughput Readers, Fixed Readers, Mobile Readers Technology: Optical Recognition, Infrared Processing, Image Capture, RFID End User: Law Enforcement, Logistics Companies, Toll Authorities, Healthcare Facilities Application: Traffic Management, Access Control, Parking Management, Fleet Tracking |
| Companies Covered | Agilent Technologies, PerkinElmer, Thermo Fisher Scientific, BMG Labtech, Eppendorf, Tecan Group, Molecular Devices, Berthold Technologies, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Plate Readers Market Strategic Shifts
Instrument architectures are converging around modular optical paths and cloud-native data platforms, compressing the traditional boundary between hardware procurement and software subscription while enabling remote diagnostic capabilities that reduce field service dependency.
Multimodal detection engines is consolidating discrete absorbance, fluorescence, and luminescence capabilities into single optical benches with interchangeable filter modules. Pharmaceutical screening facilities in Massachusetts and California are adopting these consolidated platforms to reduce bench space requirements and standardize operator training across assay types. The consolidation is compressing vendor R&D budgets previously allocated to standalone instrument lines while elevating software differentiation as the primary competitive battleground.
REACH substance restriction amendments are forcing European instrument manufacturers to reformulate optical coatings and electronic solder compositions to eliminate restricted heavy metals. German and Swiss production facilities face twelve-to-eighteen month material qualification timelines that delay product launches relative to North American competitors. Diagnostic instrument categories with direct patient contact face the most stringent material documentation requirements, pushing some vendors toward modular designs that segregate regulated from non-regulated components.
Consolidated procurement through pharmaceutical central purchasing departments is displacing decentralized laboratory manager autonomy over instrument selection. Contract research organizations in the United States and United Kingdom now route plate reader acquisitions through global category managers who negotiate enterprise-wide pricing and service level agreements. This concentration is compressing regional vendor margins while elevating importance of referenceable installations at flagship pharmaceutical headquarters facilities.
Automated Plate Readers Market Segmentation
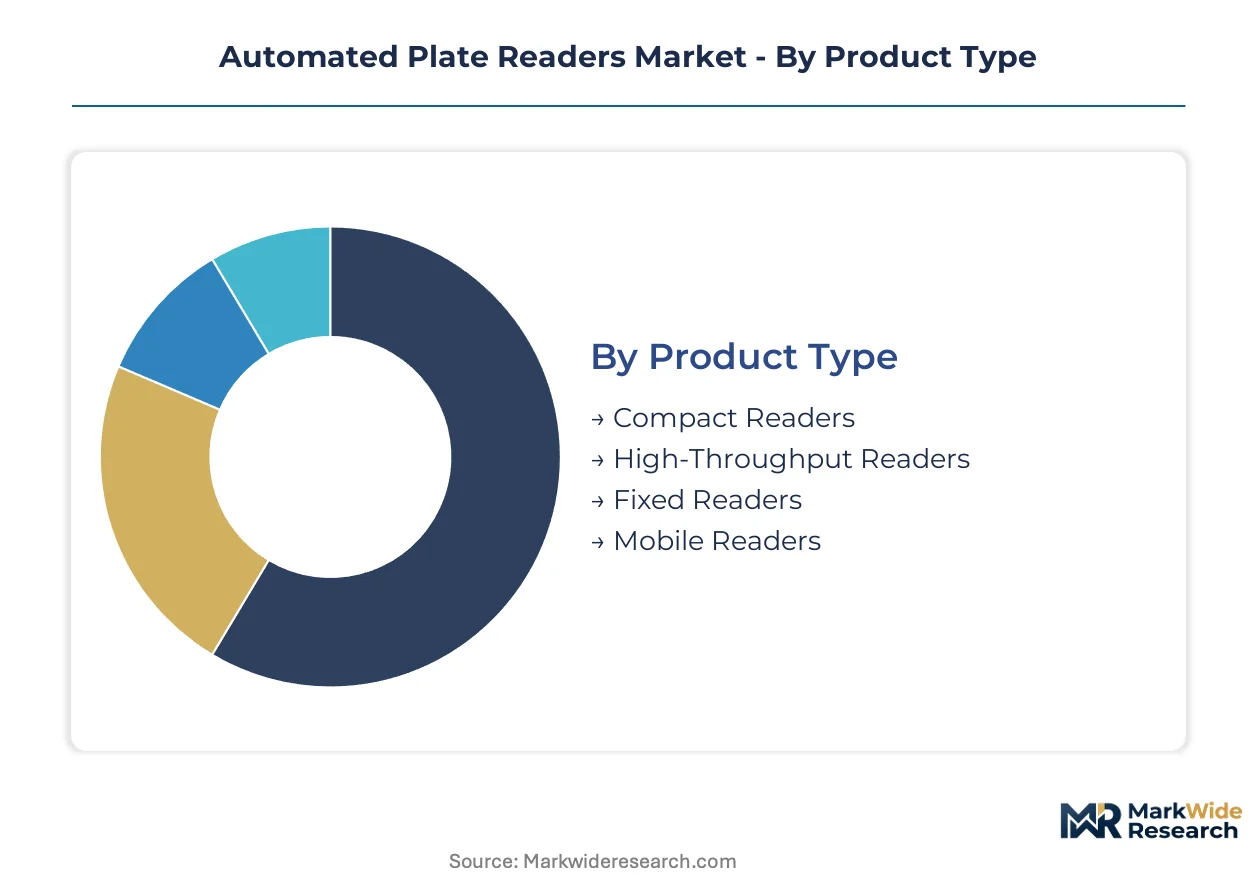
Automated plate reader procurement varies sharply by operational environment, with pharmaceutical laboratories prioritizing optical precision while biobanking networks emphasize sample traceability. Segment-specific requirements around FDA 21 CFR Part 11 validation and EU MDR compliance create divergent vendor development priorities.
Product Type:
Supply concentration in photonics manufacturing favors vendors with captive optical component sourcing or long-term supplier contracts.
- Compact Readers:Benchtop units with 6-384 well capacity dominate academic and clinical settings where space constraints limit instrument footprint. Demand concentrates in United States research universities and German university hospital networks where federal funding sustains equipment refresh cycles.
- High-Throughput Readers:Parallel processing architectures handle 1536-well formats and multi-million sample libraries. Pharmaceutical contract research facilities in Massachusetts and California anchor demand, with compound screening throughput directly determining operational economics.
- Fixed Readers:Permanent installation configurations serve dedicated screening lines with minimal reconfiguration requirements.
- Mobile Readers:Portable units with battery power and wireless data transmission support field-based sample analysis and temporary laboratory setups.
Compact readers absorb the bulk of installed capacity; high-throughput readers are expanding most quickly.
Technology:
Cost tier differentiation separates premium multimodal engines from single-mode entry systems, with software subscription bundling compressing upfront hardware margins.
- Optical Recognition:Absorbance, fluorescence, and luminescence detection through filter-based or monochromator optical paths. Mid-sized biotechnology firms in United States and China favor modular configurations that reduce per-assay capital intensity through shared hardware platforms.
- RFID:Integrated radio-frequency identification modules enable real-time sample tracking and chain-of-custody documentation. Biobanking networks in Germany and China mandate RFID capabilities for audit readiness under tightening regulatory documentation requirements.
- Infrared Processing:Near-infrared detection for label-free assay formats and specialized biochemical applications.
- Image Capture:CCD and CMOS-based imaging for cellular analysis and morphometric quantification workflows.
Optical recognition retains dominant placement share; RFID capabilities are climbing the fastest as traceability mandates spread.
End User:
Application concentration in drug discovery creates volume concentration among pharmaceutical and contract research segments, with clinical diagnostic users driving compliance-validated feature development.
- Healthcare Facilities:Hospital laboratories and clinical diagnostic centers require FDA-cleared or CE-marked instruments with validated software for patient sample testing. German clinical laboratories face mandatory EU MDR transition timelines that compress replacement windows.
- Logistics Companies:Biobanking and sample transport networks deploy readers for intake verification and custody transfer documentation. Cold chain logistics providers in United States and China integrate readers with temperature monitoring systems for regenerative medicine shipments.
- Law Enforcement:Forensic laboratories use readers for DNA quantification and evidentiary sample processing.
- Toll Authorities:Government and municipal facilities with specialized identification requirements.
Healthcare facilities command premium pricing tiers; logistics companies are gaining share fastest as biobanking networks expand.
Application:
Customer type maturity separates regulated pharmaceutical environments from emerging precision medicine applications, with reimbursement pathways determining adoption velocity in clinical segments.
- Traffic Management:High-volume compound screening and lead optimization workflows in pharmaceutical discovery pipelines. Massachusetts and California facilities process multi-million sample libraries annually, making parallel detection capacity an operational necessity.
- Access Control:Secure sample handling and restricted reagent access in biobanking and clinical trial material management. Centralized biorepositories in Germany and China deploy integrated reader-access systems for regulatory compliance.
- Parking Management:Fleet and asset tracking applications with specialized identification requirements.
- Fleet Tracking:Mobile laboratory and distributed screening operations requiring portable detection capabilities.
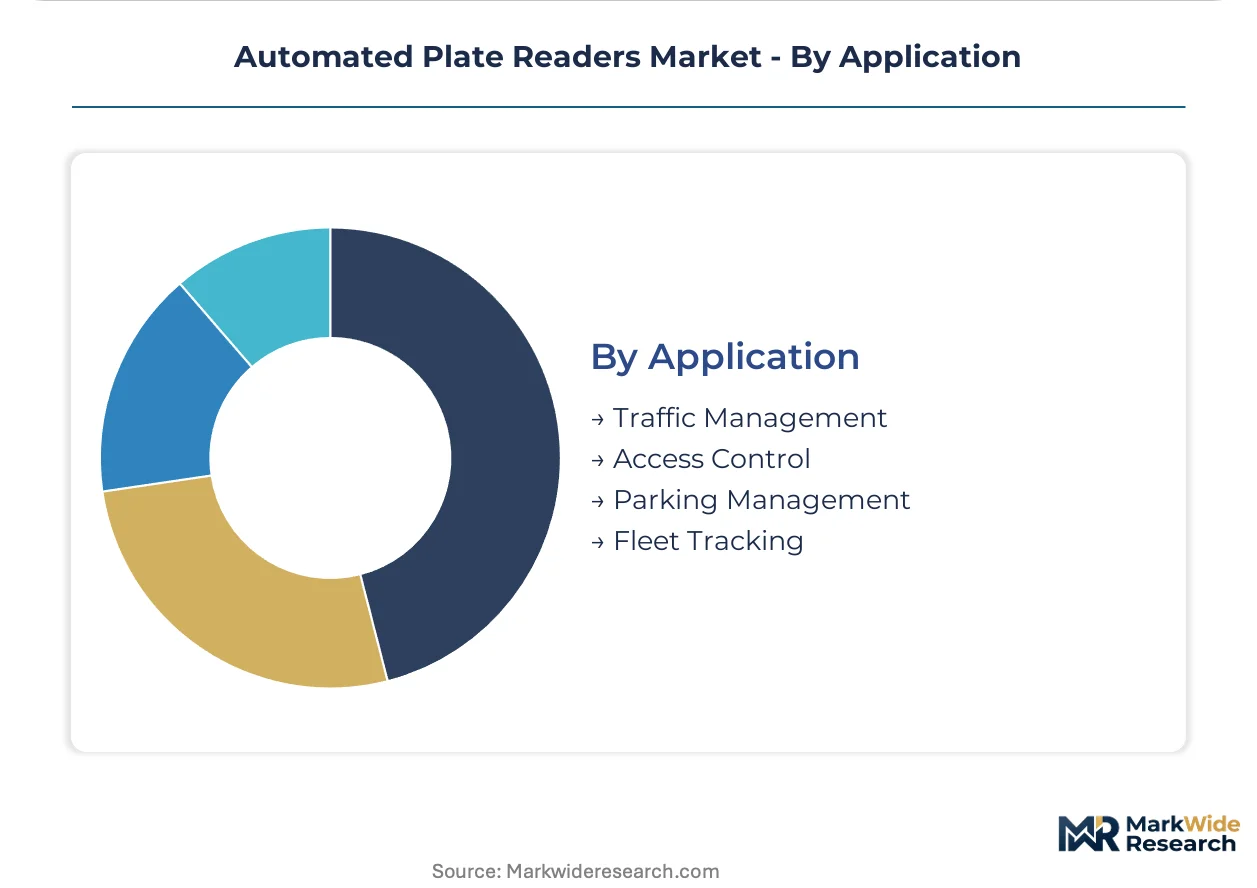
Traffic management applications anchor revenue concentration; access control integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized life science economic zones in Massachusetts and Bavaria concentrate automated plate reader demand through co-located pharmaceutical R&D and precision medicine infrastructure. These zones channel public-private funding into high-throughput screening facilities that anchor regional procurement volumes.
United States
FDA 21 CFR Part 11 compliance mandates drive replacement cycles in pharmaceutical quality control laboratories. The National Institutes of Health's precision medicine initiative sustains equipment funding for academic medical centers. Greater Boston hosts concentrated contract research operations processing multi-million compound libraries annually.
Germany
EU MDR diagnostic infrastructure timelines compress replacement windows for clinical laboratories in university hospital networks. The country's national pharmaceutical regulator enforces stringent software validation requirements for patient-facing instruments. Bavaria's biotechnology cluster integrates automated readers into centralized biobanking facilities serving pan-European clinical trials.
China
NMPA regulatory harmonization efforts accelerate adoption of traceability-enabled systems in domestic pharmaceutical development. Government-funded precision medicine initiatives under the 14th Five-Year Plan expand centralized biorepository capacity. Yangtze River Delta pharmaceutical parks deploy high-throughput screening infrastructure for innovative drug discovery.
India
CDSCO-regulated clinical trial expansion creates demand for compliance-validated instruments in contract research organizations. Government biobanking initiatives under the Department of Biotechnology fund regional precision medicine infrastructure. Maharashtra's pharmaceutical manufacturing corridor integrates automated readers into quality control workflows for export-oriented production.
United Kingdom
MHRA post-Brexit regulatory autonomy shapes distinct validation requirements for diagnostic instrument placement. NHS England's genomic medicine service drives biobanking standardization across regional laboratory networks. Cambridge-London life science corridor concentrates gene editing screening operations requiring integrated optical detection platforms.
Automated Plate Readers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: full-workflow integrators controlling liquid handling touchpoints, optical technology specialists commanding premium detection modules, and regional service-heavy players capturing replacement demand. M&A activity concentrates on software validation capabilities and field service network density. Portfolio diversification toward subscription-based analytics access represents the dominant competitive response to compressed capital equipment cycles.
Among diversified life science conglomerates, Thermo Fisher Scientific and PerkinElmer exemplify the full-workflow integration archetype through global service infrastructure and enterprise account management. BMG Labtech represents the optical specialization tier with application-specific module development. These three companies anchor distinct competitive vectors: scale-driven service coverage, precision detection engineering, and modular platform flexibility respectively.
| Leading Market Players |
|---|
| Agilent Technologies |
| PerkinElmer |
| Thermo Fisher Scientific |
| BMG Labtech |
| Eppendorf |
| Tecan Group |
| Molecular Devices |
| Berthold Technologies |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
Photonics engineering talent concentration in Bavaria and Massachusetts establishes labor-cost differentials that widen pricing-tier spreads between premium multimodal systems and entry-level compact units. German and Swiss manufacturing facilities face twelve-to-eighteen month material qualification timelines under REACH amendments, compressing margins on mid-tier instruments while elevating premium positioning for vendors with validated supply chains.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate standard-delivery contracts from spot procurement of RFID-enabled configurations in biobanking networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by optical module complexity and FDA 21 CFR Part 11 validation depth. Cost compression in economy-tier compact readers intensifies because Chinese manufacturers are expanding photonics assembly capacity. Academic laboratories exhibit highest price sensitivity, while pharmaceutical quality control operations prioritize compliance-validated specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German suppliers dominating photomultiplier tube and laser diode production for optical detection engines. Instrument manufacturing draws from precision optical component feedstock concentrated in Japan, Germany, and the United States, with electronic subassemblies sourced from Taiwan and South Korea. Tariff exposure on precision optics imported into the United States from German suppliers elevates landed costs for domestic instrument assemblers. Distribution runs through authorized service distributors in regulated markets and direct enterprise sales in pharmaceutical contract research networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated plate readers are undergoing technology transition from standalone hardware procurement to integrated workflow platforms, with cloud-native data architectures and subscription analytics replacing perpetual software licenses.
For Market Incumbents: Extend service infrastructure density into emerging biobanking clusters in India and China to defend placement share against regional challengers. Deepen backward integration into optical component sourcing to mitigate single-supplier vulnerability from Japanese photomultiplier tube manufacturers. Prioritize FDA 21 CFR Part 11 validation documentation as a competitive moat against software-only entrants. For New Entrants and Emerging Players: Modular RFID tracking modules offer technology-first wedge into biobanking and logistics segments where legacy vendors bundle hardware with inflexible enterprise software. Target mid-sized biotechnology firms in the United States and Germany with SaaS-decoupled hardware pricing that reduces upfront capital barriers. Pursue white-label partnerships with liquid handling integrators to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: The window for entry favors software validation specialists and field service network operators over pure hardware manufacturers. Long-term viability hinges on recurring revenue attachment rates rather than instrument placement volume. Watch FDA-EU IVDR harmonization progress as the signal indicating compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Module Integration | Biobanking networks in Germany and China mandate chain-of-custody documentation for audit readiness. |
| Subscription Analytics Launch | Mid-sized biotechnology firms in Massachusetts adopt SaaS data packages to reduce upfront capital requirements. |
| Backward Integration into Optics | Captive photomultiplier tube sourcing insulates vendors from Japanese supplier concentration risk. |
| Service Network Expansion | Local engineering presence in India's pharmaceutical corridors captures CDSCO-regulated clinical trial demand. |
| Cloud-Native Platform Development | Remote diagnostic capabilities reduce field service dependency for distributed screening operations. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, and pharmaceutical contract research procurement databases, complemented by interviews with instrument development executives, regulatory affairs specialists at German notified bodies, biobanking operations directors, and laboratory information management system integrators. Secondary validation drew from SEC 10-K disclosures, NIH precision medicine initiative reports, and customs trade data on optical component flows. Bottom-up instrument placement estimates triangulated against top-down pharmaceutical R&D spending allocations.
Market size outputs and growth trajectories were derived through multi-segment modeling across product type, detection technology, end-user category, and application workflow, with CAGRs computed from year-over-year expansion rates normalized across the projection horizon. Forecast inputs incorporated EU MDR transition timelines, NMPA regulatory harmonization schedules, and precision medicine infrastructure funding commitments under China's 14th Five-Year Plan.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization shifts between FDA and EU IVDR frameworks, supply chain disruptions from REACH substance restriction amendments, and breakthrough detection technologies displacing optical bench architectures. Forecasts reflect documented assumptions about replacement cycle timing and funding continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Global Cell Analysis Instruments Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
ASEAN Laboratory Equipment Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market