
 Laboratory Glassware and Plasticware Market | 2026-2036
Laboratory Glassware and Plasticware Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Glassware and Plasticware Market Intelligence
Modular kit configurations for cell culture workflows is pivoting how pharmaceutical buyers evaluate suppliers. Corning Inc. leverages its deep expertise in coated surfaces to dominate advanced cell culture vessel segments. Thermo Fisher Scientific Inc. sustains broad catalog breadth across both glass and polymer formats, competing on one-stop procurement convenience. Eppendorf AG specializes in precision liquid handling tools, differentiating through ergonomic design calibrated to automated workflows.
Laboratory glassware and plasticware comprises vessels, containers, and instruments fabricated from borosilicate glass or engineered polymers such as polypropylene and polystyrene, with thermal shock resistance specifications typically ranging from 150°C to 500°C for glass and autoclavability up to 121°C for plastics, serving the containment, measurement, and manipulation of reagents in controlled environments. Pipettes and test tubes within the product type dimension occupy mature volume positions with thin margin profiles, while beakers and flasks for bioprocessing applications capture expanding value pools. Glass retains structural importance in analytical applications requiring thermal and chemical resistance, though polypropylene is displacing polystyrene in biological research due to superior solvent compatibility and repeated sterilization durability.
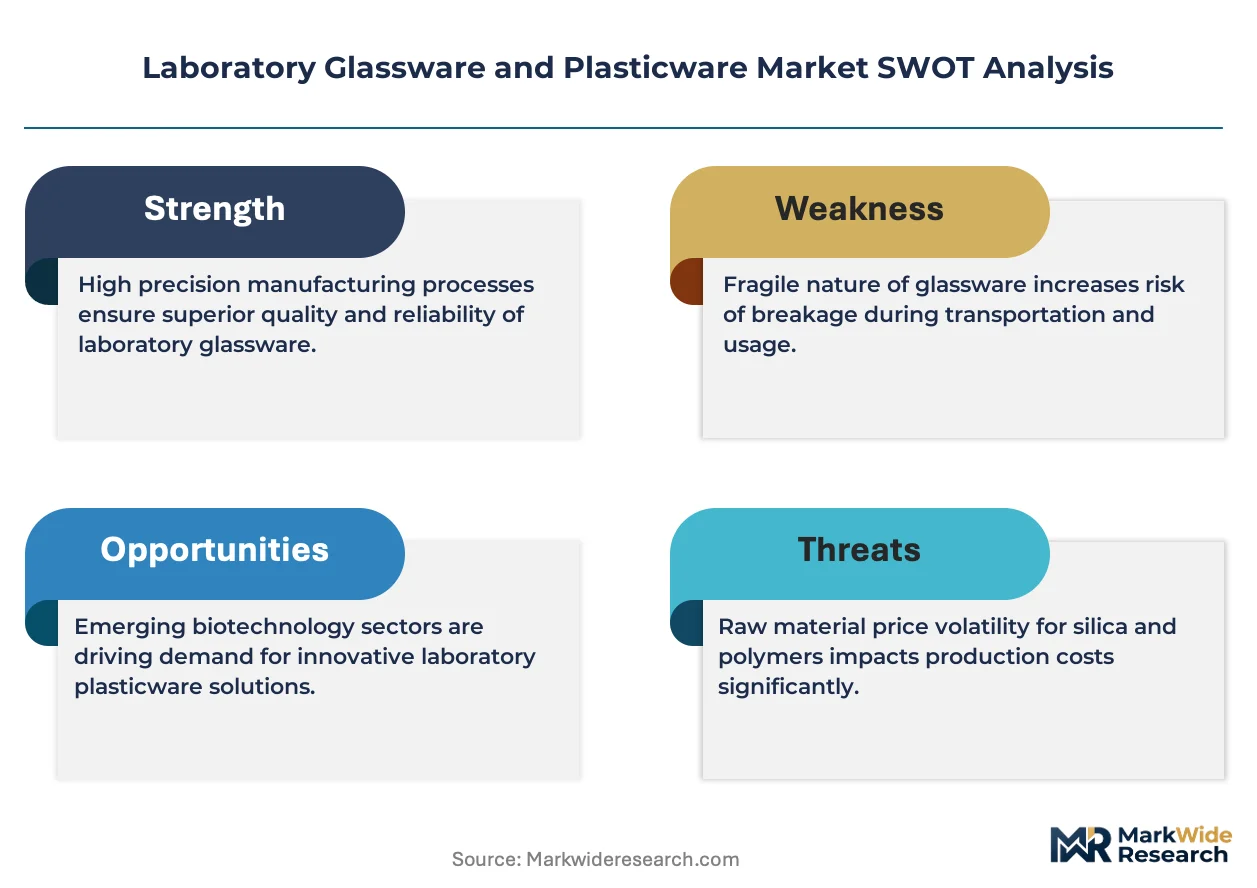
The FDA enforces container closure integrity standards for parenteral drug packaging, directly shaping material selection and validation protocols for laboratory vessels used in pharmaceutical development. ISO 17025 accreditation requirements and the EPA's Good Laboratory Practice standards further constrain supplier qualification, raising barriers for uncertified manufacturers. REACH restrictions in Europe on certain phthalate plasticizers are accelerating reformulation investments across polymer supply chains. Stakeholders must monitor evolving biocompatibility testing standards and automated compatibility specifications as lab informatics integration reshapes procurement criteria.
Market Dynamics
Single-use plasticware adoption in biologics manufacturing is restructuring procurement relationships as pharmaceutical buyers prioritize contamination control over capital equipment longevity, compressing supplier qualification timelines and elevating material traceability requirements.
Growth Catalysts
- Container Closure Integrity Mandates:The FDA's updated parenteral drug packaging standards compel pharmaceutical developers to validate vessel materials earlier in clinical pipelines, extending laboratory consumable demand into pre-formulation stages.
- Biologics Manufacturing Scale-Up:Cell and gene therapy production facilities are expanding single-use system deployments, creating sustained pull for gamma-sterilized polymer vessels with documented extractables profiles.
- German Production Cluster Density:Specialized manufacturing corridors around Mainz and Göttingen concentrate pharmaceutical-grade glass and polymer expertise, reducing lead times for European biotech procurement.
Market Restraints
- Borosilicate Glass Supply Concentration:High-purity sand deposits and specialized melting furnace capacity concentrate among limited Central European suppliers, exposing buyers to energy cost volatility and logistics disruption.
- REACH Plasticizer Restrictions:ECHA's accelerating phase-out of phthalate additives forces polymer reformulation investments, compressing margins for mid-tier manufacturers lacking R&D scale.
- Autoclave Durability Limits:Repeated steam sterilization degrades polypropylene mechanical properties at rates faster than glass thermal shock failure, constraining reuse economics in high-throughput core facilities.
Strategic Opportunities
- India Biopharma Infrastructure Buildout:CDSCO's streamlined clinical trial regulations and PLI scheme incentives are attracting contract manufacturing investment, creating virgin demand for GMP-compliant consumable supply chains.
- Lab Informatics Integration:RFID-embedded vessels enabling automated inventory tracking and chain-of-custody documentation command pricing premiums from regulated pharmaceutical laboratories.
- Cell Culture Workflow Modularization:Pre-configured kit formats combining coated surfaces, media, and vessels reduce buyer sourcing complexity, favoring suppliers with cross-category assembly capabilities.
Industry Challenges
- ISO 17025 Accreditation Timelines:Third-party laboratory certification for polymer extractables testing extends 18-24 months, delaying new product commercialization for specialized vessel manufacturers.
- Automation Interface Standardization:Proprietary gripping geometries and barcode formats across liquid handling platforms fragment demand, forcing suppliers to maintain multiple tooling configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Glassware and Plasticware Market |
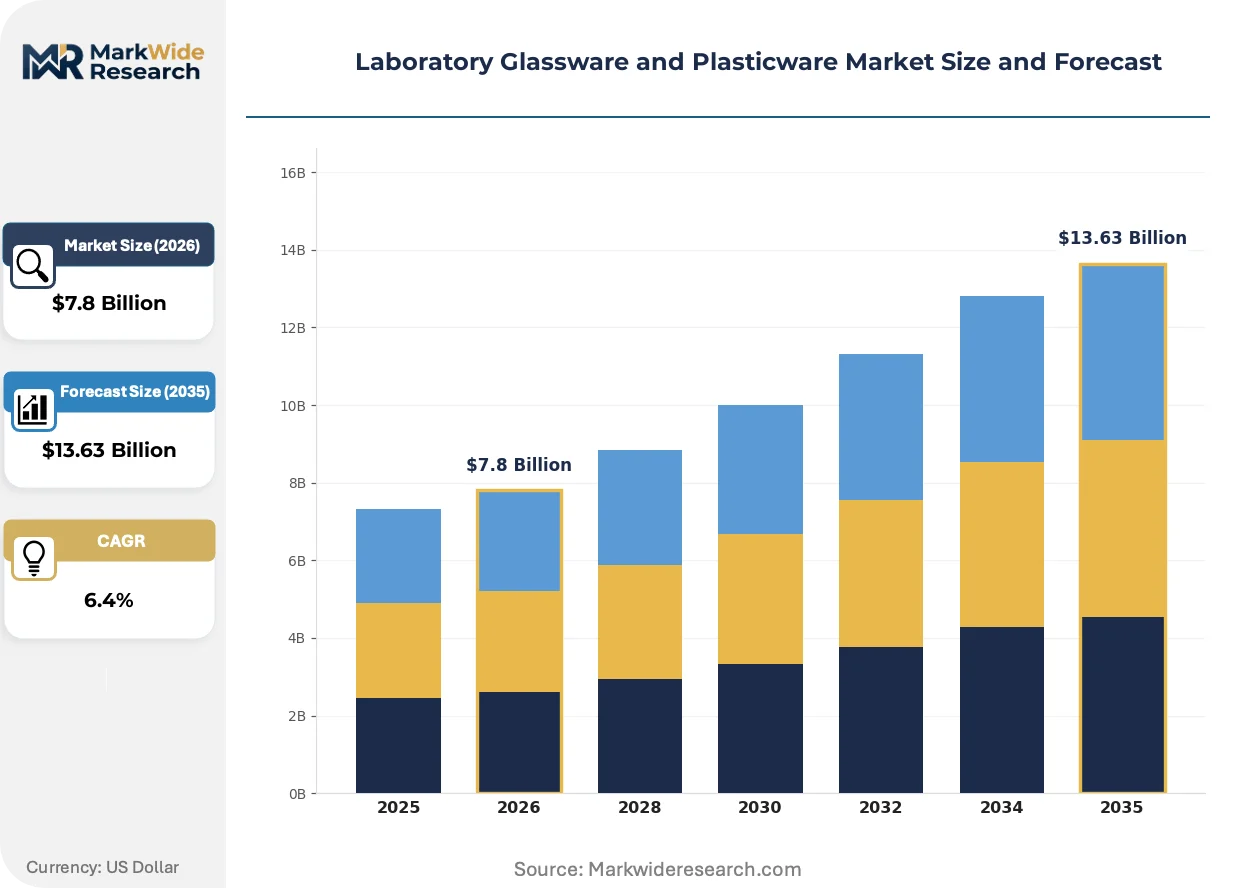
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beakers, Flasks, Pipettes, Test Tubes Material: Glass, Polypropylene, Polystyrene, Borosilicate Application: Chemical Analysis, Biological Research, Quality Control, Educational Purposes End User: Laboratories, Educational Institutions, Pharmaceutical Companies, Research Organizations |
| Companies Covered | Bellco Glass Inc., Mettler Toledo International Inc., Corning Inc., Eppendorf AG, Gerresheimer AG, Thermo Fisher Scientific Inc., Sartorius AG, Crystalgen Inc., DWK Life Sciences GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Glassware and Plasticware Market Strategic Shifts & Innovations
Surface engineering and digital traceability technologies are converging to redefine how laboratory vessels deliver value beyond containment, shifting competitive differentiation toward validated performance data and workflow integration.
Coated cell culture surfaces incorporating recombinant extracellular matrix proteins are consolidating advanced vessel segments, as stem cell and organoid researchers migrate from self-coated protocols to manufacturer-validated formats. Academic core facilities and emerging biotechs are adopting these surfaces at accelerating rates, compressing the addressable market for uncoated polystyrene alternatives and elevating technical support expectations.
REACH restrictions on phthalate plasticizers are tightening material specifications across European pharmaceutical supply chains, compelling polymer suppliers to accelerate bio-based alternative validation. ECHA's substance evaluation timelines are compressing reformulation windows, with parenteral drug packaging applications facing the most acute compliance pressure and fastest substitution mandates.
Consolidated procurement platforms are displacing fragmented distributor relationships as large pharmaceutical buyers centralize laboratory consumable purchasing through enterprise agreements. Thermo Fisher and VWR's integrated supply contracts are capturing volume from independent regional distributors, with this concentration most visible in the United States where formulary standardization reduces supplier management overhead for multi-site operators.
Laboratory Glassware and Plasticware Market Segmentation
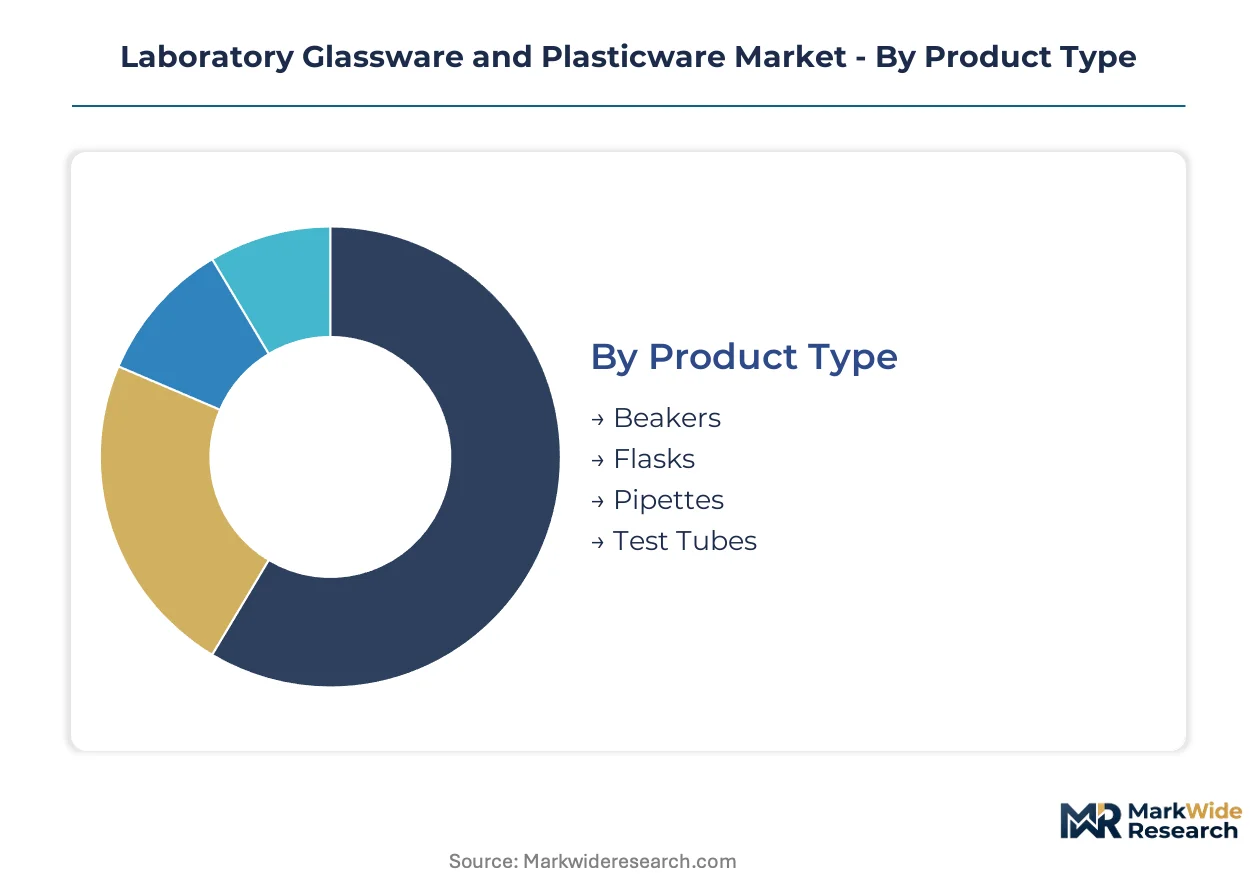
Segmentation in laboratory glassware and plasticware reveals how procurement criteria fragment across thermal performance demands, contamination control protocols, and workflow automation requirements. Buyers optimize vessel selection against sterilization cycles, solvent compatibility, and regulatory validation burdens rather than unit cost alone.
Product Type:
Supply concentration among specialized borosilicate melters and precision molders for polymer vessels creates tiered availability constraints across vessel formats.
- Beakers:Cylindrical vessels with pour spouts fabricated in borosilicate or polypropylene, rated for thermal shock resistance between 150°C and 230°C. Demand concentrates in German pharmaceutical manufacturing corridors where Gerresheimer AG anchors high-volume supply, though energy cost volatility at Central European glass furnaces constrains spot procurement flexibility.
- Flasks:Erlenmeyer and cell culture formats with baffled or flat bottoms, increasingly specified with surface coatings for adherent cell propagation. Biological research facilities in Mainz and Göttingen clusters are expanding flask procurement for bioprocessing scale-up, with gamma-sterilized single-use formats displacing reusable glass in cell therapy manufacturing.
- Pipettes:Volumetric and serological formats for liquid measurement and transfer, spanning disposable polystyrene to reusable borosilicate with calibration certification.
- Test Tubes:Cylindrical containers for sample storage and reaction observation, manufactured in glass or polymer with rim or screw-cap configurations.
Today's leader: Flasks. Tomorrow's challenger: Beakers.
Material:
Cost tier stratification separates premium validated grades from commodity polymer feedstocks, with extractables documentation commanding substantial price premiums in pharmaceutical applications.
- Glass:Soda-lime and borosilicate compositions offering thermal shock resistance to 500°C and chemical inertness for aggressive solvents. Quality control laboratories in the United States maintain glass preference for USP dissolution testing and EPA-mandated analytical methods where thermal stability outweighs breakage risk.
- Polypropylene:Autoclavable thermoplastic with solvent compatibility superior to polystyrene, tolerating repeated 121°C steam sterilization cycles. Research organizations across India are accelerating polypropylene adoption as CDSCO-aligned GMP infrastructure expands, though mechanical fatigue limits reuse economics in high-throughput core facilities.
- Polystyrene:Clear amorphous polymer for optical clarity in cell culture and diagnostic applications, constrained by solvent sensitivity and single-use disposal economics.
- Borosilicate:High-silica glass composition with lowest coefficient of thermal expansion, specified for pharmaceutical parenteral drug development under FDA container closure integrity mandates.
Glass dominates analytical validation. Polypropylene gains share fastest in biological workflows.
Application:
Volume concentration in biological research is restructuring supplier qualification priorities toward extractables testing and gamma sterilization documentation.
- Chemical Analysis:Vessels for chromatography sample prep, titration, and spectroscopic measurement requiring solvent resistance and thermal stability. Pharmaceutical companies in Switzerland specify borosilicate for Swissmandated stability testing protocols where method transfer demands material consistency across development phases.
- Biological Research:Cell culture, organoid propagation, and molecular biology workflows utilizing surface-engineered vessels and single-use sterile formats. Educational institutions in South Korea are upgrading biological research infrastructure under MFDS-aligned quality frameworks, compressing demand for basic polystyrene toward coated and validated alternatives.
- Quality Control:Validated vessels for batch release testing, environmental monitoring, and compendial method execution with documented calibration traceability.
- Educational Purposes:Entry-level glassware and plasticware for undergraduate laboratory instruction, prioritizing durability and cost over performance specifications.
Chemical analysis anchors premium pricing. Biological research drives volume expansion.
End User:
Customer type determines procurement channel concentration, with pharmaceutical buyers consolidating through enterprise agreements while educational institutions fragment across distributor networks.
- Laboratories:Clinical diagnostic, environmental testing, and forensic facilities requiring ISO 17025-aligned vessel calibration and chain-of-custody documentation. Laboratories in Australia are adopting RFID-embedded vessels for automated inventory tracking under TGA quality management expectations, commanding pricing premiums from regulated operators.
- Pharmaceutical Companies:Drug developers and manufacturers subject to FDA, EMA, and national pharmaceutical regulator mandates for container closure integrity and extractables profiles. CDSCO's streamlined clinical trial regulations in India are attracting contract manufacturing investment, creating virgin demand for GMP-compliant consumable supply chains with documented material traceability.
- Educational Institutions:Universities and secondary schools with budget-constrained procurement, standardizing on durable borosilicate for introductory chemistry instruction.
- Research Organizations:Government and nonprofit research institutes with mixed funding sources, balancing performance requirements against grant-funded budget cycles.
Pharmaceutical companies concentrate value capture. Research organizations represent expanding volume opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German glassblowing guilds established the modern laboratory glassware industry during the late 19th century, with Schott AG's borosilicate innovations setting material standards that persist today. Contemporary demand distributes across pharmaceutical manufacturing corridors, academic research hubs, and emerging biotech clusters spanning multiple continents.
Germany
Pharmaceutical-grade consumable demand concentrates around Mainz and Göttingen manufacturing corridors, where specialized production clusters serve European biotech procurement. ECHA's REACH restrictions on phthalate plasticizers are accelerating polymer reformulation investments across German supply chains. Gerresheimer AG and Sartorius AG anchor high-volume glass and polymer vessel production, reducing lead times for GMP-compliant deliveries.
United States
Quality control laboratories maintain borosilicate preference for USP dissolution testing and EPA-mandated analytical methods. FDA container closure integrity standards compel pharmaceutical developers to validate vessel materials earlier in clinical pipelines. Thermo Fisher Scientific's integrated supply contracts capture volume from independent regional distributors through enterprise procurement centralization.
India
CDSCO's streamlined clinical trial regulations and PLI scheme incentives are attracting contract manufacturing investment, creating virgin demand for GMP-compliant consumable supply chains. Research organizations across Maharashtra and Gujarat are accelerating polypropylene adoption as GMP infrastructure expands. Educational institutions in Bangalore and Hyderabad upgrade biological research infrastructure under quality-aligned frameworks.
China
Domestic biopharma infrastructure buildout is restructuring procurement toward gamma-sterilized polymer vessels with documented extractables profiles. NMPA alignment with ICH guidelines elevates material traceability requirements for parenteral drug development. Yangtze River Delta manufacturing zones concentrate precision molding capacity for cell culture workflow modularization.
Switzerland
Pharmaceutical companies specify borosilicate for Swiss-mandated stability testing protocols where method transfer demands material consistency across development phases. Swissmedic regulations enforce stringent container closure documentation for parenteral packaging applications. Basel and Zurich clusters anchor specialized vessel validation services for European drug developers.
Laboratory Glassware and Plasticware Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and extractables-documentation dimensions, with three-tier pricing structure separating validated pharmaceutical grades from standard research grades and economy educational tiers. Consolidated procurement platforms displace fragmented distributor relationships as large buyers centralize purchasing through enterprise agreements. Two strategic archetypes dominate: diversified life science conglomerates competing on catalog breadth, and specialized precision-tooling houses differentiating through ergonomic automation interfaces. Dominant competitive moves include backward integration into coated surface technologies and geographic expansion into Indian biopharma infrastructure.
Among diversified conglomerates, Corning Inc. and Thermo Fisher Scientific Inc. represent scale-driven catalog breadth strategies, while Eppendorf AG exemplifies precision-tooling specialization. Gerresheimer AG and Sartorius AG occupy positions within German pharmaceutical-grade manufacturing clusters. Bellco Glass Inc., DWK Life Sciences GmbH, and Crystalgen Inc. sit within mid-tier specialist categories serving regional research markets.
| Leading Market Players |
|---|
| Bellco Glass Inc. |
| Mettler Toledo International Inc. |
| Corning Inc. |
| Eppendorf AG |
| Gerresheimer AG |
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| Crystalgen Inc. |
| DWK Life Sciences GmbH |
| Others |
Cost & Logistics Intelligence
Specialized glassblowing guilds concentrated in Central European manufacturing corridors create labor-cost differentials that widen pricing-tier spreads between pharmaceutical-grade validated vessels and standard research consumables.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates extractables-documented pharmaceutical grades from ISO 17025-certified research grades and basic educational tiers. Price differentiation rests on certification depth and gamma-sterilization documentation, with FDA-aligned validation commanding substantial premiums. Cost compression in mid-tier polymer segments is intensifying because REACH-mandated reformulation investments compress margins for manufacturers lacking captive R&D scale. Educational institutions exhibit highest price sensitivity, while pharmaceutical quality control laboratories prioritize material traceability over unit cost.
Supply Chain Analysis
ISO 17025 accreditation timelines extending 18-24 months for polymer extractables testing gate entry for uncertified manufacturers and concentrate supply among established qualification holders. High-purity borosilicate glass production draws from specialized melting furnace capacity in Germany, China, and the United States. Raw material dependencies include high-silica sand deposits, pharmaceutical-grade polymer resins, and recombinant protein coatings for advanced cell culture surfaces. Single-source vulnerability concentrates in Central European borosilicate feedstock. Distribution runs through consolidated enterprise procurement platforms serving large pharmaceutical buyers alongside fragmented regional distributors for academic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on coating technology premiums displacing commodity vessel economics, with surface-engineered formats capturing value from self-coated protocol abandonment.
For Market Incumbents: Anchor defensive positioning through backward integration into coated surface technologies and captive gamma-sterilization capacity. Threat from modular kit competitors assembling cross-category workflows demands channel control reinforcement through enterprise formulary lock-in. Certification investment in CDSCO-aligned Indian GMP infrastructure opens volume capture in contract manufacturing expansion zones. For New Entrants and Emerging Players: RFID-embedded traceability technologies offer entry wedge into pharmaceutical quality control segments where automated inventory integration commands pricing premiums. White-space concentrates in India's biopharma infrastructure buildout under PLI scheme incentives, with GMP-compliant consumable supply chains showing lowest incumbent saturation. Go-to-market through CDSCO-registered contract manufacturing organization partnerships accelerates qualification timeline compression. For Investors and Strategic Acquirers: Life science conglomerates with catalog breadth strategies are the most active acquirer in this space, targeting specialized precision-tooling houses with ergonomic automation interfaces. Long-term viability favors targets with validated coating IP and established extractables documentation libraries. The signal to watch is NMPA-ICH alignment acceleration in China elevating material traceability requirements and consolidating procurement toward pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Surface Coating Technology Acquisition | Captures stem cell research migration toward manufacturer-validated formats. |
| Gamma-Sterilization Capacity Expansion | Secures single-use biologics vessel supply for cell therapy manufacturing. |
| Indian GMP Infrastructure Partnership | Positions for CDSCO-aligned contract manufacturing procurement growth. |
| RFID Traceability Platform Integration | Enables automated chain-of-custody documentation for regulated laboratories. |
| REACH-Compliant Polymer Reformulation | Preempts ECHA phthalate restrictions with bio-based alternative validation. |
Research Approach
Multiple input streams — primary interviews with laboratory procurement managers, regulatory affairs specialists, and bioprocess engineers; secondary validation against FDA container closure guidance documents, ECHA substance evaluation databases, and ISO 17025 accreditation registries — were reconciled through bottom-up vessel volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across product type, material composition, application workflow, and end-user procurement channel dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing-tier mix shifts. Forecast inputs incorporated gamma-sterilization capacity expansion timelines and CDSCO regulatory streamlining implementation pace.
The model holds under stable REACH implementation schedules and continued ICH guideline convergence; deviation in ECHA acceleration of phthalate phase-outs or NMPA traceability mandate timing would shift polymer substitution curves and regional supply concentration. A model refresh is warranted upon material change in biologics manufacturing automation adoption rates affecting single-use vessel demand intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Human Milk Analyzers Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
South Korea Pipette Tips Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Cuvettes Market