
 Chest Compressors Market | 2026-2036
Chest Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Chest Compressors Market Outlook
Hospital procurement departments are rotating toward automated chest compression systems as emergency medical services budgets tighten. Stryker Corporation leverages its installed base in acute care settings to sustain recurring revenue streams. ZOLL Medical Corporation differentiates through integrated feedback technologies that optimize compression depth and rate.
Chest compressors are electromechanical or pneumatic devices designed to deliver standardized, high-frequency compressions to the sternum at depths of 50-60 millimeters and rates of 100-120 per minute, primarily used to maintain circulatory perfusion during cardiac arrest when manual CPR becomes unsustainable. Automated systems dominate hospital purchasing due to reduced rescuer fatigue and consistent hemodynamic output, while portable units represent the fastest-growing configuration as pre-hospital protocols expand. Pneumatic technology anchors the installed base for institutional customers, though hybrid electric-pneumatic architectures are gaining traction in ambulance deployments where power reliability varies.
FDA 510(k) premarket notification requirements and EU MDR conformity assessment procedures shape device validation timelines and clinical evidence thresholds for manufacturers seeking market access. ISO 13485 quality management certification functions as a baseline procurement filter across OECD health systems. Stakeholders must monitor evolving ILCOR resuscitation guidelines and their translation into national protocol updates, as these directly determine replacement cycles and specification requirements.
Market Dynamics
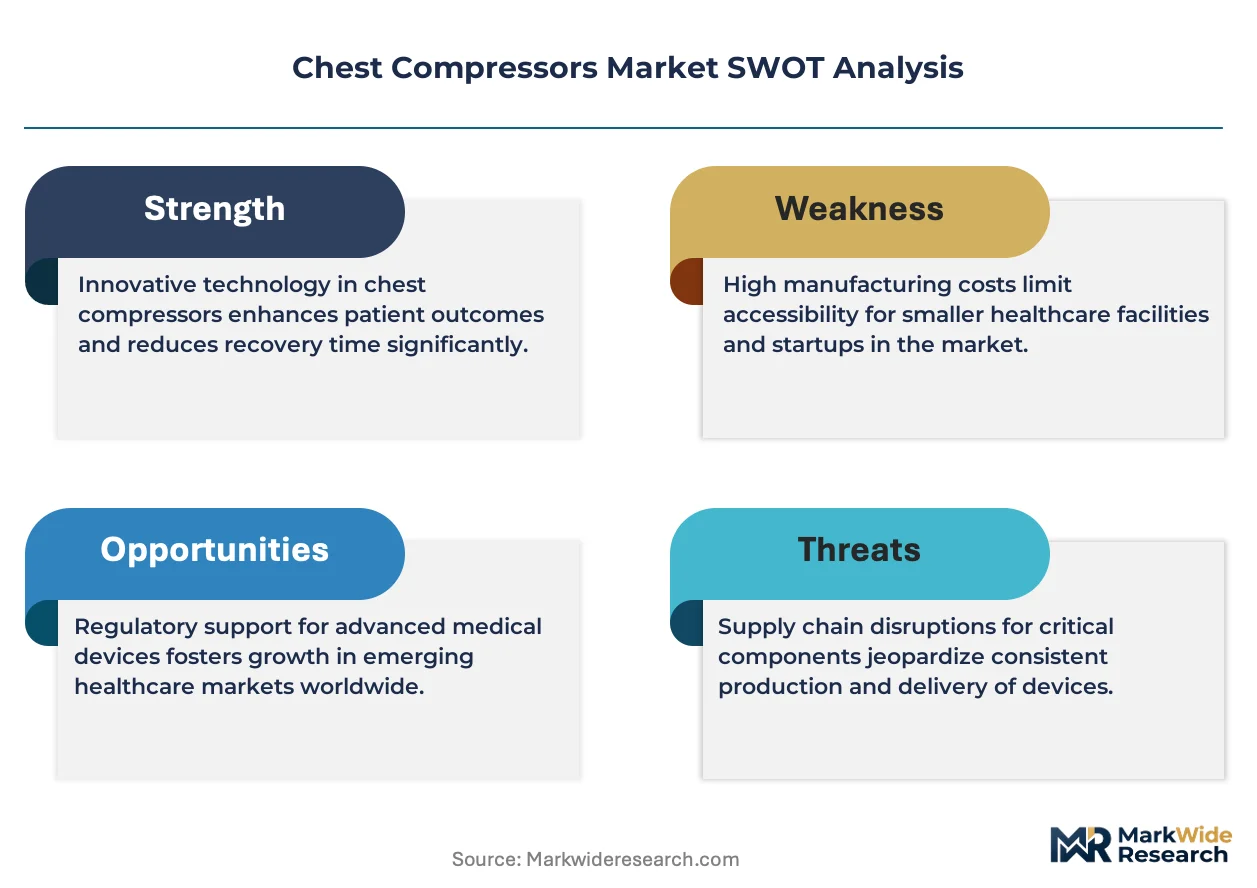
Hospital emergency departments are consolidating manual CPR protocols toward automated chest compression systems as clinical evidence accumulates on hemodynamic consistency and rescuer fatigue reduction. This technology transition is compressing replacement cycles for legacy pneumatic devices while expanding the addressable market for portable electromechanical units in pre-hospital settings.
Growth Catalysts
- EU MDR compliance deadlines:The 2024-2025 transition period for Class IIa medical device recertification is forcing hospital procurement departments to accelerate replacement of aging compressor inventories.
- Pre-hospital protocol expansion:Ambulance services in Germany and Japan are mandating automated compression devices for extended transport scenarios exceeding fifteen minutes.
- ILCOR guideline translation:National resuscitation councils in the United States, United Kingdom, and Australia are incorporating automated CPR into advanced cardiac life support standards.
Market Restraints
- Lithium battery supply concentration:Electromechanical portable units depend on cylindrical cell supply chains centered in China, creating input cost volatility and qualification delays.
- FDA 510(k) clinical evidence thresholds:Predicate device comparisons for novel compression algorithms require expensive hemodynamic studies that extend validation timelines for smaller manufacturers.
- Manual CPR training infrastructure:Established certification programs for healthcare workers create institutional inertia against capital expenditure on automation despite superior outcomes.
Strategic Opportunities
- Rural emergency medical services in India:Underpenetrated district ambulance fleets present first-mover potential for battery-powered units with solar charging compatibility.
- Integrated feedback convergence:Coupling real-time compression depth sensors with capnography and ECG analysis creates premium positioning for comprehensive resuscitation platforms.
- Direct-to-hospital digital distribution:Bypassing traditional medical device distributors through specialized emergency care procurement platforms reduces channel margin capture.
Industry Challenges
- Biomedical technician specialization:Electromechanical systems require expertise in servo motor calibration and force sensor maintenance that outpaces training program expansion.
- ISO 13485 certification timeline:Quality management system audits for new market entrants average fourteen to eighteen months, delaying revenue recognition.
- Legacy pneumatic integration:Hospital IT infrastructure for device connectivity and electronic health record documentation varies across acute care networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chest Compressors Market |
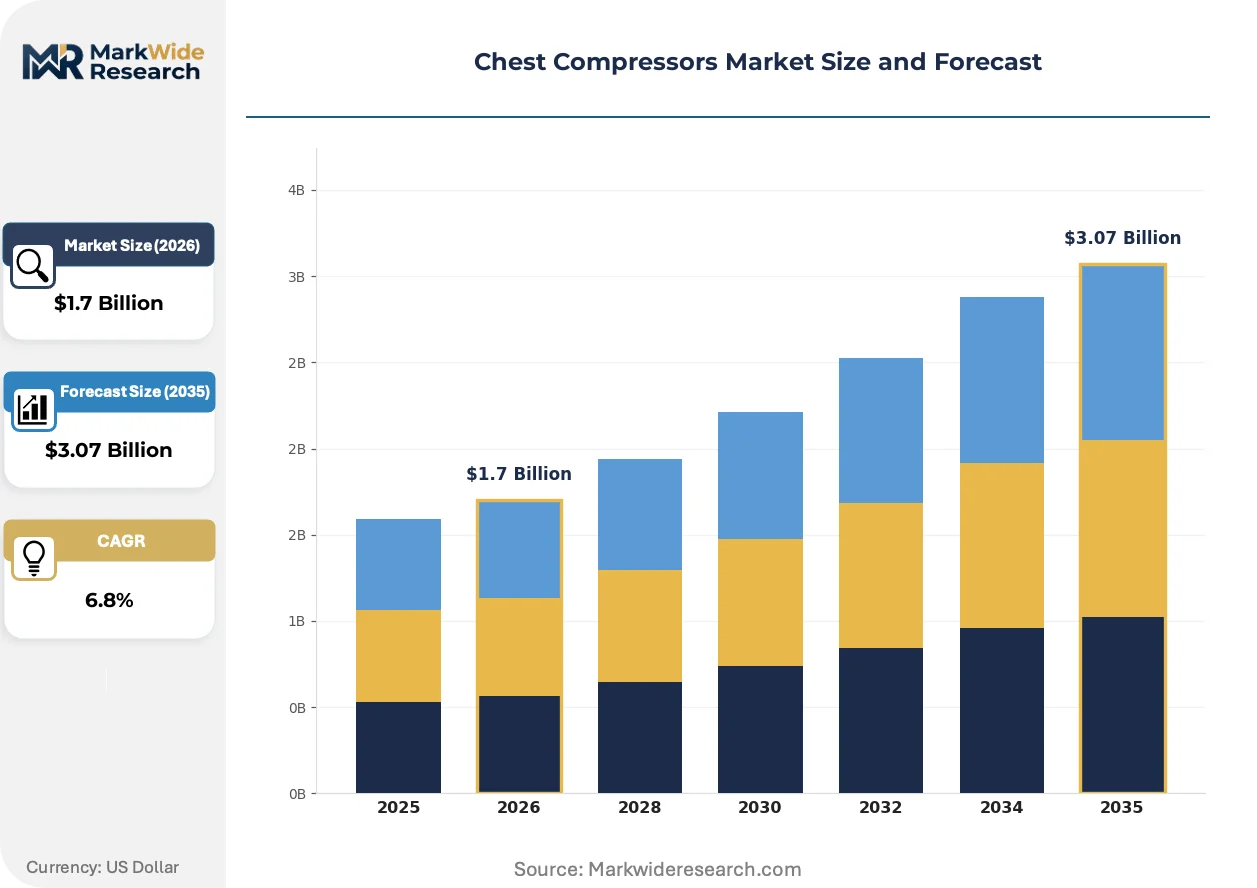
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Manual, Portable, Fixed Technology: Pneumatic, Electric, Mechanical, Hybrid End User: Hospitals, Ambulance Services, Home Care, Emergency Services Application: Cardiac Arrest, Trauma Management, Respiratory Failure, Clinical Trials |
| Companies Covered | Stryker Corporation, ZOLL Medical Corporation, Michigan Instruments, Schiller AG, SunLife Science, Corpuls, Resuscitation International, Defibtech, CPR Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chest Compressors Market Strategic Shifts
Electromechanical architectures are displacing pneumatic systems across the installed base as battery energy density improves and compression algorithm sophistication advances. Three developments are reshaping competitive positioning and procurement criteria.
Hybrid electric-pneumatic drive systems are fragmenting the traditional technology dichotomy between hospital-grade pneumatic compressors and portable battery units. Ambulance operators in Germany and Japan are adopting these dual-mode devices to maintain compression continuity during vehicle power transitions. The technology is fragmenting vendor specialization boundaries as pneumatic specialists develop electric competencies and electromechanical manufacturers integrate air reservoir subsystems.
EU MDR Annex IX conformity assessment procedures are extending clinical evidence requirements for chest compressors classified as active therapeutic devices. Manufacturers must now submit post-market surveillance data and risk management files beyond previous Medical Device Directive thresholds. The regulation is compressing the competitive field as smaller competitors withdraw from European market access efforts.
Outcome-based purchasing criteria are displacing capital expenditure models in United States hospital networks. Procurement committees now evaluate total cost of resuscitation events including device utilization rates, training overhead, and litigation risk reduction. This behavioral shift favors vendors with comprehensive service agreements and predictive maintenance capabilities over equipment-only suppliers.
Chest Compressors Market Segmentation
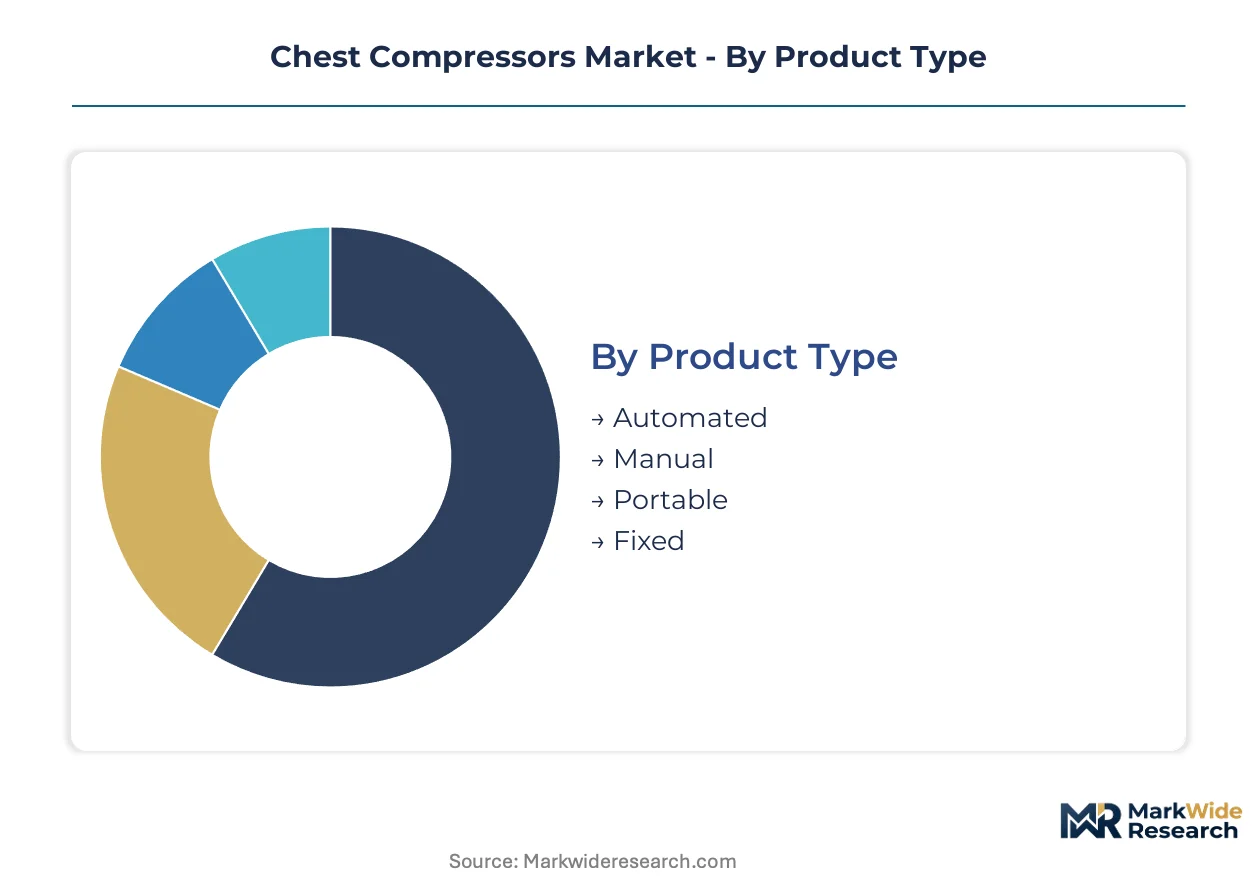
Chest compressors serve distinct operational environments with divergent power, portability, and precision requirements. Segmentation reveals how technology choices align with institutional budgets, transport logistics, and regulatory compliance pathways across acute care networks.
Product Type:
Portable and fixed systems dominate export flows to pre-hospital services, while automated units anchor domestic hospital procurement in the United States, Germany, and Japan.
- Automated:Electromechanical systems deliver 100-120 compressions per minute at 50-60mm depth with force feedback algorithms. Demand concentrates in United States emergency departments where ILCOR guideline translation drives replacement of manual protocols. FDA 510(k) clearance requirements extend validation timelines for algorithm modifications.
- Portable:Battery-powered units weigh under 10 kilograms for ambulance deployment and air transport compatibility. German and Japanese emergency services mandate these devices for transport scenarios exceeding fifteen minutes, though lithium battery supply concentration in China creates input cost volatility.
- Manual:Hand-operated devices with mechanical leverage assist rescuer fatigue management in resource-constrained settings. Indian district hospitals deploy these units where capital budgets limit electromechanical acquisition.
- Fixed:Wall-mounted or cart-based systems integrate with hospital IT infrastructure for electronic health record documentation. United Kingdom acute care networks standardize on these configurations for resuscitation bay deployment.
Fixed systems command the established base. The steepest expansion runs through portable configurations.
Technology:
Cost tier stratification separates premium hybrid architectures from legacy pneumatic installations, with electric systems capturing mid-market pre-hospital contracts.
- Hybrid:Dual-mode electric-pneumatic drives maintain compression continuity during vehicle power transitions. German ambulance operators adopted these systems first, with Japanese services following for extended rural transport routes. EU MDR Annex IX conformity assessments now require expanded clinical evidence for active therapeutic device classification.
- Pneumatic:Compressed air systems with mechanical timing mechanisms anchor hospital installed bases installed before electromechanical maturation. These units face accelerated replacement cycles as EU MDR compliance deadlines force inventory turnover.
- Electric:Servo motor architectures with force sensor feedback optimize compression depth in real time. Australian emergency services specify these systems for coastal deployment where salt corrosion degrades pneumatic components.
- Mechanical:Spring-loaded or piston-driven devices without electronic control suit austere environments with unreliable power. Humanitarian medical organizations deploy these units in conflict zones where technical support infrastructure is absent.
Pneumatic technology holds the legacy installed base. Hybrid architectures are climbing the fastest as ambulance operators seek operational flexibility.
End User:
Application intensity varies by customer type, with hospitals demanding integration capabilities and ambulance services prioritizing battery endurance and rapid deployment.
- Hospitals:Acute care networks require FDA-cleared devices with predictive maintenance contracts and biomedical technician training programs. United States procurement committees evaluate total cost of resuscitation events including litigation risk reduction.
- Ambulance Services:Pre-hospital providers in Germany and Japan mandate automated compression for extended transport, creating specification requirements that filter vendor eligibility. Solar charging compatibility opens rural Indian district fleets to battery-powered penetration.
- Emergency Services:Fire departments and disaster response teams need rapid-deployment configurations with minimal calibration. Australian state emergency services standardize on interoperable equipment across jurisdictional boundaries.
- Home Care:Domestic settings with caregiver-operated devices represent nascent demand as palliative care protocols evolve. Regulatory frameworks for non-clinical operators remain underdeveloped in most jurisdictions.
Hospitals anchor procurement volume. Ambulance services represent the steepest expansion trajectory as pre-hospital protocols extend.
Application:
Volume concentration aligns with cardiac arrest incidence, while trauma and respiratory applications demand specialized compression algorithms and adjunct monitoring.
- Cardiac Arrest:Standardized high-frequency compressions for circulatory maintenance during ventricular fibrillation or asystole. United States hospital networks consolidate protocols around automated systems as evidence accumulates on hemodynamic consistency.
- Trauma Management:Modified compression patterns for hypovolemic or tension pneumothorax casualties require integrated feedback from capnography and invasive pressure monitoring. Military medical research drives algorithm development for damage control resuscitation.
- Respiratory Failure:Coordinated compression-ventilation sequences for respiratory arrest with maintained cardiac output. Clinical trials in the United Kingdom evaluate automated systems against manual CPR for drowning and overdose presentations.
- Clinical Trials:Standardized compression delivery for pharmaceutical or device studies requiring protocol consistency across multi-site investigations. Contract research organizations specify calibrated systems with data logging for regulatory submission packages.
Cardiac arrest commands the established base. Trauma management is gaining share fastest as military and civilian protocols converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and Japan concentrate purchasing power for automated chest compression systems. Pre-hospital service expansions in these markets are reshaping vendor qualification requirements and compliance timelines.
United States
FDA 510(k) clearance pathways structure product validation timelines for electromechanical systems entering emergency department procurement cycles. The American Heart Association guideline translations drive protocol standardization across acute care networks. The Boston-Cambridge medical device cluster anchors domestic manufacturing and clinical trial infrastructure for compression algorithm development.
Germany
EU MDR Annex IX conformity assessments extend clinical evidence requirements for active therapeutic device classification in 2024-2025. Pre-hospital protocols now mandate automated compression for ambulance transports exceeding fifteen minutes. The Baden-Württemberg precision engineering corridor supplies servo motor components and force sensor subsystems to regional device assemblers.
Japan
METI industrial standards coordinate with PMDA device approvals to synchronize compression system specifications with national resuscitation council updates. Extended rural transport routes are accelerating hybrid electric-pneumatic adoption in district ambulance fleets. The Kansai medical technology manufacturing zone concentrates final assembly operations for domestic hospital procurement.
United Kingdom
NHS England procurement frameworks evaluate total cost of resuscitation events including litigation risk reduction in capital expenditure decisions. United Kingdom resuscitation councils incorporate automated CPR into advanced cardiac life support standards following ILCOR guideline translation. The Oxford-Cambridge healthcare technology corridor hosts clinical validation studies for compression-ventilation integration algorithms.
India
District ambulance fleets in Maharashtra and Karnataka present penetration opportunities for battery-powered units with solar charging compatibility. CDSCO medical device registration timelines create qualification barriers for imported electromechanical systems. The Delhi-NCR healthcare distribution hub channels manual and semi-automated devices to tier-two hospital networks with constrained capital budgets.
Chest Compressors Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with acute care installed bases and specialized resuscitation equipment manufacturers with algorithm differentiation. Market structure concentrates around vendors with FDA-cleared predicate devices and EU MDR conformity certification. Two strategic archetypes dominate: integrated emergency care platform providers and standalone compression technology specialists. Competitive moves center on predictive maintenance service agreements and direct-to-hospital digital distribution channel development.
Among diversified medical technology conglomerates, Stryker Corporation and ZOLL Medical Corporation exemplify the integrated platform archetype, anchoring competitive positioning through acute care network relationships and feedback technology integration. Schiller AG and Corpuls represent European specialist manufacturers with regulatory compliance depth across MDR jurisdictions. Michigan Instruments occupies a position within the pneumatic technology legacy tier, while SunLife Science and Defibtech sit within the portable electromechanical specialization segment targeting pre-hospital service expansion.
| Leading Market Players |
|---|
| Stryker Corporation |
| ZOLL Medical Corporation |
| Michigan Instruments |
| Schiller AG |
| SunLife Science |
| Corpuls |
| Resuscitation International |
| Defibtech |
| CPR Medical Devices |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month ISO 13485 certification timelines compress inventory buffers for electromechanical compressor manufacturers, concentrating pricing power with incumbent vendors holding predicate FDA 510(k) clearances while forcing new entrants into cost-absorbing qualification delays. This lead-time structure amplifies margin capture for certified suppliers serving United States hospital procurement committees and German ambulance fleet operators.
Pricing Analysis
Next-generation hybrid electric-pneumatic systems command 25-40% premiums over legacy pneumatic installations, while first-generation portable electromechanical units face price erosion in pre-hospital tenders. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and predictive maintenance bundling. Pricing pressure stems from lithium battery input cost volatility and Chinese cylindrical cell supply qualification delays. Ambulance services in India and district hospital networks exhibit highest price sensitivity, while United States acute care networks prioritize litigation risk reduction over capital expenditure minimization.
Supply Chain Analysis
Strait of Malacca transit vulnerability for cylindrical lithium-ion cells from Chinese manufacturing zones creates chokepoint exposure for portable electromechanical compressor assemblers. Component sourcing concentrates in China for battery cells, Germany for servo motor subsystems, and Japan for force sensor modules. Raw material dependencies span rare-earth magnets, medical-grade aluminum housings, and pneumatic valve assemblies. Single-source vulnerability in Chinese battery supply chains threatens production continuity for German and Japanese ambulance fleet orders. Distribution runs through specialized emergency care procurement platforms and traditional medical device distributors serving hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual CPR training infrastructure and established certification programs constitute a persistent substitution threat that automated chest compressor incumbents must neutralize through outcome-based contracting and litigation risk quantification.
For Market Incumbents: Fortify installed base retention through predictive maintenance service agreements and biomedical technician certification programs that embed switching costs. Develop backward integration into servo motor component supply to mitigate German and Japanese supplier concentration. Counter manual CPR substitution threat by quantifying hemodynamic consistency evidence for hospital procurement committees. For New Entrants and Emerging Players: Predictive maintenance service gaps in rural Indian district ambulance fleets present white-space penetration opportunities for solar-charging-compatible portable units. Target underpenetrated pre-hospital services in Maharashtra and Karnataka with battery-powered configurations. Pursue direct-to-hospital digital distribution channel development to bypass traditional medical device distributor margin capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core resuscitation equipment divisions. Long-term viability hinges on algorithm differentiation and EU MDR compliance depth rather than hardware commoditization. Monitor ILCOR guideline translation velocity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Device Expansion | Accelerates market access for algorithm modifications in United States emergency departments. |
| EU MDR Annex IX Conformity Investment | Compresses competitive field as smaller competitors withdraw from European market access efforts. |
| Hybrid Electric-Pneumatic Development | Captures German and Japanese ambulance fleet mandates for extended transport scenarios. |
| Predictive Maintenance Platform Launch | Aligns with United States hospital outcome-based purchasing criteria and litigation risk reduction. |
| Solar Charging Compatibility Integration | Opens rural Indian district ambulance fleets to battery-powered portable unit penetration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with emergency department clinicians, hospital procurement committee members, ambulance fleet managers, biomedical engineers, and GPO contracts administrators. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment filings, hospital procurement contract registries, and ILCOR resuscitation guideline documentation. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from device shipment records and installed base estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product type, technology architecture, end-user category, and geographic regulatory cluster. CAGRs derived from replacement cycle analysis, protocol adoption curves, and compliance deadline impacts. Industry-specific inputs incorporated EU MDR transition timelines, lithium battery supply chain qualification delays, and ILCOR guideline translation velocity into national resuscitation standards.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR Annex IX conformity assessment procedures; material policy shifts would require re-modeling of validation timelines and market access barriers. Practitioners should keep alternative scenarios live as ILCOR guideline updates, battery supply chain disruptions, and pre-hospital protocol expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
Global Emergency Medical Apps Market