
 Laboratory Data Loggers Market | 2026-2036
Laboratory Data Loggers Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Data Loggers Market Foresight
Market Context
German sensor manufacturers is pivoting toward integrated calibration services to capture recurring revenue from pharmaceutical clients. Testo SE & Co. KGaA leverages its domestic production base to dominate European temperature logger distribution. Vaisala Oyj anchors its position through specialized humidity sensing technology for cleanroom applications. Onset Computer Corporation competes via compact wireless designs optimized for distributed research networks.
Technical Definition and Segments
Laboratory data loggers are electronic instruments that autonomously record environmental or process variables at programmed intervals, typically achieving measurement resolutions of 0.1°C for temperature and ±2% relative humidity accuracy. These devices serve primarily to generate audit trails for regulatory compliance and to flag deviations in sensitive storage or experimental conditions. Multi-parameter loggers command the widest deployment flexibility across pharmaceutical quality control units, while cloud-enabled loggers represent the fastest-expanding technology category as laboratories seek centralized data governance. Wired loggers retain dominance in process validation applications where electromagnetic interference exclusion takes priority over mobility.
Regulatory Outlook
FDA 21 CFR Part 11, EU GDP Annex 9, and ISO 17025 calibration standards collectively mandate tamper-evident digital records and traceable measurement uncertainty for laboratory monitoring equipment. These frameworks compel logger vendors to embed cryptographic signatures and automated alert protocols directly into firmware architectures. Stakeholders must weigh the capital cost of cloud infrastructure against the operational risk of paper-based audit failures during regulatory inspections.
Market Dynamics
Pharmaceutical cold chain compliance is compressing procurement cycles for wireless and cloud-enabled logger systems, forcing vendors to embed cryptographic validation protocols directly into firmware architectures rather than offering them as aftermarket add-ons.
Growth Catalysts
- FDA 21 CFR Part 11:Tamper-evident digital record mandates are compelling pharmaceutical manufacturers to replace paper-based temperature logs with automated audit trail systems.
- Biologics manufacturing:Cell and gene therapy production facilities require continuous environmental monitoring across distributed cleanroom suites.
- German precision clusters:Stuttgart and Munich manufacturing corridors are standardizing multi-parameter logger specifications for EMA-aligned quality protocols.
Market Restraints
- Sensor component concentration:MEMS humidity sensor supply chains concentrate in East Asian foundries, exposing European logger assemblers to input volatility.
- Calibration labor scarcity:ISO 17025-accredited technicians remain concentrated in metropolitan testing hubs, extending service lead times for peripheral installations.
- Wired logger substitution:Electromagnetic-hardened wired systems retain dominance in process validation applications where wireless interference exclusion is mandatory.
Strategic Opportunities
- India pharmaceutical exports:CDSCO-mandated cold chain documentation for generic drug shipments is creating first-time demand for GDP-compliant logger systems.
- Cloud-telemetry convergence:Integration of LoRaWAN connectivity with SaaS calibration management platforms enables remote audit preparation.
- EU Green Deal procurement:Public research funding now prioritizes energy-harvesting logger designs that eliminate battery replacement waste streams.
Industry Challenges
- Firmware validation timelines:FDA software validation requirements extend product development cycles for cloud-enabled architectures.
- Legacy system integration:Pharmaceutical quality units face protocol translation costs when connecting wireless loggers to existing LIMS infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Data Loggers Market |
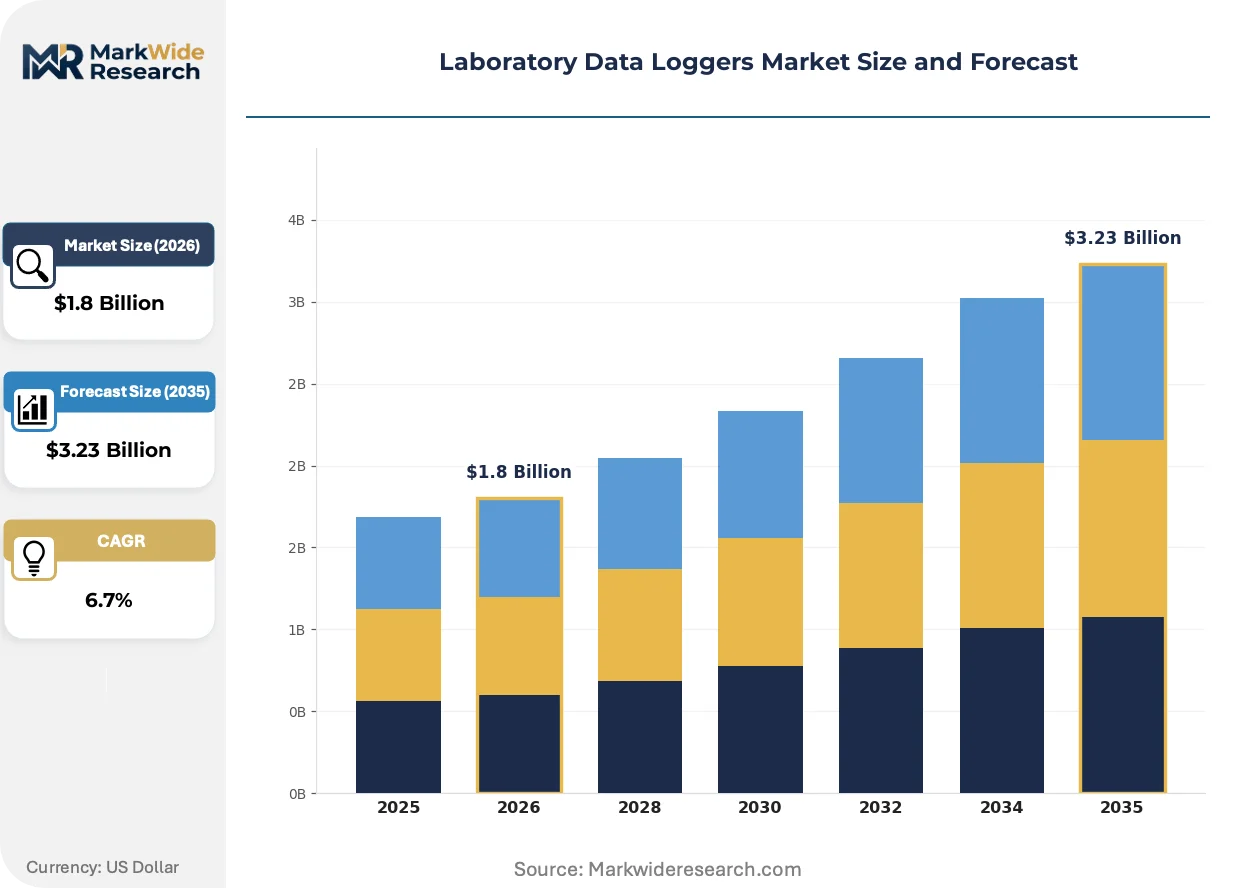
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Loggers, Humidity Loggers, Pressure Loggers, Multi-parameter Loggers End User: Pharmaceuticals, Biotechnology Firms, Research Laboratories, Quality Control Units Technology: Wired Loggers, Wireless Loggers, Bluetooth Loggers, Cloud-enabled Loggers Application: Environmental Monitoring, Process Validation, Storage Monitoring, Transport Monitoring |
| Companies Covered | Testo SE & Co. KGaA, Onset Computer Corporation, Hioki E.E. Corporation, Vaisala Oyj, Omega Engineering, Inc., ELPRO-BUCHS AG, Dickson Co., Campbell Scientific, Inc., MadgeTech, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Data Loggers Market Shifts & Advancements
Embedded cryptographic authentication and energy-harvesting power architectures are compressing the functional gap between premium validation-grade instruments and economy-tier monitoring devices.
Multi-sensor fusion architectures combining temperature, humidity, and differential pressure sensing in single-form-factor devices are rewriting procurement patterns for cleanroom qualification protocols. Biopharmaceutical quality units in Basel and Boston are adopting these consolidated instruments to reduce calibration overhead. The convergence is compressing vendor margins on standalone humidity loggers while elevating service revenue from integrated validation packages.
EU GDP Annex 9 guidance on risk-based temperature monitoring is tightening documentation requirements for wholesale distribution networks. Pharmaceutical logistics operators must now demonstrate continuous monitoring across secondary packaging handoffs. German and Dutch cold chain service providers are responding by deploying disposable Bluetooth loggers with automated cloud handoff.
Research institutions are unbundling hardware ownership from calibration service contracts, treating loggers as monitored infrastructure rather than capital equipment. University procurement offices in Oxford and Singapore are piloting subscription models where vendors retain asset ownership. This shift is most visible in distributed field research networks where equipment utilization rates remain unpredictable.
Laboratory Data Loggers Market Segmentation
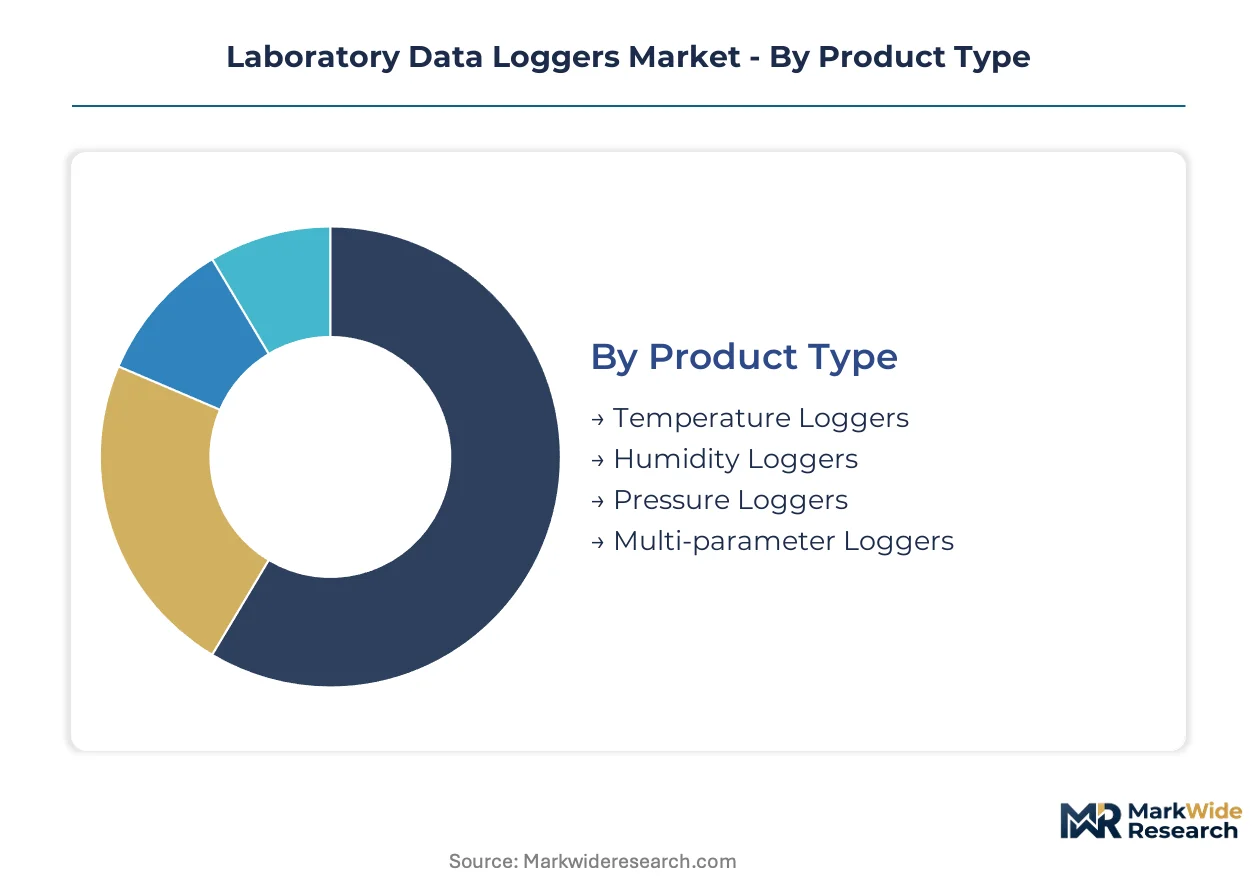
Segmentation in laboratory data loggers reveals how procurement priorities diverge between compliance-driven pharmaceutical buyers and cost-sensitive research institutions. Understanding these splits enables vendors to align firmware architectures, calibration service bundles, and distribution channels with distinct purchasing workflows.
Product Type:
Buyers select instrument tiers based on measurement complexity and validation burden rather than unit price alone.
- Multi-parameter Loggers:These instruments consolidate temperature, humidity, and differential pressure sensing within unified firmware architectures. Pharmaceutical quality control units in Stuttgart and Basel procurement offices favor consolidated validation protocols that reduce calibration overhead across cleanroom suites.
- Temperature Loggers:Single-parameter devices achieve the tightest measurement uncertainty budgets, typically ±0.1°C resolution with NIST-traceable calibration chains. Cold chain logistics operators in Dutch distribution hubs deploy these for GDP Annex 9 compliance across secondary packaging handoffs.
- Humidity Loggers:Specialized capacitive or resistive sensors target cleanroom qualification and stability chamber validation where relative humidity excursions threaten biologic product integrity.
- Pressure Loggers:Differential pressure instruments monitor containment integrity in biosafety cabinets and isolator systems, serving gene therapy manufacturing facilities with stringent environmental controls.
Volume sits with temperature loggers; growth tilts toward multi-parameter instruments.
End User:
Customer type determines service contract structure and firmware customization depth.
- Pharmaceuticals:Large manufacturers mandate embedded cryptographic signatures and automated audit trails for FDA 21 CFR Part 11 compliance. These buyers prioritize validation documentation packages over hardware acquisition cost.
- Biotechnology Firms:Cell and gene therapy developers require continuous monitoring across distributed cleanroom suites with LoRaWAN telemetry for remote audit preparation.
- Research Laboratories:University procurement offices in Oxford and Singapore pilot subscription ownership models where vendors retain asset control and calibration responsibility.
- Quality Control Units:Embedded within larger manufacturing organizations, these groups specify logger integration with existing LIMS infrastructures and SAP quality management modules.
Pharmaceuticals dominate current installed base; biotechnology firms are expanding most quickly.
Technology:
Connectivity architecture trades electromagnetic resilience against deployment flexibility and total cost of ownership.
- Cloud-enabled Loggers:Devices with native SaaS integration enable centralized data governance and remote audit preparation. These systems command premium positioning as pharmaceutical cold chain compliance compresses procurement cycles toward automated documentation.
- Wireless Loggers:WiFi and proprietary radio protocols serve distributed research networks where cabling infrastructure proves impractical. Battery life and network security protocols remain primary selection criteria.
- Bluetooth Loggers:Short-range connectivity supports disposable or semi-disposable deployments for transport monitoring and last-mile distribution handoffs.
- Wired Loggers:Electromagnetic-hardened systems retain dominance in process validation applications where interference exclusion outweighs mobility requirements.
Wired systems anchor validation-grade applications; cloud-enabled architectures gain share fastest.
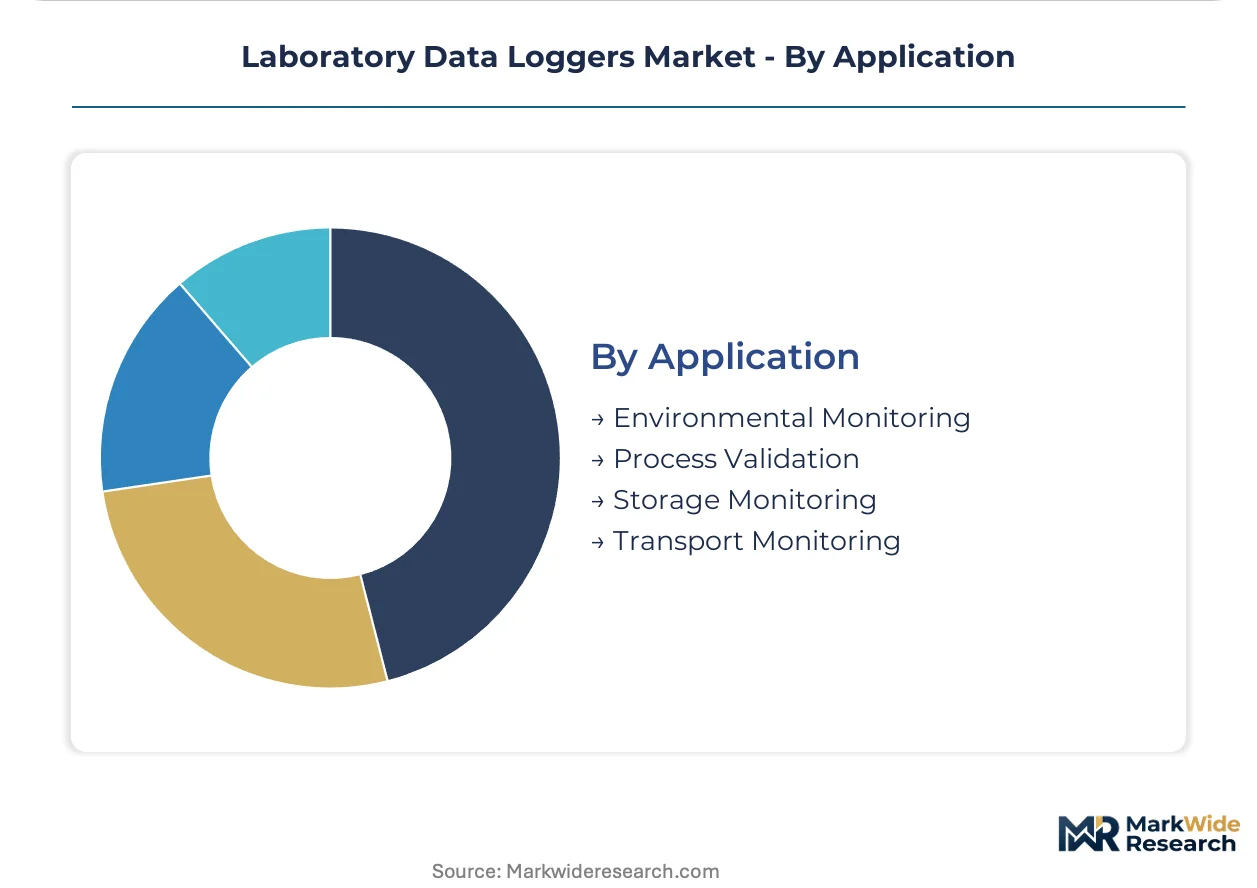
Application:
Use case dictates sensor specification, data logging frequency, and regulatory documentation depth.
- Environmental Monitoring:Continuous tracking of temperature, humidity, and pressure in manufacturing suites, warehouses, and stability chambers. Multi-sensor fusion architectures are rewriting procurement patterns for cleanroom qualification protocols.
- Storage Monitoring:Long-duration logging with extended battery life for ultra-low temperature freezers and cryogenic repositories serving biorepositories and cell therapy manufacturing.
- Process Validation:High-accuracy, tamper-evident records for equipment qualification and batch release documentation under FDA and EMA guidelines.
- Transport Monitoring:Ruggedized, disposable, or returnable loggers for shipment integrity verification across pharmaceutical cold chain distribution networks.
Environmental monitoring captures the broadest deployment base; transport monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Taiwan and South Korea supplies the MEMS sensor cores that European and North American logger assemblers depend upon for humidity and pressure measurement modules.
Germany
Stuttgart and Munich manufacturing corridors standardize multi-parameter logger specifications for EMA-aligned pharmaceutical quality protocols. The German Medicines Act (AMG) and GDP guidelines mandate continuous environmental monitoring across wholesale distribution networks. Baden-Württemberg precision clusters drive premium instrument procurement for cleanroom qualification.
United States
FDA 21 CFR Part 11 compliance requirements compress procurement cycles toward automated audit trail systems in biologics manufacturing. The FDA's software validation framework extends development timelines for cloud-enabled logger architectures. Greater Boston cell and gene therapy facilities deploy continuous monitoring across distributed cleanroom suites.
India
CDSCO-mandated cold chain documentation for generic drug exports creates first-time demand for GDP-compliant logger systems. The country's national pharmaceutical regulator tightens storage monitoring requirements for temperature-sensitive shipments. Maharashtra pharmaceutical export corridors in Mumbai and Pune adopt disposable Bluetooth loggers with automated cloud handoff.
Switzerland
Swissmedic guidelines for biologics storage monitoring elevate validation-grade instrument specifications across Basel pharmaceutical quality units. The country's medical device regulator aligns with EU MDR traceability requirements for environmental monitoring equipment. Basel biopharmaceutical clusters adopt multi-sensor fusion architectures to reduce calibration overhead.
Japan
PMDA quality guidelines for cell therapy manufacturing drive adoption of tamper-evident digital record systems. METI standards for measurement traceability mandate ISO 17025-accredited calibration chains for laboratory equipment. Kanto region research institutions in Tokyo and Tsukuba pilot subscription ownership models where vendors retain asset control.
Laboratory Data Loggers Market Competitive Landscape
Global majors compete with regional champions across firmware validation capabilities and calibration service density. The vendor base organizes around three tiers: integrated validation-grade specialists, wireless connectivity-focused technology providers, and economy-tier hardware assemblers. Two dominant competitive moves are reshaping positioning: backward integration into sensor component sourcing to secure MEMS supply, and geographic expansion through calibration laboratory networks to reduce service lead times.
Within the integrated validation-grade tier, Testo SE & Co. KGaA and Vaisala Oyj exemplify archetypes combining domestic production bases with specialized sensing technology. Among North American connectivity-focused providers, Onset Computer Corporation occupies a position emphasizing compact wireless designs. ELPRO-BUCHS AG represents the Swiss-German precision segment with embedded cryptographic authentication capabilities. These named entities anchor industry-level commentary on how firmware architecture choices and service model differentiation separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Testo SE & Co. KGaA |
| Onset Computer Corporation |
| Hioki E.E. Corporation |
| Vaisala Oyj |
| Omega Engineering, Inc. |
| ELPRO-BUCHS AG |
| Dickson Co. |
| Campbell Scientific, Inc. |
| MadgeTech, Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal procurement mandates for energy-harvesting logger designs are gating qualified supply access and premium-tier pricing power, as battery-free architectures require specialized MEMS foundry partnerships that only ISO 17025-accredited assemblers can secure.
Pricing Analysis
Warranty and calibration service bundling separates premium validation-grade instruments from unbundled economy-tier hardware. Three-tier pricing structure across premium, standard, and economy levels reflects firmware validation depth and ISO 17025 certification status. Cost compression in economy-tier wired loggers is intensifying because East Asian contract manufacturers are absorbing margin pressure from MEMS sensor input volatility. Research laboratories exhibit highest price sensitivity, while pharmaceutical quality units prioritize validation documentation over acquisition cost.
Supply Chain Analysis
MEMS humidity and pressure sensor cores rest on Taiwanese and South Korean wafer fabrication capacity that European and North American logger assemblers cannot easily replicate. Raw material dependencies span silicon wafers, lithium coin cells, and specialized polymer sensor housings. Single-source vulnerability in East Asian foundry concentration exposes assemblers to geopolitical logistics chokepoints. Distribution runs through authorized calibration laboratory networks that pharmaceutical buyers mandate for GDP-compliant documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited technician scarcity across metropolitan testing hubs props pricing for integrated calibration service bundles, constraining rapid capacity expansion by new entrants.
For Market Incumbents: Deploy backward integration into MEMS sensor sourcing to secure captive supply of humidity and pressure measurement modules. Anchor calibration laboratory networks in Stuttgart and Basel corridors to compress service lead times for EMA-aligned pharmaceutical clients. Wireless connectivity specialists threaten premium positioning through compact LoRaWAN designs; firmware cryptographic validation investments defend against audit-trail commoditization.
For New Entrants and Emerging Players: Launch via subscription ownership models targeting Oxford and Singapore research institutions where equipment utilization rates remain unpredictable. CDSCO-mandated cold chain documentation for Indian pharmaceutical exports represents the most penetrable geography. SaaS calibration management platforms enable remote audit preparation without legacy LIMS integration costs.
For Investors and Strategic Acquirers: Cloud-telemetry convergence with automated GDP compliance handoff is the leading indicator that recurring revenue models are displacing transactional hardware sales. Five-to-ten year viability favors vendors combining domestic production bases with specialized sensing technology rather than pure connectivity plays. Acquisition targets should display embedded cryptographic authentication capabilities and existing FDA 21 CFR Part 11 validation documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sourcing | Captive sensor supply from Taiwanese foundries insulates assemblers from input volatility. |
| Calibration Laboratory Network Expansion | Baden-Württemberg and Basel proximity compresses service lead times for pharmaceutical clients. |
| Energy-Harvesting Product Line Launch | EU Green Deal compliance opens public research funding for battery-free architectures. |
| Cloud-Telemetry Platform Integration | SaaS calibration management enables remote audit preparation for distributed cleanroom suites. |
| Subscription Ownership Model Pilot | Oxford and Singapore university procurement offices treat loggers as monitored infrastructure. |
Research Methodology
Multi-period observation of pharmaceutical cold chain compliance mandates, MEMS sensor supply allocations, and calibration laboratory capacity utilization anchored the trend analysis, supplemented by interviews with quality control unit heads, regulatory affairs specialists at EMA-aligned manufacturers, biomedical engineers in gene therapy facilities, and procurement officers at research institutions. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU GDP Annex 9 regulatory texts, ISO 17025 accreditation registries, and customs data on sensor component trade flows. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Segment-weighting across product type, end user, technology architecture, and application use case informed the analytical framework. Temperature logger volumes, multi-parameter instrument growth trajectories, cloud-enabled adoption curves, and pharmaceutical versus research institution procurement splits were modeled throughout the forecast period. CAGRs derived from historical penetration rates adjusted for regulatory enforcement intensity and sensor technology substitution patterns. Firmware validation timeline extensions and legacy LIMS integration friction served as industry-specific forecast modifiers.
Regulatory enforcement delays, MEMS foundry capacity reallocation, and pharmaceutical capital expenditure freezes are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about compliance mandate timelines and sensor supply continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Microplate Reader Market