
 Western Blotting Processors Market | 2026-2036
Western Blotting Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Western Blotting Processors Market Outlook
Buyer concentration in academic research institutions is expanding as federal funding agencies consolidate grants toward high-throughput proteomics centers, while smaller laboratories fragment across shared core facility models. Bio-Rad Laboratories leverages its installed base of electrophoresis systems to sustain recurring revenue from consumables and accessories. Thermo Fisher Scientific anchors its position through integrated workflows spanning imaging systems and detection reagents. Merck KGaA competes in European markets with specialized transfer equipment optimized for sensitive protein detection.
Western blotting processors are laboratory instruments that automate or semi-automate the transfer, blocking, antibody incubation, and detection steps of protein immunodetection, typically operating with throughput capacities from 1 to 96 samples per run and detection sensitivity thresholds in the picogram range. Their primary commercial purpose is to standardize reproducibility in protein expression analysis while reducing manual handling time for research and diagnostic laboratories. Automated systems command the highest margin pools due to capital intensity and service attach rates, while imaging systems represent the fastest-growing technology segment driven by multiplex fluorescence capabilities. Academic research institutions remain the dominant end user channel, though pharmaceutical companies are shifting procurement toward validated systems for biomarker discovery workflows.
FDA oversight of in-vitro diagnostic reagents and EMA's In Vitro Diagnostic Regulation shape validation requirements for detection reagents used in clinical laboratory settings, while ISO 13485 quality management standards govern manufacturing processes for equipment destined for regulated environments. The EU AI Act introduces emerging compliance considerations for automated image analysis algorithms embedded in next-generation imaging systems. Stakeholders must monitor evolving cross-border harmonization between FDA and EMA technical documentation requirements as automated western blotting platforms seek dual-market clearance.
Market Dynamics
Precision medicine infrastructure investments are consolidating procurement authority toward high-throughput proteomics centers, fragmenting smaller laboratories into shared core facility models that prioritize automated workflow standardization over capital ownership.
Growth Catalysts
- FDA diagnostic reagent oversight:Tightening validation requirements for transfer equipment and detection systems are forcing laboratories to upgrade legacy manual systems toward validated automated platforms.
- Multiplex fluorescence capabilities:Imaging systems with picogram-range detection thresholds are displacing chemiluminescence in biomarker discovery workflows across academic research institutions.
- German biopharmaceutical R&D scaling:Federal funding consolidation toward protein analysis centers is concentrating demand for throughput capacities from 1 to 96 samples per run.
Market Restraints
- Capital intensity of automated systems:Service attach rates and maintenance contracts create multi-year total cost of ownership barriers for mid-sized diagnostic laboratories.
- Supply concentration in optical sensor components:Dependence on specialized CCD and CMOS detector suppliers exposes lead time volatility for imaging system manufacturers.
- Technical limitation in low-abundance protein detection:Sensitivity thresholds below picogram range remain unreliable for clinical diagnostic applications without extensive protocol optimization.
Strategic Opportunities
- China precision medicine infrastructure:Biopharmaceutical R&D capacity expansion is creating demand for integrated electrophoresis-to-detection workflows in tier-one research clusters.
- EU AI Act compliance services:Automated image analysis algorithm validation represents emerging revenue pools for equipment vendors seeking dual-market FDA-EMA clearance.
- Convergence of western blotting with mass spectrometry:Hybrid protein characterization workflows are opening procurement channels in proteomics core facilities seeking unified sample preparation.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation for regulated environments extends product launch cycles by 12-18 months.
- Integration complexity with legacy gel electrophoresis systems:Proprietary cartridge formats and software protocols create switching friction for laboratories with sunk investments in existing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Western Blotting Processors Market |
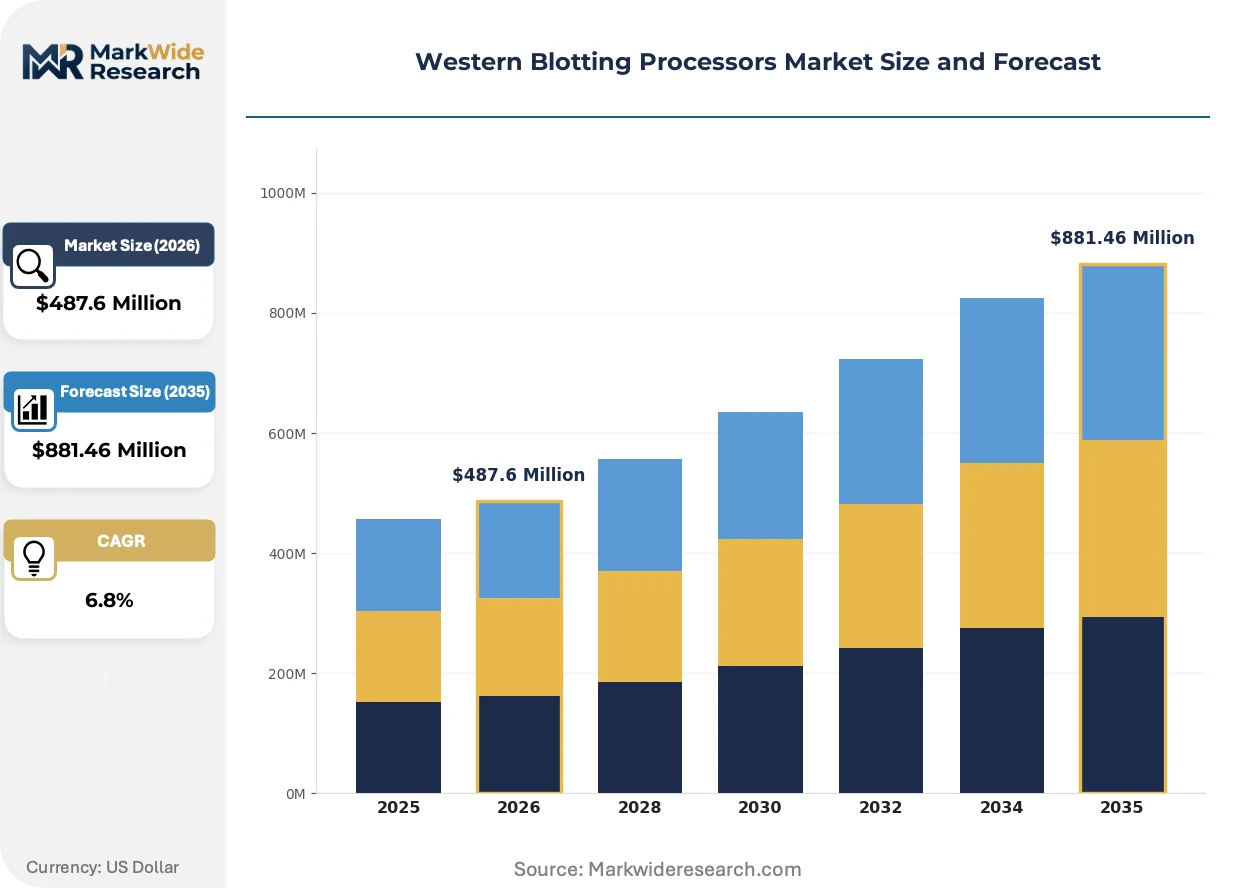
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Semi-Automated Systems, Manual Equipment, Accessories End User: Academic Research Institutions, Pharmaceutical Companies, Clinical Laboratories, Biotechnology Firms Technology: Electrophoresis, Imaging Systems, Transfer Equipment, Detection Reagents Application: Protein Analysis, Disease Diagnosis, Biomarker Discovery, Quality Control |
| Companies Covered | Bio-Rad Laboratories, Thermo Fisher Scientific, GE Healthcare, Merck KGaA, PerkinElmer, Agilent Technologies, LI-COR Biosciences, Bio-Techne Corporation, Analytik Jena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Western Blotting Processors Market Strategic Shifts
Multiplex detection architectures and algorithmic image analysis are compressing the traditional separation between protein separation and quantification steps, enabling single-run biomarker panel validation.
Fluorescence-based multiplex western blotting is unifying protein detection with spatial resolution capabilities previously requiring separate immunohistochemistry workflows. Pharmaceutical companies developing biomarker discovery pipelines are adopting these systems at accelerating replacement cycles for legacy chemiluminescence platforms. The technology is unifying capital equipment procurement decisions that previously fragmented across imaging, analysis software, and reagent suppliers.
EMA's In Vitro Diagnostic Regulation is mandating technical documentation harmonization that exceeds prior CE marking requirements for detection reagents used in clinical settings. Equipment manufacturers must now validate transfer efficiency and antibody binding consistency across temperature and humidity ranges. Automated western blotting platforms seeking dual-market clearance are restructuring quality management systems to satisfy both FDA 510(k) and EMA technical file requirements simultaneously.
Core facility service contracts are displacing direct equipment ownership among academic research institutions with fragmented laboratory structures. Federal funding agencies in the United States and Germany are consolidating grants toward centralized proteomics centers that amortize high-throughput systems across multiple principal investigators. This concentration is most visible in National Institutes of Health-funded institutions where shared resource facility budgets now exceed individual laboratory capital allocations.
Western Blotting Processors Market Segmentation
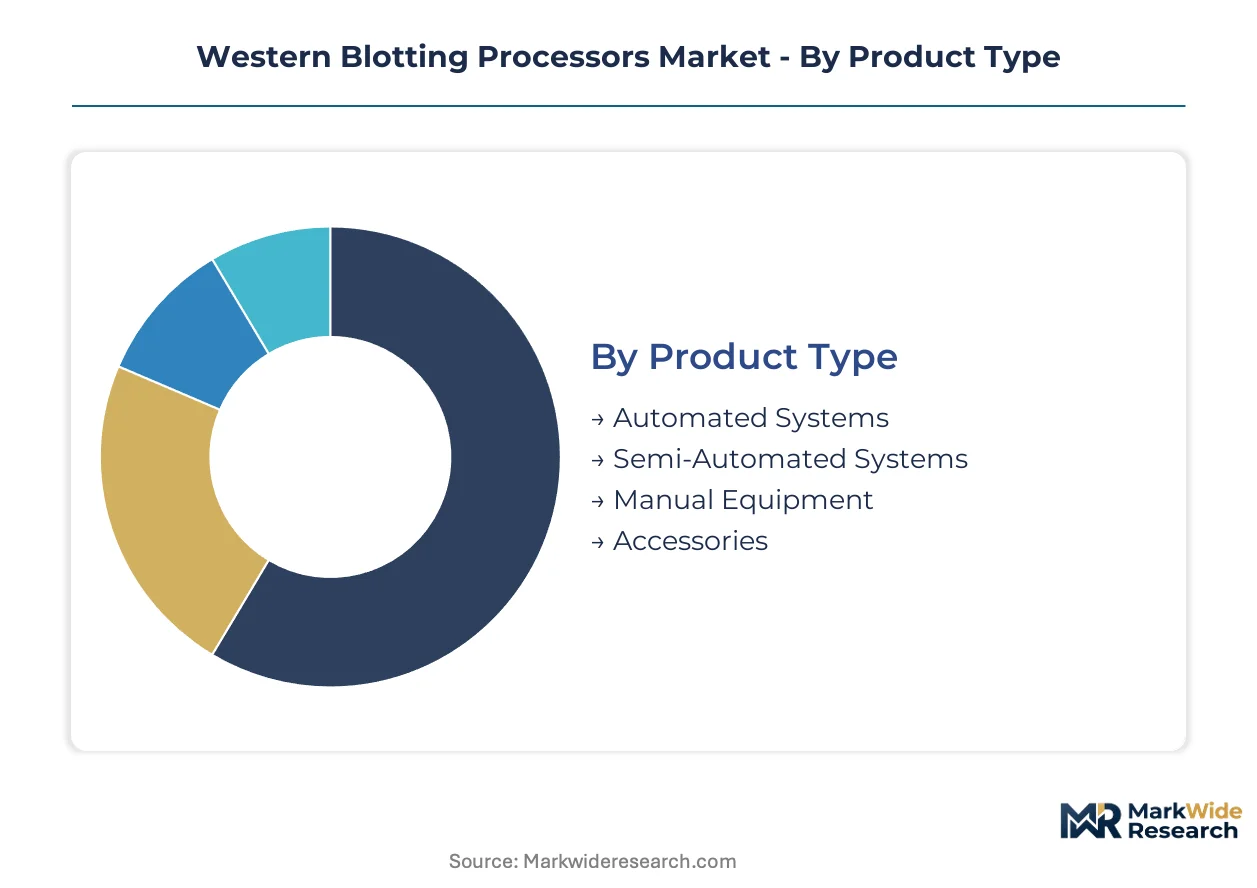
Procurement patterns in western blotting processors diverge sharply across capital intensity tiers and validation requirements. Laboratories select equipment based on throughput demands, regulatory exposure, and integration with existing electrophoresis infrastructure.
Product Type:
Capital allocation decisions separate high-throughput core facilities from fragmented laboratory networks.
- Automated Systems:These platforms integrate transfer, blocking, incubation, and detection with programmable protocols and 1-96 sample throughput ranges. Academic proteomics centers in the United States and Germany concentrate procurement here, driven by NIH and DFG funding consolidation toward shared resource facilities.
- Semi-Automated Systems:Modular designs automate selective workflow steps while preserving manual control over critical protocol variables. Mid-sized biotechnology firms in China favor these for biomarker discovery pipelines requiring flexibility without full validation burdens.
- Manual Equipment:Entry-level transfer tanks and gel boxes serve budget-constrained teaching laboratories.
- Accessories:Consumable membranes, antibody dilution stations, and calibration standards generate recurring revenue streams.
Volume sits with Manual Equipment; growth tilts toward Automated Systems.
End User:
Validation requirements and funding mechanisms reshape purchasing authority across institutional types.
- Academic Research Institutions:Federal grant consolidation is concentrating capital budgets in centralized proteomics cores rather than individual laboratories. These facilities prioritize throughput capacity and workflow standardization across multiple principal investigators.
- Pharmaceutical Companies:Biomarker discovery groups demand FDA-validated platforms with audit trails for IND-enabling studies. EMA's In Vitro Diagnostic Regulation is extending documentation requirements for detection reagents used in clinical biomarker workflows.
- Clinical Laboratories:ISO 13485 certification requirements constrain vendor selection for diagnostic applications.
- Biotechnology Firms:Venture-funded startups favor service contracts and shared facility access over direct capital ownership.
Procurement authority concentrates in Academic Research Institutions; steepest expansion trajectory appears in Pharmaceutical Companies.
Technology:
Detection sensitivity thresholds and multiplexing capabilities determine replacement cycles and margin structures.
- Imaging Systems:Multiplex fluorescence detectors with picogram-range sensitivity are displacing chemiluminescence in biomarker discovery workflows. German biopharmaceutical R&D clusters and Chinese precision medicine infrastructure investments are driving accelerated replacement demand.
- Electrophoresis:Separation systems with proprietary cartridge formats create switching friction and sustain installed-base loyalty.
- Transfer Equipment:Semi-dry and wet transfer systems optimize protein migration efficiency for different molecular weight ranges.
- Detection Reagents:Antibody conjugates and chemiluminescent substrates face tightening FDA and EMA validation requirements for clinical diagnostic use.
Revenue concentrates in Electrophoresis; margin expansion favors Imaging Systems.
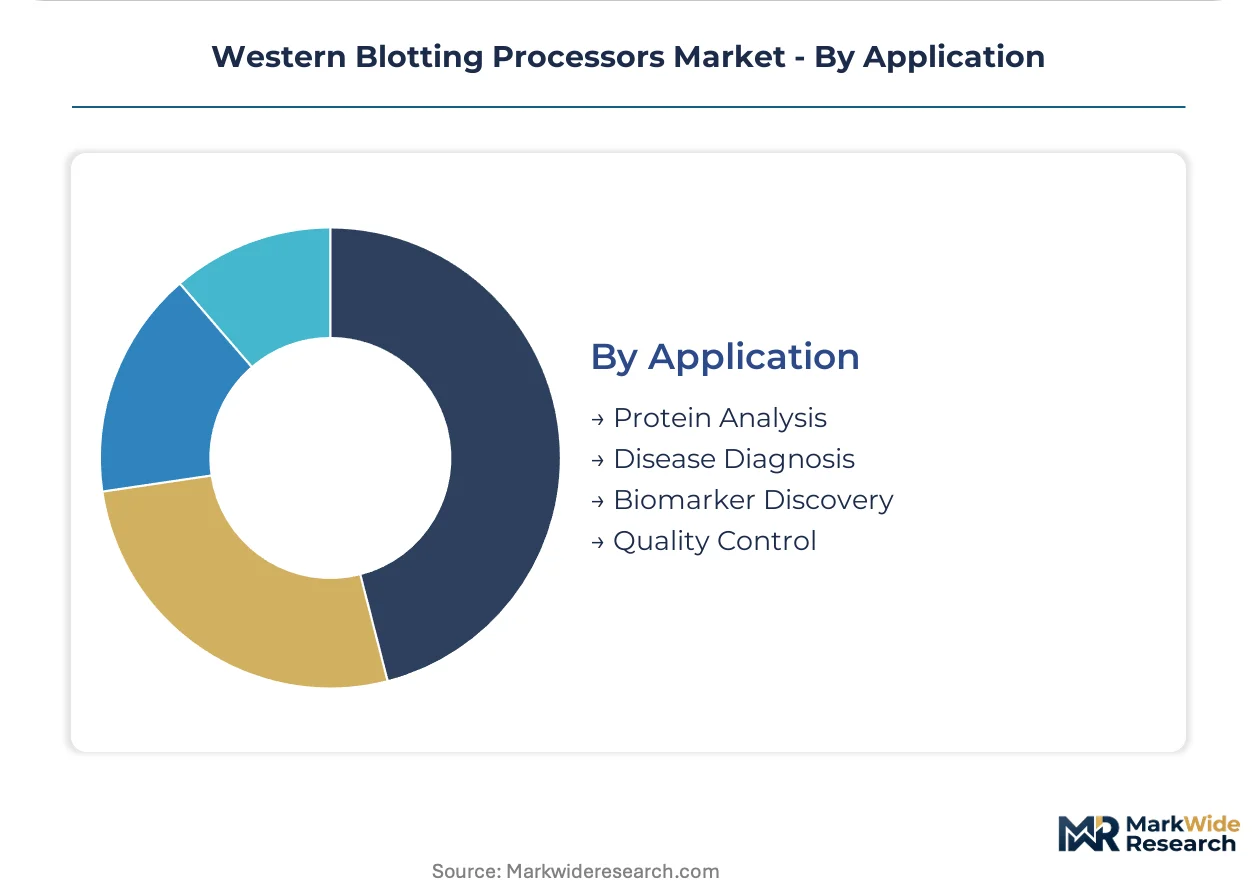
Application:
Regulatory classification and reimbursement pathways segment demand across research and clinical use cases.
- Protein Analysis:Expression profiling and post-translational modification studies dominate academic research workflows. Core facilities in the United States amortize automated platforms across high-throughput protein characterization service menus.
- Biomarker Discovery:Multiplex panel validation for precision medicine applications requires quantitative reproducibility. Chinese biopharmaceutical R&D capacity expansion and German federal funding for protein analysis centers are concentrating demand for validated workflows.
- Disease Diagnosis:Clinical validation requirements limit participation to ISO 13485-certified equipment manufacturers.
- Quality Control:Biopharmaceutical manufacturing release testing demands compliance with FDA and EMA technical documentation standards.
Activity concentrates in Protein Analysis; regulatory tailwinds favor Biomarker Discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in three distinct national clusters where precision medicine infrastructure and biopharmaceutical R&D capacity are scaling simultaneously. Federal funding consolidation and diagnostic regulatory tightening are reshaping procurement geography.
United States
NIH grant consolidation toward shared proteomics cores is fragmenting individual laboratory capital ownership. FDA diagnostic reagent oversight tightens validation requirements for transfer equipment and detection systems. The Greater Boston and San Francisco Bay Area biotech clusters drive replacement demand for multiplex fluorescence imaging systems.
Germany
DFG funding for high-throughput protein analysis centers concentrates procurement authority in centralized facilities. EMA's In Vitro Diagnostic Regulation extends documentation requirements for clinical biomarker workflows. The Munich and Heidelberg research clusters prioritize automated platforms with 1-96 sample throughput ranges.
China
Biopharmaceutical R&D capacity expansion in tier-one research clusters creates demand for integrated electrophoresis-to-detection workflows. NMPA quality standards for in-vitro diagnostic reagents are tightening equipment validation protocols. The Yangtze River Delta and Pearl River Delta concentrate procurement for precision medicine infrastructure investments.
United Kingdom
Research council funding consolidation favors core facility service contracts over direct equipment ownership. MHRA alignment with EMA technical documentation requirements shapes dual-market clearance strategies. The Cambridge and Oxford life science clusters drive adoption of validated automated platforms for biomarker discovery.
Japan
PMDA oversight of diagnostic reagents accelerates laboratory upgrades toward validated automated systems. METI precision medicine initiatives concentrate procurement in designated national research centers. The Kanto and Kansai metropolitan areas lead imaging system replacement cycles for multiplex fluorescence capabilities.
Western Blotting Processors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular semi-automated configurations for mid-sized biotechnology laboratories. The vendor base organizes around three archetypes: integrated workflow specialists leveraging electrophoresis-to-detection system bundles, imaging technology specialists commanding premium positioning through multiplex fluorescence capabilities, and European transfer equipment specialists optimizing sensitivity thresholds. Consolidation pressure intensifies through strategic partnerships between consumables suppliers and imaging platform developers, while geographic expansion into Chinese tier-one research clusters accelerates among Western manufacturers.
Among integrated workflow specialists, Bio-Rad Laboratories and Thermo Fisher Scientific exemplify contrasting archetypes. Bio-Rad Laboratories represents the installed-base leverage model, converting electrophoresis system loyalty into recurring consumables revenue. Thermo Fisher Scientific anchors the full-stack integration approach, spanning imaging hardware through detection reagents. Merck KGaA occupies a specialized position among European transfer equipment fabricators, with KGaA corporate structure indicating German-origin family-controlled enterprise positioning.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| GE Healthcare |
| Merck KGaA |
| PerkinElmer |
| Agilent Technologies |
| LI-COR Biosciences |
| Bio-Techne Corporation |
| Analytik Jena |
| Others |
Value Chain & Pricing Dynamics
Multiplex fluorescence detection architectures are compressing cost economics for high-sensitivity imaging while concentrating procurement power among CCD and CMOS sensor suppliers in Germany, Japan, and the United States. This technology transition simultaneously elevates capital barriers for automated platform manufacturers and fragments margin pools across consumables-dependent revenue models.
Pricing Analysis
Volume concentrates in manual transfer equipment and entry-level gel boxes serving teaching laboratories, while margin expansion accrues to automated systems with 1-96 sample throughput ranges and service attach rates. Price differentiation hinges on FDA validation tier for clinical diagnostic applications and ISO 13485 certification status for regulated environments. Cost compression in semi-automated configurations is intensifying because Chinese biotechnology firms are consolidating procurement through shared core facility service contracts rather than direct capital ownership. Academic research institutions exhibit highest price sensitivity due to federal grant fragmentation, whereas pharmaceutical companies prioritize audit trail capabilities and regulatory documentation over unit cost.
Supply Chain Analysis
ISO 13485 certification and FDA quality system regulation compliance function as gating mechanisms that extend equipment launch cycles by 12-18 months for manufacturers targeting clinical diagnostic channels. Optical sensor fabrication concentrates in Germany, Japan, and the United States, while precision machining for transfer equipment draws from Chinese and Taiwanese supplier networks. Specialized CCD and CMOS detector dependence creates single-source vulnerability for imaging system manufacturers facing lead time volatility. Distribution runs through direct sales forces for automated platforms in academic proteomics centers, with consumables and accessories flowing through laboratory supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Western blotting processors represent a consolidation play where EMA In Vitro Diagnostic Regulation documentation burdens and FDA diagnostic reagent oversight are forcing undercapitalized equipment vendors toward strategic exit.
For Market Incumbents: Lock in installed-base loyalty through proprietary cartridge formats that increase switching friction for laboratories with sunk investments in existing electrophoresis systems. Deepen consumables revenue streams by binding detection reagent supply to imaging platform hardware through validated workflow bundles. Threat from modular semi-automated entrants in Chinese mid-sized biotechnology laboratories demands preemptive channel control in tier-one research clusters. For New Entrants and Emerging Players: Begin with modular semi-automated configurations targeting venture-funded biotechnology firms in China that favor service contracts over capital ownership. White-space exists in EU AI Act compliance services for automated image analysis algorithm validation supporting dual-market FDA-EMA clearance. Go-to-market angle should emphasize flexible procurement models that amortize equipment access across multiple principal investigators without full validation burden. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated workflow specialists seeking electrophoresis-to-detection system bundles. Long-term viability favors vendors with captive consumables revenue and established ISO 13485 quality management infrastructure. Signal to watch is NMPA quality standard tightening in China that will accelerate laboratory upgrades toward validated automated platforms and compress replacement cycles for legacy manual systems.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Platform Launch | Captures NIH and DFG grant consolidation toward high-throughput proteomics centers. |
| Consumables Revenue Binding | Converts electrophoresis system loyalty into recurring membrane and reagent sales. |
| Dual-Market Clearance Investment | Simultaneous FDA 510(k) and EMA technical file validation opens clinical diagnostic channels. |
| Algorithm Validation Service | EU AI Act compliance for automated image analysis creates emerging revenue pool. |
| Core Facility Partnership | Shared resource facility contracts displace direct ownership among fragmented academic laboratories. |
Study Parameters
SEC 10-K filings, FDA 510(k) clearance databases, and EMA technical documentation registries formed the secondary backbone for equipment revenue and regulatory pathway analysis. Primary interviews with proteomics core facility directors, biopharmaceutical R&D procurement leads, and laboratory supply distributors validated secondary estimates and informed segmentation assumptions. Bottom-up and top-down triangulation reconciled manufacturer shipment data with end-user procurement surveys across academic, pharmaceutical, and clinical laboratory channels.
Bottom-up modeling aggregated product-level revenue across automated systems, semi-automated platforms, imaging hardware, and consumables accessories, while top-down analysis cross-checked totals against federal funding allocation patterns and biopharmaceutical R&D expenditure trends. Segmentation dimensions included product type, end user category, detection technology, and application area across the analysis window. CAGRs derived from curve-fitting historical shipment trajectories against precision medicine infrastructure investment schedules and regulatory tightening timelines.
Underlying measurement precision varies by segment; automated systems and imaging hardware carry tighter precision due to concentrated manufacturer reporting, while manual equipment and accessories estimates draw from distributor channel sampling with wider confidence intervals. Forecasts reflect assumptions regarding federal funding consolidation rates, EMA In Vitro Diagnostic Regulation implementation pace, and Chinese biopharmaceutical R&D capacity expansion that could revise materially if policy priorities shift. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market