
 Global Hematology Instruments and Reagents Market | 2026-2036
Global Hematology Instruments and Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hematology Instruments and Reagents Market Foresight
Silicon photomultipliers is decoupling legacy photomultiplier tube dependency in optical detection hematology analyzers, cutting detector costs while preserving fluorescence sensitivity. Sysmex Corporation leverages its Japan-centric manufacturing scale to dominate high-throughput automated analyzer exports. Danaher Corporation anchors North American reagent supply through captive formulation networks. Siemens Healthineers competes on integrated platform architectures that bundle hematology with immunoassay workflows.
Hematology instruments and reagents encompass automated analyzers, coagulometers, flow cytometers, and consumable reagents designed for quantitative blood cell analysis and coagulation profiling, typically operating through impedance-based counting chambers with hydrodynamic focusing achieving coefficients of variation below 3% for erythrocyte indices. Automated analyzers occupy the largest installed base across hospital core laboratories, while flow cytometers represent the fastest-expanding technology segment as immune phenotyping protocols migrate from research into routine leukemia diagnostics. Reagent streams generate recurring revenue pools with gross margins structurally higher than instrument hardware, creating asymmetric profit concentration among suppliers with locked-in consumable contracts.
FDA 510(k) clearance pathways and the EU In Vitro Diagnostic Regulation reshape product development timelines, forcing manufacturers to front-load clinical validation spending before commercial release. ISO 15189 accreditation standards for clinical laboratories drive demand for traceable calibrator materials and closed-system reagent compatibility. Stakeholders must monitor how China's NMPA accelerates domestic hematology instrument approvals against import substitution policy targets.
Market Dynamics
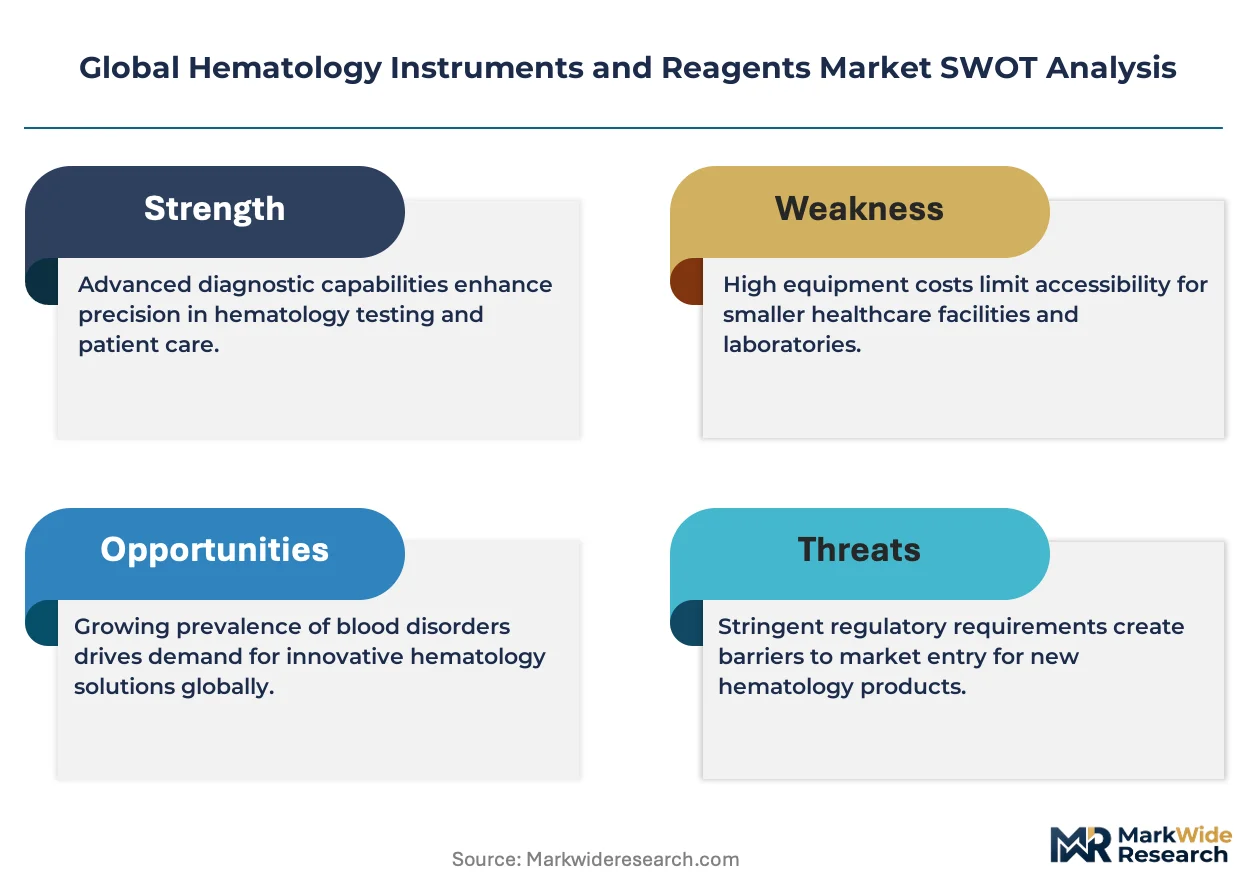
Silicon photomultiplier adoption is decoupling legacy photomultiplier tube dependency in optical detection hematology analyzers, cutting detector costs while preserving fluorescence sensitivity. This technology shift compresses hardware margins and forces reagent-centric revenue models.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined clearance timelines for moderate-risk hematology analyzers accelerate commercial release cycles for manufacturers with robust clinical validation datasets.
- Centralized Diagnostic Infrastructure Scaling:China's NMPA accelerates domestic instrument approvals against import substitution targets, concentrating demand in tier-one hospital clusters.
- Immune Phenotyping Protocol Migration:Flow cytometry adoption for routine leukemia diagnostics expands addressable test volumes beyond research settings into hospital core laboratories.
Market Restraints
- Reagent Input Cost Volatility:Fluorochrome and antibody raw material supply concentrates among specialty chemical suppliers in Germany and Switzerland, exposing margin compression risks.
- EU IVDR Compliance Friction:The In Vitro Diagnostic Regulation forces front-loaded clinical validation spending and extended notified body queue times before commercial release.
- Closed-System Lock-In Effects:Captive reagent contracts on automated analyzer platforms create switching costs that fragment procurement flexibility for mid-sized clinical laboratories.
Strategic Opportunities
- Underpenetrated Indian Diagnostics Networks:CDSCO regulatory harmonization with ISO 15189 standards opens accredited laboratory expansion in tier-two and tier-three cities.
- Artificial Intelligence-Enabled Morphology Analysis:Machine learning classification algorithms converge with digital imaging to reduce manual slide review burden in high-throughput settings.
- Point-of-Care Hematology Decentralization:Compact impedance-based analyzers penetrate ambulatory surgery centers and emergency departments previously served by core laboratory send-outs.
Industry Challenges
- Multiplex Assay Development Talent Scarcity:Cross-functional expertise spanning fluorescence chemistry, microfluidics, and clinical validation remains concentrated among specialists in Japan and the United States.
- Legacy System Integration Complexity:Hospital information system interoperability with third-party hematology middleware requires custom HL7 interface development, extending deployment timelines.
- ISO 15189 Accreditation Burden:Traceable calibrator material sourcing and closed-system reagent compatibility verification consume quality management resources in mid-cap laboratory networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hematology Instruments and Reagents Market |
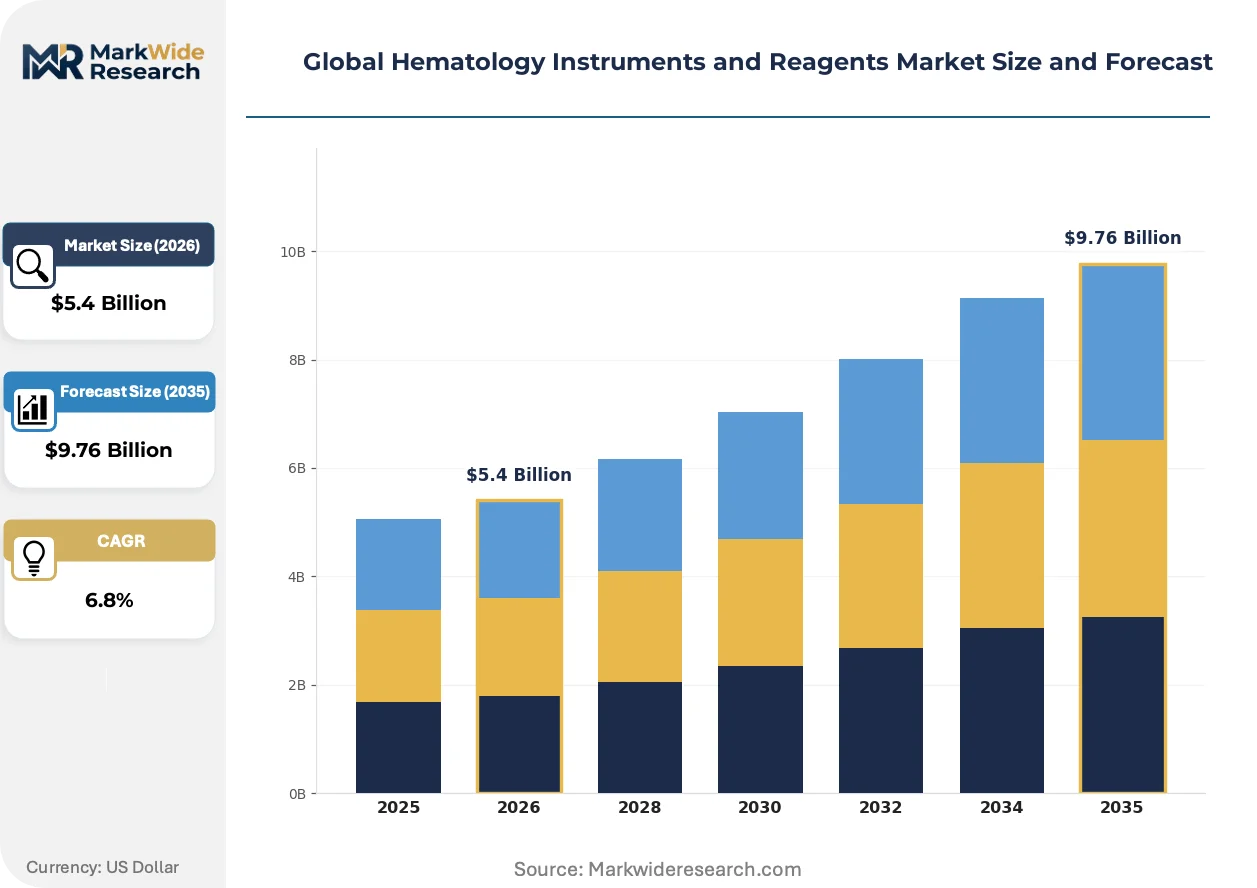
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Hematology Reagents, Coagulometers, Flow Cytometers, Microhematocrit Centrifuges Application: Blood Cell Counting, Coagulation Testing, Immune Phenotyping, Disease Diagnosis, Research Analysis End User: Clinical Laboratories, Diagnostic Centers, Blood Banks, Research Institutes, Pharmaceutical Companies Technology: Impedance, Optical Detection, Fluorescence, Cytometry, Spectrophotometry |
| Companies Covered | Sysmex Corporation, Danaher Corporation, Siemens Healthineers, Abbott Laboratories, Beckman Coulter, HORIBA Ltd, Nihon Kohden Corporation, Shenzhen Mindray Bio-Medical Electronics Co. Ltd., Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hematology Instruments and Reagents Market Shifts & Advancements
Automated analyzer architectures are converging with immunoassay platforms, compressing footprint requirements while expanding test menu breadth. This integration wave reshapes vendor competitive positioning around workflow efficiency rather than standalone hematology throughput.
Silicon photomultipliers is consolidating optical detection subsystems in next-generation flow cytometers and hematology analyzers. Academic medical centers in the United States and Germany are adopting these solid-state detectors for research-grade instruments. The technology is consolidating supplier tiers by eliminating vacuum tube manufacturing dependencies and enabling fabless semiconductor sourcing models.
REACH chemical registration requirements and RoHS substance restrictions are tightening fluorochrome and electronic component compliance burdens for hematology reagent and instrument manufacturers. The European Chemicals Agency substance evaluation process extends formulation reformulation timelines. High-complexity flow cytometry reagent portfolios face disproportionate impact as manufacturers reformulate dye conjugates to meet candidate list substance thresholds.
Hospital procurement committees are unbundling after-sales service contracts from analyzer hardware purchases, compressing multi-year maintenance agreement attach rates. Group purchasing organizations in the United States negotiate discrete service pricing separate from capital equipment financing. This behavioral shift concentrates service revenue risk on manufacturers while creating third-party independent service organization opportunities in mature installed base markets.
Global Hematology Instruments and Reagents Market Segmentation
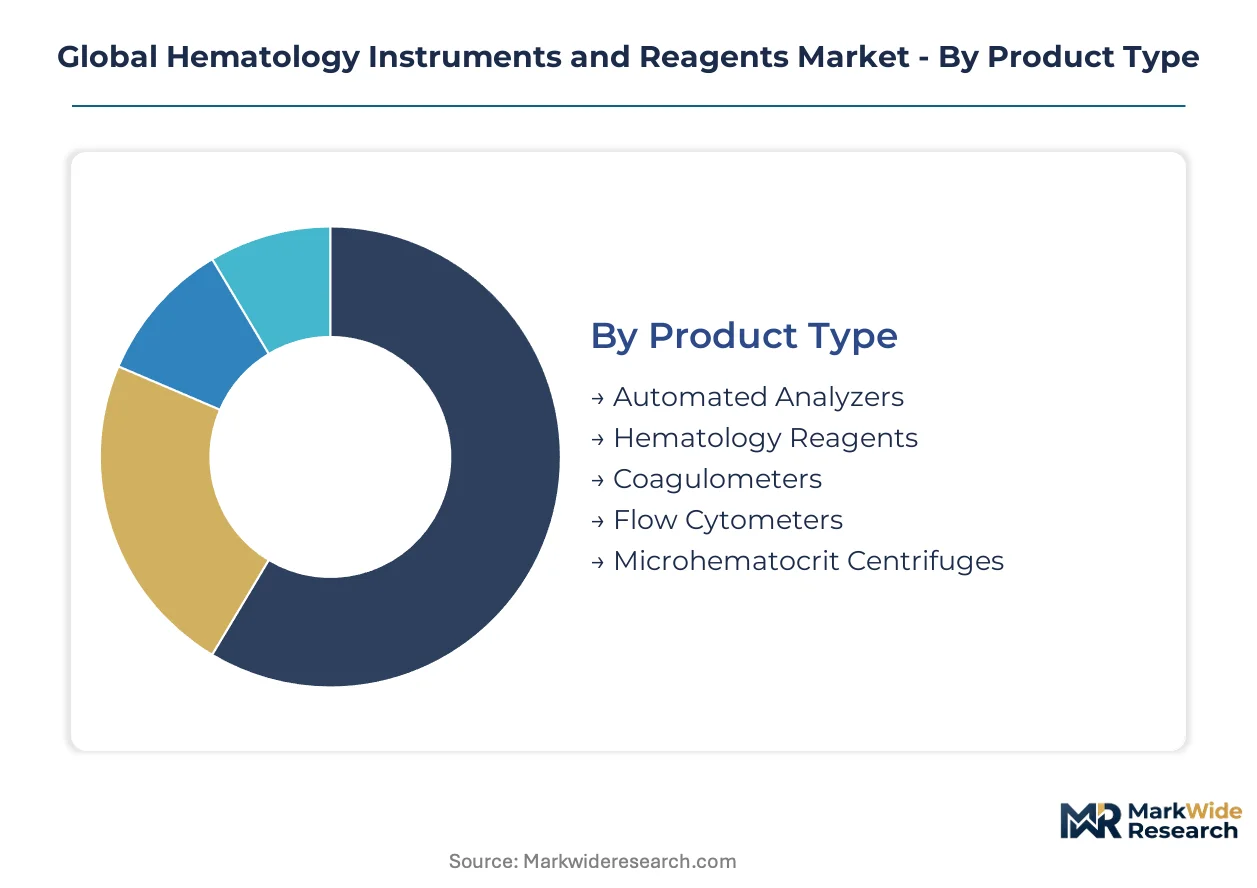
Hematology market segmentation reflects divergent procurement logic across hardware capital cycles and consumable replenishment rhythms. Buyers prioritize throughput scalability in automated analyzers, reagent compatibility in consumables, and assay specificity in research applications. Understanding these decision hierarchies enables precise positioning against laboratory budget constraints and accreditation requirements.
Product Type:
Capital allocation intensity drives purchasing committee composition and vendor negotiation leverage.
- Automated Analyzers:High-throughput systems integrate impedance-based counting chambers with hydrodynamic focusing to achieve coefficients of variation below 3% for erythrocyte indices. Hospital core laboratories in the United States and China concentrate demand as these facilities scale centralized diagnostic infrastructure to manage rising test volumes.
- Hematology Reagents:Consumable formulations include diluents, lysing agents, and calibrator materials designed for closed-system compatibility with specific analyzer platforms. Recurring revenue pools carry structurally higher gross margins than instrument hardware, creating asymmetric profit concentration among suppliers with locked-in consumable contracts.
- Coagulometers:Dedicated coagulation testing systems measure prothrombin time and activated partial thromboplastin time for hemostasis monitoring.
- Flow Cytometers:Multi-parameter cell analysis instruments are penetrating routine leukemia diagnostics beyond research settings.
- Microhematocrit Centrifuges:Compact manual devices serve point-of-care and resource-limited environments with basic hematocrit determination.
Automated analyzers lead on scale; flow cytometers lead on momentum.
Application:
Test volume concentration and reimbursement coding complexity shape segment profitability.
- Blood Cell Counting:Quantitative analysis of erythrocytes, leukocytes, and platelets constitutes the foundational workload for clinical hematology laboratories. Diagnostic centers in Germany and China drive demand as these facilities expand automated analyzer fleets to replace manual microscopy methods.
- Coagulation Testing:Hemostasis profiling monitors anticoagulant therapy and detects inherited bleeding disorders through clotting time measurement. Blood banks in the United States prioritize this application for pre-transfusion screening compliance with FDA quality benchmarks.
- Immune Phenotyping:Surface marker identification for lymphocyte subset classification supports leukemia and lymphoma diagnostics.
- Disease Diagnosis:Comprehensive hematologic assessment enables anemia, infection, and malignancy detection across patient populations.
- Research Analysis:Investigational protocols explore novel biomarkers and therapeutic mechanisms in academic settings.
Blood cell counting dominates installed base volume; immune phenotyping climbs the fastest on protocol migration into routine diagnostics.
End User:
Accreditation status and test menu breadth determine reagent contract structures and service attach rates.
- Clinical Laboratories:Hospital-affiliated and independent testing facilities process high-throughput sample volumes with ISO 15189 accreditation requirements. Laboratories in China and India concentrate procurement as NMPA and CDSCO regulatory harmonization accelerates accredited network expansion.
- Diagnostic Centers:Outpatient-focused facilities provide accessible hematology testing with streamlined workflow configurations. Centers in tier-two and tier-three Indian cities represent underpenetrated expansion territory against centralized infrastructure scaling.
- Blood Banks:Transfusion services require coagulation and cell count screening for donor qualification and component preparation.
- Research Institutes:Academic medical centers deploy flow cytometry and advanced cytometry for investigational protocols.
- Pharmaceutical Companies:Drug development operations utilize hematology endpoints for safety pharmacology and clinical trial monitoring.
Clinical laboratories anchor revenue concentration; diagnostic centers offer the steepest expansion trajectory in emerging markets.
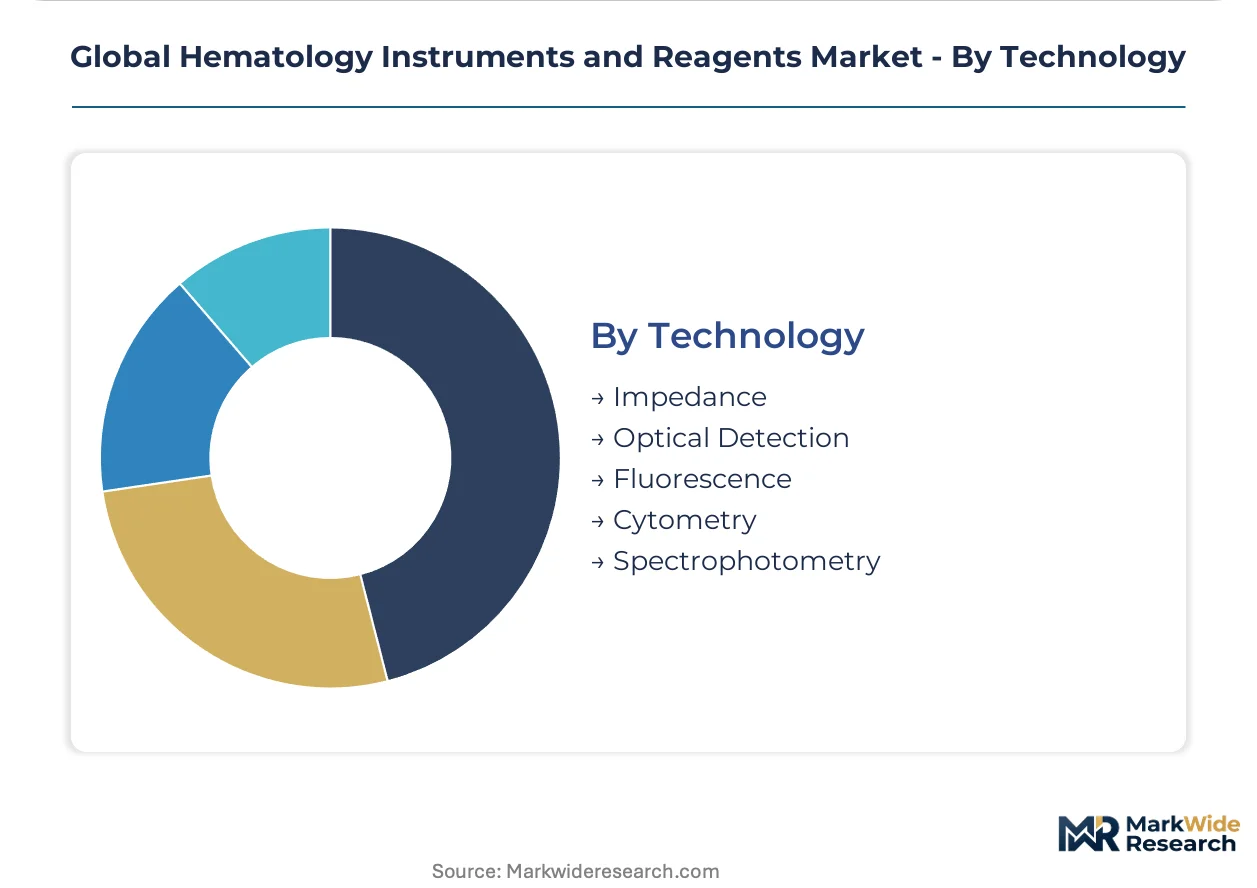
Technology:
Detection modality selection determines capital cost structures and maintenance complexity.
- Impedance:Coulter principle-based counting measures electrical resistance changes as cells pass through an aperture, enabling rapid enumeration without fluorescent labeling. Automated analyzer manufacturers in Japan leverage this mature technology for cost-efficient high-throughput platforms.
- Optical Detection:Light scatter and absorbance measurements classify cells by size and internal complexity. Silicon photomultiplier adoption is displacing legacy photomultiplier tube dependency, cutting detector costs while preserving sensitivity.
- Fluorescence:Dye-based emission detection enables specific marker identification for immune phenotyping applications.
- Cytometry:Fluidic focusing and laser interrogation support multi-parameter single-cell analysis.
- Spectrophotometry:Wavelength-specific absorbance quantification underlies hemoglobin concentration determination.
Impedance commands the largest installed base; optical detection gains share fastest on solid-state detector cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing-Tianjin-Hebei anchors the highest concentration of hematology instrument manufacturing capacity outside Japan. Regulatory divergence across major economies is fragmenting product registration pathways and extending commercialization timelines for multinational suppliers.
United States
Hospital core laboratories in Texas and California are consolidating automated analyzer fleets to manage rising test volumes. FDA 510(k) pathway modernization streamlines clearance timelines for moderate-risk hematology analyzers with robust clinical validation datasets. The Boston-Cambridge corridor concentrates flow cytometry research applications as academic medical centers migrate immune phenotyping protocols into routine diagnostics.
China
Tier-one hospital clusters in Shanghai and Guangzhou are scaling centralized diagnostic infrastructure to replace manual microscopy methods. NMPA accelerates domestic hematology instrument approvals against import substitution policy targets. The Yangtze River Delta dominates manufacturing scale for high-throughput automated analyzer exports.
Germany
Diagnostic centers in Bavaria and North Rhine-Westphalia drive demand for traceable calibrator materials under ISO 15189 accreditation standards. ECHA REACH chemical registration requirements tighten fluorochrome and electronic component compliance burdens for hematology reagent manufacturers. The Rhine-Main region concentrates specialty chemical suppliers for antibody raw materials.
India
Tier-two and tier-three cities in Maharashtra and Karnataka represent underpenetrated expansion territory for accredited laboratory networks. CDSCO regulatory harmonization with ISO 15189 standards opens diagnostic center procurement flexibility. The Delhi-NCR corridor anchors commercial distribution for imported analyzer platforms.
Japan
Academic medical centers in Tokyo and Osaka adopt silicon photomultiplier-equipped research-grade instruments. PMDA maintains stringent clinical validation requirements for novel hematology analyzer architectures. The Kansai region concentrates photonics manufacturing for solid-state detector subsystems.
Global Hematology Instruments and Reagents Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek to bundle hematology with immunoassay workflows. The vendor base concentrates around three tiers: diversified conglomerates with captive reagent networks, specialized hematology pure-plays with Japan-centric manufacturing scale, and emerging platform challengers from China. Two archetypes prevail: integrated system architects competing on workflow efficiency and consumable-centric operators defending reagent contract lock-in. M&A activity and geographic expansion represent the dominant competitive moves as manufacturers pursue closed-system installed base growth.
Among diversified conglomerates, Danaher Corporation and Siemens Healthineers exemplify the integrated platform architecture archetype. Sysmex Corporation occupies a position within the specialized pure-play tier. Shenzhen Mindray Bio-Medical Electronics Co. Ltd. represents the emerging challenger archetype competing on domestic manufacturing scale. These three anchors illustrate how competitive positioning stratifies across workflow bundling, reagent contract density, and geographic manufacturing concentration.
| Leading Market Players |
|---|
| Sysmex Corporation |
| Danaher Corporation |
| Siemens Healthineers |
| Abbott Laboratories |
| Beckman Coulter |
| HORIBA Ltd |
| Nihon Kohden Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co. Ltd. |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Hospital procurement committees unbundling after-sales service contracts from analyzer hardware purchases forces manufacturers to restructure bundled offerings and compress multi-year maintenance agreement attach rates. This buyer-driven unbundling concentrates service revenue risk on original equipment manufacturers while creating pricing volatility across discrete service pricing negotiations.
Pricing Analysis
Fluorochrome and antibody raw material supply concentration among specialty chemical suppliers in Germany and Switzerland drives input-cost pass-through into hematology reagent formulations. Pricing stratifies across premium, standard, and economy tiers based on ISO 15189 accreditation tier and closed-system compatibility verification. Cost compression in mid-tier reagent portfolios is intensifying because REACH chemical registration requirements extend formulation reformulation timelines. Mid-sized clinical laboratories exhibit highest price sensitivity due to fragmented procurement flexibility, while academic medical centers demonstrate lowest sensitivity tied to research-grade specification requirements.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, Kansai region, and Rhine-Main corridor anchor hub-and-spoke patterns for hematology instrument and reagent fulfillment. Manufacturing concentration in China, Japan, and Germany draws from silicon photomultiplier subsystems, fluorochrome dye conjugates, and precision fluidic components as critical inputs. Single-source vulnerability in photonics manufacturing for solid-state detectors exposes supply continuity risks. Distribution runs through captive reagent networks for locked-in consumable contracts alongside third-party independent service organization channels in mature installed base markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on silicon photomultiplier cost-down curves displacing legacy photomultiplier tube architectures, coupled with reagent-centric revenue models capturing premium-tier immune phenotyping protocol adoption.
For Market Incumbents: To counter emerging platform challengers from China competing on domestic manufacturing scale, deepen backward integration into fluorochrome formulation capabilities and expand captive reagent network density in tier-one hospital clusters. Prioritize ISO 15189 accreditation support services as a channel control mechanism to reinforce consumable contract lock-in. For New Entrants and Emerging Players: CDSCO regulatory harmonization with ISO 15189 standards in India opens a window for accredited laboratory expansion in tier-two and tier-three cities. Target underpenetrated diagnostic center networks in Maharashtra and Karnataka with compact impedance-based analyzers designed for point-of-care decentralization. Pursue hospital information system interoperability certification as the primary go-to-market angle to reduce deployment timeline friction. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized hematology pure-plays possessing Japan-centric manufacturing scale and silicon photomultiplier-equipped research-grade instrument portfolios. Long-term viability over the next decade hinges on immune phenotyping protocol migration momentum and reagent contract renewal rates in academic medical center installed bases. Monitor NMPA domestic approval acceleration timelines as the critical inflection indicator for import substitution policy impact on multinational market access.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photomultiplier Platform Migration | Solid-state detector adoption cuts hardware costs while preserving fluorescence sensitivity for next-generation analyzers. |
| Immune Phenotyping Assay Expansion | Flow cytometry menu breadth captures protocol migration from research settings into routine leukemia diagnostics. |
| Captive Reagent Network Densification | Locked-in consumable contracts generate recurring revenue pools with structurally higher gross margins than instrument hardware. |
| ISO 15189 Accreditation Support Services | Traceable calibrator material sourcing and closed-system compatibility verification anchor quality management partnerships. |
| Point-of-Care Analyzer Miniaturization | Compact impedance-based systems penetrate ambulatory surgery centers previously served by core laboratory send-outs. |
Research Methodology
Bottom-up clinical laboratory and diagnostic center modeling reconciled against top-down hematology instrument manufacturing capacity tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at IVD manufacturers combined with secondary validation against FDA 510(k) filings, NMPA approval databases, hospital procurement records, and ECHA REACH substance registrations. Triangulation between demand-side test volume projections and supply-side production capacity assessments ensures cross-verified output integrity.
Input-output matrices mapping analyzer installed base growth, reagent consumption rates per instrument, and immune phenotyping protocol adoption curves drive volume and value outputs across the projection horizon. Segmentation dimensions span product type, application, end user, and technology modality alongside regional regulatory cluster differentiation. CAGRs derive from instrument replacement cycle analysis, reagent contract renewal probability modeling, and flow cytometry research-to-routine migration trajectory assessment. Forecast inputs incorporate silicon photomultiplier cost-down curves and EU IVDR compliance friction timelines.
Revisions become necessary when NMPA import substitution policy targets accelerate, REACH candidate list substance thresholds tighten, or hospital procurement committee unbundling behaviors intensify beyond modeled parameters. Forecasts reflect documented assumptions regarding regulatory pathway timelines, raw material supply concentration stability, and closed-system lock-in persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Laboratory Furniture Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Mobile Sterile Units Market