
 Global Thermoelectric Devices in Medical and Laboratory Offering Market | 2026-2036
Global Thermoelectric Devices in Medical and Laboratory Offering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermoelectric Devices in Medical and Laboratory Offering Market Foresight
Multi-source procurement of thermoelectric modules is recalibrating how medical device OEMs manage thermal subsystem risk. Ferrotec Holdings Corporation leverages vertical integration across ceramic substrates and semiconductor materials to secure supply continuity for laboratory coolers. Laird Thermal Systems anchors its position through dedicated cleanroom manufacturing lines serving diagnostic OEMs in North America and Europe. TEC Microsystems GmbH differentiates via precision sensor assemblies calibrated for PCR thermal cycling protocols.
Thermoelectric devices in medical and laboratory offerings are solid-state heat pumps fabricated from bismuth telluride or skutterudite alloys, operating on the Peltier effect to achieve temperature stability within ±0.1°C for sensitive biological samples and reagents. Their primary purpose is replacing mechanical refrigeration in point-of-care diagnostics and genomic sequencing platforms where vibration-free cooling and compact form factors prove essential. Bulk thermoelectric technology still dominates unit shipments due to mature manufacturing economics, though nanostructured materials are capturing R&D investment as efficiency benchmarks tighten. Coolers and temperature control modules concentrate margin pools because diagnostic laboratories prioritize uptime guarantees over upfront hardware cost.
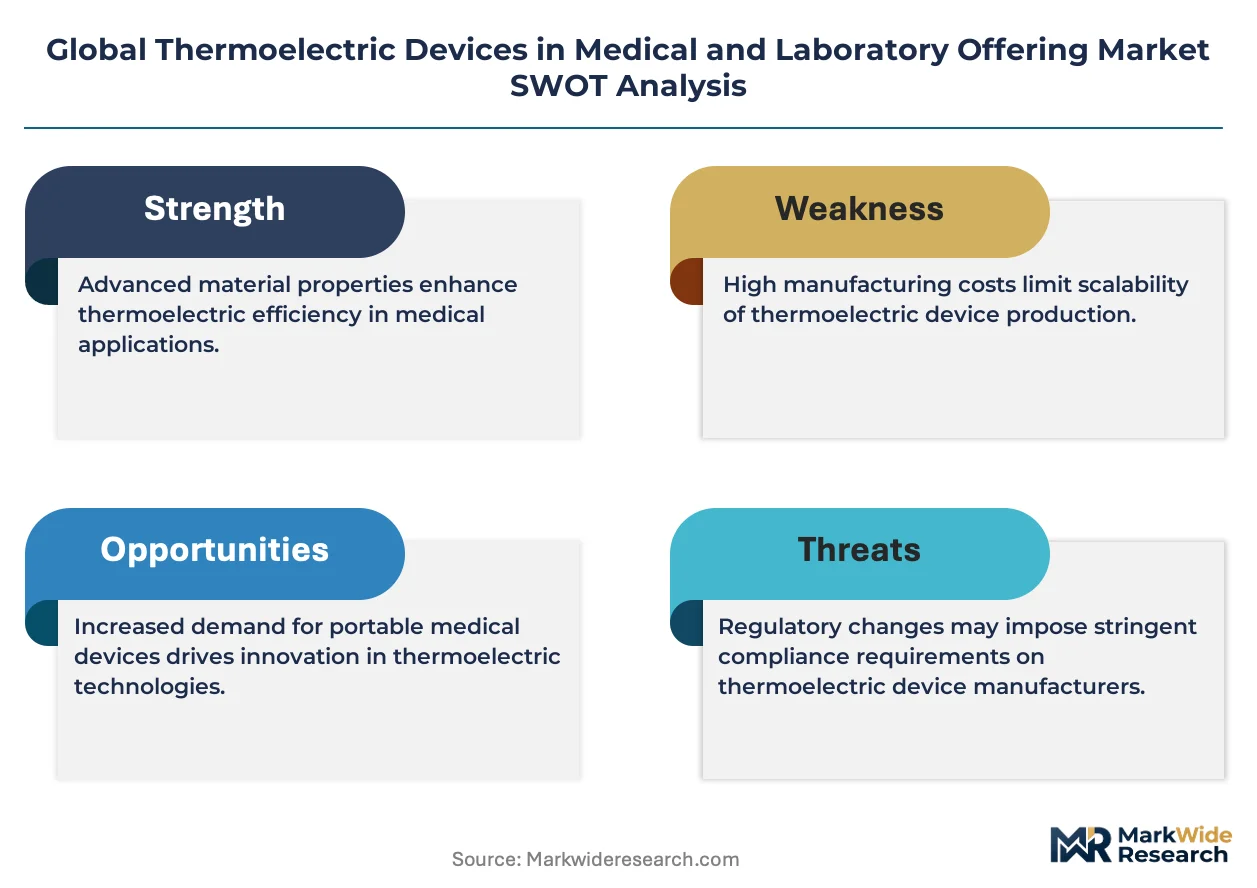
FDA 21 CFR Part 820 quality system regulations and the EU MDR's Annex I general safety requirements impose thermal performance documentation burdens on device manufacturers seeking US and European market access. China's NMPA medical device classification rules now explicitly cover thermoelectric components in Class II diagnostic equipment, tightening local registration timelines. ISO 13485 certification has become a baseline filter for supplier qualification across all three jurisdictions. Stakeholders must monitor how evolving efficiency standards for solid-state cooling reshape material selection roadmaps and qualification cycles.
Market Dynamics
Medical device OEMs are consolidating thermal subsystem suppliers to mitigate qualification-cycle risk as FDA 21 CFR Part 820 and EU MDR documentation burdens tighten concurrently with raw material concentration in East Asian semiconductor foundries.
Growth Catalysts
- PCR Thermal Cycling Protocols:Diagnostic laboratories demand ±0.1°C stability for nucleic acid amplification workflows. Thermoelectric modules replace mechanical compressors in point-of-care platforms where vibration corrupts optical readouts.
- China NMPA Class II Registration:Explicit coverage of thermoelectric components in diagnostic equipment classification rules accelerates domestic manufacturing investment and local supplier qualification.
- Bismuth Telluride Supply Chains:Mature bulk thermoelectric manufacturing economics in Germany and the United States enable cost-competitive module production for genomic sequencing instrument builders.
Market Restraints
- Tellurium Price Volatility:Refining capacity concentration in East Asia exposes module assemblers to input cost swings that compress gross margins on standardized cooler SKUs.
- Coefficient of Performance Ceiling:Bulk thermoelectric materials face theoretical efficiency limits below vapor-compression alternatives, restricting addressable market share in high-heat-flux applications.
- ISO 13485 Qualification Timelines:Medical-grade certification cycles extending 18-24 months delay new entrant market access and lock incumbent supplier relationships.
Strategic Opportunities
- Skutterudite Nanostructuring:R&D investment in quantum-confined thermoelectric materials promises figure-of-merit improvements that could unlock surgical laser cooling and implantable device applications.
- India Diagnostic Infrastructure:Central government health scheme expansion into tier-two cities creates demand for portable PCR platforms with solid-state thermal management.
- EU F-Gas Phase-Down:Regulatory compression of hydrofluorocarbon refrigerant availability positions thermoelectric cooling as compliance pathway for laboratory equipment refresh cycles.
Industry Challenges
- Multi-Jurisdiction Documentation:Simultaneous FDA 510(k), EU MDR technical file, and China NMPA registration requirements strain regulatory affairs bandwidth at mid-cap device manufacturers.
- Thermal Interface Material Compatibility:Silicone-based gap fillers degrade under cyclic Peltier operation, forcing redesign of heat-spreader architectures in miniaturized diagnostic cartridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermoelectric Devices in Medical and Laboratory Offering Market |
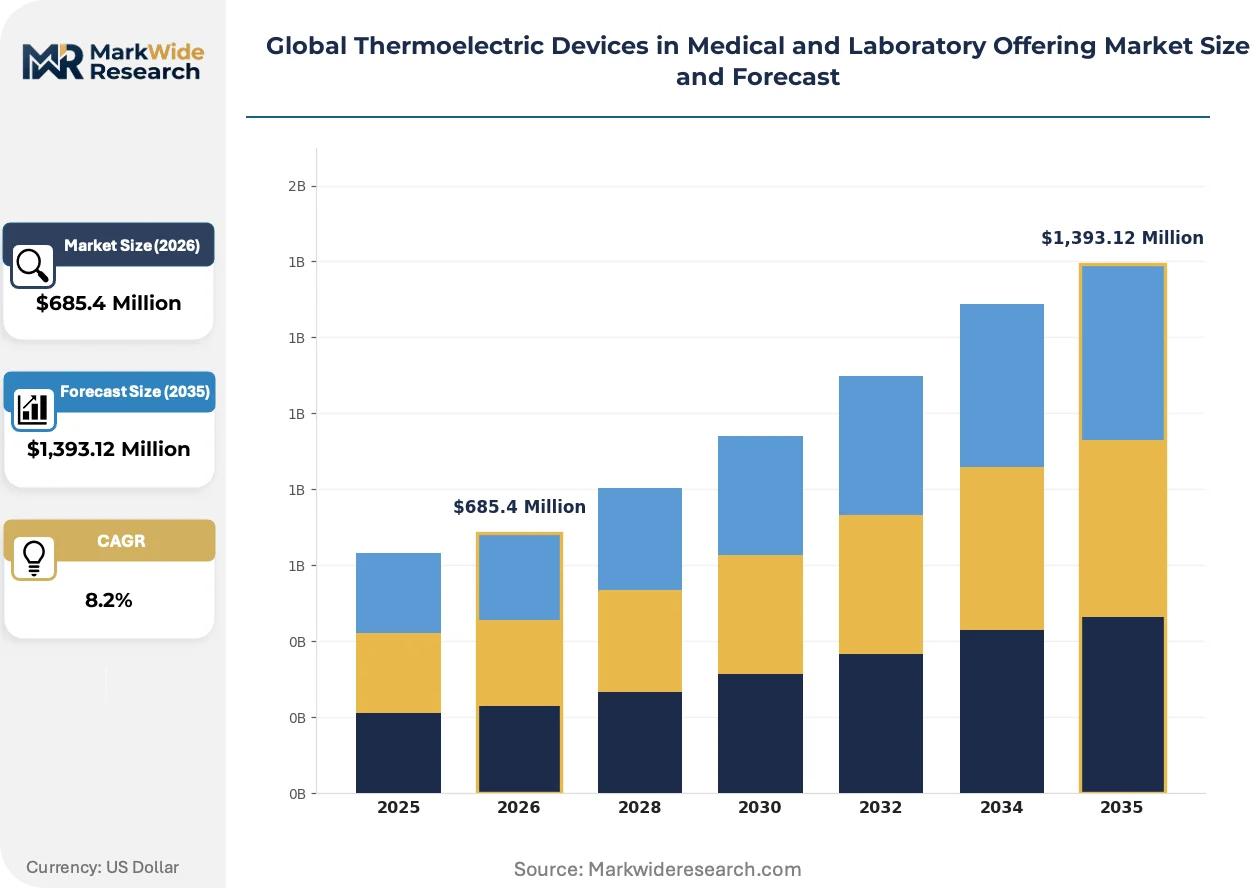
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolers, Heaters, Sensors, Modules, Assemblies Technology: Bulk Thermoelectric, Thin Film, Quantum Well, Nanostructured, Skutterudite Application: Biosensing, Temperature Control, Sample Preservation, Medical Imaging, Lab Research End User: Diagnostic Laboratories, Research Institutes, Pharma Companies, Medical Device Manufacturers, Clinical Centers |
| Companies Covered | Ferrotec Holdings Corporation, Laird Thermal Systems, KELK Ltd., II-VI Incorporated, TEC Microsystems GmbH, Crystal Ltd., Thermonamic Electronics (Jiangxi) Corp., Ltd., TE Technology, CUI Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermoelectric Devices in Medical and Laboratory Offering Market Shifts & Advancements
Precision temperature control architectures are converging with biosensor miniaturization and distributed diagnostic networks, compressing form-factor requirements while elevating calibration standards for solid-state cooling subsystems.
Nanostructured bismuth telluride superlattices are absorbing R&D investment from venture-backed thermal materials ventures and corporate innovation labs. Genomic sequencing platform builders in the United States and Germany are piloting these structures for PCR thermal cycling applications where ZT coefficient improvements translate directly to power consumption reduction. The technology is absorbing market share from legacy bulk modules in premium diagnostic instrument tiers where total cost of ownership calculations favor efficiency over upfront module cost.
EU MDR Annex I general safety requirements are forcing thermal performance documentation into device technical files for all Class IIa and above diagnostic equipment. Manufacturers must now validate temperature uniformity across sample wells under fault conditions, extending qualification timelines and elevating subsystem traceability standards. In vitro diagnostic OEMs serving European reference laboratories are responding by consolidating supplier bases to reduce audit surface area.
Diagnostic laboratories are unbundling cooler maintenance contracts from capital equipment purchases, creating standalone service revenue pools for thermal subsystem specialists. Third-party service providers in North America are capturing refurbishment and recalibration workflows previously captive to OEM service organizations. This shift is most visible in United States academic medical centers where extended equipment utilization cycles maximize grant-funded instrument depreciation.
Global Thermoelectric Devices in Medical and Laboratory Offering Market Segmentation
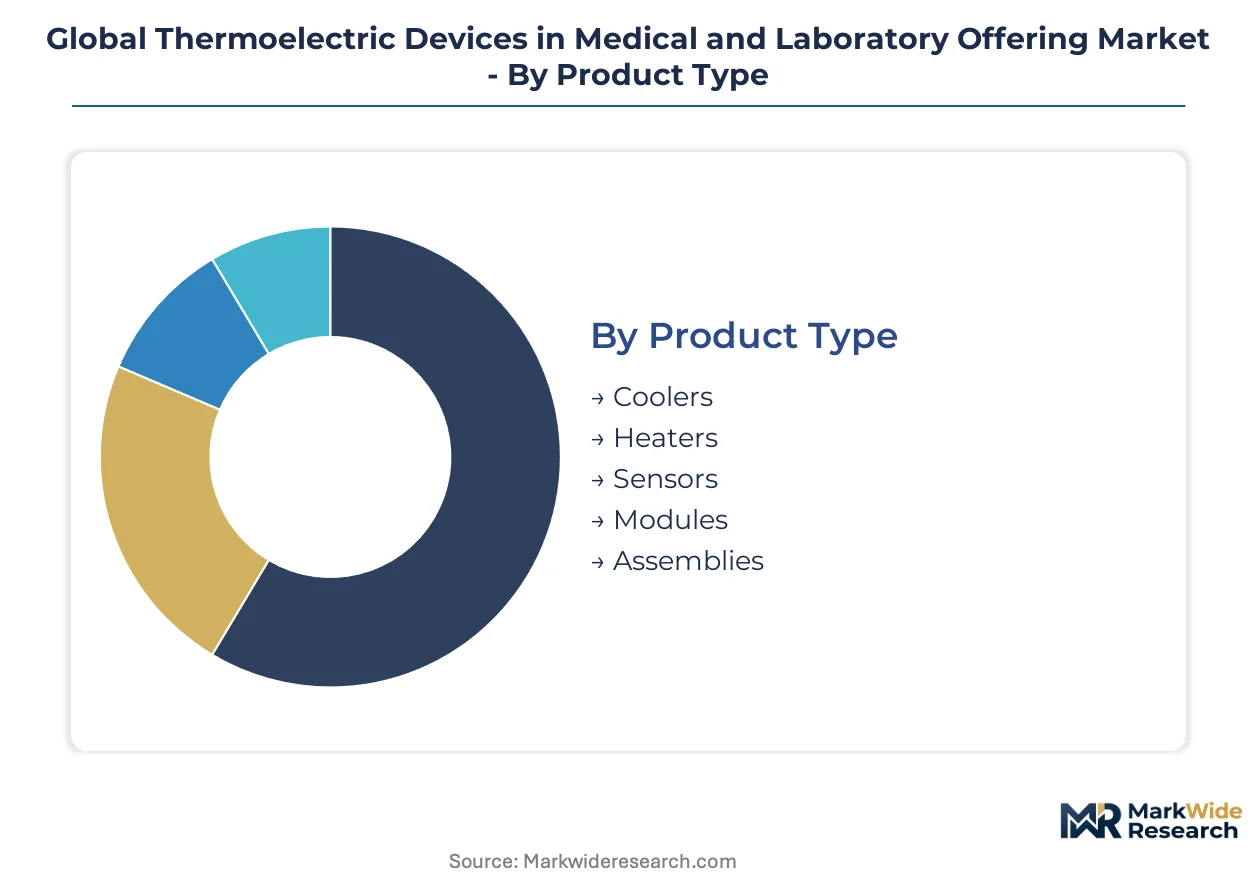
Segmentation in thermoelectric medical devices reveals how thermal performance specifications map to distinct procurement budgets and regulatory qualification burdens across diagnostic workflows. Technology-material choices and application-criticality determine pricing power and supplier consolidation patterns.
Product Type:
Thermal management hardware varies in integration depth and calibration complexity, with higher-assembly products commanding service revenue attachment and recurring replacement cycles.
- Coolers:Solid-state refrigeration units built around bismuth telluride junction arrays achieve vibration-free cooling for PCR and sequencing platforms. Demand concentrates in United States academic medical centers where extended equipment utilization cycles maximize grant-funded instrument depreciation.
- Temperature Control Modules:Closed-loop assemblies integrating Peltier elements with PID controllers and sensor feedback deliver ±0.1°C stability for biosensing cartridges. German and United States diagnostic OEMs prioritize these for point-of-care nucleic acid amplification workflows where optical readout integrity depends on thermal uniformity.
- Heaters:Reverse-polarity thermoelectric operation provides precise warming for enzymatic reaction preparation and thaw protocols.
- Sensors:Thermocouple-integrated assemblies monitor junction temperatures and fault conditions in miniaturized diagnostic cartridges.
- Modules:Unhoused Peltier elements serve as build-to-print components for instrument builders with in-house thermal engineering.
- Assemblies:Complete thermal subsystems including heat sinks, fans, and interface materials reduce OEM design cycle time.
Mature deployment sits with Coolers. Newer deployment is concentrated in Temperature Control Modules.
Technology:
Material science advancement creates a performance-cost frontier where bulk manufacturing economics compete with nanostructured efficiency gains for premium diagnostic instrument tiers.
- Bulk Thermoelectric:Conventional bismuth telluride ingots processed by zone melting or hot pressing dominate unit economics. United States and German manufacturing clusters supply cost-competitive modules for genomic sequencing instrument builders where mature qualification pathways reduce regulatory risk.
- Nanostructured:Bismuth telluride superlattices and quantum-dot composites absorb R&D investment from venture-backed thermal materials ventures. Pilot programs at United States sequencing platform builders target PCR thermal cycling applications where ZT coefficient improvements translate to power consumption reduction and footprint compression.
- Thin Film:Electrochemical deposition of thermoelectric materials onto flexible substrates enables conformal cooling for wearable diagnostic patches.
- Quantum Well:Superlattice structures with confined electron transport promise efficiency breakthroughs for implantable device applications.
- Skutterudite:Cobalt antimonide alloys with rare-earth filler atoms target elevated-temperature surgical laser cooling where bismuth telluride performance degrades.
Volume leadership belongs to Bulk Thermoelectric. Steepest expansion trajectory attaches to Nanostructured materials as efficiency benchmarks tighten.
Application:
Clinical workflow criticality determines thermal stability tolerances and the economic trade-off between solid-state reliability and vapor-compression efficiency.
- Temperature Control:Active thermal management for PCR thermal cyclers, incubators, and reagent storage maintains biological activity within narrow bands. Chinese diagnostic laboratories under NMPA Class II registration requirements drive adoption of qualified solid-state subsystems for domestic instrument production.
- Sample Preservation:Cold-chain integrity for biospecimens, vaccines, and temperature-sensitive reagents leverages thermoelectric cooling where mechanical compressor vibration risks sample integrity. EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants positions this application for laboratory equipment refresh cycles.
- Biosensing:Integrated thermal management for electrochemical and optical biosensors stabilizes signal transduction.
- Medical Imaging:Detector cooling for infrared and photon-counting modalities requires cryogenic or near-cryogenic performance.
- Lab Research:General-purpose thermal control for analytical instrumentation and experimental protocols.
Established demand concentrates in Temperature Control. Emerging demand clusters in Sample Preservation as refrigerant regulations tighten.
End User:
Procurement sophistication and qualification bandwidth vary sharply across institutional types, filtering supplier access and contract structures.
- Diagnostic Laboratories:High-throughput reference labs and hospital-based facilities prioritize uptime guarantees and maintenance contracts over upfront hardware cost. United States academic medical centers unbundle cooler refurbishment from capital purchases, creating standalone service revenue for thermal subsystem specialists.
- Medical Device Manufacturers:OEMs building PCR, sequencing, and point-of-care platforms consolidate supplier bases to reduce FDA 510(k) and EU MDR technical file audit surface area. Mid-cap manufacturers face strained regulatory affairs bandwidth from simultaneous multi-jurisdiction documentation requirements.
- Research Institutes:Grant-funded laboratories balance performance specifications against capital budget constraints.
- Pharma Companies:Quality-controlled manufacturing and stability testing operations require validated thermal systems.
- Clinical Centers:Point-of-care deployment settings prioritize compact footprint and minimal maintenance.
Revenue concentration rests with Diagnostic Laboratories. Fastest share gains appear at Medical Device Manufacturers consolidating thermal subsystem sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bismuth telluride refining capacity in East Asia and established semiconductor foundries in Germany and the United States anchor the geographic footprint for thermoelectric module supply. Diagnostic instrument manufacturing clusters concentrate where FDA, EU MDR, and NMPA regulatory expertise co-locates with precision engineering infrastructure.
United States
Genomic sequencing platform builders and point-of-care diagnostic OEMs drive demand for PCR thermal cycling modules with ±0.1°C stability. FDA 21 CFR Part 820 quality system regulations impose documentation burdens that extend supplier qualification timelines. Greater Boston and San Diego biotech corridors host concentrated R&D activity for nanostructured thermoelectric materials.
Germany
Reference laboratories and in vitro diagnostic manufacturers prioritize temperature control modules with ISO 13485 certification for EU MDR technical file compliance. The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants accelerates laboratory equipment refresh cycles toward solid-state cooling. Bavaria and Baden-Württemberg manufacturing clusters supply cost-competitive bulk thermoelectric modules to European instrument builders.
China
Domestic diagnostic instrument production scales under NMPA Class II registration requirements that explicitly cover thermoelectric components. Central government health scheme expansion into tier-two cities creates procurement volume for portable PCR platforms. Yangtze River Delta and Pearl River Delta manufacturing bases are consolidating local supplier qualification for thermoelectric subsystems.
Japan
Precision medical device manufacturers source vibration-free cooling for optical biosensing and photon-counting detector applications. METI industrial policy supports advanced materials R&D for next-generation thermoelectric efficiency. Kanto and Kansai industrial corridors maintain specialized cleanroom fabrication lines for medical-grade thermal management components.
India
Central government diagnostic infrastructure schemes in tier-two cities generate demand for compact, maintenance-minimal thermal subsystems. CDSCO medical device rules are tightening registration requirements for imported thermoelectric components. Maharashtra and Karnataka pharmaceutical manufacturing hubs are qualifying local thermal module suppliers for stability testing and quality-controlled production environments.
Global Thermoelectric Devices in Medical and Laboratory Offering Market Competitive Landscape
Supplier consolidation dominates the current landscape as medical device OEMs reduce audit surface area for FDA 510(k) and EU MDR submissions. The vendor base separates into three tiers: integrated materials-to-modules conglomerates with captive ceramic substrate production; specialized thermal subsystem houses with dedicated cleanroom lines; and precision sensor-integrated module specialists serving PCR protocols. M&A activity and backward integration into semiconductor materials represent the primary competitive vectors reshaping supplier relationships.
Among integrated conglomerates, Ferrotec Holdings Corporation exemplifies the materials-backward archetype through in-house production of ceramic substrates and semiconductor feedstocks. Laird Thermal Systems occupies a position within the cleanroom-specialist tier, serving North American and European diagnostic OEMs through controlled-environment manufacturing lines. TEC Microsystems GmbH represents the precision-integration archetype, anchoring the sensor-calibrated module segment for PCR thermal cycling applications. These three structures illustrate how supply continuity, regulatory compliance bandwidth, and protocol-specific calibration each command premium positioning in procurement decisions.
| Leading Market Players |
|---|
| Ferrotec Holdings Corporation |
| Laird Thermal Systems |
| KELK Ltd. |
| II-VI Incorporated |
| TEC Microsystems GmbH |
| Crystal Ltd. |
| Thermonamic Electronics (Jiangxi) Corp., Ltd. |
| TE Technology |
| CUI Devices |
| Others |
Supply & Pricing Matrix
Diagnostic laboratory OEMs in the United States and Germany dominate procurement volume, anchoring contract-based long-term offtake agreements that bundle temperature control modules with multi-year uptime guarantees and ISO 13485 recertification services. This buyer concentration rewards suppliers who unbundle cooler maintenance from capital equipment purchases, creating service revenue attachment that offsets margin compression on standardized hardware SKUs.
Pricing Analysis
Warranty and service-bundling separates premium-tier suppliers from economy alternatives, with German and United States diagnostic OEMs paying 20-40% premiums for modules carrying extended calibration guarantees and rapid field-replacement commitments. Pricing stratifies across premium, standard, and economy tiers based on certification grade (ISO 13485 vs. industrial-grade) and volume scale, with academic medical centers leveraging grant-funded depreciation cycles to prioritize total cost of ownership over upfront unit cost. Cost compression in standardized cooler SKUs is intensifying because tellurium price volatility from East Asian refining concentration squeezes module assembler margins. Medical device manufacturers with strained regulatory affairs bandwidth prove least price-sensitive, while research institutes operating on fixed capital grants exhibit highest sensitivity to per-unit hardware cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China operate hub-and-spoke patterns that position finished modules within 72-hour delivery windows of major diagnostic instrument manufacturing clusters. Bismuth telluride ingot supply draws from established zone-melting facilities in Germany and the United States, while ceramic substrate production concentrates in East Asian semiconductor foundries. Single-source vulnerability in tellurium refining capacity exposes module assemblers to input cost swings that propagate through contract pricing renegotiation cycles. Distribution runs through authorized distributor networks serving FDA-registered and EU MDR-compliant OEMs, with direct fulfillment relationships reserved for high-volume sequencing platform builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoelectric medical device market sits in a technology-transition phase where nanostructured bismuth telluride superlattices displace legacy bulk modules in premium PCR thermal cycling applications. This substitution dynamic compresses qualification timelines for incumbent suppliers while opening white-space for materials-science entrants with captive nanofabrication capabilities.
For Market Incumbents: Hedge against skutterudite efficiency breakthroughs by securing backward integration into ceramic substrate production and expanding cleanroom capacity in Bavaria and Baden-Württemberg manufacturing clusters. Lock in multi-year bismuth telluride supply offtake with German and United States refining partners before nanostructured materials capture additional share in genomic sequencing instrument tiers. Prioritize ISO 13485 certification bandwidth expansion to reduce audit surface area for FDA 510(k) and EU MDR technical file consolidation.
For New Entrants and Emerging Players: Enter via India's tier-two city diagnostic infrastructure expansion, where central government health scheme procurement creates demand for portable PCR platforms with solid-state thermal management. Target CDSCO-registered local manufacturing partnerships in Maharashtra and Karnataka pharmaceutical hubs to bypass import registration timelines for thermoelectric subsystems. Position around maintenance-contract unbundling, capturing refurbishment and recalibration workflows previously captive to OEM service organizations in United States academic medical centers.
For Investors and Strategic Acquirers: The window for entry favors precision sensor-integrated module specialists with PCR protocol calibration expertise and established NMPA Class II registration pathways in China. Long-term viability hinges on skutterudite nanostructuring R&D maturation toward surgical laser cooling applications beyond diagnostic laboratory addressable market. Watch EU F-Gas Regulation enforcement intensity as inflection indicator for laboratory equipment refresh cycle acceleration toward solid-state cooling compliance pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Ferrotec Holdings Corporation's captive supply of alumina substrates insulates against East Asian foundry concentration risk. |
| NMPA Class II Registration Investment | Domestic qualification timelines in China accelerate local manufacturing cluster formation in Yangtze River Delta. |
| Skutterudite Nanostructuring R&D | Quantum-confined materials development targets surgical laser cooling beyond PCR thermal cycling applications. |
| Maintenance Contract Unbundling | Third-party service providers in North America capture recalibration revenue from extended equipment utilization cycles. |
| EU MDR Technical File Consolidation | Supplier base reduction reduces audit surface area for in vitro diagnostic OEMs serving European reference laboratories. |
Research Methodology
Document review covered FDA 510(k) submissions, EU MDR technical files, NMPA Class II registration databases, and ISO 13485 certification records, complemented by interviews with thermal subsystem procurement managers at genomic sequencing platform builders, regulatory affairs directors at point-of-care diagnostic OEMs, and biomedical engineers at United States academic medical centers. Secondary validation drew from SEC filings of thermoelectric materials suppliers, customs trade data for bismuth telluride ingot flows, and hospital procurement database extracts. Bottom-up module shipment estimates triangulated against top-down diagnostic instrument production forecasts.
Cross-referencing historical CAGR patterns with expert panel input on nanostructured materials adoption timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type integration depth, technology-material performance tier, application criticality level, and end-user procurement sophistication. CAGRs derived from slope-intercept calibration against qualified installation base growth and replacement cycle compression. Industry-specific inputs incorporated PCR thermal cycling protocol standardization trends and EU F-Gas Regulation phase-down enforcement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tellurium supply disruption scenarios or accelerated skutterudite efficiency breakthroughs. Outputs reflect assumptions regarding NMPA registration timeline stability and ISO 13485 audit backlog resolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Organoids Kits Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
United States Stair Lift Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Memory Implants Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Europe Otoscope Market