
 Microplate Instrumentation and Supplies Market | 2026-2036
Microplate Instrumentation and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Microplate Instrumentation and Supplies Market Foresight
Modular bundling of readers with integrated washers and stackers is expanding as laboratories seek to reduce capital deployment complexity and vendor management overhead. Thermo Fisher Scientific leverages its consumables-recurring-revenue model to anchor long-term contracts in core facilities. Bio-Rad Laboratories competes through specialized detection modules that differentiate its portfolio in fluorescence and luminescence applications. Tecan Group sustains geographic dominance in European automation workflows through localized service networks and application support.
Microplate instrumentation and supplies encompass analytical devices and consumables designed for parallel processing of samples in standardized 96-, 384-, or 1536-well formats, with optical detection thresholds typically spanning 0.1 to 4 optical density units for absorbance-based assays. These systems enable quantitative biochemical and cell-based measurements at throughputs exceeding 100,000 wells daily in pharmaceutical screening operations. Microplate readers dominate installed base value due to their central role in detection workflows, while microplate sealers represent the fastest-growing product category as labs prioritize contamination control and sample integrity in automated environments. Drug discovery applications command the largest application share, though clinical diagnostics is gaining structural importance as point-of-care and decentralized testing models expand validated assay menus.
FDA 21 CFR Part 11 compliance requirements shape instrument software architecture and audit trail capabilities for US-deployed systems, while ISO 13485 quality management standards govern manufacturing processes for diagnostic-grade microplates and readers. The EPA's Good Automated Laboratory Practices influence environmental testing protocols that depend on microplate-based colorimetric and fluorometric detection methods. Stakeholders must monitor evolving GxP harmonization between FDA and EMA guidelines as multi-site trials demand interoperable data formats across instrument platforms.
Market Dynamics
Pharmaceutical high-throughput screening workflows are compressing refresh cycles for microplate instrumentation as contract research organizations scale automated compound libraries beyond 100,000 wells daily.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates are forcing instrument software upgrades across US biopharma facilities, accelerating replacement demand for audit-trail-compliant readers.
- Cell-based assay proliferation:Biologics pipelines in Boston and San Diego clusters are driving 384-well and 1536-well format adoption for phenotypic screening applications.
- Modular system architecture:Integrated washer-reader-stacker configurations are reducing vendor management overhead in core screening facilities.
Market Restraints
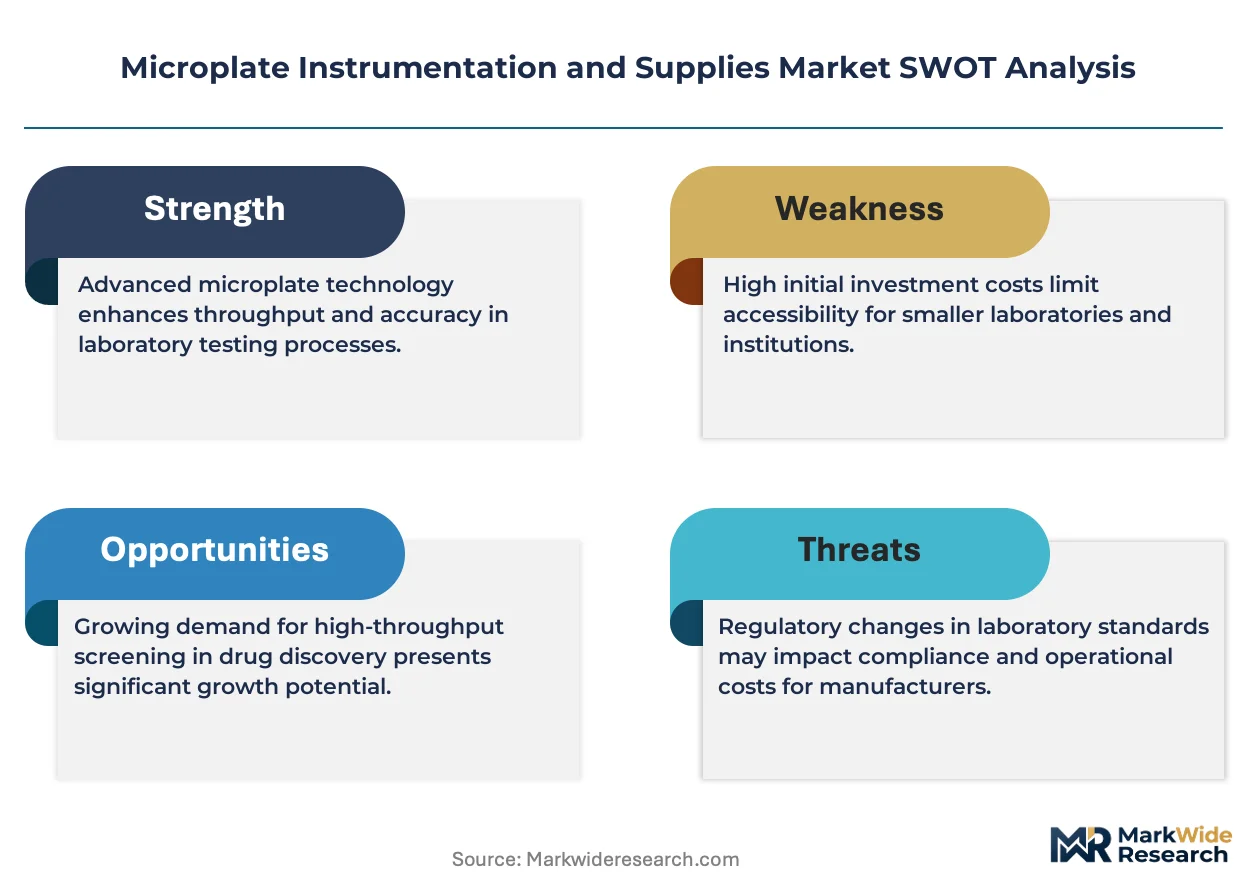
- Consumables cost concentration:Proprietary microplate formats and detection reagents lock laboratories into recurring spend exceeding instrument depreciation by 3-5x annually.
- Optical detection limits:Absorbance-based assays face sensitivity ceilings at 0.1 optical density units, constraining low-abundance biomarker applications.
- European service network density:Localized technical support gaps outside Germany and Switzerland extend instrument downtime for automated workflows.
Strategic Opportunities
- Point-of-care diagnostics expansion:Decentralized testing models in clinical settings are opening validated assay menu development for compact readers.
- ISO 13485 diagnostic-grade certification:Quality management standards for microplate manufacturing are creating premium positioning for GxP-compliant consumables suppliers.
- AI-driven hit identification:Machine learning integration with kinetic imaging readers is automating compound prioritization in early-stage drug discovery.
Industry Challenges
- Multi-platform data interoperability:GxP harmonization gaps between FDA and EMA guidelines complicate multi-site trial instrument validation protocols.
- Specialized application engineering talent:Fluorescence and luminescence module optimization requires scarce optical engineering expertise concentrated in Basel and Cambridge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microplate Instrumentation and Supplies Market |
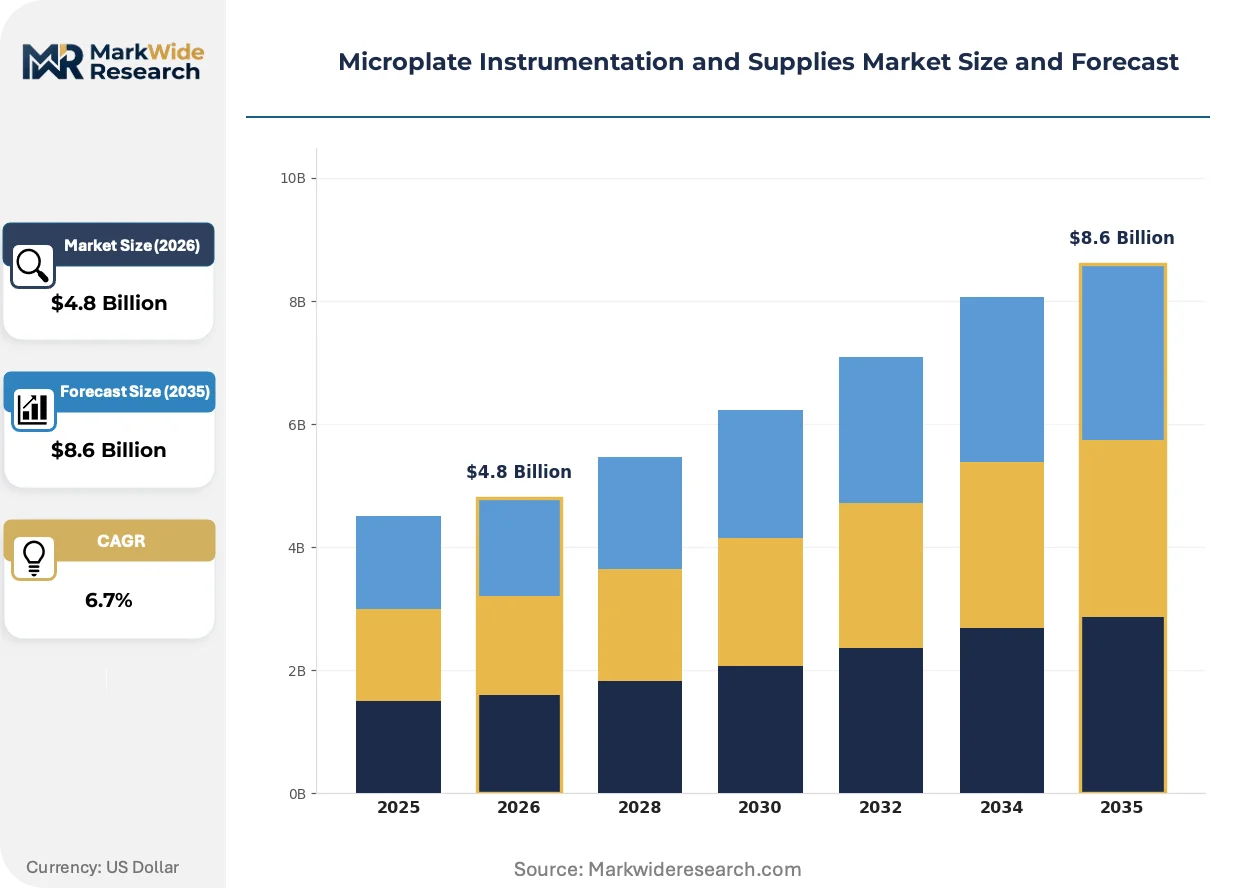
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microplate Readers, Microplate Washers, Microplate Stackers, Microplate Sealers Application: Drug Discovery, Clinical Diagnostics, Life Science Research, Environmental Testing End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations Material: Polypropylene, Polystyrene, Glass, Coated Plates |
| Companies Covered | Beckman Coulter, Thermo Fisher Scientific, Bio-Rad Laboratories, PerkinElmer, Tecan Group, BioTek Instruments, BMG LABTECH, Molecular Devices, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microplate Instrumentation and Supplies Market Shifts & Advancements
Detection sensitivity thresholds, regulatory data integrity mandates, and procurement consolidation are simultaneously reshaping instrument specifications and vendor relationship structures across pharmaceutical and clinical laboratory end-uses.
High-content imaging readers equipped with kinetic fluorescence tracking are automating compound mechanism-of-action studies that previously required discrete plate washing and reagent addition steps. Large-molecule biopharma developers in Massachusetts and California are deploying these systems at pilot-scale facilities ahead of commercial manufacturing commitments. The technology is automating cell health assessment workflows that formerly demanded manual microscopy intervention, compressing assay timelines from days to hours.
EMA's evolving GxP guideline harmonization with FDA audit trail requirements is mandating timestamped, tamper-evident data architectures for European-deployed screening instruments. Manufacturers must now engineer dual-compliant software stacks that satisfy both jurisdictions without hardware reconfiguration. Diagnostic-grade microplate suppliers pursuing CE marking under MDR face expanded technical documentation burdens that extend certification timelines by 12-18 months.
Core facility directors are consolidating vendor relationships through multi-year consumables-anchored contracts that bundle instrument placement with minimum annual reagent commitments. This procurement model displaces capital-purchase decisions with operational expenditure structures favoring integrated system providers. The shift is most visible in National Institutes of Health-funded academic consortia, where shared resource grants now prioritize total cost-of-ownership metrics over upfront equipment pricing.
Microplate Instrumentation and Supplies Market Segmentation
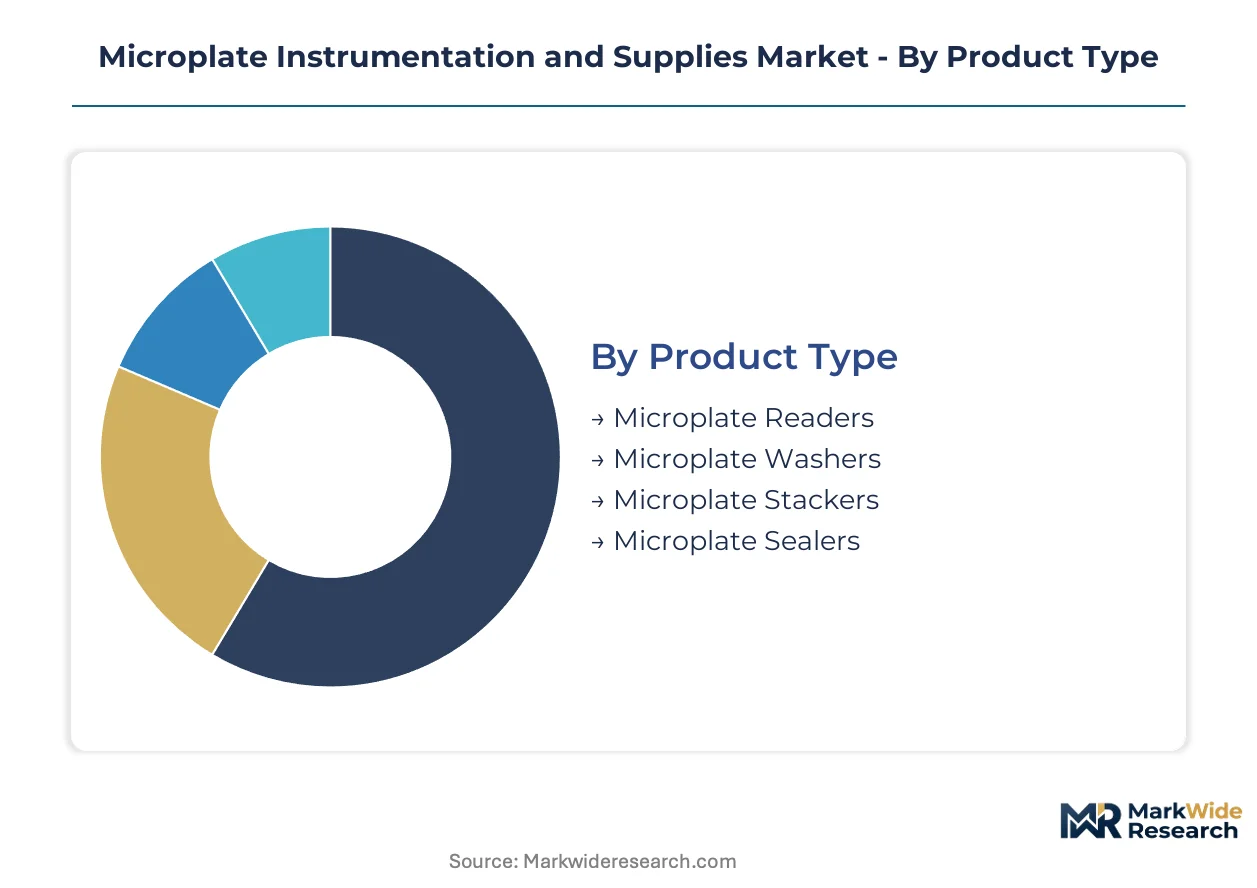
Segmentation in microplate instrumentation reveals how procurement patterns bifurcate between high-throughput pharmaceutical screening and lower-volume research environments. Vendor bundling strategies and consumables lock-in mechanics vary sharply across these divides, reshaping competitive positioning for integrated system providers.
Product Type:
Supply concentration in detection modules favors vendors with captive optical engineering capabilities, while peripheral automation equipment fragments across specialized manufacturers.
- Microplate Readers:Optical detection systems spanning absorbance, fluorescence, luminescence, and multimodal configurations form the analytical core of screening workflows. Pharmaceutical facilities in Boston and San Diego clusters prioritize 384-well and 1536-well compatibility for biologics phenotypic screening, with kinetic imaging capabilities commanding placement premiums in pilot-scale facilities.
- Microplate Washers:Automated plate washing systems eliminate manual intervention in cell-based and biochemical assays, with integrated washer-reader configurations reducing vendor management overhead in core screening facilities. Demand concentrates among contract research organizations scaling compound libraries beyond 100,000 wells daily.
- Microplate Stackers:Plate handling automation enables unattended overnight screening runs, with modular stacker-reader integration supporting walk-away operation in high-throughput environments.
- Microplate Sealers:Heat-sealing and adhesive systems preserve sample integrity in automated storage and retrieval workflows, with contamination control priorities driving specification upgrades in clinical diagnostic laboratories.
Microplate readers absorb the bulk of installed capacity; microplate sealers are expanding most quickly as contamination control protocols tighten across automated environments.
Application:
Cost tier differentiation separates capital-intensive pharmaceutical screening from operational-expenditure clinical diagnostic deployments, with reimbursement dynamics constraining instrument specifications in the latter.
- Drug Discovery:High-throughput screening workflows in pharmaceutical and biotechnology settings demand multimodal detection capabilities, with 384-well and 1536-well format adoption accelerating for biologics mechanism-of-action studies. Massachusetts and California facilities deploy kinetic imaging readers ahead of commercial manufacturing commitments.
- Clinical Diagnostics:Point-of-care and decentralized testing models are opening validated assay menu development for compact readers, with ISO 13485 quality standards and FDA 21 CFR Part 11 compliance requirements governing instrument software architecture.
- Life Science Research:Academic core facilities prioritize total cost-of-ownership metrics in National Institutes of Health-funded consortia, favoring consumables-anchored contracts over capital-purchase structures.
- Environmental Testing:EPA Good Automated Laboratory Practices influence colorimetric and fluorometric detection protocols for water quality and contaminant monitoring applications.
Drug discovery absorbs the bulk of installed capacity; clinical diagnostics is climbing the fastest as point-of-care models expand validated assay menus.
End User:
Customer type determines procurement leverage, with pharmaceutical consolidators extracting multi-year consumables commitments against instrument placement against fragmented academic purchasing.
- Pharmaceutical Companies:Internal screening operations command instrument specification authority, with refresh cycles compressing as compound library scales exceed 100,000 wells daily and audit-trail-compliant software becomes mandatory under FDA 21 CFR Part 11.
- Biotechnology Firms:Phenotypic screening pipelines in Boston and San Diego clusters drive 384-well and 1536-well format adoption, with modular system configurations reducing capital deployment complexity.
- Academic Institutions:Shared resource grants in NIH-funded consortia prioritize operational expenditure structures favoring integrated system providers over upfront equipment pricing.
- Contract Research Organizations:Scaled screening services demand unattended automation capabilities, with localized service network density influencing vendor selection for European workflows.
Pharmaceutical companies absorb the bulk of installed capacity; contract research organizations are gaining share fastest as outsourcing concentrates high-throughput screening operations.
Material:
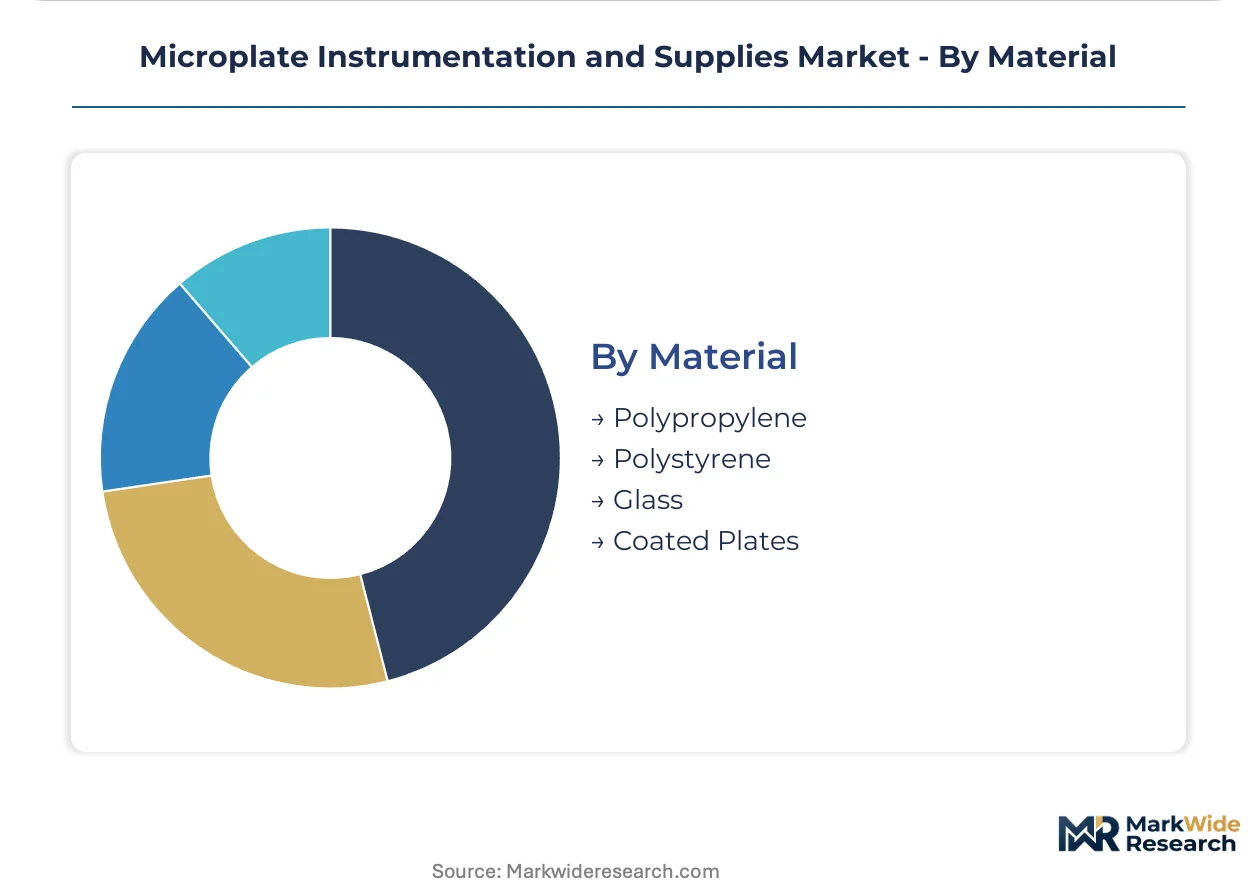
Volume economics in consumables manufacturing favor polypropylene and polystyrene molding at scale, while specialty coatings and glass substrates serve premium diagnostic-grade applications with extended certification timelines.
- Polypropylene:Thermal stability and chemical resistance make this the default for compound storage and cell culture applications, with high-throughput pharmaceutical screening driving standardized 96-well and 384-well format demand.
- Polystyrene:Optical clarity in the visible spectrum supports absorbance and fluorescence detection, with untreated and tissue-culture-treated variants serving distinct cell adhesion requirements in life science research settings.
- Glass:Chemical inertness and thermal tolerance suit high-temperature applications and solvent-resistant compound storage, with premium positioning in specialized pharmaceutical workflows.
- Coated Plates:Surface treatments including collagen, poly-D-lysine, and proprietary formulations enable specific cell attachment profiles, with ISO 13485 diagnostic-grade certification creating premium positioning for GxP-compliant suppliers.
Polypropylene absorbs the bulk of installed capacity; coated plates are expanding most quickly as cell-based assay proliferation demands specialized surface chemistries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision manufacturing hubs across Germany, Switzerland, and Japan, while consumption clusters in biopharma R&D corridors in the United States, United Kingdom, and China. Regulatory divergence between FDA 21 CFR Part 11 and EMA GxP guidelines forces dual-compliant software architectures.
United States
FDA 21 CFR Part 11 mandates are accelerating replacement cycles for audit-trail-compliant readers across Massachusetts and California biotech clusters. The National Institutes of Health prioritizes total cost-of-ownership metrics in shared resource grant allocations. Boston and San Diego sustain instrument refresh demand through phenotypic screening pipeline expansion.
Germany
EMA GxP guideline harmonization pressures are extending certification timelines for diagnostic-grade consumables suppliers. ISO 13485 quality management standards govern manufacturing processes for CE-marked microplates under MDR. Basel-proximate optical engineering talent concentrates in Baden-Württemberg precision instrument fabrication.
Switzerland
Swissmedic diagnostic-grade certification requirements create premium positioning for GxP-compliant consumables manufacturers. Localized service network density in Basel and Zurich supports European automation workflow dominance. Roche-proximate suppliers leverage captive demand from large-molecule biopharma developers.
China
NMPA regulatory pathways for diagnostic instruments are expanding validated assay menu development for domestic manufacturers. Yangtze River Delta biotech parks in Shanghai and Suzhou are scaling compound library screening beyond 100,000 wells daily. Government funding for precision medicine initiatives is compressing capital deployment timelines for core facilities.
United Kingdom
MHRA post-Brexit regulatory divergence from EMA guidelines complicates multi-site trial instrument validation protocols for London and Cambridge research consortia. UK Research and Innovation grants prioritize operational expenditure structures favoring integrated system providers. Oxford and Cambridge biotech clusters drive 384-well format adoption for cell-based assay proliferation.
Microplate Instrumentation and Supplies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across detection module and automation equipment segments. The vendor base organizes around three strategic archetypes: integrated life science platforms with consumables-recurring-revenue models, precision optical engineering houses with specialized fluorescence capabilities, and modular automation specialists with localized service networks. Consolidation pressure favors bundled washer-reader-stacker configurations that reduce vendor management overhead in core screening facilities.
Among diversified life science platforms, Thermo Fisher Scientific and PerkinElmer exemplify the consumables-anchored contract model that displaces capital-purchase decisions with operational expenditure structures. Bio-Rad Laboratories occupies a position within the specialized detection tier, while Tecan Group represents European automation workflow dominance through application support density. These three anchors illustrate how competitive positioning bifurcates between scale-driven platform consolidation and precision engineering specialization.
| Leading Market Players |
|---|
| Beckman Coulter |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| PerkinElmer |
| Tecan Group |
| BioTek Instruments |
| BMG LABTECH |
| Molecular Devices |
| Eppendorf |
| Others |
Supply & Pricing Matrix
Pharmaceutical consolidators and NIH-funded academic core facilities command procurement leverage through multi-year consumables-anchored contracts, displacing capital-purchase decisions with operational expenditure structures that favor integrated system providers with captive recurring revenue models.
Pricing Analysis
Price erosion across standard detection modules traces to vendor consolidation pressure as core facilities reduce supplier counts through bundled washer-reader-stacker configurations. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-compliant audit-trail systems from basic research-grade readers and entry-level absorbance-only units. Academic institutions exhibit highest price sensitivity due to grant-dependent funding cycles, while pharmaceutical companies absorb premium positioning for kinetic imaging capabilities. Cost compression in mid-tier multimodal systems accelerates because contract research organizations scale compound screening beyond 100,000 wells daily.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and Massachusetts operate hub-and-spoke patterns for precision optical components and molded consumables. Manufacturing concentrates in Baden-Württemberg precision instrument fabrication, Basel-proximate optical engineering clusters, and Japanese mechatronics hubs for automated stacker mechanisms. Supply chains draw from specialized glass substrates for high-temperature applications, injection-molded polypropylene resins for compound storage plates, and proprietary surface coating chemistries for cell-based assays. Single-source vulnerability concentrates in fluorescence filter sets and high-numerical-aperture objective lenses. Distribution runs through authorized service networks with localized application support density determining vendor selection in European workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical engineering talent scarcity in fluorescence and luminescence module optimization props pricing for specialized detection capabilities, constraining supply expansion despite pharmaceutical screening demand acceleration.
For Market Incumbents: Anticipate margin compression in standard absorbance readers as Chinese manufacturers penetrate mid-tier segments through NMPA-certified domestic production. Defensive consolidation moves should prioritize backward integration into proprietary microplate formats that lock laboratories into recurring consumables spend exceeding instrument depreciation, and deepen captive service network density in European automation workflows outside Germany and Switzerland where technical support gaps extend instrument downtime. For New Entrants and Emerging Players: FDA 21 CFR Part 11 in the United States opens a window for software-native audit-trail architectures that displace legacy instrument upgrades in Massachusetts and California biotech clusters. White-space targets include compact point-of-care readers for decentralized clinical diagnostics with ISO 13485 certification, and AI-integrated kinetic imaging systems for phenotypic screening in Boston and San Diego. A go-to-market angle through NIH shared resource grant channels prioritizing total cost-of-ownership metrics bypasses capital-purchase committee resistance. For Investors and Strategic Acquirers: The window for entry favors specialized optical engineering houses with fluorescence and luminescence module capabilities concentrated in Basel and Cambridge. Long-term viability hinges on consumables-recurring-revenue attachment rates rather than instrument placement volume. Acquisition target archetypes include precision filter manufacturers and surface chemistry coating specialists for cell-based assay plates. The signal to watch is EMA-FDA GxP harmonization progress, which would compress dual-compliant software development costs and accelerate European market penetration for unified platform architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables-Anchored Contract Expansion | Locks laboratories into recurring revenue streams exceeding instrument depreciation through proprietary microplate formats. |
| Dual-Compliant Software Architecture Development | Satisfies simultaneous FDA 21 CFR Part 11 and EMA GxP requirements without hardware reconfiguration for multi-site trials. |
| Localized Service Network Density Investment | Reduces instrument downtime in European automation workflows where technical support gaps outside Germany extend repair timelines. |
| Kinetic Imaging Reader Platform Launch | Automates compound mechanism-of-action studies for Massachusetts and California biologics developers ahead of manufacturing commitments. |
| ISO 13485 Diagnostic-Grade Certification Pathway | Creates premium positioning for GxP-compliant consumables suppliers pursuing CE marking under MDR extended timelines. |
Research Methodology
SEC filings, FDA 510(k) clearances, and EMA regulatory submission databases formed the secondary backbone for vendor positioning and compliance pathway mapping. Primary interviews with core facility directors at NIH-funded consortia, pharmaceutical screening operations heads in Boston and San Diego, and optical engineering specialists in Basel and Cambridge validated instrument specification trends and procurement pattern shifts. Bottom-up triangulation across product-type demand curves and top-down cross-check against pharmaceutical R&D expenditure flows anchored volume estimates.
Bottom-up modeling segmented demand across detection modality, well format compatibility, and end-user procurement structure, while top-down validation referenced biopharma capital equipment spending patterns across the projection horizon. Analytical frameworks incorporated assay menu expansion rates in clinical diagnostics, compound library scaling trajectories in contract research organizations, and refresh cycle compression from audit-trail compliance mandates. CAGRs derived from instrument placement velocity against consumables attachment rate assumptions through the modeling period.
Caveats apply where FDA-EMA GxP harmonization delays or optical component supply disruptions could materially shift the outlook for dual-compliant system deployment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Global Cell Analysis Instruments Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Pipettes and Accessories Market