
 Labeling Equipment Market | 2026-2036
Labeling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Labeling Equipment Market Analysis
The EU Green Deal is broadening compliance requirements for packaging recyclability across European labeling operations. Krones AG leverages its integrated bottling and labeling platform to sustain engineering leadership in high-speed beverage applications. Herma GmbH anchors its position through precision self-adhesive dispensing systems that dominate pharmaceutical serialization workflows. ProMach competes across North American food packaging lines with modular labeling architectures that accommodate rapid format changeovers.
Labeling equipment comprises automated machinery that applies, prints, or encodes labels onto products, containers, or packaging substrates at speeds ranging from 100 to 60,000 units per hour depending on configuration. These systems integrate print engines, applicator heads, vision verification modules, and conveyor synchronization to ensure traceability, brand presentation, and regulatory compliance across manufacturing environments. Self-adhesive label systems occupy the largest installed base due to versatility across container geometries, though RFID label equipment represents the fastest-growing technology segment as inventory authentication requirements intensify. Flexographic printing technology maintains cost advantages for long-run commodity labels, while digital printing equipment captures margin pools in personalized and variable-data applications where job change frequency disqualifies analog setups.
The European Medicines Agency enforces serialization standards that mandate unique identifier verification on pharmaceutical packaging, directly shaping equipment specifications for vision systems and data-matrix print quality. The EPA regulates volatile organic compound emissions from solvent-based flexographic inks, pushing converters toward water-based formulations or digital alternatives that require compatible drying and curing subsystems on labeling lines. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions will redefine material compatibility requirements and equipment qualification protocols for circular packaging targets.
Market Dynamics
Digital printing technology is modularizing labeling equipment architectures, compressing changeover times from hours to minutes while fragmenting demand across shorter production runs and personalized packaging workflows.
Growth Catalysts
- Pharmaceutical serialization mandates:The European Medicines Agency enforces track-and-trace requirements that mandate vision-verified data-matrix printing on drug packaging, forcing equipment upgrades across EU pharmaceutical manufacturing lines.
- F-Gas Regulation compliance:Germany's machinery engineering clusters are driving equipment replacements as refrigerant-based drying systems face phase-out timelines, accelerating demand for compatible labeling subsystems in beverage packaging.
- RFID inventory authentication:Retail and logistics operators are deploying radio-frequency identification label applicators to combat counterfeiting and enable real-time supply chain visibility, expanding the addressable equipment base beyond conventional adhesive systems.
Market Restraints
- Stainless steel and servo motor cost volatility:Precision labeling equipment relies on corrosion-resistant alloys and motion-control components whose input prices fluctuate with commodity markets, squeezing margins for mid-tier equipment manufacturers.
- Specialized component supplier concentration:High-resolution print engine and vision system modules concentrate among a handful of German and Japanese suppliers, creating single-source vulnerability for equipment integrators.
- Water-based ink drying limitations:EPA volatile organic compound regulations are pushing converters away from solvent flexography, but water-based alternatives require longer thermal drying tunnels that constrain line speeds and floor space efficiency.
Strategic Opportunities
- India pharmaceutical contract manufacturing:CDSCO serialization requirements are tightening, creating first-mover advantage for equipment vendors that qualify systems for Indian packaging lines ahead of enforcement deadlines.
- EU Green Deal packaging recyclability:Extended producer responsibility frameworks are redefining material compatibility specifications, opening retrofit markets for equipment capable of handling mono-material labels and wash-off adhesives.
- Digital-analog hybrid architectures:Convergence of flexographic cost efficiency with digital variable-data capability is enabling equipment configurations that serve both long-run commodity and short-run personalized applications from a single platform.
Industry Challenges
- Multi-protocol integration complexity:Equipment must synchronize with enterprise resource planning, manufacturing execution systems, and anti-counterfeiting databases simultaneously, stretching systems engineering capabilities at mid-sized equipment builders.
- Vision system calibration talent scarcity:Pharmaceutical serialization compliance requires technicians capable of validating optical character recognition and data-matrix grading to ISO standards, creating hiring bottlenecks for equipment operators and service organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Labeling Equipment Market |
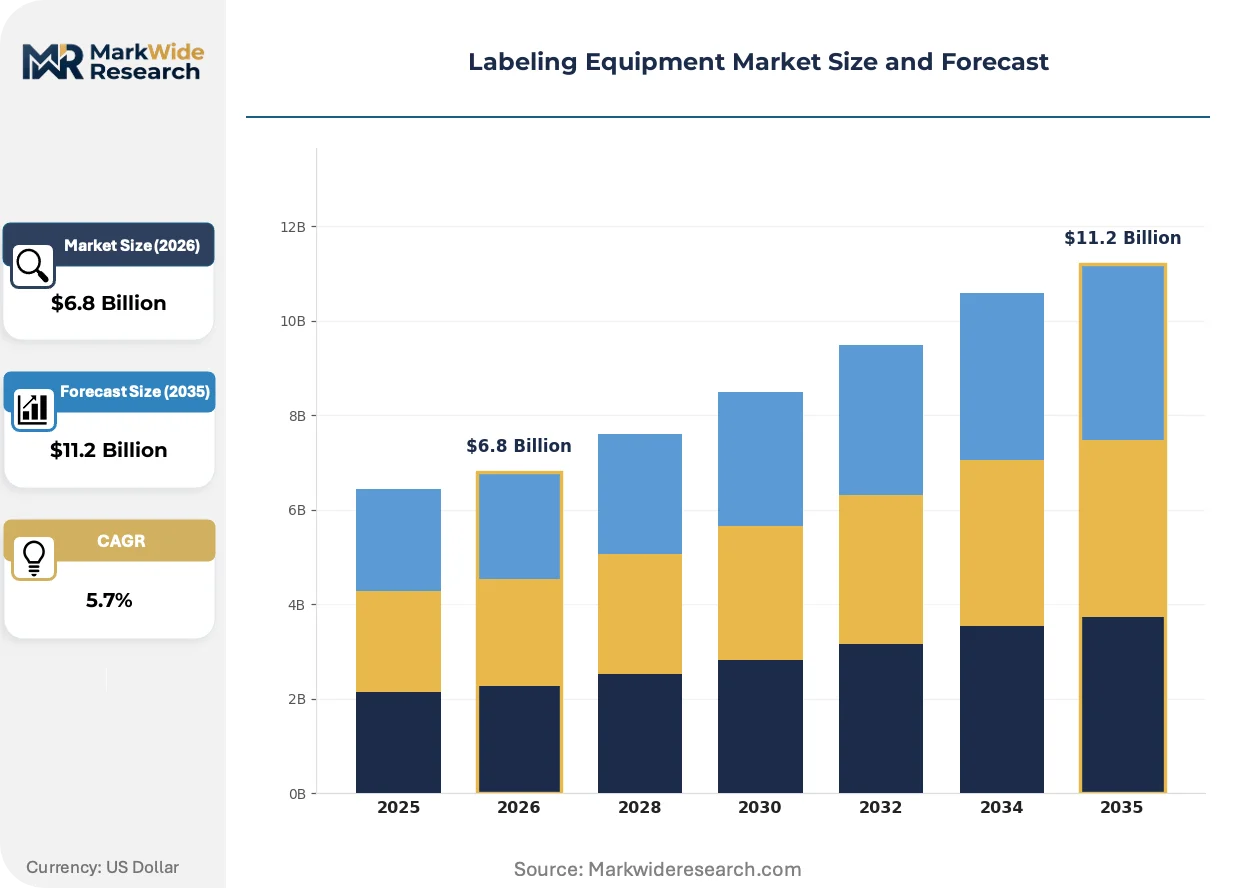
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Labels, Shrink Sleeve Labels, In-Mold Labels, RFID Labels Technology: Digital Printing, Flexographic Printing, Offset Printing, Letterpress Printing End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesalers |
| Companies Covered | Krones AG, Herma GmbH, ProMach, Sidel Group, Sacmi Group, Barry-Wehmiller Companies, Fuji Seal International, Inc., Markem-Imaje, Weber Packaging Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Labeling Equipment Market Emerging Trajectories
Equipment architectures are fragmenting into configurable subsystems that accommodate rapid format changeovers, compressed batch sizes, and regulatory traceability requirements without dedicated hardware swaps.
Print engine technology is modularizing around interchangeable digital heads that snap into existing flexographic frames. Beverage and personal care packagers in Germany and the Netherlands are retrofitting legacy lines with hybrid configurations that switch between analog efficiency and digital personalization within a single production shift. This modularizing approach is collapsing the economic threshold for variable-data jobs, pulling short-run work back from outsourced converters into in-house packaging operations.
The EPA's volatile organic compound emission limits for solvent-based flexographic inks are forcing equipment redesigns toward water-based or ultraviolet-cured alternatives. Converters across North American food packaging are installing extended drying tunnels and LED curing stations that occupy 40% more line length than conventional configurations. The regulatory pressure is most acute in California and Northeast corridor states with overlapping state-level air quality mandates, where equipment buyers are prioritizing compliant configurations over speed specifications.
Contract packagers are unbundling after-sales service from capital purchases, negotiating performance-based maintenance agreements that transfer uptime risk to equipment vendors. Food and pharmaceutical co-manufacturers in the US Midwest and Rhineland industrial clusters are leading this shift, replacing fixed-fee service contracts with variable payments tied to verified equipment availability metrics. The model concentrates vendor relationships among suppliers with sufficient field service density to absorb operational risk profitably.
Labeling Equipment Market Segmentation
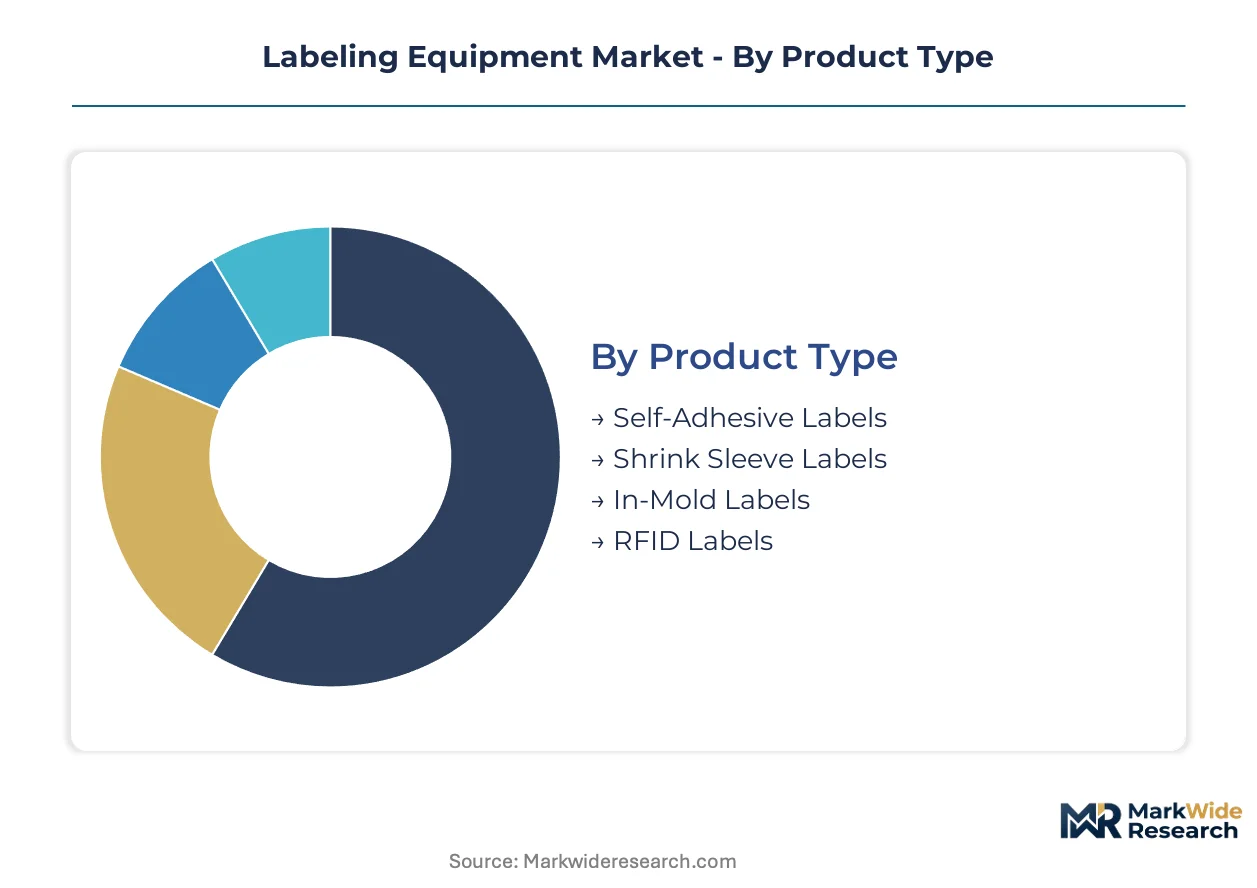
Labeling equipment purchasing decisions cluster around substrate compatibility, print technology economics, and regulatory compliance intensity. Equipment replacement cycles vary dramatically across these dimensions, with pharmaceutical serialization mandates forcing shorter upgrade intervals than food commodity applications.
Product Type:
Equipment refresh cycles diverge sharply by label format, with adhesive-based systems facing obsolescence pressure from RFID integration requirements and sustainability-driven material shifts.
- Self-Adhesive Labels:Pressure-sensitive applicators dominate installed capacity across beverage and personal care lines in Germany and the Netherlands. Equipment upgrades concentrate in high-speed rotary systems as packagers seek to reduce changeover downtime between stock-keeping units. ECHA chemical restrictions on adhesive formulations are forcing applicator retrofits compatible with wash-off and compostable substrates.
- RFID Labels:Radio-frequency identification encoding and verification modules represent the steepest expansion trajectory as retailers mandate item-level tracking. Pharmaceutical distributors in Switzerland and logistics operators in the Benelux region are driving demand for integrated inlay applicators with real-time authentication capability.
- Shrink Sleeve Labels:Heat-tunnel configurations face energy efficiency scrutiny under EU Green Deal carbon accounting rules.
- In-Mold Labels:Injection molding integration limits addressable equipment base to container manufacturers with captive decorating operations.
Self-adhesive equipment sits at the top of the volume ranking, with RFID label systems climbing the fastest.
Technology:
Print engine selection determines capital recovery periods, with analog systems amortizing over longer runs and digital configurations justified by job fragmentation.
- Digital Printing:Inkjet and toner-based systems capture personalized packaging and pharmaceutical serialization work where variable data density disqualifies plate-based methods. Equipment purchasers in California prioritize EPA-compliant water-based ink configurations over solvent alternatives. Modular digital heads that retrofit into existing flexographic frames are collapsing the economic threshold for short-run jobs.
- Flexographic Printing:Rotary letterpress technology retains cost advantages for long-run commodity labels in food and beverage applications. Central impression drum configurations dominate high-volume beverage operations in Germany, where machinery engineering clusters support rapid spare parts availability.
- Offset Printing:Sheet-fed offset label presses serve premium cosmetic and pharmaceutical carton applications requiring fine-line halftone reproduction.
- Letterpress Printing:Water-based flexographic displacement has confined letterpress to narrow specialty applications with metallic or tactile effects.
Flexographic equipment commands the largest installed base, though digital printing platforms are gaining share fastest among contract packagers.
End User:
Compliance intensity and batch complexity shape equipment specifications, with regulated industries accepting premium pricing for traceability integration.
- Pharmaceuticals:EMA serialization mandates require vision-verified data-matrix printing with ISO-grade optical character recognition validation. Equipment specifications emphasize reject-and-divert mechanisms for non-conforming units. CDSCO alignment in India is extending these requirements to contract manufacturing organizations serving export markets.
- Food & Beverage:High-throughput rotary applicators dominate beverage bottling lines, with Germany's F-Gas Regulation driving dryer subsystem replacements. Extended thermal tunnels for water-based inks constrain line speeds and floor space efficiency in North American facilities facing EPA emission limits.
- Cosmetics:Premium positioning demands metallic embellishment and tactile effects that favor hybrid digital-analog configurations.
- Electronics:Anti-static labeling environments and miniature component formats require precision dispensing systems with sub-millimeter placement accuracy.
Food and beverage equipment constitutes the largest revenue pool, while pharmaceutical applications show the steepest specification escalation.
Distribution Channel:
Equipment procurement patterns reflect capital intensity and technical complexity, with integrated systems favoring direct manufacturer relationships.
- Direct Sales:Complex pharmaceutical serialization lines and high-speed beverage integrations require factory-direct specification, installation, and commissioning. Performance-based maintenance agreements are displacing fixed-fee service contracts among co-manufacturers in the US Midwest.
- Distributors:Regional equipment distributors serve mid-tier food packagers with standardized applicator configurations and local spare parts stocking.
- Online Retailers:Benchtop and semi-automatic systems for small-batch cosmetics and craft beverage producers migrate through e-commerce channels.
- Wholesalers:Secondary market equipment refurbishment and resale concentrates in wholesaler networks serving emerging market price sensitivity.
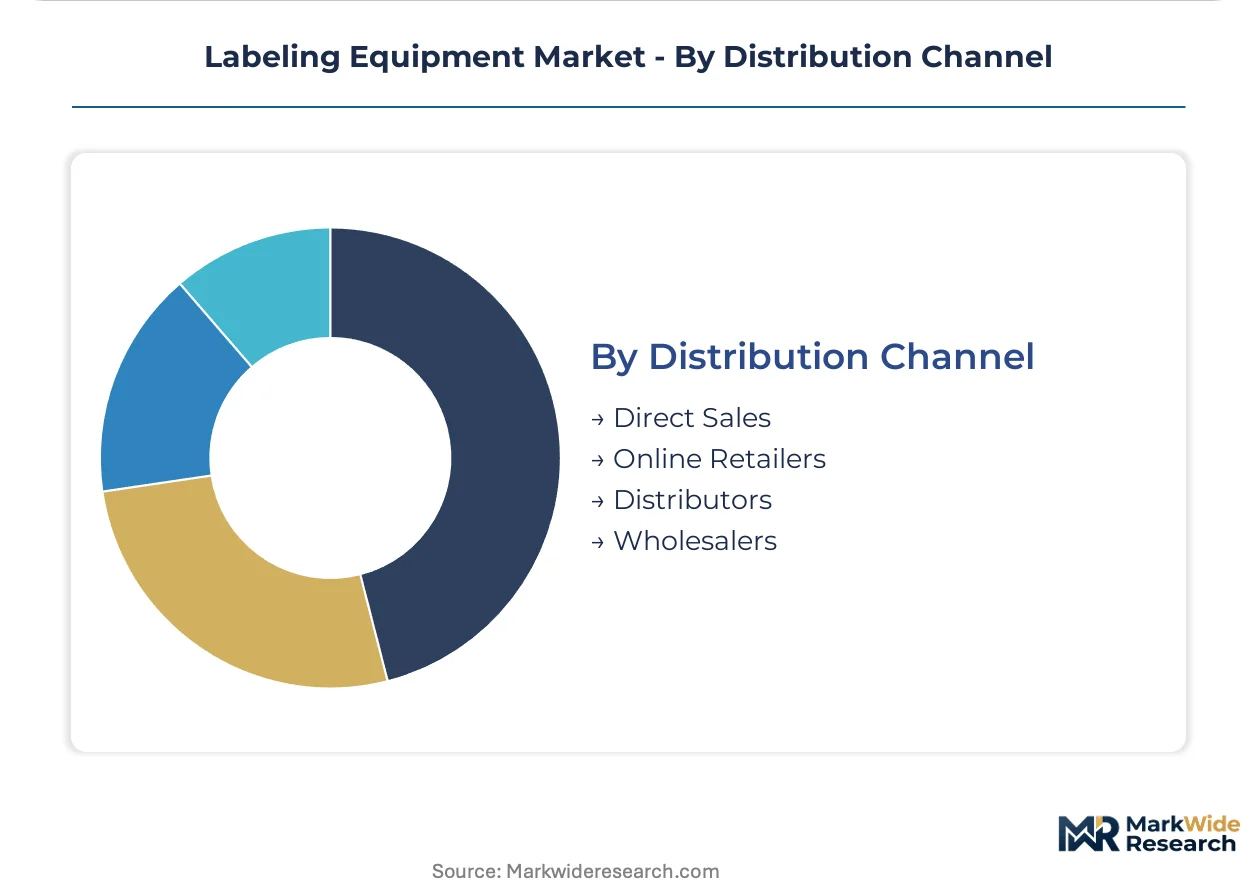
Direct sales channels capture the highest value transactions, with distributor networks expanding most quickly in Eastern European pharmaceutical manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Labeling equipment manufacturing originated in German engineering clusters during the post-war industrial expansion, with rotary pressure-sensitive applicators first scaling in Rhineland beverage bottling lines. This heritage continues to shape equipment standards and export dominance across pharmaceutical and food packaging applications.
Germany
EMA serialization mandates and F-Gas Regulation compliance timelines are forcing simultaneous upgrades across pharmaceutical and beverage packaging lines. Machinery engineering clusters in Bavaria and North Rhine-Westphalia dominate high-speed rotary system production. Krones AG anchors the Rhineland corridor with integrated bottling and labeling platforms serving export markets.
United States
EPA volatile organic compound limits are pushing converters toward water-based ink configurations with extended thermal drying tunnels. Food co-manufacturers in the Midwest are negotiating performance-based maintenance agreements that transfer uptime risk to equipment vendors. California and Northeast corridor states with overlapping air quality mandates are prioritizing compliant configurations over speed specifications.
India
CDSCO serialization alignment is extending EMA-equivalent track-and-trace requirements to contract manufacturing organizations serving export markets. Pharmaceutical packaging lines in Maharashtra and Gujarat are qualifying vision-verified data-matrix systems ahead of enforcement deadlines. Mumbai-Pune industrial corridor demand is concentrating among domestic equipment integrators with local service density.
China
NMPA pharmaceutical packaging regulations and dual carbon goals are reshaping equipment specifications for domestic and export-oriented manufacturers. Yangtze River Delta electronics and personal care packagers are adopting RFID label applicators for inventory authentication. Shanghai and Suzhou machinery clusters are scaling digital printing module production for regional supply.
Switzerland
Swissmedic serialization standards and precision manufacturing heritage sustain demand for high-accuracy dispensing systems. Pharmaceutical distributors in Basel and Zurich are driving integrated inlay applicator requirements with real-time authentication capability. Alpine logistics operators are deploying RFID verification modules for cross-border supply chain visibility.
Labeling Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the labeling equipment landscape, with integrated system builders maintaining foundry-like control over manufacturing while modular component specialists focus on print engine and vision system innovation. The vendor base separates into three strategic archetypes: diversified packaging machinery conglomerates with captive labeling divisions, pure-play labeling equipment specialists with deep substrate expertise, and regional integrators serving emerging market price sensitivity. Consolidation pressure is intensifying as pharmaceutical serialization mandates concentrate procurement among vendors with validated quality systems, while technology licensing agreements proliferate around digital print head compatibility.
Among German-based engineering conglomerates, Krones AG and Herma GmbH exemplify the integrated systems archetype, with Krones representing beverage packaging line integration and Herma anchoring precision self-adhesive dispensing for pharmaceutical workflows. ProMach occupies a position within the North American modular architecture segment, competing across food packaging lines with format-flexible configurations. These three entities illustrate the geographic and technological stratification shaping competitive positioning, with European heritage concentrated in high-speed rotary systems and North American players emphasizing rapid changeover capabilities.
| Leading Market Players |
|---|
| Krones AG |
| Herma GmbH |
| ProMach |
| Sidel Group |
| Sacmi Group |
| Barry-Wehmiller Companies |
| Fuji Seal International, Inc. |
| Markem-Imaje |
| Weber Packaging Solutions |
| Others |
Supply Flow & Price Mechanics
EMA serialization mandates and EPA volatile organic compound limits are forcing pharmaceutical and food packagers toward premium-configured equipment with integrated vision systems and extended drying tunnels, compressing procurement flexibility and anchoring supplier pricing power among qualified German and Japanese component specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-validated systems with ISO-grade vision modules from mid-tier food packaging configurations and entry-level benchtop units for craft producers. Price differentiation hinges on certification tier—CE-marked pharmaceutical lines command substantial premiums over standard industrial configurations—and after-sales service bundling, with performance-based maintenance agreements transferring uptime risk to vendors. Cost compression in mid-tier segments is intensifying as stainless steel and servo motor input volatility squeezes equipment integrator margins. Contract packagers in the US Midwest exhibit highest price sensitivity, while Swiss pharmaceutical distributors prioritize specification compliance over unit economics.
Supply Chain Analysis
ISO-grade vision system and high-resolution print engine qualification requirements concentrate component supply among German and Japanese specialists, creating single-source vulnerability for equipment integrators assembling complete lines. Manufacturing draws from precision machining clusters in Germany, servo motor production in Japan, and corrosion-resistant alloy foundries in China. Tariff exposure on Chinese steel inputs and Japanese motion-control components elevates cost unpredictability for North American equipment builders. Distribution runs through direct manufacturer relationships for complex pharmaceutical lines, with regional distributors serving standardized food packaging configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in India, where CDSCO serialization enforcement lags EMA-equivalent standards by several regulatory cycles, allowing qualified equipment vendors to capture first-mover premiums ahead of domestic compliance deadlines.
For Market Incumbents: To counter modular digital print head displacement of conventional flexographic architectures, Krones AG and Herma GmbH should deepen backward integration into vision system module production and expand captive service density across the Mumbai-Pune corridor to absorb performance-based contract risk profitably. For New Entrants and Emerging Players: Launch via online retail channels targeting craft beverage and small-batch cosmetics producers seeking semi-automatic benchtop systems, then ladder into mid-tier food packaging through distributor partnerships in Eastern European markets where pharmaceutical manufacturing investment is accelerating fastest. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play labeling equipment specialists possessing validated pharmaceutical quality systems and dense installed bases in Germany's machinery engineering clusters; monitor CDSCO enforcement timeline acceleration as the inflection signal for Indian contract manufacturing equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Head Retrofit Programs | Modular inkjet integration into existing flexographic frames collapses short-run economic thresholds for beverage packagers. |
| Performance-Based Maintenance Contracts | Uptime risk transfer to vendors concentrates relationships among suppliers with sufficient field service density in US Midwest clusters. |
| RFID Inlay Applicator Development | Real-time authentication capability addresses Swissmedic serialization standards and retail inventory tracking mandates. |
| Water-Based Ink Drying Tunnel Expansion | Extended thermal configurations satisfy EPA emission limits while constraining line speeds in California food packaging facilities. |
| Indian Pharmaceutical Line Qualification | CDSCO alignment with EMA track-and-trace requirements creates first-mover equipment certification advantages in Maharashtra. |
Methodological Framework
Coverage spans Germany, the United States, India, China, and Switzerland, with primary inputs from each market combining structured interviews with plant engineers at beverage bottling facilities, procurement leads at pharmaceutical contract manufacturers, aftermarket service heads at equipment integrators, and regulatory affairs specialists at vision system module suppliers, validated against secondary sources including EMA guidance documents, EPA emission standard filings, CDSCO draft regulations, SEC 10-K disclosures from listed packaging machinery conglomerates, and trade flow data from German engineering export associations, with bottom-up equipment shipment tallies triangulated against top-down packaging line investment surveys.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon, modeling demand by product type (self-adhesive, RFID, shrink sleeve, in-mold), technology (digital, flexographic, offset, letterpress), end user (pharmaceutical, food and beverage, cosmetics, electronics), and distribution channel (direct sales, distributors, online retailers, wholesalers), with CAGRs derived from regression analysis of historical equipment replacement cycles against regulatory enforcement timelines and input cost indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated F-Gas Regulation phase-out schedules or sudden stainless steel price spikes. The analysis reflects documented assumptions regarding serialization mandate enforcement consistency and digital print head reliability maturation. A model refresh is warranted upon material change in EPA volatile organic compound regulatory stringency or CDSCO implementation timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Packer Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Packaging Racks Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Volumetric Filing Lines Market