
 Global 2-Shot Injection Molding Market | 2026-2036
Global 2-Shot Injection Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Global 2-Shot Injection Molding Market Foresight
Aftermarket mold refurbishment and spare hot-runner component supply is rewriting margin capture across the value chain. Arburg GmbH + Co KG leverages its captive control over servo-electric injection unit technology to sustain premium positioning in precision medical applications. ENGEL Holding GmbH anchors large-tonnage rotary-table installations across European automotive Tier-1 suppliers. Gemini Group, Inc. competes on vertically integrated mold fabrication and validation capabilities in North American medical device supply chains.
Global 2-Shot Injection Molding refers to a sequential or simultaneous multi-material forming process where two distinct polymers—typically a rigid substrate and an elastomeric overmold—are injected into a single mold cavity in one machine cycle, achieving chemical or mechanical bonding without secondary assembly. The process operates at clamp forces ranging from 50 to 5,000 metric tons and serves primarily to eliminate manual assembly, improve sealing performance, and enable functional surface textures in finished goods. Hard-soft combinations dominate current output volumes owing to their ubiquity in medical device grips and consumer electronics button interfaces, while conductive-nonconductive configurations represent the fastest-expanding segment as OEMs integrate touch-sensitive surfaces into appliance housings. Rotary mold technology leads capital equipment deployments due to its proven repeatability, though stack mold architectures are gaining share where floor space constraints dominate facility planning.
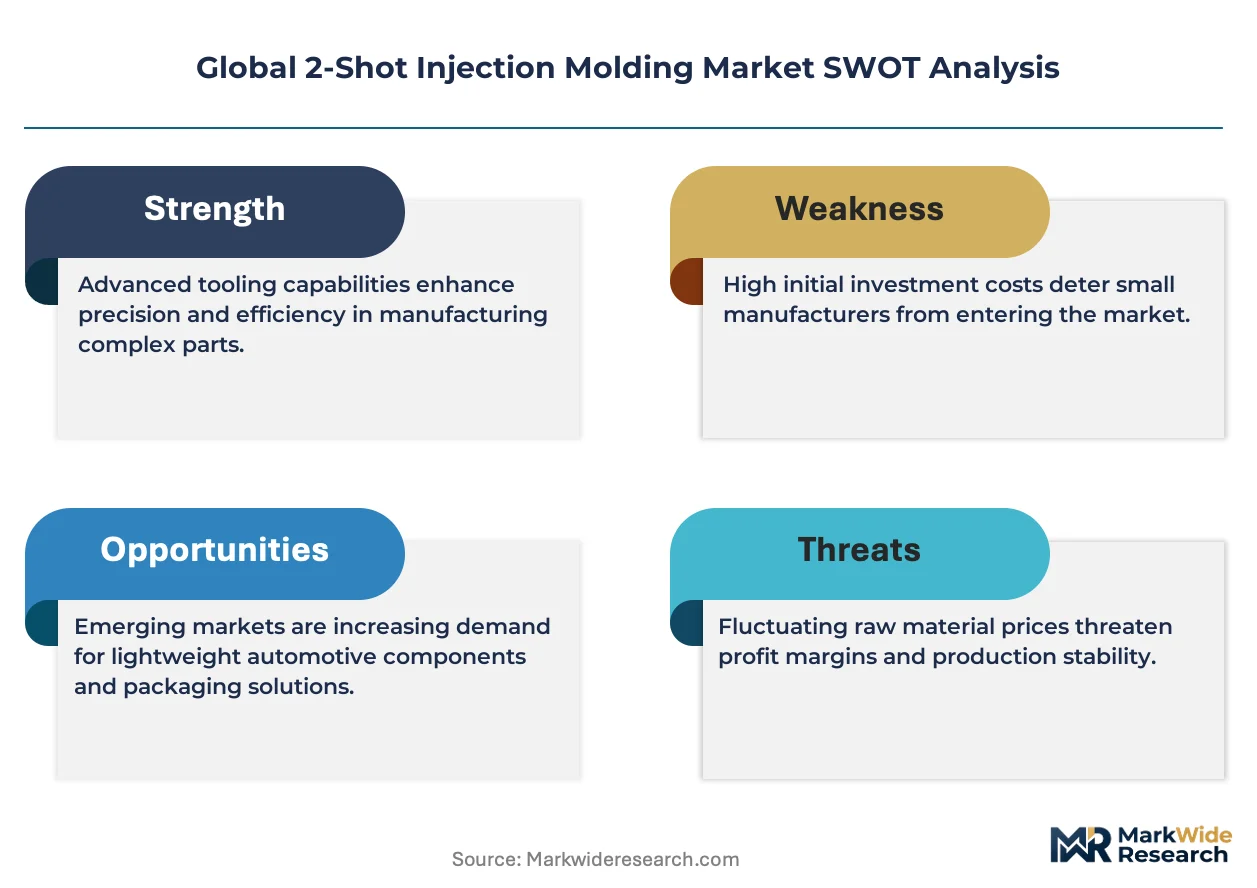
ISO 13485 medical device quality management systems and FDA 21 CFR Part 820 quality system regulation shape product validation requirements for molders serving diagnostic and surgical instrument clients, extending cycle times but creating defensible barriers against unqualified competitors. REACH substance restrictions and RoHS hazardous substance limits in Europe constrain eligible polymer portfolios, favoring suppliers with pre-certified material libraries and documented biocompatibility testing. ECHA's ongoing scrutiny of phthalate plasticizers is accelerating converter migration to bio-based TPE alternatives, a transition that demands close monitoring of supply chain qualification timelines and mold-process parameter revalidation costs.
Market Dynamics
Automotive interior component manufacturers in Germany and China are expanding adoption of multicomponent molding to reduce assembly steps and improve seal integrity, while REACH compliance in the European Union and China's GB standards tighten material compatibility requirements.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA enforcement of CO2 reduction targets pushes Tier-1 suppliers toward hard-soft TPE combinations that eliminate separate gaskets and clips.
- REACH substance restrictions:ECHA's ongoing scrutiny of phthalate plasticizers accelerates converter migration to bio-based TPE alternatives with documented biocompatibility testing.
- Rotary mold technology:Proven repeatability in medical device manufacturing supports ISO 13485 validation requirements for diagnostic and surgical instrument clients.
Market Restraints
- Specialized hot-runner component supply:Concentrated production of valve-gate nozzles and temperature controllers in German and Japanese suppliers creates lead-time vulnerability.
- Dual-carbon policy compliance:China's MEE enforcement of energy-intensity caps raises electricity costs for electric injection molding operations in the Yangtze River Delta cluster.
- Silicone overmolding substitution:Liquid silicone rubber processing achieves comparable sealing performance at lower capital investment for high-volume medical applications.
Strategic Opportunities
- Conductive-nonconductive configurations:Appliance OEMs integrate touch-sensitive surfaces into housings, creating fastest-expanding segment demand for capacitive-interface molding.
- Stack mold architectures:Floor-space-constrained facilities in Japan's Aichi Prefecture automotive cluster adopt vertical cavity arrangements to double output without facility expansion.
- Aftermarket refurbishment services:Mold resurfacing and hot-runner component replacement capture margin from installed base of 5,000+ metric ton rotary machines across European automotive Tier-1 networks.
Industry Challenges
- Cross-trained technician scarcity:Simultaneous expertise in polymer rheology, mold thermal management, and machine control systems commands premium wages in China's Shenzhen electronics corridor.
- Validation timeline compression:FDA 21 CFR Part 820 quality system regulation extends first-article approval cycles, delaying revenue recognition for medical device contract manufacturers.
- Legacy equipment integration:Retrofitting servo-electric injection units onto hydraulic clamp platforms requires custom control architecture development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 2-Shot Injection Molding Market |
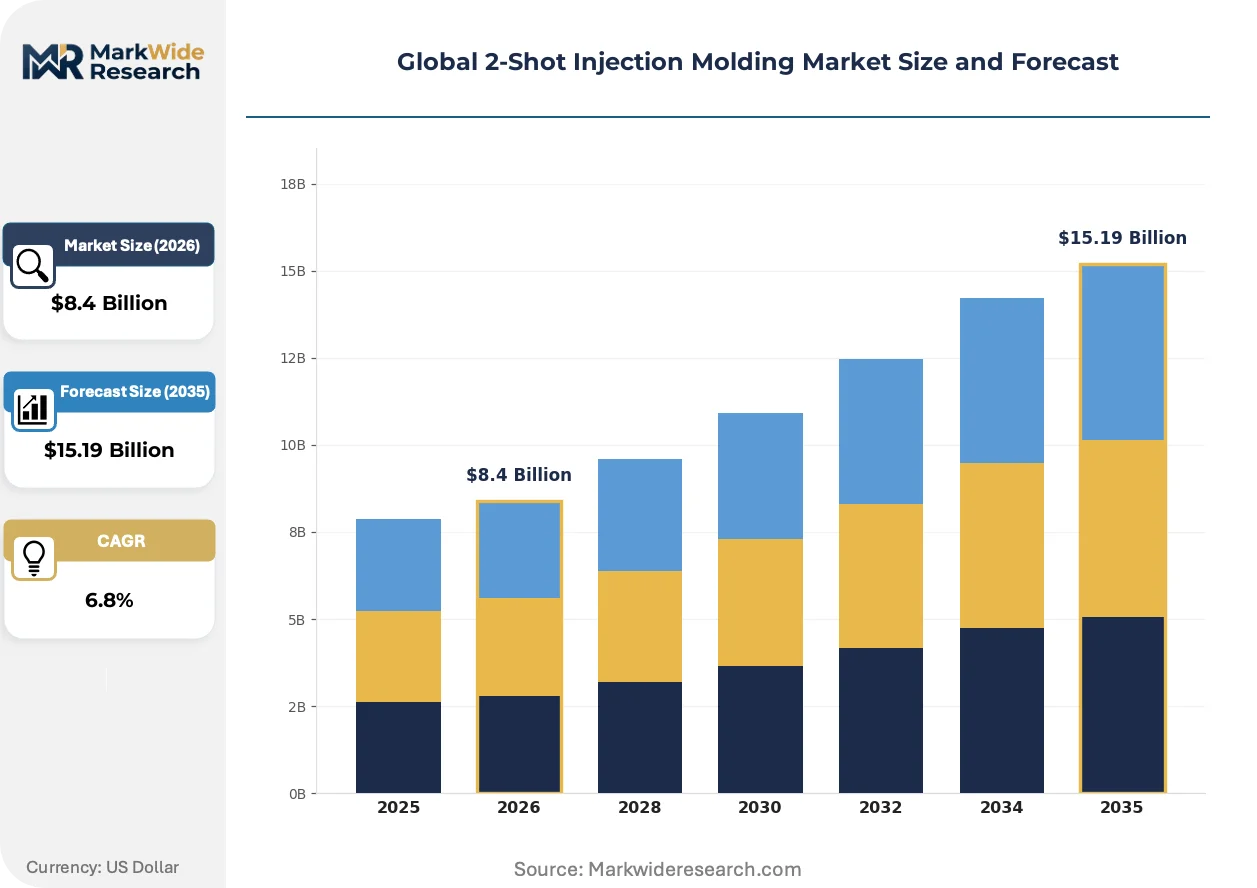
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard-Soft Combination, Color Combination, Material Blend, Transparent-Opaque, Conductive-Nonconductive Technology: Stack Mold, Rotary Mold, Multicomponent Mold, Hot Runner, Cold Runner Application: Consumer Electronics, Household Appliances, Packaging Components, Medical Devices, Sporting Goods End User Industry: Electrical Equipment Manufacturers, Plastic Goods Producers, Medical Equipment Companies, Medical Device Suppliers, Sports Equipment Fabricators |
| Companies Covered | Gemini Group, Inc., Arburg GmbH + Co KG, Paragon Rapid Technologies, Season Group, Girard Rubber Corporation, CM International Industries Corp., SIMTEC Silicone Parts, Bemis Manufacturing Company, ENGEL Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 2-Shot Injection Molding Market Shifts & Advancements
Sequential multi-material forming is advancing through three interconnected developments: machine control architecture, regulatory material frameworks, and buyer procurement models.
Electric injection unit technology is migrating from niche medical applications toward mainstream automotive and consumer electronics production. Arburg GmbH + Co KG and ENGEL Holding GmbH deploy servo-electric drives for precision medical applications, while Chinese molders in Dongguan adopt hybrid electric-hydraulic systems for cost-sensitive electronics housings. This migration is compressing energy consumption differentials between European and Asian production economics.
ECHA's REACH substance restrictions and RoHS hazardous substance limits constrain eligible polymer portfolios across European converter operations. Pre-certified material libraries from compounders with documented biocompatibility testing create procurement preference hierarchies. Medical device molders serving diagnostic instrument clients prioritize suppliers with ISO 10993 testing completion to accelerate FDA submission timelines.
Integrated mold-making and injection capacity procurement models concentrate in China's Yangtze River Delta manufacturing cluster. Buyers source complete prototyping-to-production cycles from single-source providers rather than dispersing mold fabrication and molding across separate vendors. This pattern is most visible in consumer electronics housing programs where compressed product lifecycles demand 72-hour design iteration cycles.
Global 2-Shot Injection Molding Market Segmentation
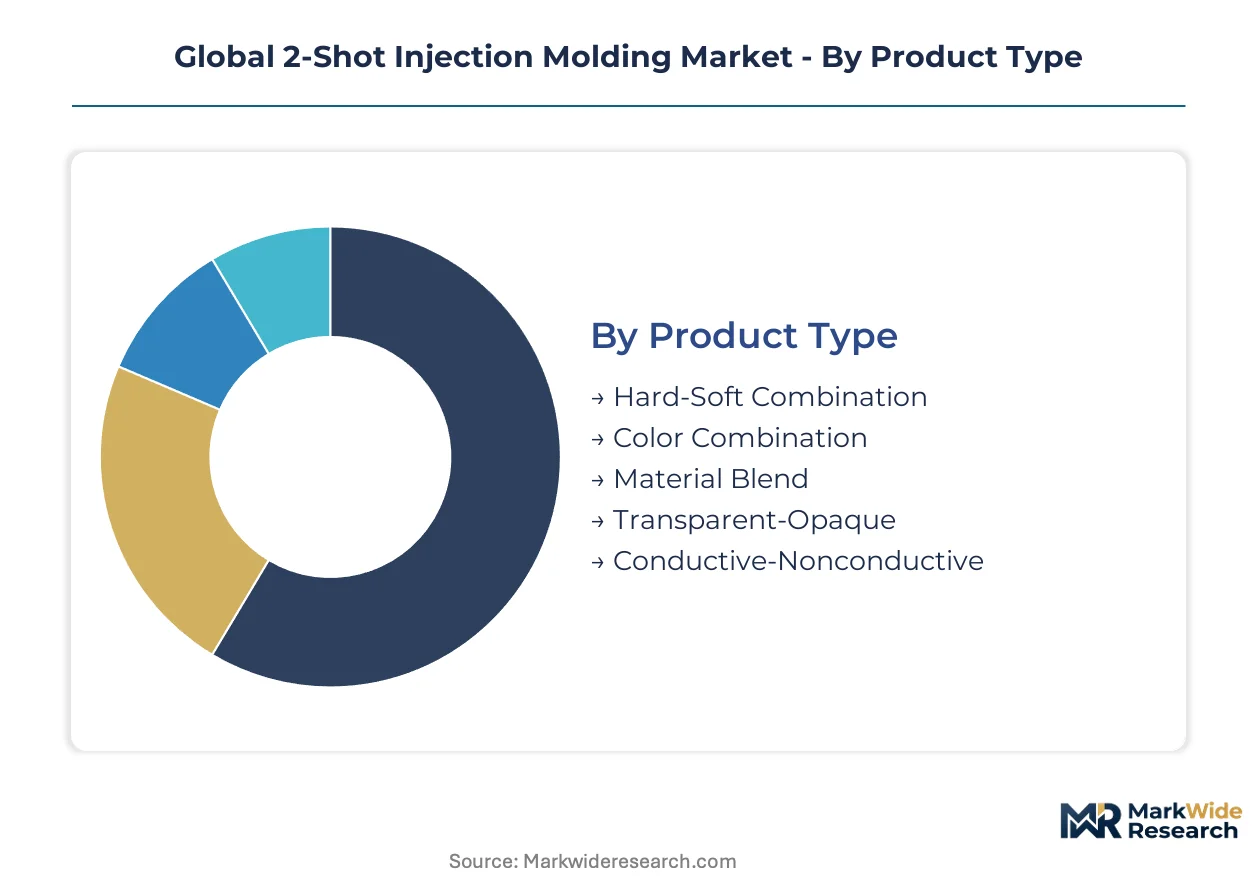
Segmentation in 2-shot injection molding reveals how cycle-time economics, tooling complexity, and regulatory validation requirements fragment production across distinct technical tiers. Buyers select configurations based on whether speed-to-market or compliance documentation commands priority in their supply chain.
Product Type:
Cycle times compress most dramatically for commodity combinations while specialized material pairings extend validation timelines by weeks.
- Hard-Soft Combination:Rigid thermoplastic substrates bonded with elastomeric TPE overmolds dominate medical device grips and automotive seals. German Tier-1 suppliers and China's Yangtze River Delta electronics molders anchor demand for validated hard-soft TPE combinations under REACH and GB standards.
- Conductive-Nonconductive:Capacitive-interface molding integrates touch-sensitive circuits into appliance housings without secondary assembly. Appliance OEMs in Japan's Aichi Prefecture and South Korea's Gyeonggi Province drive the steepest expansion trajectory for this configuration as smart home interfaces proliferate.
- Color Combination:Aesthetic multi-tone finishes for consumer electronics housings require precise pigment stability across melt temperatures. Dongguan molders execute 72-hour design iteration cycles for compressed product lifecycles.
- Material Blend:Engineered polymer alloys combine mechanical properties unavailable in single-resin formulations. Automotive lightweighting mandates from Germany's KBA push development of structural blends.
- Transparent-Opaque:Optical clarity combined with diffusive backing serves diagnostic instrument windows and lighting diffusers. Medical device suppliers prioritize ISO 10993-tested material libraries to accelerate FDA submission timelines.
Hard-Soft Combination anchors the volume base while Conductive-Nonconductive gains share at the steepest rate.
Technology:
Capital intensity stratifies sharply between precision servo-electric systems and cost-optimized hydraulic alternatives.
- Rotary Mold:Proven repeatability in medical device manufacturing supports ISO 13485 validation requirements. ENGEL Holding GmbH anchors large-tonnage rotary-table installations across European automotive Tier-1 suppliers.
- Stack Mold:Vertical cavity arrangements double output within fixed floor space constraints. Japan's Aichi Prefecture automotive cluster adopts stack architectures where facility expansion is physically constrained.
- Hot Runner:Valve-gate nozzle systems eliminate cold slug waste and reduce cycle times. Concentrated production in German and Japanese suppliers creates lead-time vulnerability for aftermarket refurbishment.
- Multicomponent Mold:Sequential injection stations enable complex material sequencing in single cycles. Arburg GmbH + Co KG leverages captive control over servo-electric injection unit technology for precision medical applications.
- Cold Runner:Lower capital investment suits prototype-to-production transitions and short-run specialty applications. Chinese molders in Dongguan deploy hybrid electric-hydraulic cold runner systems for cost-sensitive electronics programs.
Rotary Mold commands the premium tier while Stack Mold captures the fastest adoption among space-constrained facilities.
Application:
Regulatory burden intensity separates medical validation cycles from consumer electronics speed-to-market demands.
- Consumer Electronics:Housing programs demand 72-hour design iteration cycles with compressed product lifecycles. China's Yangtze River Delta manufacturing cluster concentrates integrated mold-making and injection capacity for rapid prototyping-to-production transitions.
- Medical Devices:FDA 21 CFR Part 820 quality system regulation extends first-article approval cycles. Gemini Group, Inc. competes on vertically integrated mold fabrication and validation capabilities in North American medical device supply chains.
- Household Appliances:Touch-sensitive surface integration drives conductive-nonconductive configuration demand. OEMs in South Korea and Japan prioritize capacitive-interface molding for smart home product differentiation.
- Packaging Components:Seal integrity requirements push adoption of multicomponent molding to eliminate separate gaskets. Germany's KBA enforcement of CO2 reduction targets accelerates lightweighting in automotive-adjacent packaging.
- Sporting Goods:Ergonomic grip surfaces and impact-dampening structures utilize hard-soft combinations. Sports equipment fabricators source from molders with documented biocompatibility testing for skin-contact applications.
Consumer Electronics generates the highest transaction velocity while Medical Devices commands the longest contract durations.
End User Industry:
Procurement sophistication varies from commodity volume buyers to specification-driven medical validators.
- Medical Device Suppliers:ISO 13485 quality management systems and FDA 21 CFR Part 820 requirements shape supplier qualification. ECHA's REACH substance restrictions and RoHS limits constrain eligible polymer portfolios.
- Electrical Equipment Manufacturers:Appliance OEMs integrate touch-sensitive surfaces into housings, creating demand for capacitive-interface molding. Japan's METI efficiency standards influence equipment specification priorities.
- Plastic Goods Producers:General-purpose molders serve packaging and consumer goods with cost-optimized configurations. China's MEE enforcement of energy-intensity caps raises electricity costs for electric injection molding operations.
- Medical Equipment Companies:Diagnostic instrument clients prioritize suppliers with ISO 10993 testing completion. Pre-certified material libraries create procurement preference hierarchies.
- Sports Equipment Fabricators:Performance-oriented products demand specialized elastomeric properties for grip and impact absorption. Bio-based TPE alternatives are displacing phthalate plasticizers under regulatory pressure.
Medical Device Suppliers maintain the most stringent qualification barriers while Electrical Equipment Manufacturers drive the fastest specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Yangtze River Delta cluster demonstrate the highest price elasticity, squeezing margins on standard hard-soft configurations, while medical device validators in Germany and Switzerland absorb premium pricing for ISO 13485-compliant production with minimal volume sensitivity.
Germany
KBA enforcement of CO2 reduction targets accelerates automotive lightweighting mandates for Tier-1 suppliers. REACH substance restrictions and ECHA scrutiny of phthalate plasticizers constrain eligible polymer portfolios toward bio-based TPE alternatives. The Baden-Württemberg and Bavaria industrial corridors concentrate rotary-table installations for precision medical and automotive sealing applications.
China
Integrated mold-making and injection capacity in the Yangtze River Delta supports 72-hour prototyping-to-production cycles for consumer electronics housings. MEE enforcement of dual-carbon energy-intensity caps raises electricity costs for electric injection molding operations. Dongguan molders deploy hybrid electric-hydraulic systems for cost-sensitive electronics programs with compressed product lifecycles.
United States
FDA 21 CFR Part 820 quality system regulation extends validation timelines for diagnostic instrument contract manufacturers. ISO 13485 medical device quality management systems create defensible barriers against unqualified competitors. Vertically integrated mold fabrication and validation capabilities concentrate in Midwest medical device supply chains serving surgical instrument clients.
Japan
METI efficiency standards influence equipment specification priorities for appliance OEMs integrating touch-sensitive surfaces into smart home housings. Floor-space constraints in the Aichi Prefecture automotive cluster drive adoption of stack mold architectures to double output without facility expansion. Kansai and Chubu regions anchor demand for capacitive-interface molding configurations.
South Korea
Appliance OEMs in Gyeonggi Province prioritize conductive-nonconductive configurations for smart home product differentiation. MFDS medical device regulations shape supplier qualification requirements for domestic diagnostic instrument production. The Seoul Capital Area concentrates electronics housing molders serving compressed product lifecycle demands from regional consumer brands.
Global 2-Shot Injection Molding Market Competitive Landscape
Capability concentration sits with European and Japanese precision equipment fabricators; scale advantage sits with Chinese integrated mold-making and molding operations. The vendor base stratifies across three tiers: captive technology developers controlling servo-electric injection architectures, vertically integrated mold fabricators with validation capabilities, and cost-optimized hybrid system deployers. Dominant competitive moves include geographic expansion through integrated prototyping-to-production service models and technology licensing partnerships for rotary-table precision systems.
Within the captive technology tier, Arburg GmbH + Co KG and ENGEL Holding GmbH represent German precision equipment archetypes with control over servo-electric injection unit architectures. Gemini Group, Inc. anchors North American vertically integrated positioning through mold fabrication and validation capabilities. Among Asia-Pacific fabricators, Season Group exemplifies the integrated service model spanning rapid prototyping through volume production for consumer electronics programs.
| Leading Market Players |
|---|
| Gemini Group, Inc. |
| Arburg GmbH + Co KG |
| Paragon Rapid Technologies |
| Season Group |
| Girard Rubber Corporation |
| CM International Industries Corp. |
| SIMTEC Silicone Parts |
| Bemis Manufacturing Company |
| ENGEL Holding GmbH |
| Others |
Supply & Pricing Matrix
Dongguan's hybrid electric-hydraulic system deployers anchor cost-sensitive electronics production, compressing margins on standard hard-soft configurations while European medical validators absorb premium pricing for ISO 13485-compliant rotary-table precision. This geographic bifurcation concentrates pricing power with captive technology developers controlling servo-electric architectures and fragments margin capture among commoditized mold refurbishment providers.
Pricing Analysis
Aftermarket mold refurbishment and spare hot-runner component supply drives lifetime value capture across installed bases exceeding 5,000 metric tons in European automotive Tier-1 networks. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in China's Yangtze River Delta cluster intensifies because integrated mold-making and injection capacity enables rapid prototyping-to-production cycles. Consumer electronics housing buyers demonstrate highest price sensitivity, while medical device suppliers absorb premium positioning with minimal volume sensitivity.
Supply Chain Analysis
Tariff exposure between Germany and China dominates strategic planning for valve-gate nozzle and temperature controller procurement. Supply concentrates in German and Japanese precision equipment fabricators, with raw material dependencies spanning specialized TPE compounds, servo-electric drive components, and certified mold steels. Single-source vulnerability in hot-runner component production creates lead-time risk for aftermarket refurbishment. Distribution runs through integrated prototyping-to-production service models in China's Yangtze River Delta and vertically validated supply chains in North American medical device corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as conductive-nonconductive configurations for capacitive-interface molding penetrate appliance housings at accelerating rates. Regulatory migration from phthalate plasticizers toward bio-based TPE alternatives sustains converter qualification demand across medical and automotive supply chains.
For Market Incumbents: Build captive control over servo-electric injection unit technology as the defensive moat. Deepen ISO 13485 validation capabilities to create defensible barriers against unqualified competitors. Add stack mold architecture capacity in Japan's Aichi Prefecture where floor-space constraints dominate facility planning. Liquid silicone rubber processing substitution threatens hard-soft combination volumes in high-volume medical applications.
For New Entrants and Emerging Players: Mid-market conductive-nonconductive configurations for smart home appliance OEMs in South Korea's Gyeonggi Province represent the most penetrable entry point. Aftermarket hot-runner component replacement services across European automotive Tier-1 networks offer margin capture from aging rotary-table installations. Partner with compounders holding pre-certified bio-based TPE libraries to accelerate supply chain qualification timelines. Target integrated mold-making and injection capacity procurement models in China's Yangtze River Delta.
For Investors and Strategic Acquirers: Long-term, this sits as a process technology consolidation play because captive servo-electric architecture control and validated mold fabrication capabilities concentrate with European and Japanese precision equipment fabricators. Acquisition targets include vertically integrated mold fabricators with ISO 10993 testing completion and regional medical device validation credentials. Monitor ECHA enforcement actions on phthalate plasticizer restrictions as the inflection indicator for bio-based TPE substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mold Fabrication | Captures margin from validation-intensive medical device supply chains requiring ISO 13485 credentials. |
| CE Marking Pathway Investment | Accelerates European market access for multicomponent molding systems serving automotive Tier-1 suppliers. |
| Joint Venture for Regional Capacity | Establishes presence in China's Yangtze River Delta cluster with integrated prototyping-to-production capabilities. |
| Long-term Supply Agreement | Secures dedicated allocation of valve-gate nozzles from concentrated German and Japanese component suppliers. |
| Green Manufacturing Transition | Aligns production with ECHA REACH substance restrictions and China's MEE dual-carbon energy-intensity caps. |
Research Methodology
Cross-validation between primary interviews with mold process engineers, procurement leads at automotive Tier-1 suppliers, biomedical engineers at medical device OEMs, and hot-runner component distributors anchors the qualitative findings. Secondary validation draws from SEC filings of precision equipment manufacturers, customs data on injection molding machine trade flows, FDA 510(k) submission databases for multicomponent medical devices, and ECHA substance restriction announcements. Bottom-up capacity modeling across China's Yangtze River Delta manufacturing cluster triangulates with top-down demand segmentation by end-use industry.
Calibration against historical capacity utilization rates and documented qualification timeline compression refines the analytical framework across the projection horizon. Segmentation dimensions include product type configuration, technology architecture, application vertical, and end-user industry procurement sophistication. CAGRs derive from elasticity-adjusted demand modeling incorporating regulatory phase-in schedules and substitution dynamics from liquid silicone rubber processing. Industry-specific forecast inputs span KBA automotive lightweighting mandate enforcement patterns and MFDS medical device regulation evolution in South Korea.
Practitioners should monitor ECHA enforcement intensity on phthalate plasticizers, MEE energy-intensity cap adjustments, and silicone overmolding substitution rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Hand Sealers Market