
 Strapping Devices Market | 2026-2036
Strapping Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Strapping Devices Market Analytics
E-commerce fulfillment centers are collapsing the traditional buyer mix that long favored heavy manufacturing procurement of strapping devices. FROMM Packaging Systems leverages its Swiss engineering heritage to dominate premium automatic installations across European logistics hubs. Mosca GmbH sustains R&D intensity in ultrasonic sealing technologies that reduce material waste per pallet load. Samuel Strapping Systems anchors North American steel strap demand through backward integration into mill-direct supply relationships.
Strapping devices mechanically tension, seal, and cut banding materials around palletized goods or bundled products, typically operating at tension forces between 100 and 2,500 Newtons depending on load specification. Plastic strap formats, particularly polypropylene and polyethylene terephthalate, now lead unit volume due to their corrosion resistance and compatibility with lightweight e-commerce shipments. Automatic strapping technology captures the fastest expansion trajectory as warehouse labor costs rise and throughput requirements tighten, while manual systems retain share in small-batch retail and construction settings where capital budgets constrain automation.
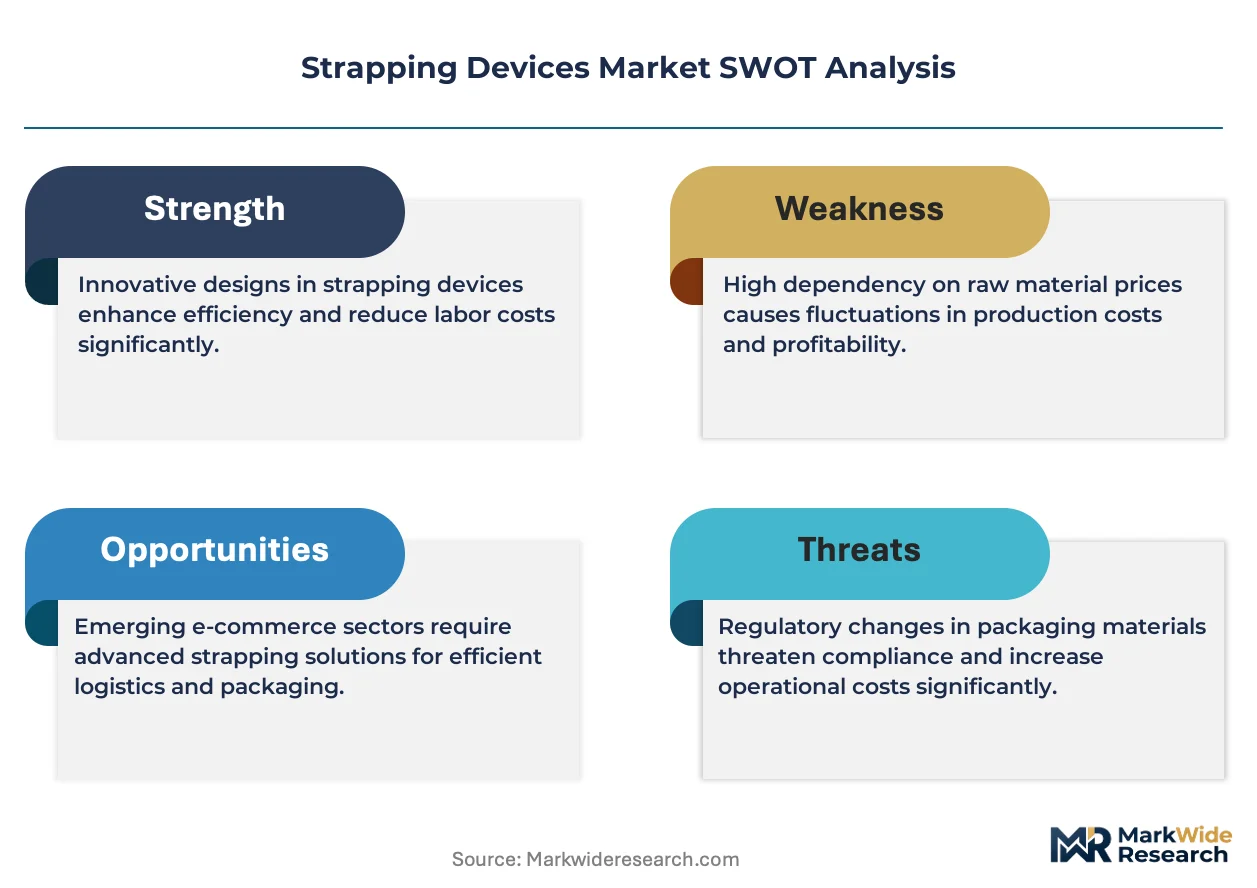
OSHA workplace safety standards in the United States mandate guarding and emergency stop protocols on powered strapping equipment, directly shaping machine design and retrofit demand. The EU Machinery Directive and CE marking requirements enforce electromagnetic compatibility and risk assessment documentation for automatic strapping lines sold across member states. China's GB standards for packaging machinery safety, administered by SAMR, increasingly align with ISO 12100 principles, raising compliance costs for imported equipment. Stakeholders must monitor how divergent regional certification timelines affect product platform standardization and aftermarket parts economics.
Market Dynamics
Warehouse automation mandates from third-party logistics operators are compressing installation timelines for high-throughput strapping lines, forcing equipment vendors to reconfigure service networks around rapid deployment models rather than traditional capital-sales cycles.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding material recovery targets push converters toward reusable strapping formats and closed-loop pallet systems, tightening specification requirements for bundling equipment durability.
- Ultrasonic sealing advancement:Heat-free bonding technology eliminates consumable metal seals and reduces material waste per pallet load, aligning with sustainability procurement criteria in European retail chains.
- China's export manufacturing belt:E-commerce fulfillment center construction concentrates demand for semi-automatic and automatic system deployments across the Yangtze River Delta and Pearl River Delta industrial corridors.
Market Restraints
- Steel price volatility:Mill-direct supply relationships for high-tensile steel strap remain vulnerable to raw material cost swings, compressing margin stability for heavy-industry bundling applications.
- Electromagnetic compatibility certification:EU Machinery Directive CE marking requirements enforce lengthy documentation and testing protocols that delay automatic strapping line launches across member states.
- Stretch film substitution:Cast film wrapping systems displace strapping in lightweight, irregular-load palletization, particularly in fresh produce and consumer goods distribution.
Strategic Opportunities
- India's warehouse automation lag:Organized retail and pharmaceutical cold chain expansion creates first-mover positioning for mid-speed automatic strapping systems in Mumbai, Delhi, and Bangalore logistics corridors.
- Reusable strapping-as-a-service:Equipment-leasing models bundled with polymer strap recycling programs align with EU Green Deal circular economy incentives and CSRD disclosure requirements.
- Machine vision convergence:Integration of tension-force sensors with optical load profiling enables dynamic strap positioning that reduces material consumption per pallet.
Industry Challenges
- ISO 12100 alignment complexity:China's SAMR-administered GB standards for packaging machinery safety are tightening risk assessment documentation requirements, raising engineering overhead for imported equipment platforms.
- Legacy warehouse management system integration:Automatic strapping lines require custom middleware development to synchronize with existing WMS protocols in brownfield distribution centers, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strapping Devices Market |
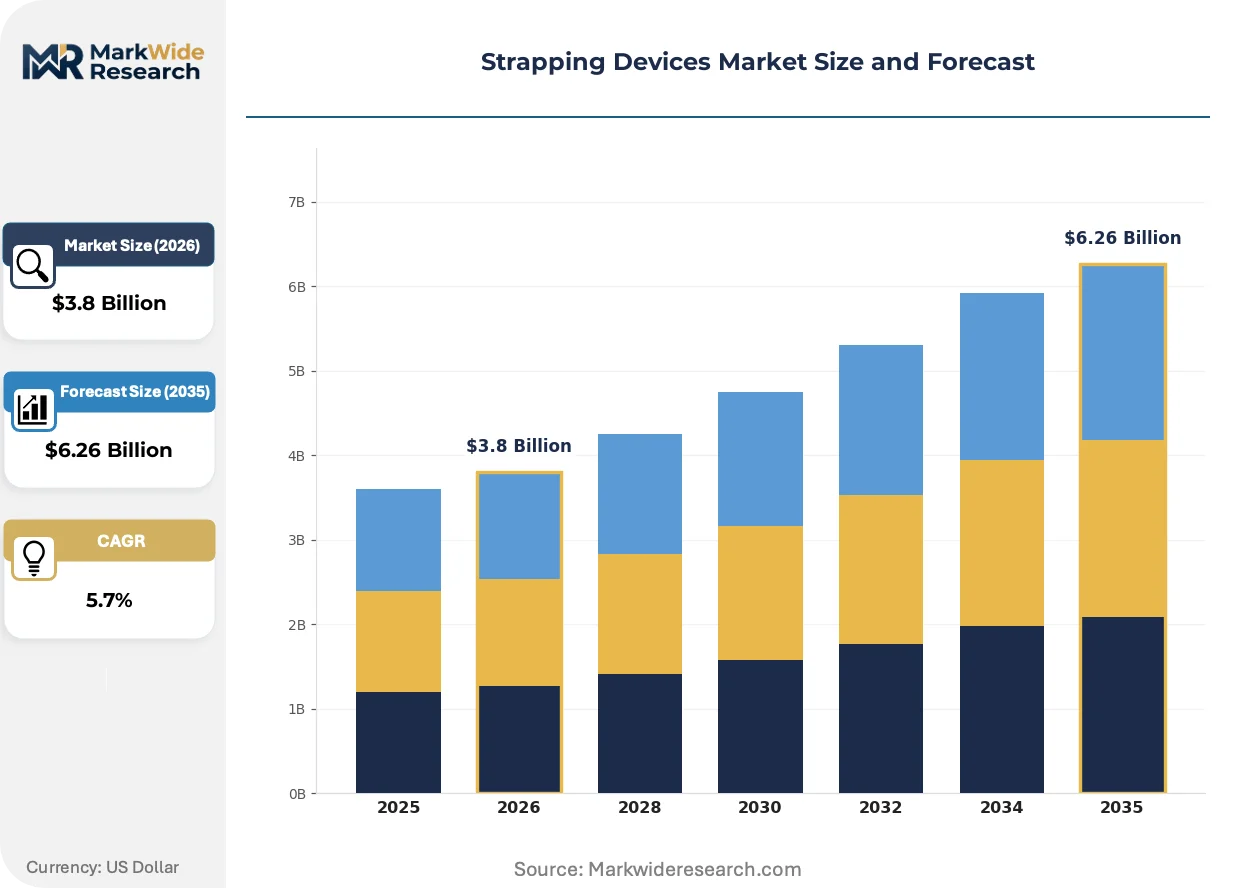
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Straps, Steel Straps, Composite Straps, Electrical Straps End User: Logistics, Manufacturing, Construction, Retail Technology: Manual Strapping, Automatic Strapping, Semi-Automatic Strapping, Pneumatic Strapping Application: Packaging, Bundling, Securing, Unitizing |
| Companies Covered | Signode Industrial Group, FROMM Packaging Systems, Mosca GmbH, StraPack Corp., Dynaric Inc., Transpak Equipment Corp., M.J. Maillis Group, Samuel Strapping Systems, Polychem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strapping Devices Market Evolving Landscape
Battery-powered handheld strapping tools are displacing pneumatic systems in mobile warehousing applications, while regulatory pressure on polymer feedstocks accelerates bio-based strap material qualification programs.
Ultrasonic welding modules for plastic strap formats are miniaturizing to handheld form factors previously dominated by mechanical friction-seal devices. Pharmaceutical distribution centers in Germany and Switzerland are adopting these units for cleanroom-compliant bundling of clinical trial shipments. The technology is compressing the addressable market for seal-consumable aftermarket revenue as heat-free bonding eliminates metal clip inventory.
REACH restrictions on phthalate plasticizers in polymer compounds are forcing strap manufacturers to reformulate polypropylene grades for tensile retention. Converter R&D budgets are redirecting toward bio-based polyester alternatives that maintain elongation characteristics under ISO 16874 testing protocols. European automotive parts suppliers face the tightest compliance timelines as OEM sustainability scorecards penalize non-compliant packaging tiers.
Third-party logistics operators are consolidating equipment procurement through integrated facility management contracts that bundle strapping system maintenance with stretch wrapping and palletizing services. Regional 3PL networks in the Netherlands and Belgium are piloting this model, displacing direct OEM relationships that previously governed aftermarket parts and service revenue. The shift compresses vendor pricing power while extending equipment lifecycle accountability to multi-technology service providers.
Strapping Devices Market Segmentation
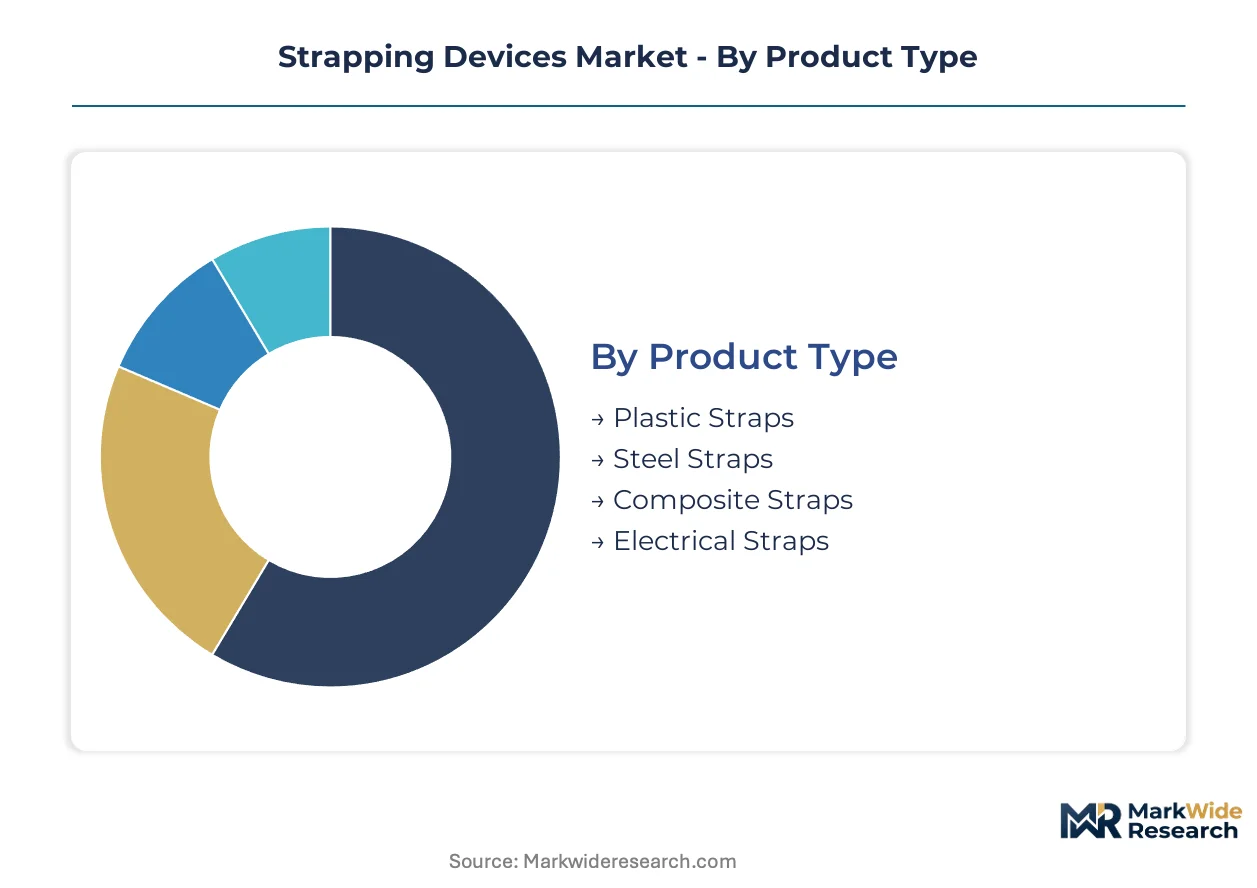
Strapping device procurement patterns diverge sharply across material formats, automation levels, and end-use workflows, with margin capture concentrating in high-tension steel applications and automatic system integration. Understanding these segment boundaries clarifies where specification requirements tighten and where standardization enables volume scaling.
Product Type:
Margin pools concentrate in steel and composite formats where specification engineering and mill-direct supply relationships sustain pricing power against commodity polymer alternatives.
- Plastic Straps:Polypropylene and polyethylene terephthalate formulations dominate unit volume through corrosion resistance and compatibility with lightweight e-commerce shipments. Demand concentrates in China's Yangtze River Delta fulfillment centers, where semi-automatic systems handle high-velocity parcel flows. REACH restrictions on phthalate plasticizers are forcing tensile retention reformulations that raise compound costs.
- Steel Straps:High-tensile carbon steel formats deliver 2,500 Newton tension capacity for heavy manufacturing and construction loads. Mill-direct supply relationships in North America anchor demand from automotive stamping plants and metal coil distributors. Raw material price volatility compresses margin stability during commodity cycles.
- Composite Straps:Woven polyester cord encased in polymer coatings combines flexibility with high break strength for irregular loads.
- Electrical Straps:Insulated polymer formulations with conductive grounding elements serve specialized industrial safety requirements.
The dominant share belongs to Plastic Straps, while Composite Straps are gaining share fastest through substitution in heavy logistics applications.
End User:
Application intensity varies by sector capital cycle timing, with logistics operators currently outspending manufacturing on automation infrastructure.
- Logistics:Third-party operators and e-commerce fulfillment networks drive automatic system deployment. Warehouse automation mandates from Asia-Pacific 3PLs compress installation timelines for high-throughput bundling lines. Integrated facility management contracts in the Netherlands and Belgium are consolidating equipment procurement across multi-technology service bundles.
- Manufacturing:Automotive stamping plants and appliance assembly lines require precision tension control for outbound palletization. OEM sustainability scorecards in European automotive supply chains penalize non-compliant packaging tiers, tightening strap material qualification protocols.
- Construction:Small-batch procurement and mobile site requirements favor manual and battery-powered handheld systems.
- Retail:Store-level backroom operations retain share for light-duty polypropylene bundling of inbound merchandise.
Logistics commands the largest revenue pool, though Manufacturing is expanding most quickly through OEM packaging specification upgrades.
Technology:
Automation intensity determines aftermarket revenue structure, with automatic lines generating service contracts while manual tools rely on consumable replacement cycles.
- Manual Strapping:Hand-held tensioners and sealers serve construction sites and small retail operations where capital budgets constrain mechanization.
- Automatic Strapping:Conveyor-integrated systems with programmable tension control capture premium positioning in high-velocity distribution centers. OSHA guarding mandates and EU Machinery Directive CE marking requirements extend commissioning timelines but lock in long-term service relationships.
- Semi-Automatic Strapping:Operator-fed machines balance throughput with flexibility for mixed-SKU operations in China's export manufacturing belt.
- Pneumatic Strapping:Shop-air-dependent systems face displacement from battery-powered alternatives in mobile warehousing applications.
Automatic Strapping holds the dominant installed base, while Semi-Automatic Strapping is climbing the fastest through mid-market warehouse upgrades.
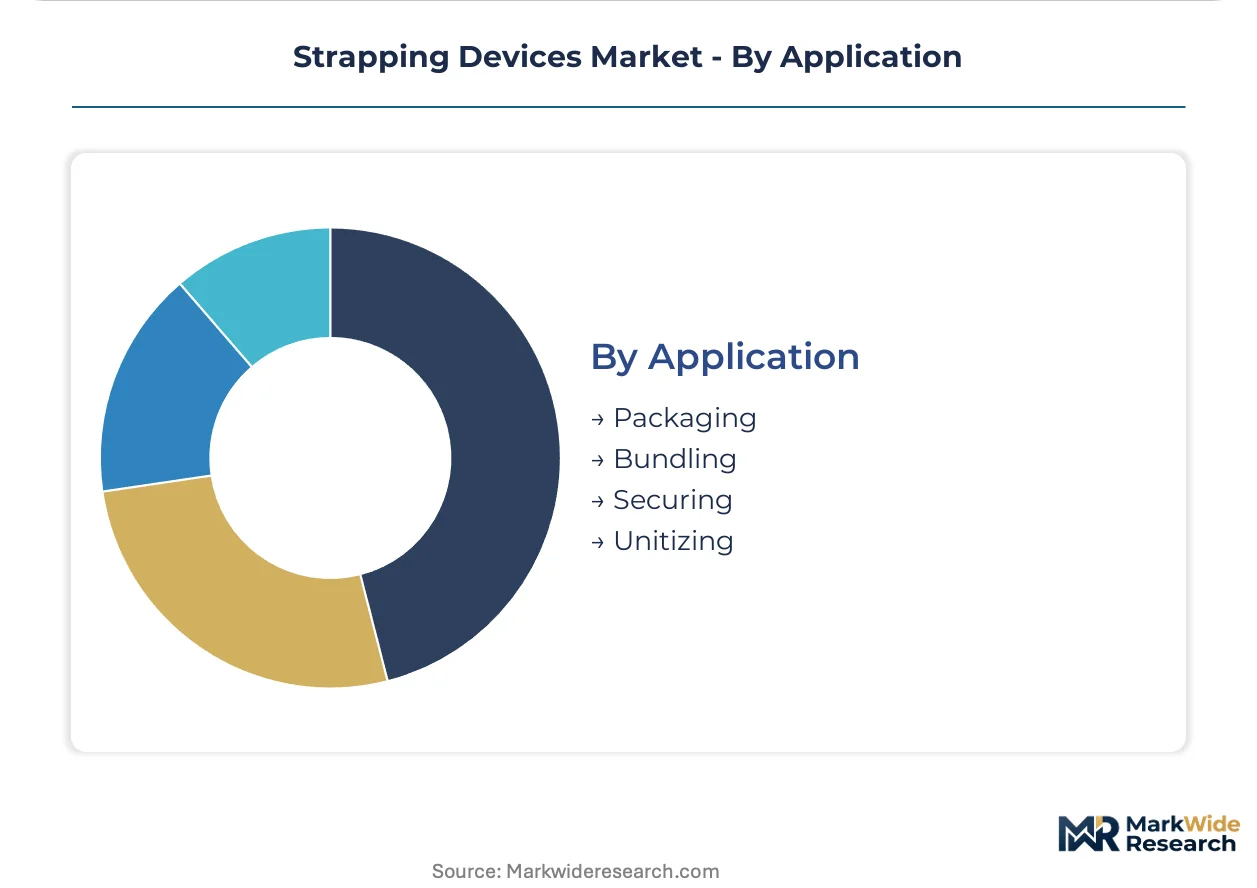
Application:
Functional requirements dictate material selection and tension specification, with securing and unitizing applications demanding higher engineering validation than basic bundling.
- Packaging:Primary and secondary containment for consumer goods distribution. Stretch film substitution threatens share in lightweight, irregular-load palletization for fresh produce.
- Bundling:Aggregation of similar products into handling units, typically at lower tension forces. Retail backrooms and construction material yards drive volume.
- Securing:Load stabilization for transport vibration and shock resistance. Pharmaceutical distribution centers in Germany and Switzerland adopt ultrasonic sealing for cleanroom-compliant clinical trial shipments.
- Unitizing:Pallet-level consolidation with multi-strap patterns for intermodal handling. Machine vision convergence enables dynamic strap positioning that reduces material consumption per pallet.
Packaging retains the broadest addressable footprint, though Unitizing is expanding most quickly through automated warehouse system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites European demand for high-throughput strapping systems, while China's Yangtze River Delta ports anchor Asia-Pacific logistics automation investment.
United States
OSHA workplace safety standards mandate guarding and emergency stop protocols on powered strapping equipment, directly shaping machine design specifications for domestic manufacturers. Third-party logistics operators in the Midwest industrial corridor compress installation timelines for automatic bundling lines. E-commerce fulfillment centers across the Chicago and Dallas logistics hubs drive semi-automatic system deployments for high-velocity parcel flows.
Germany
The EU Machinery Directive and CE marking requirements enforce electromagnetic compatibility documentation for automatic strapping lines sold across member states. REACH restrictions on phthalate plasticizers force polypropylene grade reformulations for tensile retention. Pharmaceutical distribution centers in Stuttgart and Munich adopt ultrasonic sealing modules for cleanroom-compliant clinical trial shipments.
China
GB standards for packaging machinery safety administered by SAMR increasingly align with ISO 12100 principles, raising compliance costs for imported equipment platforms. E-commerce fulfillment center construction concentrates demand across the Yangtze River Delta and Pearl River Delta industrial corridors. Export manufacturing belt warehouses deploy semi-automatic systems to handle high-velocity parcel flows for cross-border trade.
India
Bureau of Indian Standards certification requirements for industrial machinery create procedural delays for foreign equipment vendors entering the market. Organized retail and pharmaceutical cold chain expansion creates first-mover positioning for mid-speed automatic strapping systems. Mumbai, Delhi, and Bangalore logistics corridors drive procurement of battery-powered handheld tools for mobile warehousing applications.
Japan
METI industrial efficiency guidelines promote warehouse automation adoption among small and medium enterprises. JIS standards for packaging machinery safety govern domestic procurement specifications for automatic bundling equipment. Osaka and Nagoya manufacturing clusters sustain demand for precision tension control systems in automotive parts distribution.
Strapping Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and service network coverage. The vendor base spans three structural tiers: premium automatic system integrators, mid-market semi-automatic fabricators, and commodity handheld tool suppliers. Two strategic archetypes dominate competitive positioning: Swiss and German engineering-led specialists commanding premium pricing through precision mechanics, and Asian-scale manufacturers capturing volume through standardized platform economics. M&A activity concentrates in automatic system integration capabilities, while geographic expansion through distributor partnerships accelerates in underpenetrated warehouse automation markets.
Among European engineering-led specialists, FROMM Packaging Systems and Mosca GmbH exemplify the premium-tier archetype through Swiss and German heritage positioning. Samuel Strapping Systems anchors the North American steel strap segment through mill-direct supply relationships. These three entities represent distinct competitive vectors: precision mechanics heritage, ultrasonic sealing technology specialization, and backward integration into raw material sourcing.
| Leading Market Players |
|---|
| Signode Industrial Group |
| FROMM Packaging Systems |
| Mosca GmbH |
| StraPack Corp. |
| Dynaric Inc. |
| Transpak Equipment Corp. |
| M.J. Maillis Group |
| Samuel Strapping Systems |
| Polychem Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day mill-direct lead times for high-tensile steel strap concentrate pricing power among North American producers with captive smelter relationships, while polymer strap converters face margin compression from phthalate reformulation costs under REACH. Equipment vendors respond with service-contract bundling that locks in aftermarket revenue against spot-price volatility in raw materials.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Swiss-engineered automatic systems with ultrasonic sealing modules from mid-market semi-automatic fabricators and commodity handheld tool suppliers. Price differentiation hinges on CE certification grade and after-sales service bundling, with European automotive OEMs showing lowest sensitivity due to sustainability scorecard compliance requirements. Cost compression in the economy tier is intensifying because Asian-scale manufacturers are flooding standardized polypropylene systems into e-commerce fulfillment channels. Small-batch construction buyers exhibit highest price sensitivity, deferring replacement cycles when steel prices spike.
Supply Chain Analysis
Strategic stockpile preferences dominate steel strap procurement, with automotive stamping plants holding 45-60 days of inventory against mill-direct delivery schedules, while polymer strap converters run lean just-in-time programs with Yangtze River Delta compounders. Raw material flows draw from German engineering specialists for precision mechanics, Chinese resin compounders for polypropylene grades, and North American integrated steel mills for high-tensile carbon formats. Single-source vulnerability concentrates in ultrasonic transducer modules sourced from Japanese electronics suppliers. Distribution runs through integrated facility management contracts in Benelux logistics corridors that displace direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated third-party logistics operators in the Netherlands and Belgium, where integrated facility management contracts now govern multi-technology procurement bundles that compress vendor pricing power across automatic strapping lines.
For Market Incumbents: Shield premium positioning by deepening backward integration into polymer compound formulation that satisfies REACH phthalate restrictions without tensile degradation. Prioritize CE marking fast-track capabilities that compress commissioning timelines against EU Machinery Directive documentation requirements. Channel control through exclusive service partnerships with Rotterdam and Hamburg port automation integrators defends margin pools against Asian-scale entrants. For New Entrants and Emerging Players: CE marking fast-track services for mid-speed automatic systems open white-space positioning in India's pharmaceutical cold chain expansion across Mumbai and Bangalore corridors. Battery-powered handheld tools for mobile warehousing applications face lowest competitive density against established pneumatic suppliers. A leasing-plus-recycling service model aligned with EU Green Deal circular economy incentives provides differentiated go-to-market positioning against capital-sales incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automatic system integration capabilities are concentrating among engineering-led specialists while mid-market semi-automatic fabricators face margin pressure from standardized Asian platforms. Acquisition targets with machine vision convergence patents and dynamic strap positioning algorithms capture premium positioning as warehouse labor costs rise. Watch for ultrasonic sealing module miniaturization crossing handheld form-factor thresholds as inflection signal for seal-consumable aftermarket revenue collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive formulation capabilities lock in REACH-compliant tensile retention for European automotive supply chains. |
| Ultrasonic Sealing Module Miniaturization | Handheld heat-free bonding displaces mechanical friction-seal devices in pharmaceutical cleanroom environments. |
| Integrated Facility Management Partnerships | Multi-technology service bundling in Benelux corridors extends equipment lifecycle accountability beyond OEM boundaries. |
| Machine Vision Sensor Integration | Optical load profiling with tension-force sensors reduces material consumption per pallet in automated warehouses. |
| Reusable Strapping-as-a-Service Launch | Equipment-leasing models bundled with polymer recycling align with CSRD disclosure requirements and EU Green Deal incentives. |
Research Methodology
A standing panel of warehouse automation directors, aftermarket service heads at OEMs, procurement leads at third-party logistics operators, and plant engineers at automotive stamping facilities provided ongoing calibration across primary fieldwork. Secondary validation drew from EU Machinery Directive CE marking databases, OSHA workplace safety enforcement records, SAMR GB standards filings, customs trade data for steel and polymer strap flows, and SEC 10-K disclosures from listed packaging equipment manufacturers. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across material format, automation level, and end-use workflow dimensions. The analytical framework modeled plastic versus steel versus composite strap demand, manual versus automatic versus semi-automatic technology penetration, and logistics versus manufacturing versus construction application intensity throughout the forecast period. CAGRs derived from shipment data correlation with warehouse automation capex cycles and e-commerce fulfillment center construction permits.
The analysis sits within stated boundaries; outcomes outside sustained EU Packaging and Packaging Waste Regulation enforcement or abrupt steel price volatility spikes would require recalibration. Forecasts reflect assumptions regarding ultrasonic sealing adoption curves and battery-powered tool displacement timelines. Revision becomes warranted when integrated facility management contract penetration in European logistics corridors crosses threshold levels that fundamentally restructure OEM aftermarket economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Global Shrink Sleeve Applicator Market