
 Gas-Flushing Band Sealing Systems Market | 2026-2036
Gas-Flushing Band Sealing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Gas-Flushing Band Sealing Systems Market Analytics
Consolidation among contract packagers serving private-label food brands is recalibrating procurement patterns for gas-flushing band sealing systems. Ishida Co., Ltd. leverages its weighing-system integration to bundle checkweigher-sealer lines for high-throughput poultry processors. Multivac Sepp Haggenmüller SE & Co. KG anchors its position through backward integration into vacuum pump technology, reducing downstream dependency. Proseal UK Ltd. differentiates via rotary band-sealer designs optimized for trayed produce with delicate respiratory requirements.
Gas-flushing band sealing systems employ heated or unheated sealing bands combined with inert gas injection—typically nitrogen or carbon dioxide mixtures at 95-99.9% purity—to displace oxygen within flexible or semi-rigid packages before hermetic closure. These systems achieve seal integrity thresholds of 0.5-2.0 mm width at conveyor speeds reaching 12 meters per minute, primarily preserving oxidative-sensitive foods and moisture-critical electronics. Automatic sealers occupy the dominant installed base in high-volume meat and dairy operations where throughput exceeds 100 packages per minute, while hybrid pneumatic-electric systems represent the fastest-expanding technology segment as processors seek to reduce compressed-air energy intensity without sacrificing pneumatic precision for gas dosing. Manual sealers retain niche relevance in pharmaceutical compound pharmacies and small-batch chemical laboratories where batch sizes fall below 500 units.
The FDA enforces 21 CFR Part 110 requirements for sanitary equipment design in food-contact sealing systems, while the EPA regulates fugitive emissions from nitrogen and carbon dioxide supply infrastructure under Clean Air Act stationary source provisions. OSHA mandates lockout-tagout integration on automated sealer guarding systems to protect maintenance personnel from thermal and pneumatic hazards. Stakeholders must monitor evolving state-level extended producer responsibility laws that could mandate modular equipment design for end-of-life component recovery.
Market Dynamics
The EU F-Gas Regulation is compressing equipment replacement cycles as processors scramble to retrofit nitrogen and carbon dioxide dosing systems ahead of phasedown deadlines, forcing capital allocation toward compliant sealing architectures.
Growth Catalysts
- Modified atmosphere packaging mandates:The European Union's F-Gas Regulation tightens requirements on fluorinated gas handling, accelerating equipment turnover in German meat and dairy operations.
- Ready-to-eat meal expansion:Industrial kitchens across North American contract packagers are standardizing nitrogen-flush protocols to eliminate chemical preservatives from shelf-stable entrées.
- Hybrid pneumatic-electric architectures:Energy-intensive compressed-air systems are yielding to hybrid drives that cut electricity consumption without sacrificing dosing precision at high throughput.
Market Restraints
- High-purity gas supply concentration:Industrial nitrogen and carbon dioxide sourcing clusters around petrochemical corridor infrastructure, exposing processors to feedstock volatility.
- Precision engineering bottlenecks:Hermetic seal integrity thresholds of 0.5-2.0 mm width demand specialized band materials and thermal control systems with limited qualified suppliers.
- Capital intensity barriers:Automated gas-flushing sealers with integrated checkweighing command substantial upfront investment, constraining adoption among sub-scale compound pharmacies and specialty chemical labs.
Strategic Opportunities
- Electronics moisture protection:Semiconductor and battery component manufacturers are adopting modified atmosphere band sealing for moisture-critical packaging previously handled by vacuum chambers.
- Indian food processing modernization:The country's FSSAI is tightening packaged food shelf-life standards, creating retrofit demand among Mumbai and Delhi-based spice and snack processors.
- Modular equipment-as-service models:Contract packagers are piloting subscription-based sealer deployments with bundled maintenance and gas supply, reducing balance-sheet pressure.
Industry Challenges
- Multi-jurisdiction compliance synchronization:Equipment serving both FDA-regulated US exports and EFSA-governed EU distribution must satisfy divergent sanitary design and emissions protocols simultaneously.
- Legacy line integration complexity:Retrofitting gas-flushing sealers into existing conveyor configurations requires custom guarding and lockout-tagout system redesigns per OSHA mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas-Flushing Band Sealing Systems Market |
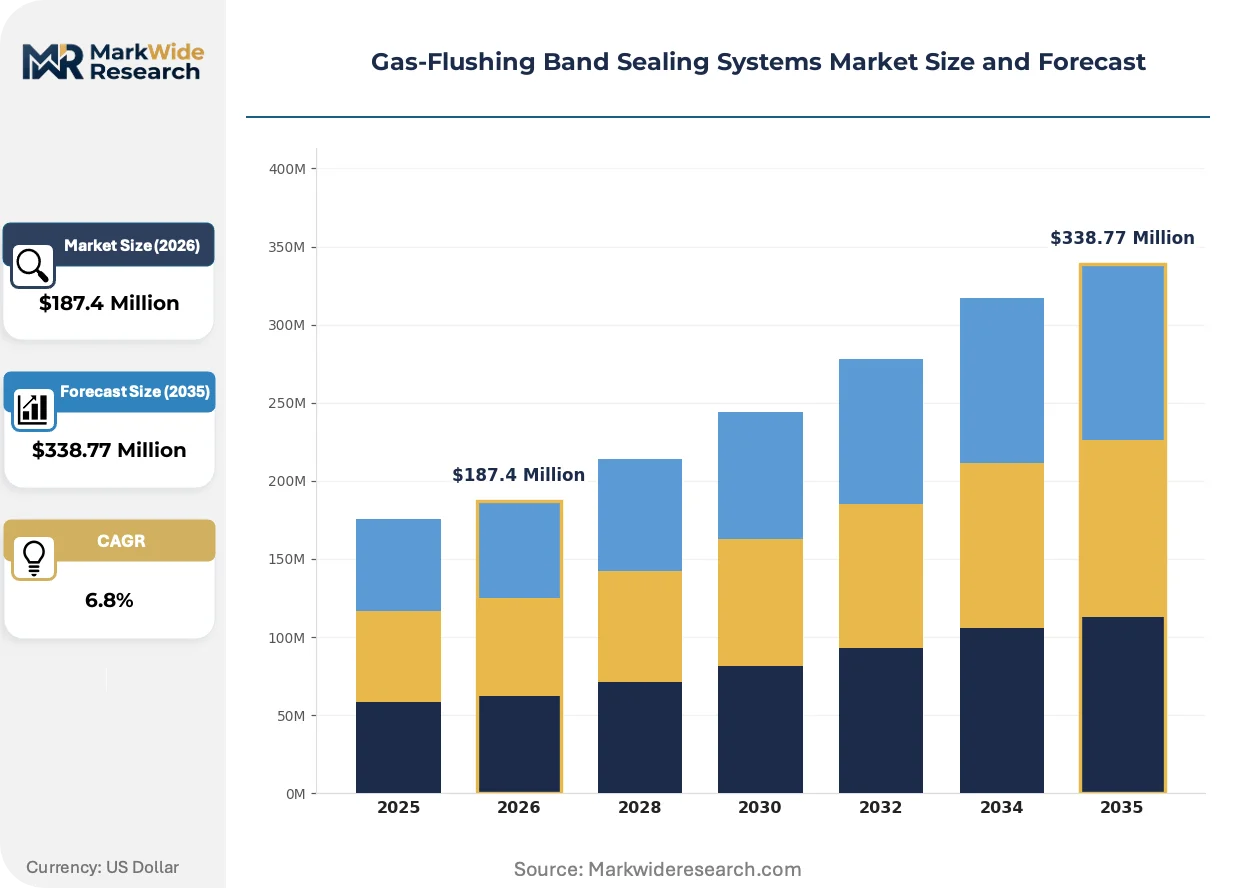
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Sealers, Cold Sealers, Automatic Sealers, Manual Sealers Application: Food Packaging, Pharmaceuticals, Electronics, Chemicals Technology: Pneumatic, Electric, Hybrid, Vacuum End User: Manufacturers, Distributors, Retailers, Contract Packagers |
| Companies Covered | Reiser, Ishida Co., Ltd., Proseal UK Ltd., Polpak Packaging Machines, Harpak-ULMA Packaging, LLC, ULMA Packaging, S.Coop., Multivac Sepp Haggenmüller SE & Co. KG, Mecapack S.A., Bosch Packaging Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas-Flushing Band Sealing Systems Market Evolving Landscape
Equipment architecture is fragmenting into interoperable subsystems as processors demand flexibility to reconfigure lines between nitrogen, carbon dioxide, and mixed-gas protocols without full replacement.
Sealing band technology is modularizing around quick-change heated and unheated cartridge designs that slash format changeover time from hours to minutes. Mid-sized bakeries in the Netherlands and Belgium are adopting these systems to alternate between oxygen-sensitive pastries and standard bread packaging on shared lines. The structural consequence is compressing the premium commanded by dedicated single-purpose sealers.
The EPA's Clean Air Act stationary source provisions are tightening fugitive emissions monitoring requirements for nitrogen and carbon dioxide supply infrastructure. Food processors in California and Texas are installing continuous leak detection systems tied to sealer gas flow controls. High-volume poultry operations face the steepest compliance costs and are consolidating supplier relationships to streamline accountability.
After-sales service unbundling is disrupting traditional capital-equipment sales as buyers separate hardware procurement from maintenance and gas supply contracts. Large meat processors in Germany and the United States are negotiating performance-based service agreements with independent technicians rather than OEM service departments. This shift is most visible in automated sealer deployments exceeding 100 packages per minute where downtime costs dwarf service premiums.
Gas-Flushing Band Sealing Systems Market Segmentation
Segmentation in gas-flushing band sealing systems reveals how capital deployment, regulatory exposure, and throughput requirements reshape procurement patterns across food, pharmaceutical, and electronics verticals. Equipment specifications diverge sharply between high-volume automated lines and precision manual installations.
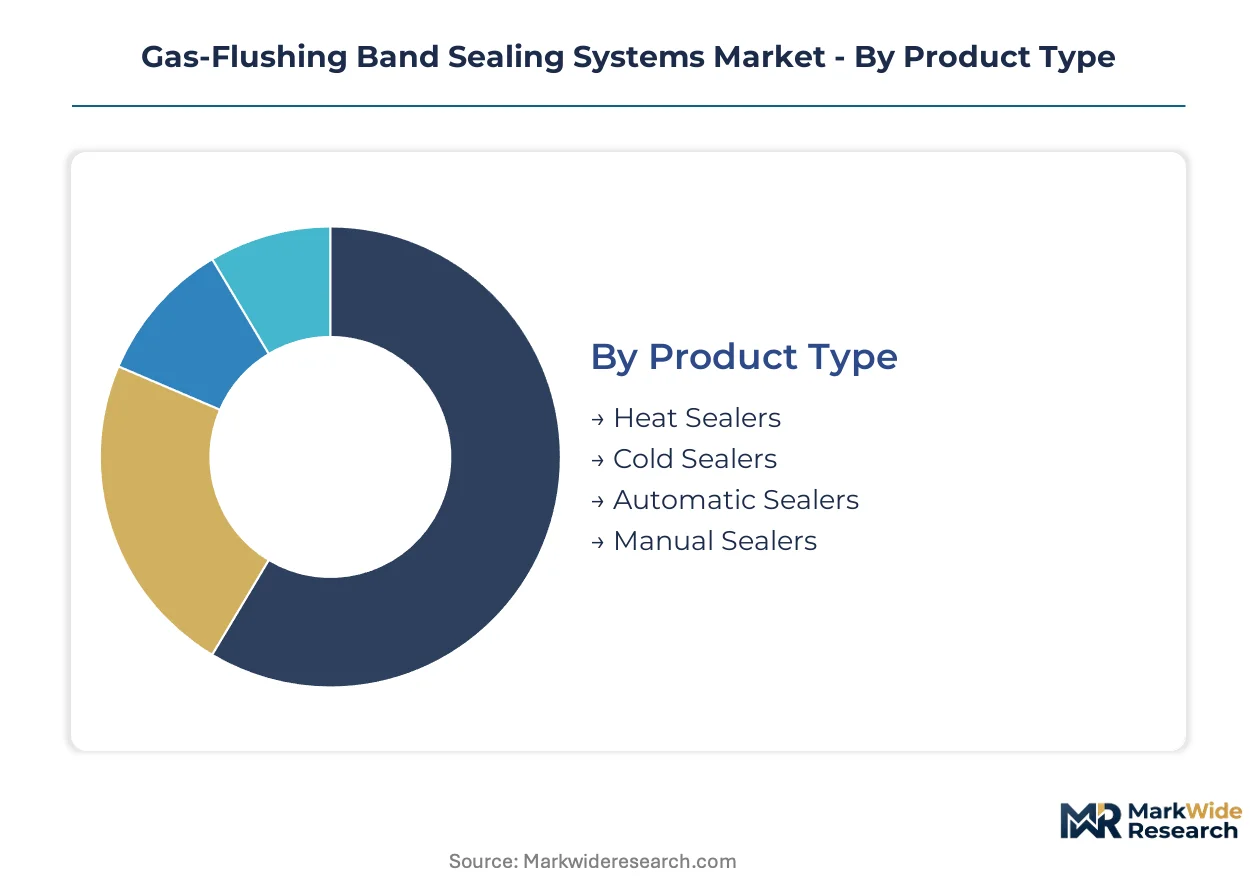
Product Type:
Capital intensity varies dramatically across this category, with automated systems demanding the heaviest upfront investment in integrated gas dosing, thermal control, and conveyor synchronization.
- Heat Sealers:Deploy heated bands operating at 120-200°C to fuse polymer films while nitrogen or carbon dioxide flushes displace oxygen. German meat processors and industrial bakeries dominate installed capacity, driven by EU F-Gas Regulation compliance deadlines forcing equipment turnover.
- Automatic Sealers:Integrate conveyor-fed packaging at throughputs exceeding 100 packages per minute with synchronized gas injection and checkweighing. North American contract packagers standardize these configurations for ready-to-eat meal lines eliminating chemical preservatives.
- Cold Sealers:Employ pressure-sensitive adhesives without thermal activation, serving temperature-sensitive pharmaceuticals and chocolate confectionery where heat degrades product integrity.
- Manual Sealers:Require minimal capital outlay and serve batch sizes below 500 units in compound pharmacies and specialty chemical laboratories.
Most installed capacity flows through Heat Sealers. Expansion is steepest in Automatic Sealers.
Application:
Application segmentation tracks how oxygen sensitivity and moisture criticality determine gas purity requirements and seal integrity specifications across end-use verticals.
- Food Packaging:Modified atmosphere protocols for meat, dairy, and bakery products employ 95-99.9% nitrogen purity to extend shelf life without chemical preservatives. Dutch and Belgian mid-sized bakeries retrofit shared lines for oxygen-sensitive pastries.
- Electronics:Semiconductor and battery component manufacturers adopt band sealing for moisture-critical packaging previously handled by vacuum chambers, driven by miniaturization trends.
- Pharmaceuticals:FDA 21 CFR Part 110 sanitary design requirements govern equipment specifications for drug packaging and compound pharmacy operations.
- Chemicals:Specialty chemical laboratories require hermetic sealing for moisture-sensitive reagents and controlled-atmosphere sample preservation.
Food Packaging commands the dominant revenue share. Electronics is climbing the fastest as semiconductor packaging requirements tighten.
Technology:
Technology segmentation reflects the energy transition in industrial pneumatics, with hybrid architectures displacing compressed-air-dependent legacy systems.
- Hybrid:Combine electric drive precision with pneumatic gas dosing to cut electricity consumption without sacrificing throughput. German poultry processors and U.S. meat operations lead adoption as energy costs escalate.
- Pneumatic:Rely entirely on compressed air for both mechanical motion and gas injection, facing pressure from sustainability mandates and energy intensity audits.
- Electric:Eliminate compressed air dependency through servo-driven band motion and electronic gas flow control, gaining traction in cleanroom pharmaceutical environments.
- Vacuum:Pre-evacuate packages before gas flushing, serving high-value electronics and moisture-critical medical devices requiring sub-atmospheric initial conditions.
Hybrid systems are gaining share fastest from pneumatic baselines. Vacuum technology remains concentrated in premium electronics applications.
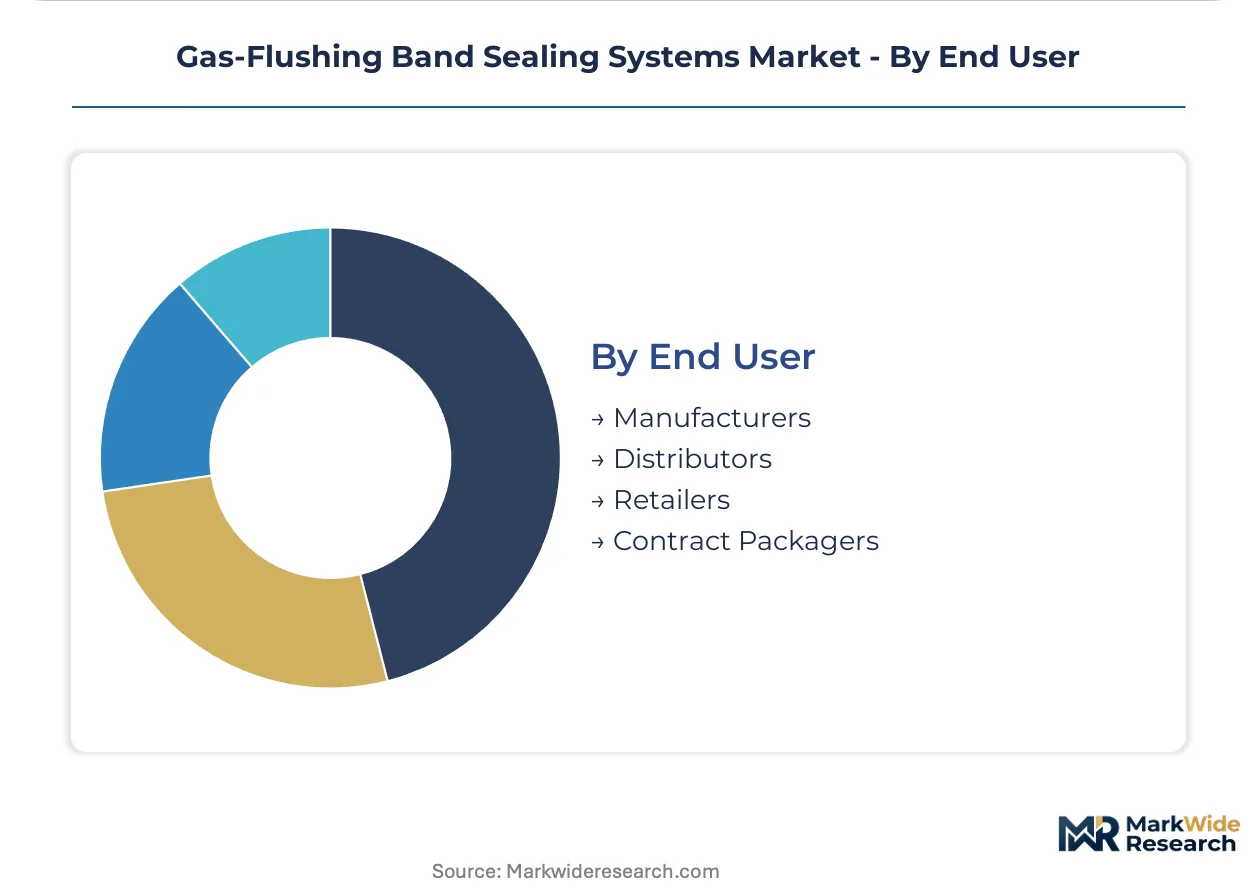
End User:
End user segmentation captures how procurement authority concentrates among integrated manufacturers versus fragmented service providers with diverging capital constraints.
- Contract Packagers:Consolidation among private-label food service providers is recalibrating equipment procurement toward subscription-based deployment models with bundled maintenance and gas supply.
- Manufacturers:Integrated meat, dairy, and electronics producers deploy captive sealing lines with direct OEM relationships and performance-based service agreements.
- Distributors:Intermediate equipment resellers serve smaller regional processors lacking direct technical procurement capabilities.
- Retailers:Private-label brand owners increasingly specify packaging protocols that upstream contract packagers must equipment to meet.
Contract Packagers are reshaping vendor relationships through equipment-as-service pilots. Manufacturers retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in gas-flushing band sealer deployment density, while India accelerates retrofit demand faster than any other Asian market. National regulations and industrial cluster concentration determine equipment procurement timelines across these territories.
United States
North American contract packagers standardize nitrogen-flush protocols for ready-to-eat meal lines. FDA enforces 21 CFR Part 110 sanitary design requirements on food-contact sealing equipment. California poultry processors install continuous leak detection systems tied to sealer gas flow controls per EPA Clean Air Act stationary source provisions.
Germany
Industrial bakeries and meat processors retrofit production lines with automated gas-flushing sealers ahead of EU F-Gas Regulation phasedown deadlines. The regulation compresses equipment replacement cycles for nitrogen and carbon dioxide dosing systems. Bavarian poultry operations consolidate supplier relationships to streamline emissions accountability.
Netherlands
Mid-sized bakeries adopt quick-change heated and unheated cartridge designs to alternate between oxygen-sensitive pastries and standard bread packaging. EFSA governs sanitary protocols for modified atmosphere packaging equipment. Amsterdam and Rotterdam-based processors pilot subscription-based sealer deployments with bundled maintenance contracts.
India
Mumbai and Delhi-based spice and snack processors retrofit lines as FSSAI tightens packaged food shelf-life standards. The national food regulator mandates extended shelf-life protocols without chemical preservatives. Western and Northern India industrial corridors attract hybrid pneumatic-electric sealer imports to reduce compressed-air energy intensity.
Japan
Semiconductor and battery component manufacturers adopt band sealing for moisture-critical electronics packaging. METI oversees industrial equipment energy efficiency standards affecting pneumatic system replacement. Osaka and Nagoya electronics clusters drive demand for hermetic seal integrity below 1.0 mm width specifications.
Gas-Flushing Band Sealing Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Tier-one positions consolidate around integrated packaging technology providers with captive vacuum pump or weighing system capabilities. Tier-two specialists differentiate through rotary band-sealer geometries or quick-change format designs. Tier-three regional fabricators serve price-sensitive emerging markets with standardized pneumatic configurations. Competitive moves concentrate on backward integration into gas flow control components and performance-based service agreement unbundling.
Within the integrated technology tier, Multivac Sepp Haggenmüller SE & Co. KG anchors German-engineered vacuum pump integration, while Ishida Co., Ltd. occupies a position bundling checkweigher-sealer synchronization for high-throughput protein processors. Proseal UK Ltd. exemplifies the specialist archetype with rotary band-sealer configurations. These three entities represent divergent strategic postures: upstream component control, downstream line integration, and format-specific mechanical optimization.
| Leading Market Players |
|---|
| Reiser |
| Ishida Co., Ltd. |
| Proseal UK Ltd. |
| Polpak Packaging Machines |
| Harpak-ULMA Packaging, LLC |
| ULMA Packaging, S.Coop. |
| Multivac Sepp Haggenmüller SE & Co. KG |
| Mecapack S.A. |
| Bosch Packaging Technology |
| Others |
Value Network & Pricing Analysis
Retrofit mandates from the EU F-Gas Regulation are compressing procurement timelines for German meat processors and Dutch bakeries, forcing supply chains to prioritize rapid equipment availability over cost optimization and compressing price negotiation windows for standard pneumatic configurations.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for sealing band materials and thermal control components. Pricing stratifies across premium automated lines with integrated checkweighing, mid-tier hybrid pneumatic-electric systems, and economy manual sealers for batch operations. Cost compression in the economy tier is intensifying because regional fabricators in India and Southeast Asia are flooding price-sensitive segments with standardized pneumatic units. Contract packagers exhibit the highest price sensitivity due to margin pressure from private-label consolidation, while integrated electronics manufacturers show the least sensitivity given moisture-critical packaging requirements.
Supply Chain Analysis
Precision engineering talent shortages in Germany and Japan are constraining output of specialized thermal control systems and hermetic seal components. Manufacturing concentrates in Germany, Japan, and the United States for high-integrity automated sealers, with China and India serving economy manual and semi-automatic segments. Supply chains draw from petrochemical corridor infrastructure for industrial nitrogen and carbon dioxide feedstock, plus specialty polymer film suppliers for sealing band substrates. Single-source vulnerability clusters around vacuum pump technology for pre-evacuation configurations. Distribution runs through OEM direct sales for large integrated processors and regional equipment resellers for mid-sized operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas-flushing band sealing systems market functions as a regulatory compounder where phasedown deadlines under the EU F-Gas Regulation are accelerating capital deployment cycles and rewarding early compliance investment.
For Market Incumbents: Cement market position through backward integration into gas flow control components and vacuum pump technology, reducing dependency on external dosing system suppliers. Prioritize capacity expansion in Germany and the Netherlands to capture compressed replacement cycles driven by EU F-Gas phasedown deadlines. Defend against emerging hybrid-electric specialists by accelerating servo-driven band motion R&D to match energy efficiency gains without sacrificing pneumatic precision for high-purity gas injection. For New Entrants and Emerging Players: Capture white-space opportunity in Indian spice and snack processing corridors where FSSAI shelf-life mandates are creating retrofit demand without entrenched incumbent relationships. Target Mumbai and Delhi-based mid-sized processors lacking direct technical procurement capabilities. Penetrate through equipment-as-service subscription models with bundled maintenance and gas supply contracts, reducing balance-sheet barriers for capital-constrained regional operators. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid pneumatic-electric technology specialists possessing proprietary servo-gas synchronization IP. Long-term viability over the projection horizon favors acquisition targets with captive vacuum pump capabilities or quick-change format modularization patents. Watch for inflection signals in California and Texas poultry operations where EPA Clean Air Act leak detection mandates are consolidating supplier relationships and rewarding integrated emissions-accountability offerings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Pump Technology | Multivac's captive pump production reduces downstream supplier dependency and streamlines emissions accountability for German poultry processors. |
| Hybrid Pneumatic-Electric Architecture Development | Servo-driven precision cuts electricity consumption without sacrificing nitrogen dosing accuracy at throughputs exceeding 100 packages per minute. |
| Quick-Change Cartridge Format Modularization | Dutch and Belgian bakeries slash changeover time from hours to minutes, compressing premiums for dedicated single-purpose sealers. |
| Equipment-as-Service Subscription Launch | Amsterdam-based processors pilot bundled maintenance and gas supply contracts, reducing capital barriers for contract packagers. |
| Continuous Leak Detection System Integration | California poultry operations tie sealer gas flow controls to EPA-mandated monitoring, consolidating supplier relationships for high-volume compliance. |
Research Methodology
Direct dialogue with plant engineers at meat and dairy processors, procurement leads at contract packaging operations, aftermarket service heads at OEMs, and regulatory affairs specialists at gas supply infrastructure providers grounded the qualitative foundation. Secondary validation drew from EU F-Gas Regulation implementation documents, EPA Clean Air Act stationary source enforcement records, FDA 21 CFR Part 110 equipment design guidance, and customs data on sealing machinery trade flows. Bottom-up equipment deployment estimates triangulated against top-down market sizing derived from nitrogen and carbon dioxide consumption patterns in modified atmosphere packaging applications.
Installed base projections across the analysis window reflect segmented modeling by product type, application vertical, technology architecture, and end-user procurement authority. The framework incorporated throughput requirements, regulatory compliance deadlines, and energy cost trajectories as primary demand drivers. CAGRs emerged from logistic curve fitting to equipment replacement cycles and retrofit penetration rates, cross-checked against gas supplier capacity expansion announcements and industrial bakery automation spending patterns.
Underlying measurement precision varies by segment; automated sealer deployments in high-volume meat operations carry tighter precision than fragmented manual sealer demand in compound pharmacies. Forecasts reflect assumptions about EU F-Gas phasedown adherence timelines, industrial electricity cost trajectories, and petrochemical feedstock stability for gas supply infrastructure. Material deviation in regulatory enforcement intensity or hybrid technology adoption curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Labeling Equipment Market