
 HAZMAT Labels Market | 2026-2036
HAZMAT Labels Market Size, Share, and Industry Trends Forecast 2026-2036
HAZMAT Labels Market Foresight
E-commerce fulfillment is hardening as the dominant demand vertical for HAZMAT labels, displacing traditional bulk chemical transport purchasing. Avery Dennison Corporation leverages its adhesive science portfolio to dominate high-performance vinyl substrates for lithium battery shipments. Brady Corporation sustains channel control through its direct safety distribution network spanning industrial MRO procurement. CCL Industries anchors North American supply with specialized printing capacity serving DOT and UN specification packaging.
HAZMAT labels are pressure-sensitive or adhesive-backed markings engineered to withstand temperature extremes from minus forty to plus sixty degrees Celsius, chemical splash exposure, and abrasion during transit, serving the critical function of communicating hazard class, handling precautions, and emergency response information to carriers and first responders. Polyester substrates lead in margin pools due to their superior dimensional stability and solvent resistance in manufacturing environments, while polypropylene is displacing paper in warehouse applications where moisture resistance and tear strength determine compliance longevity. Shipping labels command the largest volume position within label type segmentation, though handling instructions are gaining share as automated sortation systems require machine-readable hazard codes.
The US DOT Pipeline and Hazardous Materials Safety Administration mandates label durability testing under 49 CFR, while the UN Orange Book defines international hazard class specifications that IATA member airlines enforce for air cargo acceptance. OSHA's Hazard Communication Standard drives workplace label demand through its alignment with GHS pictogram requirements, creating overlapping compliance obligations for chemical manufacturers. Stakeholders must monitor evolving lithium battery shipping regulations across modal authorities, as this single hazard class is reshaping substrate specifications and print durability benchmarks faster than any other segment.
Market Dynamics
HAZMAT label demand is hardening around lithium battery compliance mandates as electric vehicle and consumer electronics shipments surge, forcing substrate suppliers to engineer adhesives that withstand thermal runaway conditions without degrading hazard communication legibility.
Growth Catalysts
- 49 CFR Durability Mandates:The US DOT Pipeline and Hazardous Materials Safety Administration now requires labels to survive 30-day immersion and abrasion testing, forcing substrate upgrades across chemical transport packaging.
- E-commerce Parcel Surge:Third-party logistics providers handling lithium batteries for direct-to-consumer electronics are multiplying order volumes for UN 38.3 compliant shipping labels.
- GHS-OSHA Alignment:Workplace chemical container labeling requirements under OSHA's Hazard Communication Standard are extending demand from transport into manufacturing facility inventory management.
Market Restraints
- Petrochemical Input Volatility:Polyester and vinyl substrate production depends on purified terephthalic acid and plasticizer feedstocks whose price swings compress converter margins unpredictably.
- Specialized Adhesive Concentration:High-tack, solvent-resistant acrylic formulations for extreme-temperature labels source from a narrow German and Japanese supplier base.
- Digital Hazard Display Substitution:Electronic logging devices and blockchain-tracked smart packaging threaten to displace physical labels on high-value chemical shipments within regulated fleet operations.
Strategic Opportunities
- India Pharmaceutical Cold Chain:CDSCO export documentation requirements for temperature-sensitive biologics are creating demand for dual-indicator labels combining hazard class with thermal excursion alerts.
- EU Battery Passport Integration:The EU Green Deal's forthcoming digital product passport mandates will require QR-embedded HAZMAT labels linking to full chemical composition databases.
- RFID-NFC Convergence:Passive RFID inlays combined with printed antenna structures are enabling automated sortation systems to read hazard class without line-of-sight barcode scanning.
Industry Challenges
- Multimodal Certification Complexity:Labels must simultaneously satisfy 49 CFR road transport, IATA DGR air cargo, and IMDG Code maritime testing protocols, extending qualification timelines.
- Legacy Print Infrastructure:Many chemical manufacturers operate thermal transfer printers incompatible with newer synthetic substrates requiring adjusted heat settings and ribbon formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HAZMAT Labels Market |
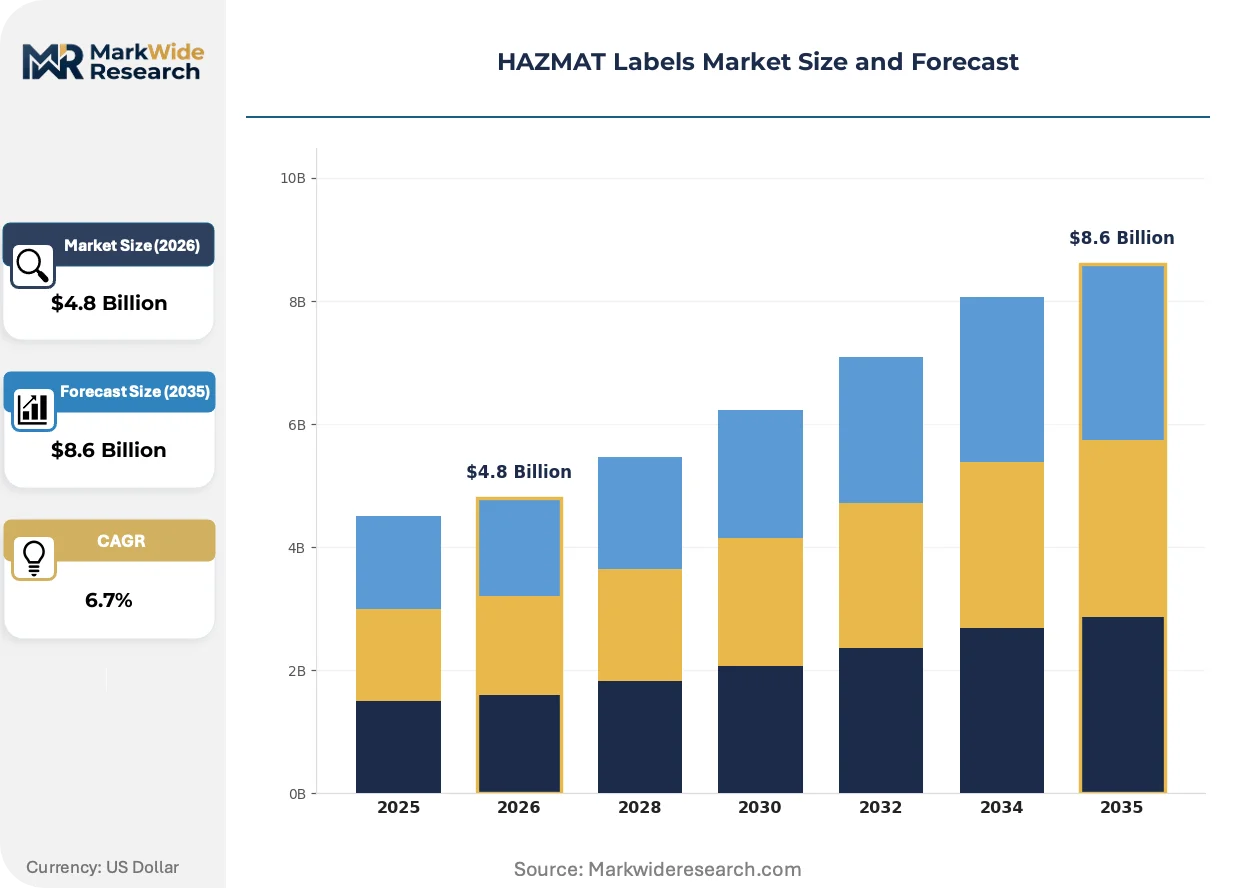
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Shipping, Warning, Handling, Storage Material: Paper, Polypropylene, Vinyl, Polyester Application: Transport, Warehouse, Manufacturing, Emergency Response Compliance Standard: DOT, IATA, OSHA, UN |
| Companies Covered | Labelmaster Services, Emedco, Brady Corporation, Avery Dennison Corporation, J.Keller & Associates, Brimar Industries, 3M Company, CCL Industries, Uline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HAZMAT Labels Market Shifts & Advancements
Active technological deployment is compressing label lifecycles while regulatory fragmentation across transport modes is multiplying specification variants. Material science advances and digital integration are converging to redefine substrate performance benchmarks.
Near-field communication (NFC) chips embedded in pressure-sensitive labels are expanding into pharmaceutical cold chain monitoring, enabling real-time temperature logging alongside static hazard warnings. Biologics distributors in Germany and the Netherlands are piloting these dual-function labels for gene therapy shipments. The technology is expanding into customs pre-clearance workflows by transmitting UN number and emergency response data directly to border inspection handhelds.
REACH authorization list expansion is restricting certain phthalate plasticizers previously standard in flexible vinyl label formulations, compelling converters to reformulate with bio-based alternatives. The industrial consequence is elevated raw material qualification costs and extended stability testing periods. Battery manufacturers exporting from China to Europe are most affected, as SAMR domestic standards have not yet aligned with ECHA substance restrictions, forcing dual inventory strategies.
Consolidated procurement by mega-carriers is displacing fragmented buyer relationships that historically characterized chemical label purchasing. DHL Supply Chain and FedEx Freight are now specifying their own substrate durability tiers, bypassing traditional converter-distributor channels. This concentration is most visible in North American cross-border chemical transport, where carrier-mandated label specifications override shipper preferences and compress supplier margins through volume-commitment contracting.
HAZMAT Labels Market Segmentation
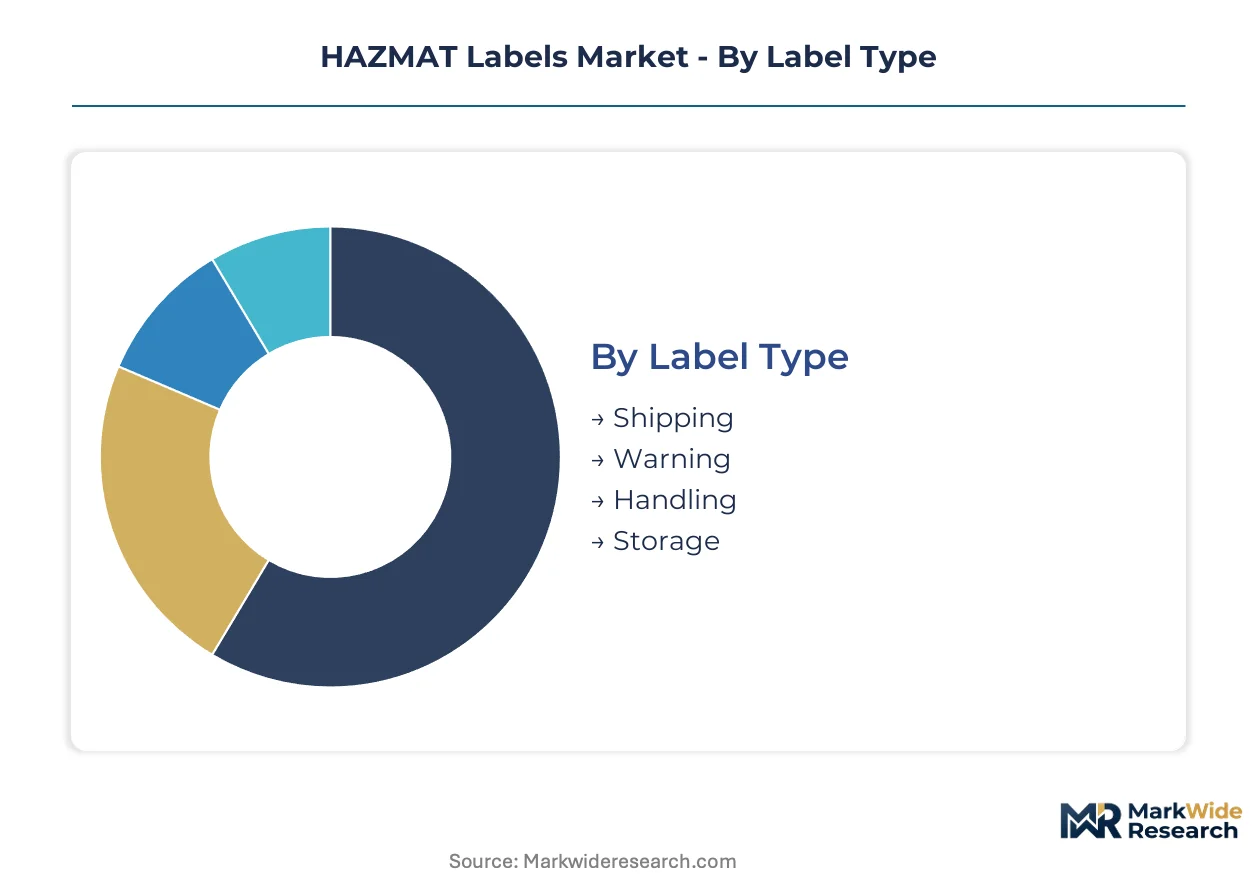
HAZMAT label segmentation reveals how substrate chemistry and regulatory scope determine procurement patterns. Chemical manufacturers, logistics providers, and safety officers each prioritize different performance thresholds across these four dimensions.
Label Type:
Customization intensity varies sharply across this category, with standardized shipping formats dominating volume while specialized handling variants command specification premiums.
- Shipping:UN specification labels for air, road, and maritime cargo constitute the highest volume position. E-commerce fulfillment centers handling lithium battery direct-to-consumer shipments are intensifying demand for 49 CFR and IATA DGR compliant formats as parcel volumes surge.
- Warning:GHS pictogram labels communicate hazard class through standardized diamond formats. OSHA's Hazard Communication Standard alignment with GHS is extending demand from transport containers into manufacturing facility chemical inventory management systems.
- Handling:Instructional markings for temperature limits, orientation, and stacking restrictions serve automated sortation systems. These labels are gaining share as machine-readable hazard codes become mandatory for warehouse robotics integration.
- Storage:Segregation and compatibility labels for warehouse racking and containment areas.
Most installed capacity flows through Shipping. Expansion is steepest in Handling.
Material:
Cost tiers separate commodity substrates from engineered synthetics, with performance premiums widening as durability mandates tighten.
- Polyester:Dimensionally stable films with superior solvent resistance and thermal performance from minus forty to plus sixty degrees Celsius. Germany's chemical manufacturing corridor around Ludwigshafen and Leverkusen concentrates demand for polyester in batch process environments where chemical splash exposure is routine.
- Vinyl:Flexible PVC formulations optimized for conformability on curved drum and cylinder surfaces. REACH authorization list expansion is restricting phthalate plasticizers, compelling converters to reformulate with bio-based alternatives and elevating raw material qualification costs.
- Polypropylene:Moisture-resistant films displacing paper in warehouse applications where tear strength determines compliance longevity.
- Paper:Lowest-cost substrate for short-duration transport and indoor manufacturing use where environmental exposure is minimal.
Polyester captures the highest margin pool. Polypropylene is climbing the fastest as warehouse automation spreads.
Application:
Customer type determines specification complexity, with transport carriers imposing the most stringent multimodal certification requirements.
- Transport:Labels for road, air, rail, and maritime cargo packaging must survive 30-day immersion and abrasion testing under 49 CFR. DHL Supply Chain and FedEx Freight are now specifying their own substrate durability tiers, bypassing traditional converter-distributor channels.
- Warehouse:Inventory location, segregation, and handling instruction labels for distribution centers. RFID-NFC convergence is enabling automated sortation systems to read hazard class without line-of-sight barcode scanning.
- Manufacturing:Workplace chemical container labels under OSHA's Hazard Communication Standard. GHS-OSHA alignment is creating overlapping compliance obligations that extend demand from transport into facility inventory management.
- Emergency Response:First responder notification labels with UN numbers and emergency contact data.
Transport absorbs the largest specification engineering resources. Warehouse is gaining share fastest as e-commerce fulfillment scales.
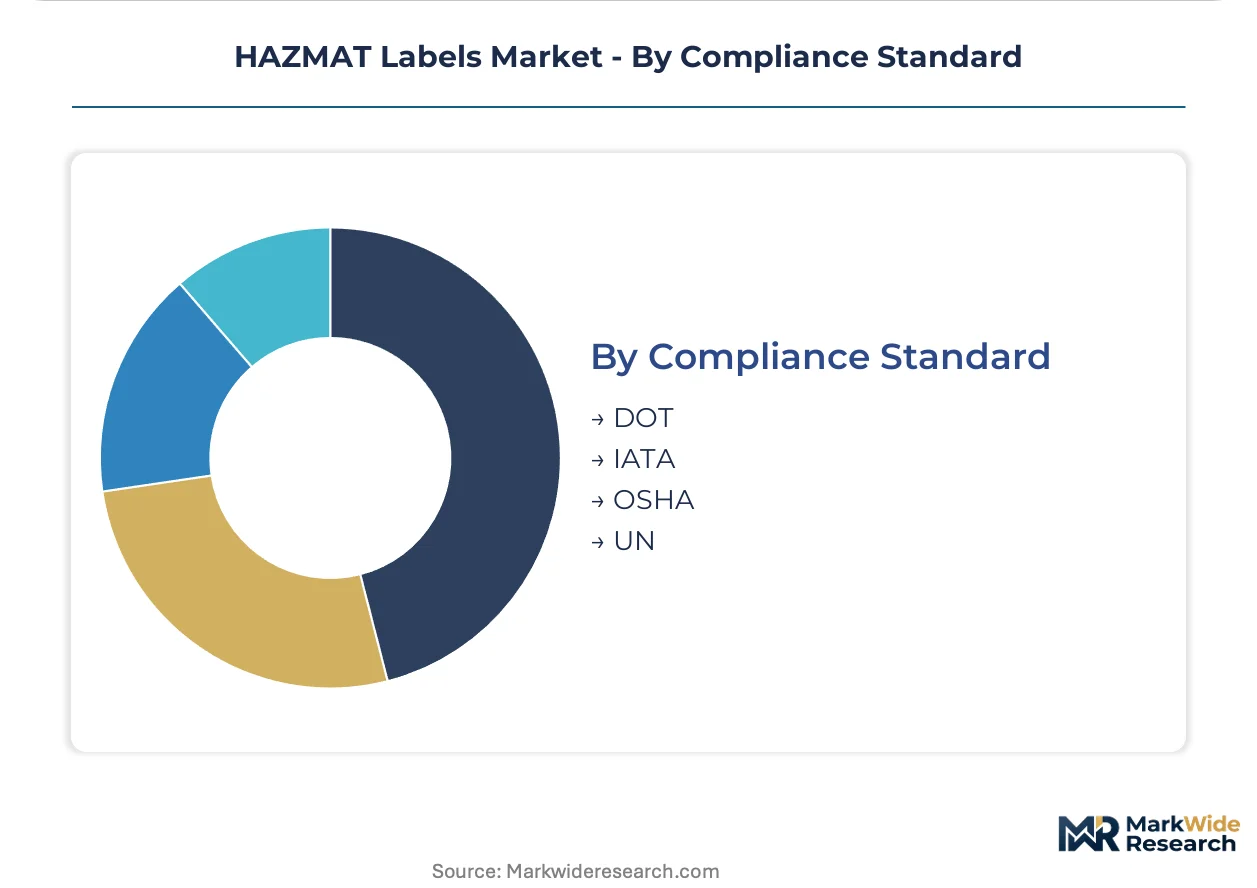
Compliance Standard:
Geographic enforcement scope fragments this category, with overlapping mandates multiplying qualification timelines for multinational chemical shippers.
- DOT:49 CFR mandates from the Pipeline and Hazardous Materials Safety Administration govern road, rail, and domestic air transport within the United States. Updated rules are tightening substrate durability requirements and forcing converter upgrades.
- IATA:Dangerous Goods Regulations for international air cargo acceptance. Lithium battery shipping regulations across modal authorities are reshaping substrate specifications and print durability benchmarks faster than any other segment.
- OSHA:Hazard Communication Standard drives workplace label demand through GHS pictogram alignment.
- UN:Orange Book hazard class specifications for international multimodal harmonization.
DOT certification covers the largest addressable market. IATA specifications are expanding most quickly as air cargo volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen and Leverkusen anchor chemical manufacturing demand for high-performance polyester substrates, with Germany's industrial corridor setting durability benchmarks that ripple through adjacent European markets. Substrate specifications from this cluster influence converter engineering decisions across multiple jurisdictions.
United States
Third-party logistics providers handling lithium battery direct-to-consumer shipments are intensifying order volumes for UN 38.3 compliant formats. OSHA's Hazard Communication Standard alignment with GHS extends demand from transport containers into manufacturing facility chemical inventory management. The Gulf Coast petrochemical corridor around Houston concentrates vinyl substrate production for drum labeling applications.
Germany
REACH authorization list expansion restricts phthalate plasticizers previously standard in flexible vinyl formulations, compelling converters to reformulate with bio-based alternatives. ECHA substance restrictions force dual inventory strategies for battery manufacturers exporting to Europe from non-aligned regulatory jurisdictions. The Rhine-Neckar metropolitan region surrounding Ludwigshafen maintains dense converter capacity serving batch process environments.
China
SAMR domestic standards have not yet aligned with ECHA restrictions, creating regulatory friction for exporters serving European markets. NMPA pharmaceutical export documentation requirements for temperature-sensitive biologics are creating demand for dual-indicator labels. The Yangtze River Delta manufacturing belt concentrates electronics fulfillment centers multiplying parcel volumes for compliant shipping labels.
India
CDSCO export documentation requirements for temperature-sensitive biologics are creating demand for dual-indicator labels combining hazard class with thermal excursion alerts. The country's national pharmaceutical regulator is tightening cold chain compliance as biologics exports expand. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune is piloting NFC-embedded labels for gene therapy shipments.
Netherlands
Biologics distributors are piloting NFC-embedded pressure-sensitive labels for gene therapy shipments, expanding the technology into pharmaceutical cold chain monitoring. The country's national pharmaceutical regulator enforces strict documentation standards for temperature-sensitive exports. The Randstad logistics cluster around Rotterdam and Amsterdam serves as the primary European distribution hub for compliant label procurement.
HAZMAT Labels Market Competitive Landscape
Capacity expansion dominates the current landscape as substrate suppliers engineer adhesives that withstand thermal runaway conditions without degrading hazard communication legibility. The vendor base separates into three tiers: multinational adhesive science portfolios, specialized safety distribution networks, and regional converter operations serving single-modal certification requirements. Two strategic archetypes have emerged: integrated materials-converter operations controlling substrate formulation through captive supply, and pure-play distributors leveraging channel relationships with industrial MRO procurement. M&A activity concentrates on adhesive technology acquisitions, while geographic expansion targets Indian pharmaceutical cold chain and EU battery passport integration opportunities.
Among North American materials specialists, Avery Dennison Corporation and CCL Industries occupy positions within the integrated substrate-converter tier, with the former representing adhesive science capabilities and the latter anchoring specialized printing capacity for DOT and UN specification packaging. Brady Corporation exemplifies the safety distribution archetype, sitting within a channel control model spanning industrial MRO procurement. These three entities represent the dominant competitive positioning vectors: materials integration, regulatory certification depth, and direct distribution reach.
| Leading Market Players |
|---|
| Labelmaster Services |
| Emedco |
| Brady Corporation |
| Avery Dennison Corporation |
| J.Keller & Associates |
| Brimar Industries |
| 3M Company |
| CCL Industries |
| Uline |
| Others |
Supply & Pricing Matrix
REACH authorization list expansion gates both qualified supply and premium-tier pricing access, compelling converters to reformulate vinyl substrates with bio-based plasticizers and elevating raw material qualification costs that filter through to end-user pricing. Battery manufacturers exporting from China to Europe now face dual inventory strategies that compress margins on non-compliant stock while opening premium capture for REACH-certified supply.
Pricing Analysis
Distributor margin layers separate converter pricing from end-user procurement, with direct safety distribution networks commanding 15-25 point markups over mill-direct relationships. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—DOT-IATA dual-certified labels capture 40% premiums over single-modal formats. Cost compression in standard-grade polyester substrates is intensifying because mega-carrier consolidated procurement bypasses traditional channel intermediaries. Third-party logistics providers demonstrate highest price sensitivity, while pharmaceutical cold chain buyers accept premium positioning for thermal excursion dual-indicator functionality.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from DHL Supply Chain and FedEx Freight, who now specify proprietary substrate durability tiers that override shipper preferences. Geographic supply concentrates in Germany's Rhine-Neckar chemical corridor, China's Yangtze River Delta electronics belt, and the US Gulf Coast petrochemical cluster around Houston. Raw material dependencies rest on purified terephthalic acid for polyester films, plasticizer feedstocks for vinyl formulations, and high-tack acrylic adhesives from narrow German and Japanese supplier bases. Single-source vulnerability in specialized adhesive chemistry creates chokepoint exposure. Distribution runs through converter-distributor networks for fragmented chemical manufacturers, while carrier-direct procurement is displacing traditional channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in HAZMAT labels rest on substrate premiumization toward lithium battery thermal runaway specifications and operational cost-down through adhesive formulation consolidation. REACH compliance investments function as both defensive moat and pricing power amplifier.
For Market Incumbents: Anchor substrate formulation control through captive adhesive science capabilities, locking in thermal performance specifications that emerging competitors cannot replicate without extended qualification timelines. Defend against carrier procurement concentration by embedding RFID-NFC convergence into premium label tiers, creating switching costs through automated sortation system integration. Prioritize certification depth investment across multimodal DOT-IATA-IMDG protocols. For New Entrants and Emerging Players: The price-point gap between premium polyester and economy paper substrates creates entry space for polypropylene specialists serving warehouse automation demand. Target India's pharmaceutical cold chain as the most penetrable geography, where CDSCO documentation requirements for temperature-sensitive biologics outpace local converter capacity. Pursue gene therapy NFC-embedded pilot programs with Maharashtra distributors as the go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional converter operations because multimodal certification complexity fragments the vendor base and extends qualification timelines that deter new entrants. Long-term viability centers on adhesive technology acquisitions that consolidate formulation IP. Watch lithium battery shipping regulation harmonization across modal authorities as the inflection signal—convergence accelerates substrate specification standardization and favors scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Science Acquisition | Captures thermal runaway formulation IP that Brady Corporation and Avery Dennison currently dominate. |
| EU Battery Passport Integration | Positions converters for QR-embedded label mandates under EU Green Deal digital product passport requirements. |
| India Pharmaceutical Cold Chain Entry | Addresses CDSCO export documentation gaps for temperature-sensitive biologics with dual-indicator label capacity. |
| RFID-NFC Convergence Development | Enables automated sortation systems at DHL Supply Chain and FedEx Freight to read hazard class without line-of-sight scanning. |
| REACH-Compliant Vinyl Reformulation | Secures premium-tier pricing access for European battery manufacturers facing ECHA phthalate restrictions. |
Research Methodology
Direct dialogue with converter operations managers, chemical manufacturer procurement leads, third-party logistics compliance officers, and adhesive R&D directors grounded qualitative findings, cross-referenced with customs trade data, DOT PHMSA regulatory filings, SEC 10-K disclosures from listed materials companies, and IATA dangerous goods incident reports. Bottom-up and top-down triangulation validated volume estimates against substrate consumption patterns and label application frequencies across transport modes.
Bottom-up modeling projected segment-level demand through the analysis window, disaggregating by label type, substrate material, application environment, and compliance standard jurisdiction. Top-down validation anchored aggregate market size to chemical transport volume indices and e-commerce parcel growth trajectories. CAGRs derived from regression analysis against historical regulatory mandate implementation timelines and substrate substitution elasticities. Lithium battery shipment density and cold chain biologics export volumes served as industry-specific forecast inputs.
Caveats apply where regulatory harmonization delays, petrochemical feedstock volatility, or digital hazard display substitution could materially shift the outlook. Forecasts embed assumptions regarding REACH authorization list expansion pace and SAMR-ECHA alignment timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Waterproof and Weatherproof Label Market
Labels
Global Automotive Labels Market
Labels
Fiber Optic Labels Market
Labels
Global QR Code Labels Market
Labels
BOPP Labels Market
Labels
GCC Labeling Market
Labels
Ripeness Indicator Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Domed Labels Market
Labels
Barcode Label Printer Market
Labels
Extended Text Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
APAC on-Demand Color Labels Market
Labels
Global Thermal Transfer Label Market
Labels
Repositionable Labels Market