
 Auger Filler Market | 2026-2036
Auger Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Auger Filler Market Outlook
Preventive maintenance contracts and IoT-enabled remote diagnostics is shifting how auger filler vendors capture lifetime value from installed equipment. PER-FIL Industries leverages its vertical integration into precision auger fabrication to sustain margin control across replacement part cycles. AMS Filling Systems anchors its competitive position through North American service density, while All-Fill Inc. differentiates via pharmaceutical-grade validation documentation.
An auger filler is a volumetric dispensing machine that uses a rotating helical screw within a cylindrical hopper to meter dry powders, granules, or semi-viscous materials into containers with fill accuracies typically ranging from ±0.5% to ±2% by weight. The device operates through controlled rotation of the auger, where pitch geometry and rotational speed determine dispensed volume, serving primary applications in food packaging, pharmaceutical tablet counting, and chemical batching. Fully automatic fillers command the largest installed base due to throughput requirements in high-volume snack and beverage powder operations, though multi-head fillers represent the fastest-expanding category as cosmetics brands pursue parallel dosing for color-matched mineral formulations. Digital technology segments attract premium pricing from pharmaceutical end users requiring audit-trail compliance and real-time weight feedback integration.
FDA cGMP guidelines and EMA Annex 15 validation requirements shape auger filler specifications through mandatory IQ/OQ/PQ documentation and material contact surface certifications. REACH compliance in Europe and USDA dairy equipment standards in the United States further constrain material selection and clean-in-place protocol design. Equipment buyers must weigh total cost of ownership against regulatory audit readiness when evaluating pneumatic versus electric drive architectures.
Market Dynamics
Serialization mandates from FDA and EMA are forcing pharmaceutical contract manufacturers to replace legacy volumetric fillers with validated auger systems capable of generating complete audit trails for every powder dose dispensed.
Growth Catalysts
- EMA Annex 15 Validation:European pharmaceutical manufacturers must maintain IQ/OQ/PQ documentation for all powder dosing equipment, creating mandatory replacement cycles for non-validated legacy machines.
- Dairy Protein Powder Expansion:Nutritional supplement brands in India and China are installing multi-head auger fillers to achieve parallel dosing throughput for whey and plant protein blends.
- IoT-Enabled Predictive Maintenance:Remote diagnostics platforms allow vendors to capture recurring revenue through service contracts while reducing unplanned downtime for high-volume snack packaging operations.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L contact surface requirements expose equipment manufacturers to nickel and molybdenum price swings that compress margin on standard-configuration machines.
- German Precision Component Concentration:High-tolerance auger fabrication depends on a concentrated supplier base in Baden-Württemberg, creating geographic single-point-of-failure risk for global OEMs.
- Clean-in-Place Protocol Complexity:USDA dairy equipment standards mandate 3A-certified surface finishes that extend validation timelines and inflate engineering costs for food-grade system variants.
Strategic Opportunities
- Brazilian Pharmaceutical Localization:ANVISA's tightening GMP enforcement creates replacement demand for imported auger fillers as domestic contract manufacturers seek validated local supply chains.
- Cosmetic Mineral Formulation Parallel Dosing:Color-matched powder blending for mineral makeup requires multi-head configurations that command premium pricing from beauty brands pursuing SKU proliferation.
- REACH-Compliant Material Substitution:ECHA restrictions on certain surface coatings push auger vendors toward plasma-nitrided steel alternatives that differentiate European-market offerings.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of servo-driven auger controls with real-time weight feedback requires controls engineers with rare cross-training in pneumatics and pharmaceutical validation protocols.
- Legacy Pneumatic Retrofit Complexity:Food manufacturers with installed bases of air-driven fillers face disruptive production downtime when converting to electric architectures required for precise powder dosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auger Filler Market |
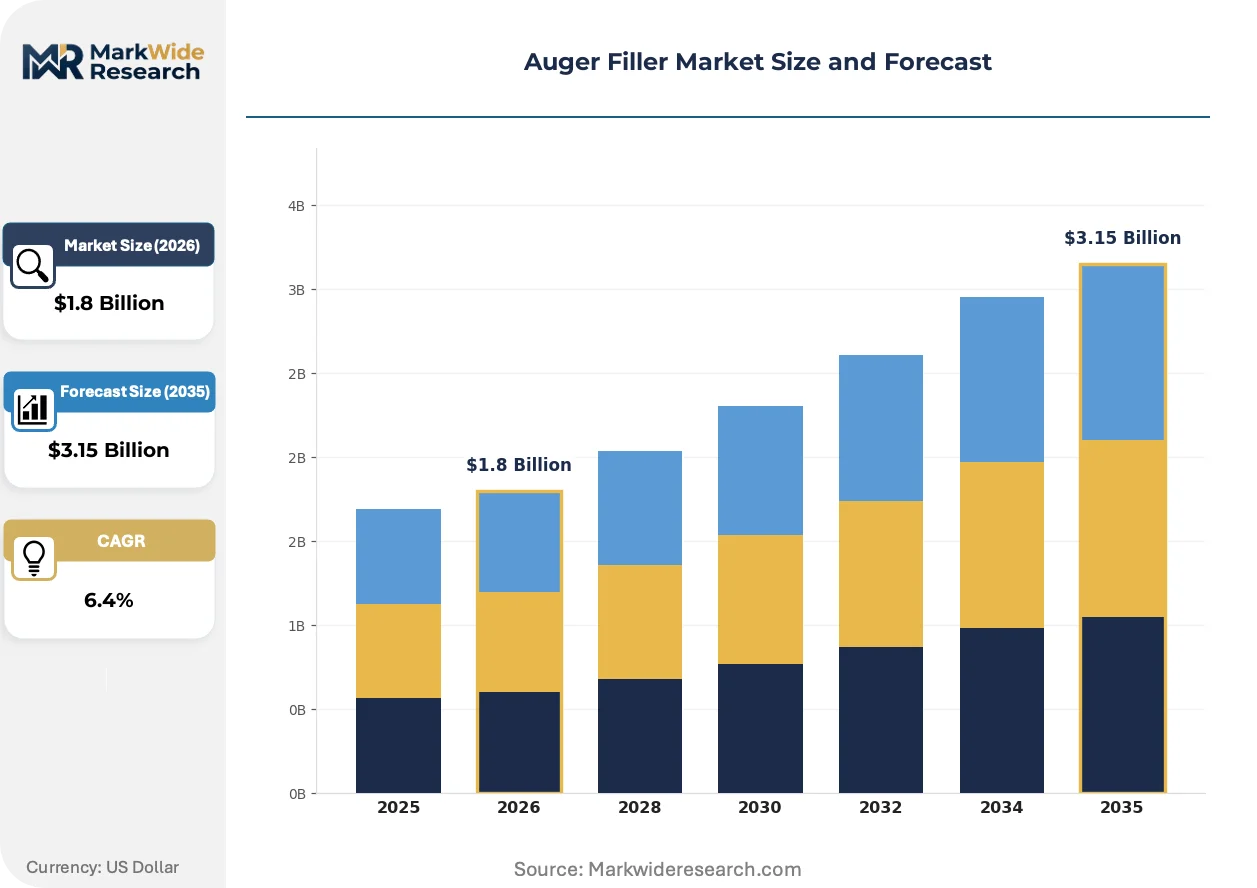
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Fillers, Semi-Automatic Fillers, Fully Automatic Fillers, Multi-Head Fillers End User: Food & Beverages, Pharmaceuticals, Cosmetics, Chemicals Application: Powders, Granules, Pastes, Liquids Technology: Digital, Pneumatic, Electric, Mechanical |
| Companies Covered | PER-FIL Industries, AMS Filling Systems, Inc., Accutek Packaging Equipment Company, Inc., VTOPS, Sanko Machinery Co., Ltd, All-Fill Inc., Spee-Dee Packaging Machinery, Inc., Allpack, Busch Machinery, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auger Filler Market Strategic Shifts
Digital weight feedback loops and servo-electric drive architectures are compressing the performance gap between pharmaceutical-grade and food-grade auger systems, forcing vendors to recalibrate tiered product strategies.
Closed-loop gravimetric feedback is unifying fill accuracy across powder density variations by replacing timed auger rotation with load-cell-verified dispense cycles. Nutritional supplement packagers in the United States are adopting these systems fastest, with dairy protein operations now specifying real-time weight correction as standard rather than optional. This convergence is unifying what were previously separate premium and standard equipment categories into a single accuracy tier.
REACH authorization requirements for chrome-plated tooling are compelling European auger manufacturers to accelerate plasma surface treatment adoption. The regulation's sunset dates for hexavalent chromium processes force capital allocation toward vacuum deposition equipment. Pharmaceutical OEMs serving EMA-regulated markets are responding by pre-qualifying alternative surface finishes ahead of mandatory compliance deadlines.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete remote monitoring, spare part subscription, and on-site technical service components. Contract manufacturers in Germany are selecting vendors based on granular service menu flexibility rather than bundled annual contracts. This behavioral shift is most pronounced among mid-scale pharmaceutical packagers seeking to match service spend to actual utilization patterns rather than fixed capacity assumptions.
Auger Filler Market Segmentation
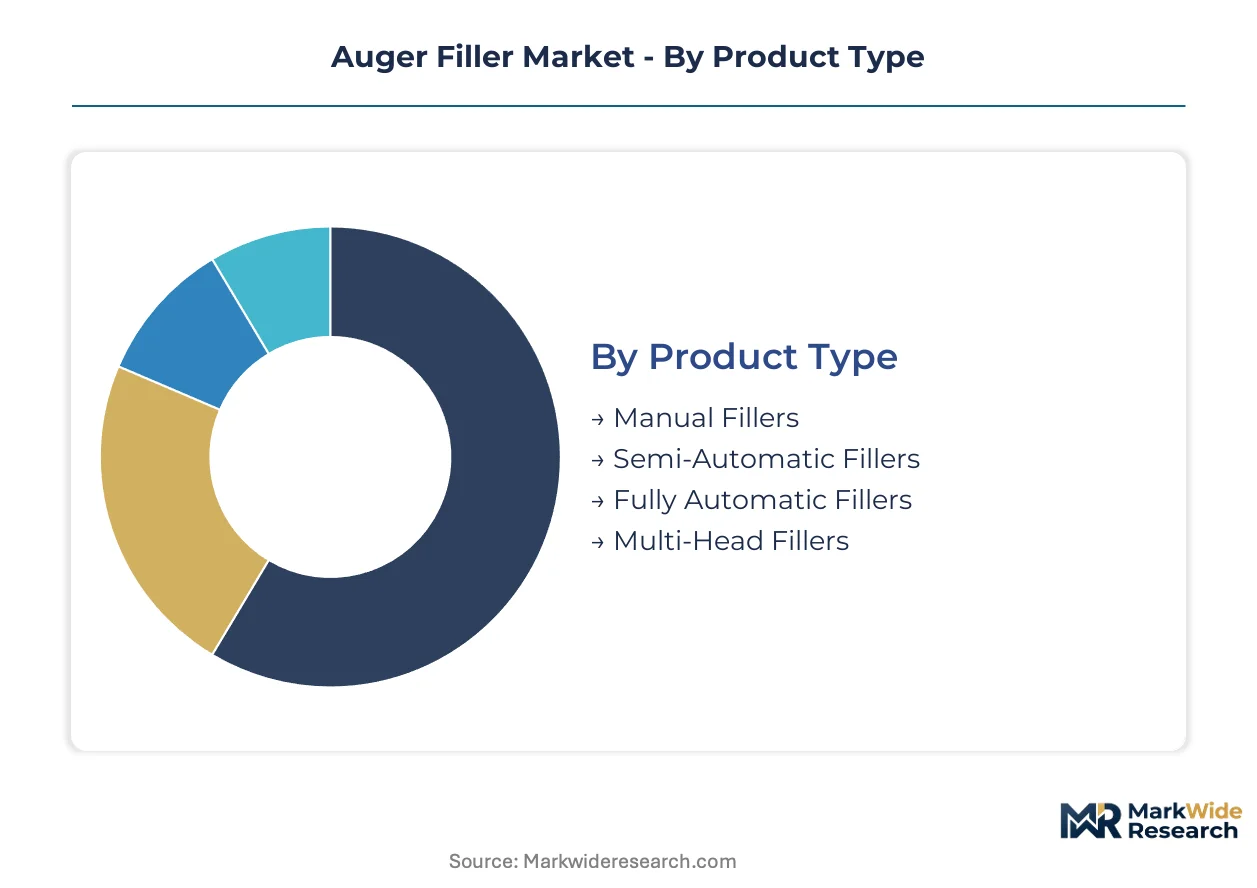
Auger filler procurement decisions pivot on throughput requirements, regulatory validation burdens, and powder characteristics. Buyers segment equipment selection by automation level, end-use compliance intensity, material rheology, and drive architecture precision.
Product Type:
Capital expenditure thresholds and labor cost structures determine automation tier selection across packaging operations.
- Fully Automatic Fillers:Continuous-motion rotary designs integrate with high-speed snack and beverage powder lines. Dairy protein operations in India and China specify these systems for whey isolate packaging at throughputs exceeding 120 containers per minute.
- Multi-Head Fillers:Parallel dosing configurations employ 4-16 independent auger stations for simultaneous filling. Color-matched mineral cosmetics brands deploy these for SKU proliferation in compact powder formulations.
- Semi-Automatic Fillers:Operator-assisted indexing suits mid-scale contract manufacturers balancing flexibility with capital constraints.
- Manual Fillers:Hand-crank or foot-pedal actuation persists in artisanal spice packaging and small-batch nutraceutical startups.
Fully Automatic Fillers lead on scale; Multi-Head Fillers lead on momentum.
End User:
Regulatory audit frequency and material contact surface standards create divergent specification requirements across industries.
- Pharmaceuticals:FDA cGMP and EMA Annex 15 mandates require IQ/OQ/PQ documentation, 316L stainless contact surfaces, and complete batch audit trails. Contract manufacturers in Germany and the United States are replacing legacy volumetric systems to meet serialization requirements.
- Food & Beverages:USDA 3A sanitary standards and FSSAI dairy equipment codes govern clean-in-place protocol design. Nutritional supplement brands specify real-time weight feedback for protein powder dosing accuracy.
- Cosmetics:Mineral makeup and loose powder formulations drive demand for dust-containment and color-change rapid cleaning features.
- Chemicals:Abrasive granules and corrosive powders necessitate hardened auger flights and exotic alloy contact surfaces.
Food & Beverages dominates installed base volume; Pharmaceuticals commands premium pricing per unit.
Application:
Material flow properties dictate auger geometry, hopper design, and fill verification methodology.
- Powders:Free-flowing and cohesive powder rheologies require differentiated flight pitch and core shaft configurations. Pharmaceutical tablet dust and nutritional protein isolates represent the largest addressable volume.
- Granules:Irregular particle shapes and density variations challenge volumetric consistency. Snack seasoning and agricultural chemical operations specify gravimetric feedback integration.
- Pastes:Semi-viscous materials demand modified auger designs with reduced pitch and increased torque transmission.
- Liquids:Limited applicability for standard auger mechanisms; specialized positive-displacement variants serve niche viscous fluid applications.
Powders anchor revenue concentration; Granules exhibits steepest technology upgrade intensity.
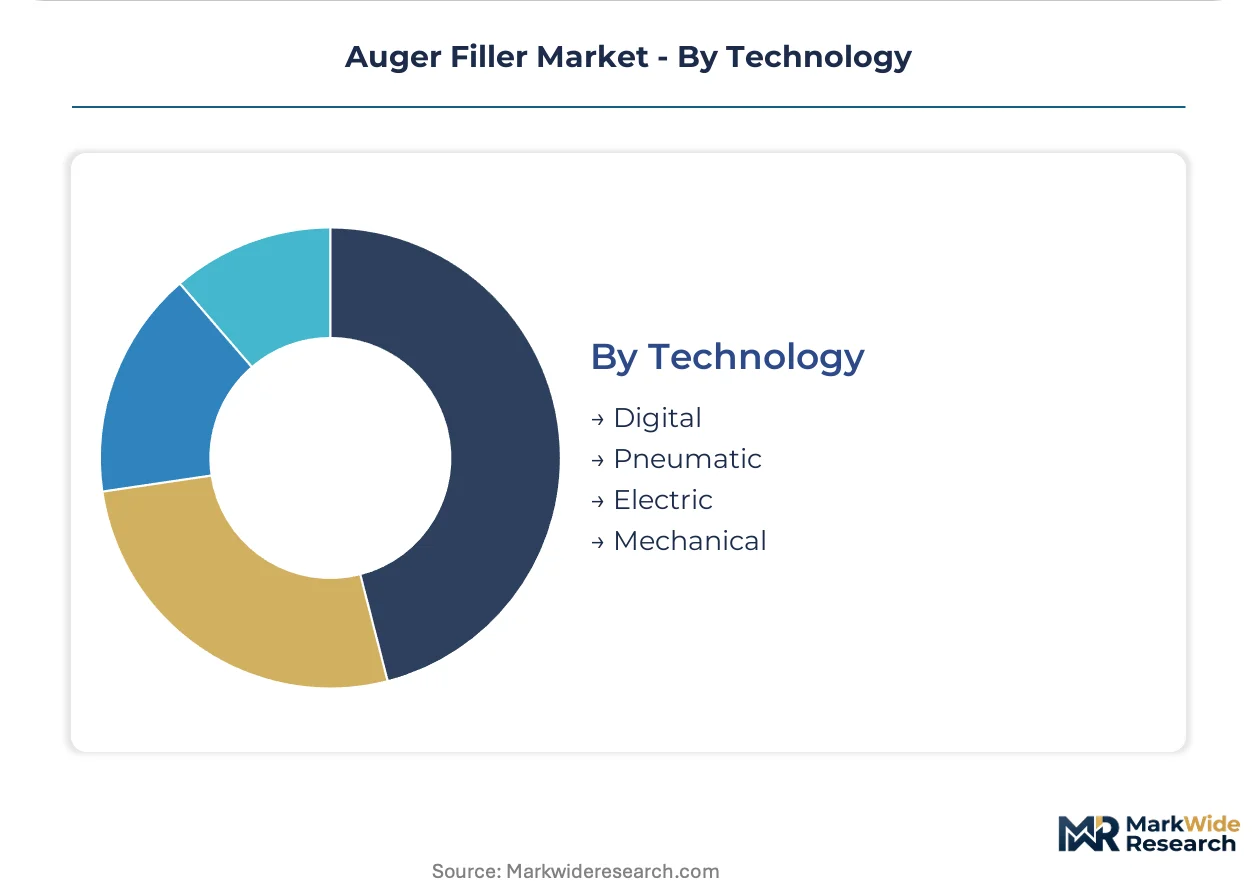
Technology:
Drive architecture selection balances initial capital outlay against long-term precision and energy efficiency.
- Electric:Servo-driven auger controls enable closed-loop gravimetric feedback with fill accuracy to ±0.5%. Pharmaceutical packagers specify electric architectures for real-time weight correction and audit trail generation.
- Digital:IoT-enabled platforms integrate remote diagnostics, predictive maintenance algorithms, and cloud-based performance monitoring. Vendors capture recurring service revenue through subscription telemetry contracts.
- Pneumatic:Compressed air actuation persists in legacy food installations but faces displacement where precision requirements tighten.
- Mechanical:Gear-driven and cam-actuated designs retain cost advantage in emerging markets with limited technical service infrastructure.
Electric systems dominate new pharmaceutical procurement; Digital platforms are climbing the fastest as vendors unbundle service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States drive pharmaceutical-grade auger filler procurement through divergent regulatory pathways, while India and China concentrate demand for high-throughput dairy protein systems.
United States
FDA serialization mandates and cGMP enforcement are accelerating replacement cycles for legacy volumetric equipment among contract manufacturers. The agency's Drug Supply Chain Security Act implementation timelines force validated IQ/OQ/PQ documentation for all powder dosing operations. New Jersey and Pennsylvania pharmaceutical packaging corridors are absorbing multi-head electric auger systems at rates outpacing national averages.
Germany
EMA Annex 15 validation requirements and REACH surface coating restrictions are reshaping equipment specifications for domestic and export-oriented manufacturers. Baden-Württemberg's precision machining clusters supply high-tolerance auger fabrication components to global OEMs. Stuttgart-area system integrators are pre-qualifying plasma-nitrided steel alternatives ahead of hexavalent chromium sunset dates.
China
Dairy protein powder expansion and nutritional supplement SKU proliferation are driving multi-head auger filler installations across domestic packaging lines. NMPA medical device classification rules for powder dosing equipment are tightening validation documentation requirements for pharmaceutical applications. Yangtze River Delta contract manufacturers are specifying real-time weight feedback integration as standard configuration.
India
FSSAI dairy equipment codes and PLI scheme incentives for food processing machinery are converging to accelerate automated filler adoption. Whey isolate and plant protein blend packagers in Gujarat and Maharashtra are specifying throughputs exceeding 120 containers per minute. Mumbai-Pune pharmaceutical corridors are importing validated electric architectures to meet CDSCO inspection readiness standards.
Brazil
ANVISA GMP enforcement tightening is generating replacement demand for non-validated legacy volumetric systems among domestic contract manufacturers. São Paulo state pharmaceutical packaging clusters are seeking localized supply chains for validated auger fillers to reduce import dependency. Campinas and Osasco industrial zones are absorbing European and North American equipment with modified Portuguese-language documentation packages.
Auger Filler Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical validation capabilities commanding premium positioning while food-grade volume players compete on throughput economics. The vendor base concentrates around three strategic archetypes: precision component fabricators with captive auger production, North American service-density operators, and pharmaceutical-grade documentation specialists. Consolidation pressure is intensifying through backward integration into precision machining and geographic expansion into Brazilian and Indian pharmaceutical corridors.
Among North American service-density operators, PER-FIL Industries and AMS Filling Systems, Inc. exemplify divergent margin capture strategies. PER-FIL's in-house production of precision auger components anchors its replacement part revenue streams across equipment lifecycles. AMS Filling Systems occupies a position defined by regional technical service density rather than vertical manufacturing scope. All-Fill Inc. represents the pharmaceutical-grade documentation archetype, with validation protocol packages that satisfy FDA and EMA audit requirements.
| Leading Market Players |
|---|
| PER-FIL Industries |
| AMS Filling Systems, Inc. |
| Accutek Packaging Equipment Company, Inc. |
| VTOPS |
| Sanko Machinery Co., Ltd |
| All-Fill Inc. |
| Spee-Dee Packaging Machinery, Inc. |
| Allpack |
| Busch Machinery, Inc. |
| Others |
Value Chain & Pricing Dynamics
Nickel and molybdenum price indices on the London Metal Exchange cascade through Grade 316L stainless steel procurement into three distinct equipment pricing tiers, with pharmaceutical-grade validation packages commanding substantial premiums over standard food-grade configurations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-configuration multi-head auger fillers, compressing margins on economy-tier equipment. Three-tier pricing structure across premium, standard, and economy levels differentiates by validation documentation intensity and drive architecture precision. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are absorbing stainless steel volatility through volume scale. Contract manufacturers in India's pharmaceutical corridors exhibit highest price sensitivity, while German EMA-regulated buyers prioritize audit-readiness over unit cost.
Supply Chain Analysis
Brazil's ANVISA domestic-content mandates for pharmaceutical equipment are reshaping sourcing patterns among São Paulo-state contract manufacturers seeking validated local supply chains. High-tolerance auger fabrication draws from concentrated precision machining clusters in Germany's Baden-Württemberg region, with secondary supply nodes in Japan and the United States. Nickel and molybdenum commodity exposure creates margin vulnerability when stainless steel input costs spike. Distribution runs through direct OEM sales for pharmaceutical validation packages and regional distributor networks for food-grade volume equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA Drug Supply Chain Security Act implementation timelines forcing replacement cycles that insulate demand from cyclical downturns.
For Market Incumbents: To counter margin compression from Chinese capacity additions in standard-configuration equipment, incumbents should deepen backward integration into precision auger fabrication to capture replacement part revenue streams, while expanding service density in Brazil's ANVISA-tightening corridors to lock in switching costs. For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical-grade and economy food-grade auger fillers creates white-space opportunity in mid-tier electric architectures for India's nutritional supplement packagers. Target semi-automatic configurations for Gujarat and Maharashtra whey isolate operations, with go-to-market through regional system integrators offering localized FSSAI compliance support. For Investors and Strategic Acquirers: Asymmetric upside sits with precision component fabricators possessing captive auger production and established pharmaceutical validation protocols. Five-to-ten year viability hinges on regulatory serialization mandates persisting across FDA and EMA jurisdictions. Acquisition focus should center on European vendors with plasma-nitrided steel surface treatment capabilities ahead of REACH hexavalent chromium sunset dates. The signal to watch is CDSCO inspection readiness standards tightening in India's Mumbai-Pune corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Auger Fabrication | Captures recurring replacement part revenue across equipment lifecycles for PER-FIL Industries and similar specialists. |
| Plasma-Nitrided Steel Surface Treatment Pre-Qualification | Positions European vendors ahead of ECHA hexavalent chromium restrictions in REACH authorization timelines. |
| Service Contract Unbundling into Discrete Components | Matches German mid-scale pharmaceutical packager demand for utilization-aligned spend rather than fixed annual contracts. |
| Brazilian Pharmaceutical Localization Partnerships | Reduces ANVISA-regulated contract manufacturer import dependency while capturing GMP enforcement-driven replacement demand. |
| Real-Time Weight Feedback Integration as Standard Configuration | Compresses the premium-standard equipment gap as nutritional supplement packagers specify closed-loop gravimetric systems. |
Study Parameters
Multiple input streams — primary interviews with equipment procurement managers at pharmaceutical contract manufacturers, technical discussions with aftermarket service heads, and regulatory affairs consultations — were reconciled against secondary validation from FDA cGMP guidance documents, EMA Annex 15 validation protocols, and stainless steel commodity trade data. Bottom-up triangulation across installed base estimates and top-down cross-checks against capital expenditure disclosures from nutritional supplement brands anchored volume and value outputs.
Data-stream reconciliation across the projection horizon employed segmentation by automation tier, end-use regulatory intensity, drive architecture precision, and powder rheology category. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate implementation schedules. Forecast inputs incorporated NMPA medical device classification timelines in China and PLI scheme incentive trajectories for Indian food processing machinery.
The model assumes a particular technology adoption path; alternative pathways for servo-electric drive displacement of legacy pneumatic architectures would alter the outlook for retrofit versus greenfield procurement splits. Forecasts reflect assumptions regarding sustained FDA and EMA serialization enforcement, with nickel and molybdenum price volatility representing a material revision risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Multihead Weighers Market
Packaging Equipment
Global Shrink Sleeve Applicator Market