
 Self-Adhesive Tear Tape Market | 2026-2036
Self-Adhesive Tear Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Adhesive Tear Tape Market Analytics
The gap between premium tamper-evident tear tape and commodity-grade packaging tape is consolidating around adhesive chemistry, substrate precision, and converter certification standards. tesa SE leverages its European coating capacity to supply pharmaceutical and tobacco clients with holographic tear tape variants. 3M competes through North American distribution density and industrial-grade polypropylene formulations. Bagla Group anchors South Asian supply chains with cost-optimized paper-backed tear tape for regional FMCG brands.
Self-adhesive tear tape is a narrow strip of pressure-sensitive material, typically 2–5 mm wide, comprising a carrier film coated with acrylic or hot-melt adhesive and wound on a release liner; it serves primarily as an opening aid and tamper-evidence feature on flexible packaging. Polypropylene carriers dominate volume due to tensile strength and printability, though PVC retains share in moisture-sensitive pharmaceutical blister overwrap where barrier performance commands premium positioning. Fabric-backed tear tape occupies a niche in heavy-duty industrial bundling, while paper substrates face margin compression from sustainability-driven shifts toward recyclable mono-material structures.
FDA 21 CFR regulations for indirect food contact materials shape adhesive migration limits in U.S. food packaging applications, while REACH and the EU Packaging and Packaging Waste Directive enforce substance restrictions and recyclability claims across European supply chains. China's GB standards for packaging materials, administered by SAMR, impose testing protocols that influence export-oriented tear tape formulations. Stakeholders must monitor evolving extended producer responsibility schemes and adhesive reclassification debates, as these will determine which material platforms retain market access without reformulation costs.
Market Dynamics
The EU F-Gas Regulation and REACH substance restrictions are forcing adhesive reformulation across European converter networks, compressing margins for solvent-dependent coating operations while creating certification premiums for compliant suppliers.
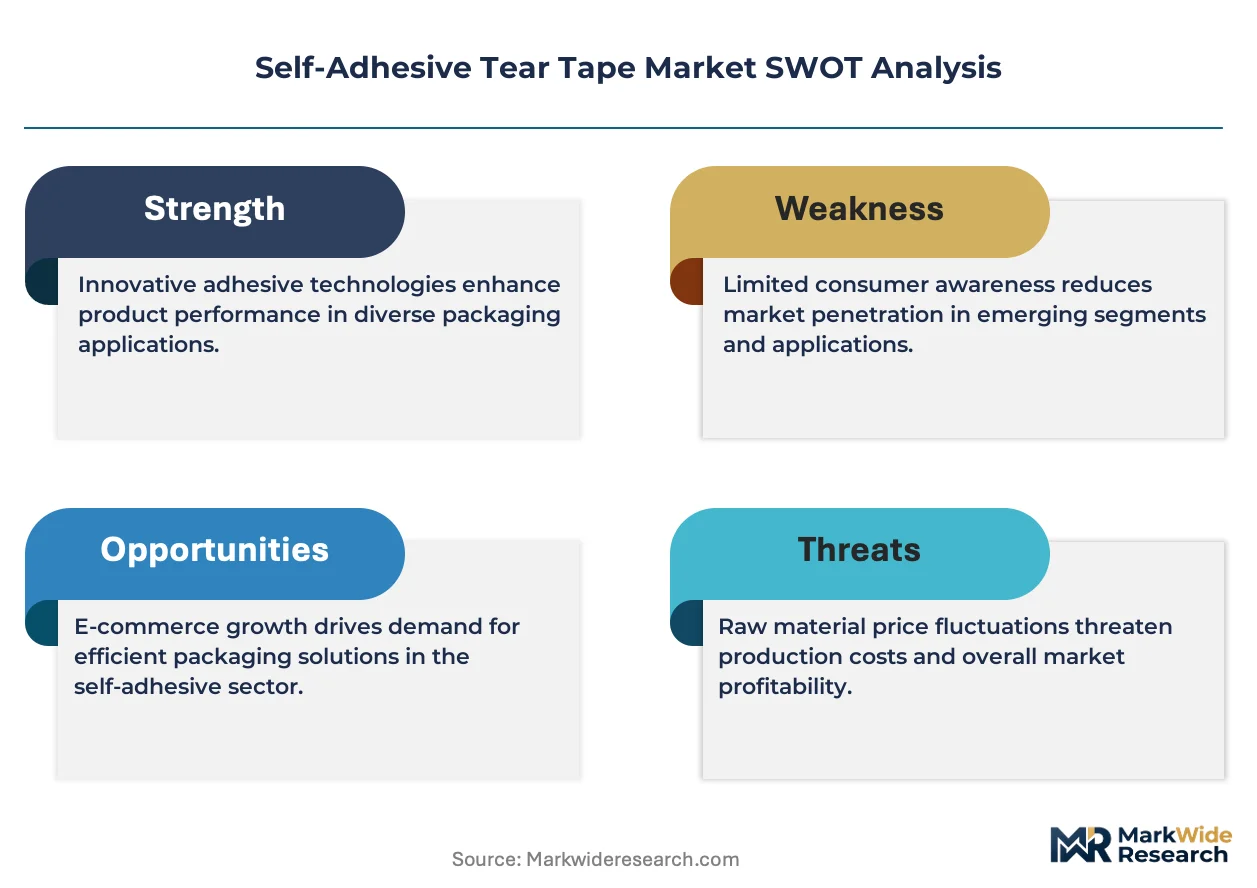
Growth Catalysts
- Tobacco packaging mandates:Cigarette manufacturers in Germany and Poland are expanding tamper-evident tear tape adoption to meet anti-counterfeiting requirements under the EU Tobacco Products Directive.
- Pharmaceutical serialization:Track-and-trace regulations from the FDA and EMA are driving demand for holographic tear tape variants that integrate with authentication systems.
- Solvent-free adhesive systems:Hot-melt and UV-curable formulations are displacing solvent-based chemistries as converters seek compliance with volatile organic compound limits.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings for propylene monomer squeeze converter margins, particularly for thin-gauge carrier films below 30 microns.
- Coating capacity concentration:European supply chains depend heavily on southwestern German production clusters, creating geographic vulnerability to energy cost spikes.
- PVC substitution pressure:REACH substance restrictions and recyclability mandates are phasing out PVC-backed tear tape in favor of lower-barrier mono-material alternatives.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO serialization requirements for export-bound medicines create demand for certified tear tape with anti-tamper features.
- Flexible packaging recyclability:The EU Packaging and Packaging Waste Directive incentivizes mono-material PP tear tape integration with recyclable film structures.
- E-commerce security sealing:Last-mile delivery operators are adopting tear tape for tamper-evident pouch closures in high-value parcel segments.
Industry Challenges
- Adhesive migration testing timelines:FDA 21 CFR indirect food contact validation requires 12-18 month certification cycles that delay product launches.
- Coater technical labor scarcity:Solvent-to-hot-melt process conversion demands skilled technicians familiar with slot-die and curtain coating equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Adhesive Tear Tape Market |
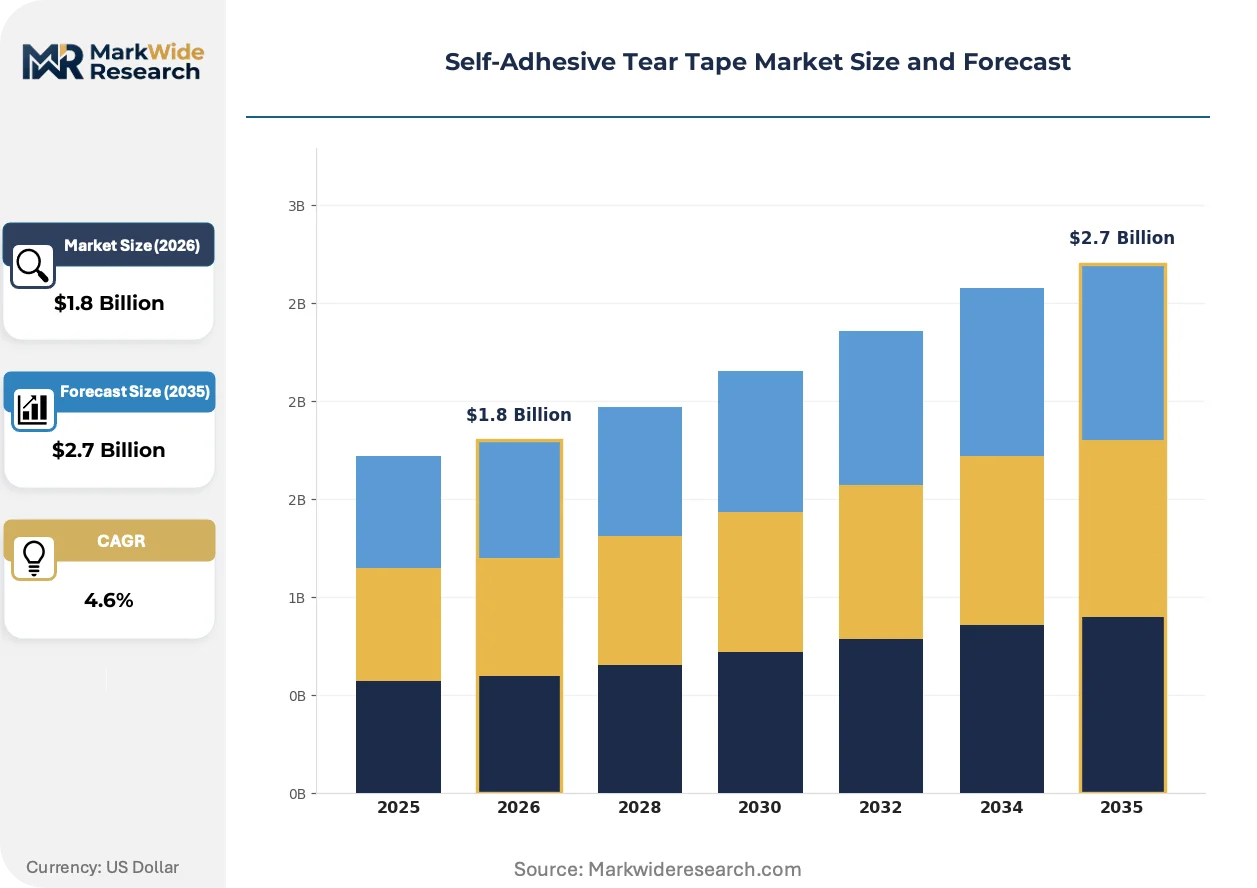
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Masking Tape, Duct Tape, Packaging Tape, Electrical Tape Application: Industrial Use, Retail Packaging, Household Use, Medical Applications Material: Polypropylene, PVC, Paper, Fabric Distribution Channel: Online Retailers, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | tesa SE, 3M, H.B. Fuller Company, Bagla Group, Marotech Inc., NADCO Tapes & Labels, Inc., Essentra plc, DS Smith, Supertape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Adhesive Tear Tape Market Evolving Landscape
Digital printing integration and regulatory chemistry shifts are compressing product development cycles while fragmenting specification requirements across end-use verticals.
Laser-scored tear tape with integrated micro-perforations is automating opening-force consistency in high-speed cigarette packaging lines. Tobacco manufacturers in Germany and Poland are adopting these precision-etched variants to reduce jam rates on G.D and Focke machines. The technology is automating quality control by eliminating manual tension adjustments during changeovers.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC carrier reformulation across European pharmaceutical blister overwrap applications. The ECHA substance evaluation process has reclassified certain adhesive plasticizers as substances of very high concern, compelling converters to validate alternative chemistries. German and Swiss packaging suppliers are responding fastest, leveraging existing hot-melt coating infrastructure.
Brand owners are consolidating tear tape procurement through master service agreements with integrated packaging converters rather than standalone tape suppliers. This channel compression bypasses traditional distributor networks in North American food packaging. The shift is most pronounced in snack and confectionery segments, where CPG giants demand single-source accountability for tamper-evidence compliance.
Self-Adhesive Tear Tape Market Segmentation
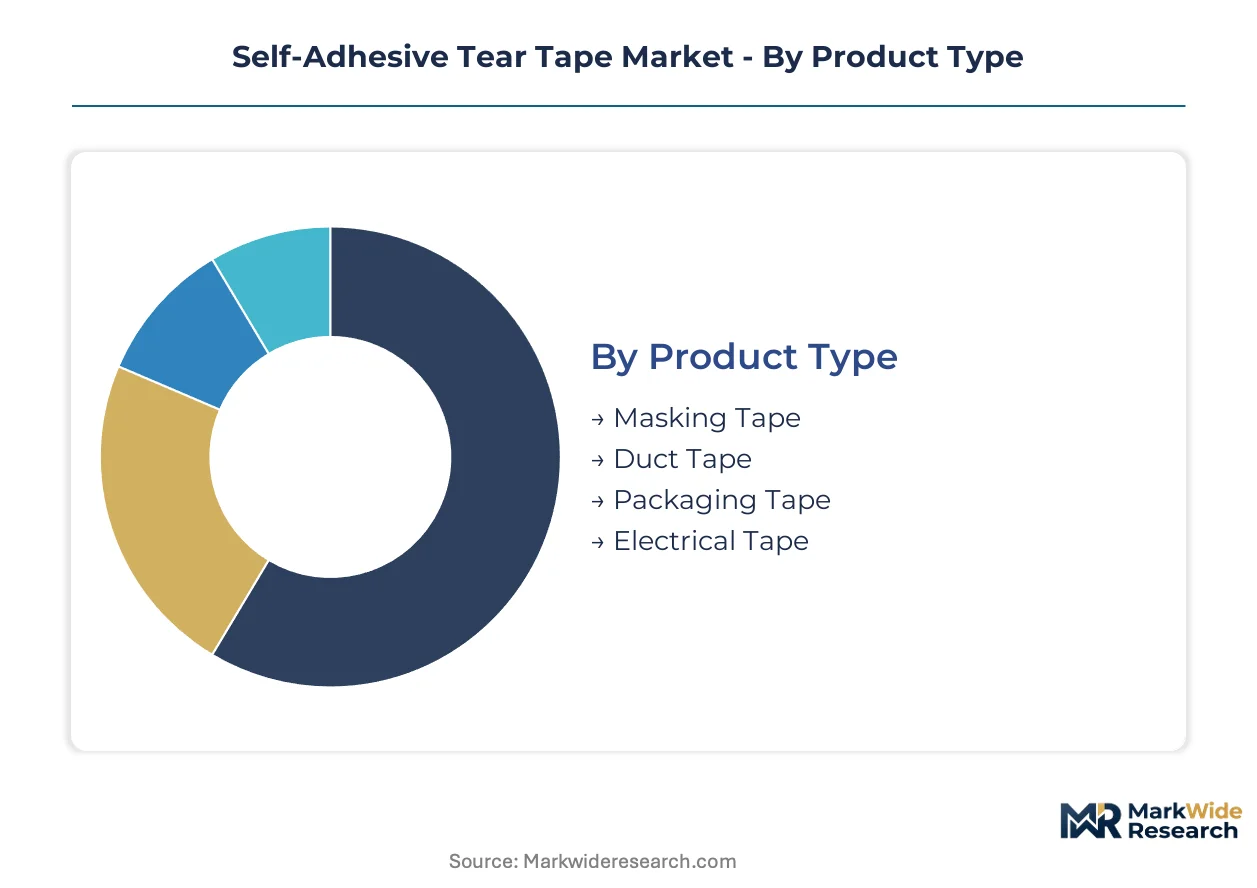
Self-adhesive tear tape specifications fragment sharply across end-use requirements, with pharmaceutical and tobacco mandates demanding precision-grade substrates while industrial applications tolerate wider tolerance bands. Converter procurement increasingly bundles tear tape with flexible packaging films, collapsing standalone segment boundaries.
Product Type:
Volume concentrates in commodity-grade formats serving high-throughput packaging lines, while premium variants command certification premiums in regulated end-uses.
- Masking Tape:Crepe paper carrier with rubber-based adhesive delivers clean removal properties for temporary surface protection during manufacturing. Automotive paint shops in Stuttgart and Wolfsburg specify low-tack variants to prevent substrate damage during masking operations.
- Duct Tape:Polyethylene-laminated cloth backing with aggressive natural rubber adhesive provides tensile strength for HVAC sealing and industrial repair. Demand clusters in German mechanical engineering corridors where equipment maintenance protocols specify tear-resistant patching materials.
- Packaging Tape:Biaxially oriented polypropylene film with hot-melt or acrylic adhesive dominates carton sealing volumes across e-commerce fulfillment networks.
- Electrical Tape:PVC or vinyl backing with pressure-sensitive rubber adhesive insulates low-voltage wiring; REACH substance restrictions are forcing phthalate-free plasticizer migration.
Mature deployment sits with packaging tape. Newer deployment is concentrated in electrical tape reformulations.
Application:
Regulatory intensity separates pharmaceutical and medical applications from industrial and household segments, with compliance costs creating tiered supplier qualification barriers.
- Industrial Use:Heavy-duty tear tape reinforces pallet bundling and steel coil wrapping in metal processing facilities. Ruhr Valley steelworks specify fabric-backed variants with 50+ kg tensile strength for horizontal strapping of hot-rolled coils.
- Retail Packaging:Holographic and metallized tear tape variants serve anti-counterfeiting functions in premium cosmetics and spirits. Polish and Czech brand owners integrate these features with track-and-trace serialization under EU Tobacco Products Directive extensions.
- Household Use:General-purpose opening aids on food pouches and consumer goods employ cost-optimized polypropylene carriers with standard acrylic adhesive.
- Medical Applications:Sterile tear tape for pharmaceutical blister overwrap demands low-extractable adhesive systems validated to EMA guidelines.
Industrial use anchors volume procurement. Medical applications are climbing the fastest as serialization mandates expand.
Material:
Substrate selection trades barrier performance against recyclability compliance, with mono-material pressures reshaping legacy PVC positions.
- Polypropylene:Biaxially oriented film delivers optimal printability and tensile strength for high-speed cigarette packaging lines. German tobacco converters specify 23-micron gauge with holographic metallization for G.D and Focke machine compatibility.
- PVC:Rigid vinyl backing provides moisture barrier properties for pharmaceutical blister overwrap in humidity-sensitive markets. ECHA substance evaluations are accelerating substitution timelines as plasticizers face SVHC reclassification.
- Paper:Recyclable kraft backing serves sustainability-positioned FMCG brands in Western European markets with extended producer responsibility schemes.
- Fabric:Woven textile carriers reinforce heavy-load industrial strapping where elongation resistance exceeds film substrate capabilities.
PVC retains entrenched pharmaceutical positions. Paper substrates are gaining share fastest under EU Packaging and Packaging Waste Directive pressure.
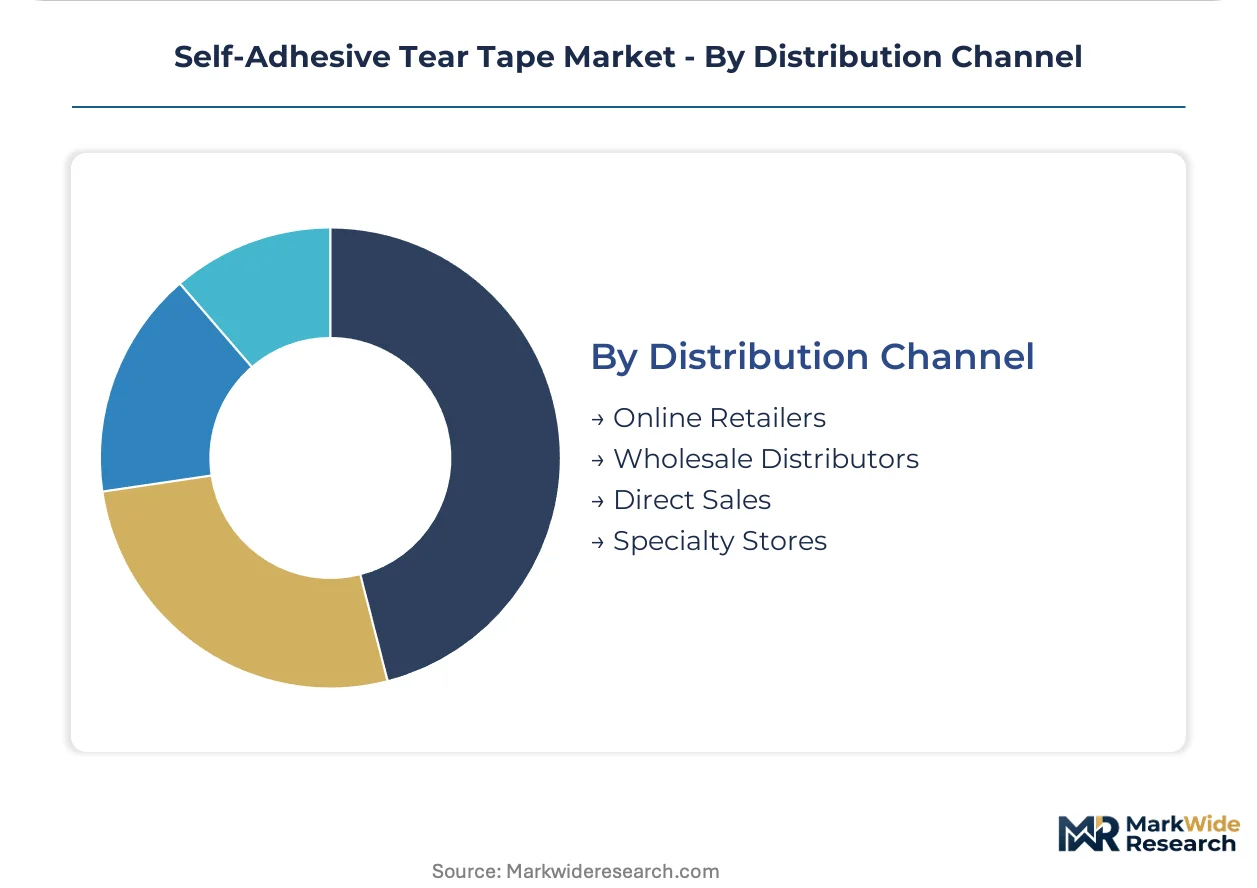
Distribution Channel:
Channel selection correlates with order scale and technical service requirements, with large converters bypassing intermediaries for direct mill relationships.
- Online Retailers:E-commerce platforms serve fragmented MRO procurement and small-batch converter sampling needs with standardized SKU offerings.
- Wholesale Distributors:Regional industrial distributors stock breadth across adhesive chemistries for mid-tier packaging converters in Benelux and Northern France.
- Direct Sales:Integrated converters negotiate master service agreements with tesa SE and Essentra plc for volume commitments with technical specification support.
- Specialty Stores:Niche outlets supply craft and hobby segments with decorative tear tape variants outside industrial procurement channels.
Direct sales dominate pharmaceutical and tobacco procurement. Online retailers are expanding most quickly in MRO replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southwestern German industrial corridor around Offenburg and Hamburg anchors European tear tape manufacturing, with coating clusters serving pharmaceutical and tobacco brand owners across the continent.
Germany
Tobacco packaging mandates under the EU Tobacco Products Directive drive holographic tear tape demand from G.D and Focke machine operators. The EU F-Gas Regulation and REACH compliance requirements force solvent-free adhesive adoption across Baden-Württemberg coating facilities. The Offenburg production cluster supplies precision-grade substrates to Polish and Czech cigarette manufacturers.
United States
FDA 21 CFR indirect food contact regulations shape adhesive migration limits for flexible packaging applications. The EPA volatile organic compound limits accelerate hot-melt formulation adoption among Midwestern converters. Chicago-area distribution networks supply e-commerce fulfillment centers with industrial-grade polypropylene tear tape.
China
GB standards administered by SAMR impose testing protocols on export-oriented tear tape formulations. The country's dual carbon goals pressure converters toward lower-emission coating processes. Yangtze River Delta packaging hubs integrate tear tape with flexible film structures for regional FMCG brands.
India
CDSCO serialization requirements for export-bound pharmaceuticals create demand for certified anti-tamper tear tape. The PLI scheme for packaging materials supports domestic converter capacity expansion. Gujarat-based suppliers serve South Asian FMCG brands with cost-optimized paper-backed variants.
Switzerland
Swissmedic pharmaceutical guidelines enforce low-extractable adhesive standards for blister overwrap applications. The country's precision manufacturing heritage supports high-tolerance substrate production. Basel-area converters supply European medical device manufacturers with validated tear tape systems.
Self-Adhesive Tear Tape Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the self-adhesive tear tape market. Integrated coating specialists with in-house adhesive compounding capabilities command certification premiums in pharmaceutical and tobacco segments. Three archetypes dominate: European precision converters with REACH-compliant solvent-free lines, North American distribution-heavy players leveraging logistics density, and South Asian cost-optimized fabricators serving regional FMCG volume. Competitive moves center on backward integration into adhesive resin production and geographic expansion through master service agreements with multinational brand owners.
Among European coating specialists, tesa SE and Essentra plc exemplify the integrated precision tier, occupying positions that bridge adhesive chemistry expertise with pharmaceutical certification protocols. 3M represents the North American distribution archetype, anchoring industrial-grade supply chains through density rather than vertical manufacturing control. Bagla Group sits within the South Asian volume tier, supplying regional markets through cost-optimized production configurations.
| Leading Market Players |
|---|
| tesa SE |
| 3M |
| H.B. Fuller Company |
| Bagla Group |
| Marotech Inc. |
| NADCO Tapes & Labels, Inc. |
| Essentra plc |
| DS Smith |
| Supertape |
| Others |
Value Network & Pricing Analysis
Propylene monomer feedstock volatility propagates through three distinct pricing tiers, with thin-gauge carrier films below 30 microns commanding certification premiums in German pharmaceutical corridors while commodity polypropylene formats face margin compression from South Asian converters.
Pricing Analysis
Throughput-linked value anchoring dominates contract structures, with holographic tear tape for G.D and Focke cigarette packaging lines priced against machine uptime guarantees rather than per-meter material cost. Three-tier pricing structure across pharmaceutical-grade, industrial-standard, and economy FMCG levels separates EMA-validated low-extractable systems from generic hot-melt formulations. Pricing pressure stems from REACH-driven adhesive reformulation costs that solvent-dependent European coaters cannot fully pass through. Brand owners in tobacco and pharmaceutical segments exhibit lowest price sensitivity, while regional snack and confectionery converters in South Asia negotiate aggressively on volume commitments.
Supply Chain Analysis
Direct-to-converter channels handle multinational tobacco and pharmaceutical procurement, bypassing distributor markups for master service agreements with technical specification support. Manufacturing gravity centers on Germany, China, and India, with coating capacity clustering in southwestern German industrial corridors and Yangtze River Delta packaging hubs. Supply chains draw from propylene monomer, acrylic adhesive resins, and metallized film substrates. Single-source vulnerability concentrates in European solvent-free coating equipment, where slot-die and curtain coater technical labor scarcity limits capacity expansion. Distribution runs through integrated packaging converters bundling tear tape with flexible film structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is concentrating around backward integration into adhesive resin production and captive coating capacity, as certification premiums reward players controlling both chemistry and substrate precision.
For Market Incumbents: Deploy hot-melt coating infrastructure upgrades to capture REACH-compliant volume migrating from solvent-dependent competitors. Consolidate position through master service agreements with Polish and Czech tobacco manufacturers expanding holographic tear tape adoption under EU Tobacco Products Directive mandates. Acquire slot-die coating technical talent pools in Baden-Württemberg to defend against emerging Asian entrants with lower labor cost structures. For New Entrants and Emerging Players: Capture CDSCO-certified pharmaceutical export demand from Gujarat-based suppliers serving Indian generic medicine manufacturers. Target e-commerce security sealing applications for last-mile delivery operators in North American and European fulfillment networks. Enter through digital printing-integrated tear tape variants that compress product development cycles for mid-tier CPG brands. For Investors and Strategic Acquirers: ECHA substance evaluation announcements on phthalate plasticizer reclassification are the leading indicator that PVC-backed tear tape assets face accelerated obsolescence. Five-to-ten year viability favors converters with validated hot-melt infrastructure and pharmaceutical certification protocols already in place. Prioritize acquisition targets with existing EMA and FDA 21 CFR indirect food contact validation rather than greenfield certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Coating Capacity Expansion | REACH and EU F-Gas Regulation compliance secures market access for European pharmaceutical and tobacco clients. |
| Backward Integration into Adhesive Resin Production | Captive acrylic and hot-melt supply insulates margins from propylene monomer price volatility. |
| Pharmaceutical Certification Investment | EMA and FDA 21 CFR validation creates tiered supplier qualification barriers against commodity competitors. |
| Digital Printing Integration | Micro-perforation and laser-scoring capabilities automate quality control for high-speed cigarette packaging lines. |
| Mono-Material PP Development | EU Packaging and Packaging Waste Directive alignment positions tear tape for recyclable flexible film structures. |
Research Methodology
Document review covered regulatory filings from ECHA, FDA, and SAMR, complemented by interviews with coating operations managers, pharmaceutical packaging procurement leads, flexible film converters, and adhesive R&D directors. Secondary sources included customs trade data for propylene monomer and polypropylene film flows, SEC 10-K disclosures from integrated tape manufacturers, and EU Tobacco Products Directive implementation reports. Bottom-up volume modeling triangulated against top-down market sizing from industry association capacity estimates.
Segment-level projections across product type, application, material substrate, and distribution channel fed into analytical frameworks spanning the projection horizon. CAGRs were derived from regression analysis of historical volume trends against regulatory mandate implementation timelines and brand owner procurement pattern shifts. Industry-specific inputs included G.D and Focke machine compatibility specifications, EMA low-extractable adhesive validation protocols, and CDSCO serialization requirement phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction scope expansions and adhesive plasticizer reclassification debates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tape Banding Machine Market
Tapes
Flocking Tape Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Lacing Tape Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Removal Strips Market
Tapes
Double Sided Tape Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Pipe Marking Tape Market
Tapes
Hydrocolloid Tapes Market
Tapes
Tape Dispenser Market
Tapes
Tear Tape Dispenser Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Twist Tube Market
Tapes
Tissue Tapes Market