
 Semi-Automatic and Manual Filling Equipment Market | 2026-2036
Semi-Automatic and Manual Filling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semi-Automatic and Manual Filling Equipment Market Outlook
Modular filling skids is hardening as the dominant configuration pattern, letting mid-sized pharmaceutical and cosmetic manufacturers reconfigure lines without full automation overhauls. Syntegon Technology leverages its electromechanical platform depth to anchor premium positions in Europe's validated packaging corridors. Accutek Packaging Equipment competes on configurable small-batch systems that dominate North American craft beverage and specialty chemical niches.
Semi-automatic and manual filling equipment encompasses piston, auger, overflow, and vacuum filler mechanisms that dispense measured product volumes into containers through operator-assisted or partially automated cycles, typically handling 10–150 containers per minute depending on viscosity and fill specification. These systems serve primary packaging operations where batch flexibility, changeover speed, or capital constraints preclude fully automated lines. Pneumatic systems lead installed base volumes across food and chemical plants due to lower maintenance burden and compressed air ubiquity in existing facilities. Electromechanical systems represent the fastest-expanding technology segment as servo-driven accuracy meets pharmaceutical serialization demands without full automation cost. Manual operations persist in cosmetic manufacturers and small-batch chemical plants where SKU proliferation outpaces automation payback thresholds.
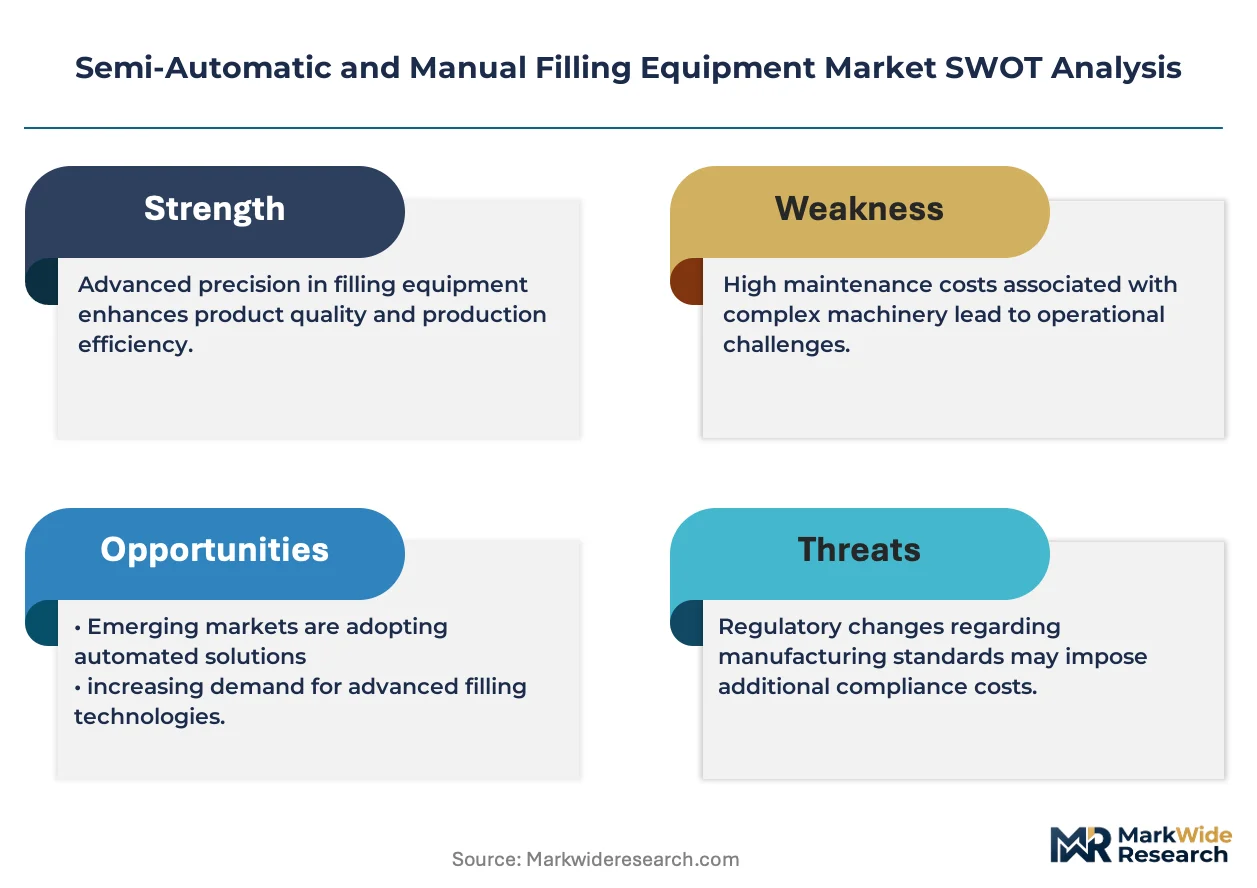
FDA 21 CFR Part 11 and EU MDR traceability mandates are forcing equipment upgrades with electronic batch recording and audit trail capabilities across pharmaceutical end users. EPA and OSHA exposure limits in chemical plants and food facilities shape material specifications and containment designs for powder and oil filling applications. Buyers must weigh electromechanical precision premiums against pneumatic reliability when retrofitting lines for multi-format contract manufacturing.
Market Dynamics
Contract manufacturers in India and Southeast Asia are compressing equipment procurement cycles as FDA validation requirements and EU MDR compliance timelines force simultaneous capacity expansion and regulatory retrofitting. This dual-pressure environment rewards modular filling skids that reconfigure without full automation overhauls.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic batch recording mandates are forcing pharmaceutical packaging lines to upgrade semi-automatic systems with audit trail capabilities, accelerating replacement demand across validated manufacturing corridors.
- Servo-driven electromechanics:Pharmaceutical serialization requirements are pulling electromechanical accuracy into mid-speed lines without the capital burden of full automation, expanding addressable market for precision fillers.
- India's contract manufacturing clusters:Export-oriented formulation facilities in Hyderabad and Ahmedabad are scaling semi-automatic piston and auger capacity to serve multi-format batch requirements for regulated markets.
Market Restraints
- Stainless steel and specialty alloy costs:Input price volatility for pharmaceutical-grade contact surfaces compresses margin on mid-range equipment, particularly affecting pneumatic system manufacturers with thinner material buffers.
- Validation documentation burden:EU MDR technical file requirements and FDA installation qualification protocols extend sales-to-revenue cycles by four to eight months for pharmaceutical-bound systems.
- Used equipment refurbishment:Secondary markets for validated pharmaceutical fillers create price anchoring that constrains new equipment premiums in cost-sensitive emerging manufacturing clusters.
Strategic Opportunities
- Indonesia's pharmaceutical manufacturing:Underpenetrated domestic formulation capacity and ASEAN regulatory harmonization create first-mover advantage for semi-automatic suppliers establishing local validation support.
- Cell and gene therapy fill-finish:Small-batch sterile processing requirements in advanced therapy manufacturing are opening specialized niches for isolator-integrated manual filling stations.
- EU Green Deal machinery standards:Energy efficiency mandates and circular economy equipment passports are creating specification premiums for electromechanical systems with regenerative servo drives.
Industry Challenges
- Commissioning and qualification specialists:Scarce talent pools for FDA and EU MDR validation execution create bottlenecks at equipment handover, particularly for mid-sized manufacturers without dedicated quality engineering functions.
- Legacy SCADA integration:Retrofitting electronic batch recording capabilities into existing pneumatic filling lines requires custom protocol bridging that extends project timelines and inflates engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi-Automatic and Manual Filling Equipment Market |
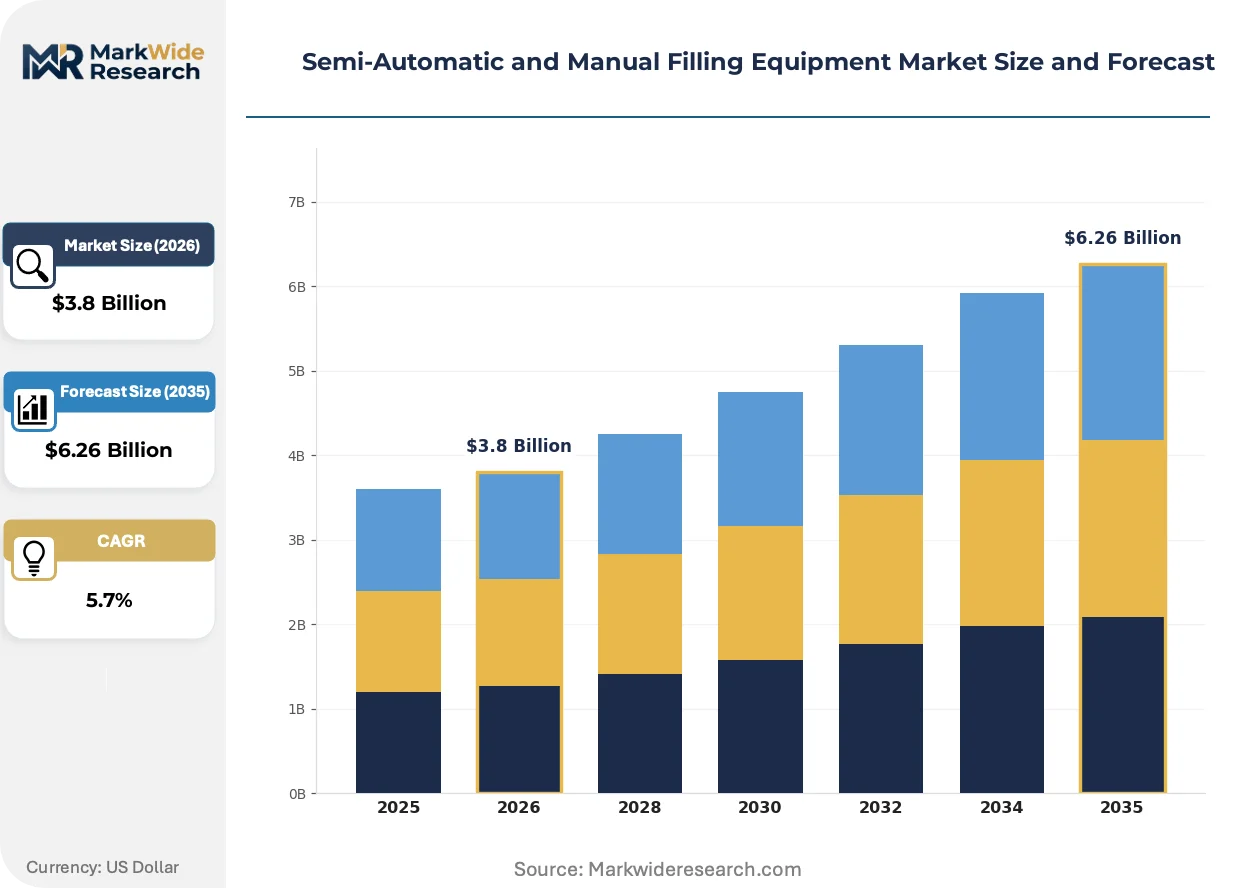
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Fillers, Auger Fillers, Overflow Fillers, Vacuum Fillers End User: Food Industry, Pharmaceutical Sector, Cosmetic Manufacturers, Chemical Plants Technology: Electromechanical Systems, Pneumatic Systems, Mechanical Systems, Manual Operations Application: Beverage Filling, Cream Filling, Oil Filling, Powder Filling |
| Companies Covered | IMA Group, Syntegon Technology, GEA Group, Coesia, ProMach, Nordson Corp., Graco Inc., Accutek Packaging Equipment, JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi-Automatic and Manual Filling Equipment Market Strategic Shifts
Electromechanical precision is displacing pneumatic dominance across pharmaceutical and high-specification chemical filling, while regulatory serialization mandates and batch-size flexibility requirements reshape equipment specification patterns. These shifts are compressing traditional technology adoption cycles.
Servo-driven piston and auger mechanisms are electrifying filling accuracy standards in mid-speed pharmaceutical lines. Contract manufacturers handling multi-SKU portfolios are adopting these systems to meet serialization mandates without full automation capital outlay. This electrification is compressing the traditional accuracy gap between semi-automatic and high-speed rotary fillers.
EU MDR Unique Device Identification and traceability mandates are forcing equipment upgrades with integrated data matrix verification and electronic batch recording. Pharmaceutical packaging lines must now embed serialization-ready infrastructure during initial qualification rather than retrofitting later. European contract manufacturers are responding by specifying electromechanical platforms with native industrial ethernet and audit trail architectures.
Buyer procurement patterns are fragmenting as mid-sized manufacturers bypass traditional distributor channels for direct OEM relationships with embedded validation support. Specialty chemical and cosmetic producers are unbundling after-sales service contracts to source regional maintenance independently. This channel disintermediation is most visible in North American craft beverage and specialty chemical niches where configurable small-batch systems dominate.
Semi-Automatic and Manual Filling Equipment Market Segmentation
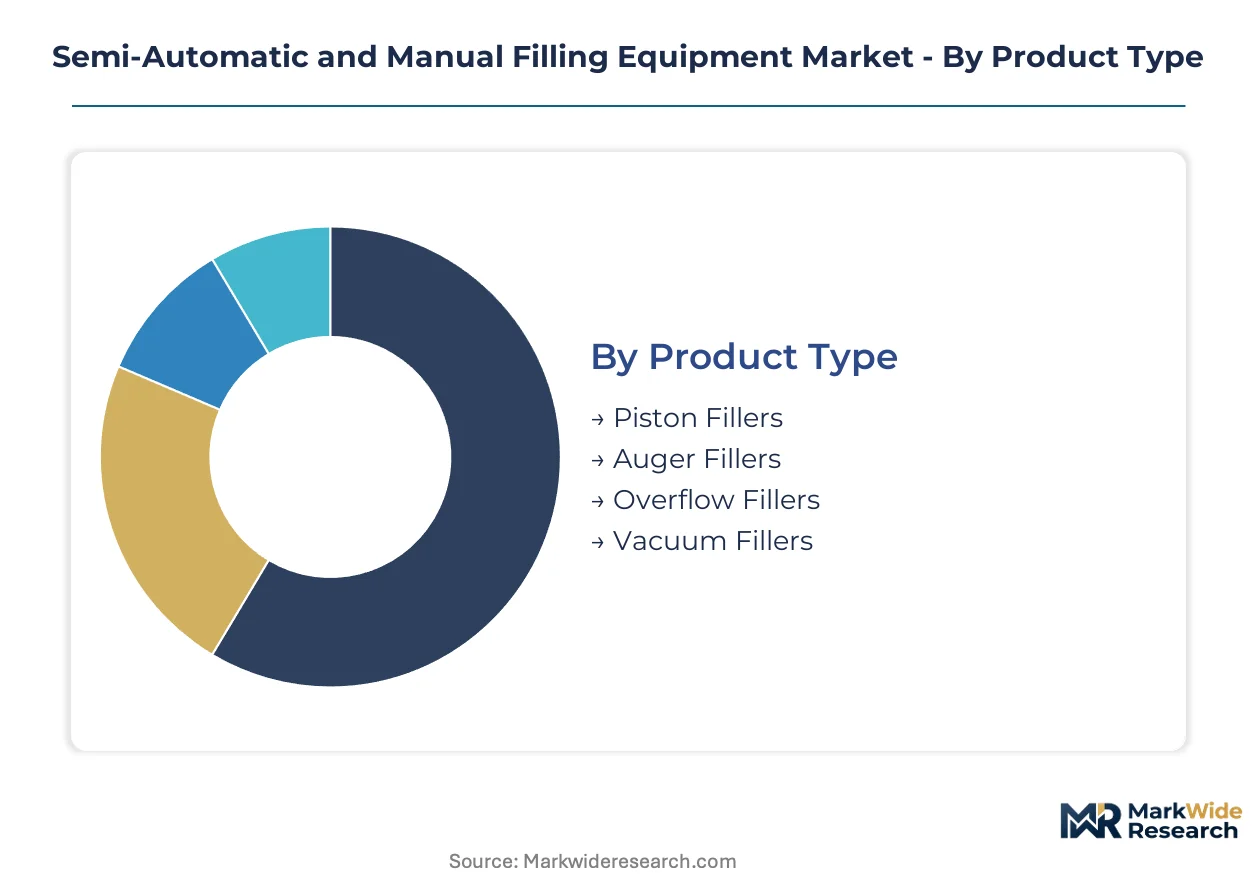
Equipment replacement cycles in pharmaceutical and food packaging lines vary sharply across filling mechanisms, technology platforms, and end-use requirements. Segmentation reveals where modular upgrades concentrate versus full-line automation investments.
Product Type:
Upgrade cycles differ materially by mechanism complexity, with piston and auger systems facing compressed replacement timelines from FDA validation mandates.
- Piston Fillers:Positive displacement mechanisms handle viscous liquids and semi-solids through reciprocating cylinder action. Pharmaceutical packaging lines in India and Southeast Asia are scaling piston capacity for multi-format export formulations under EU MDR compliance pressure.
- Auger Fillers:Rotating screw mechanisms meter dry powders and granules with dose-to-weight accuracy. Cosmetic manufacturers in Hyderabad and Ahmedabad deploy these for SKU proliferation that outpaces full automation payback.
- Overflow Fillers:Level-sensing systems fill containers to consistent visual height regardless of volume variation. Beverage producers favor these for transparent container presentation.
- Vacuum Fillers:Negative pressure systems draw product into containers for foam-sensitive applications. Specialty chemical plants use these for volatile solvent handling.
Piston fillers sit at the top of the volume ranking, with auger fillers climbing the fastest.
End User:
Capital allocation patterns diverge sharply by sector regulatory burden and batch-size economics.
- Food Industry:FSSAI compliance and export certification requirements drive stainless steel specification upgrades. Mid-sized Indian processors balance pneumatic reliability against electromechanical precision for serialization-ready lines.
- Pharmaceutical Sector:CDSCO-regulated facilities face compressed procurement cycles from simultaneous FDA 21 CFR Part 11 and EU MDR retrofit demands. Electronic batch recording mandates force audit trail capabilities into semi-automatic platforms.
- Cosmetic Manufacturers:High SKU variety and short production runs favor manual and semi-automatic flexibility over dedicated high-speed lines.
- Chemical Plants:EPA and OSHA exposure limits shape containment designs for powder and oil filling operations.
Pharmaceutical sector installations command premium pricing tiers, with food industry volume expanding most rapidly.
Technology:
Platform selection hinges on accuracy requirements versus maintenance burden tradeoffs in validated manufacturing corridors.
- Electromechanical Systems:Servo-driven actuation delivers pharmaceutical-grade precision without full automation capital outlay. Serialization mandates are pulling this technology into mid-speed lines previously served by pneumatic equipment.
- Pneumatic Systems:Compressed air actuation dominates installed base volumes through lower maintenance burden and existing infrastructure ubiquity. Food and chemical plants retain these where accuracy tolerances permit.
- Mechanical Systems:Cam-driven mechanisms persist in cost-sensitive applications with stable product specifications.
- Manual Operations:Operator-assisted filling stations serve small-batch sterile processing in cell and gene therapy manufacturing.
Pneumatic systems retain the largest installed base, though electromechanical platforms gain share fastest.
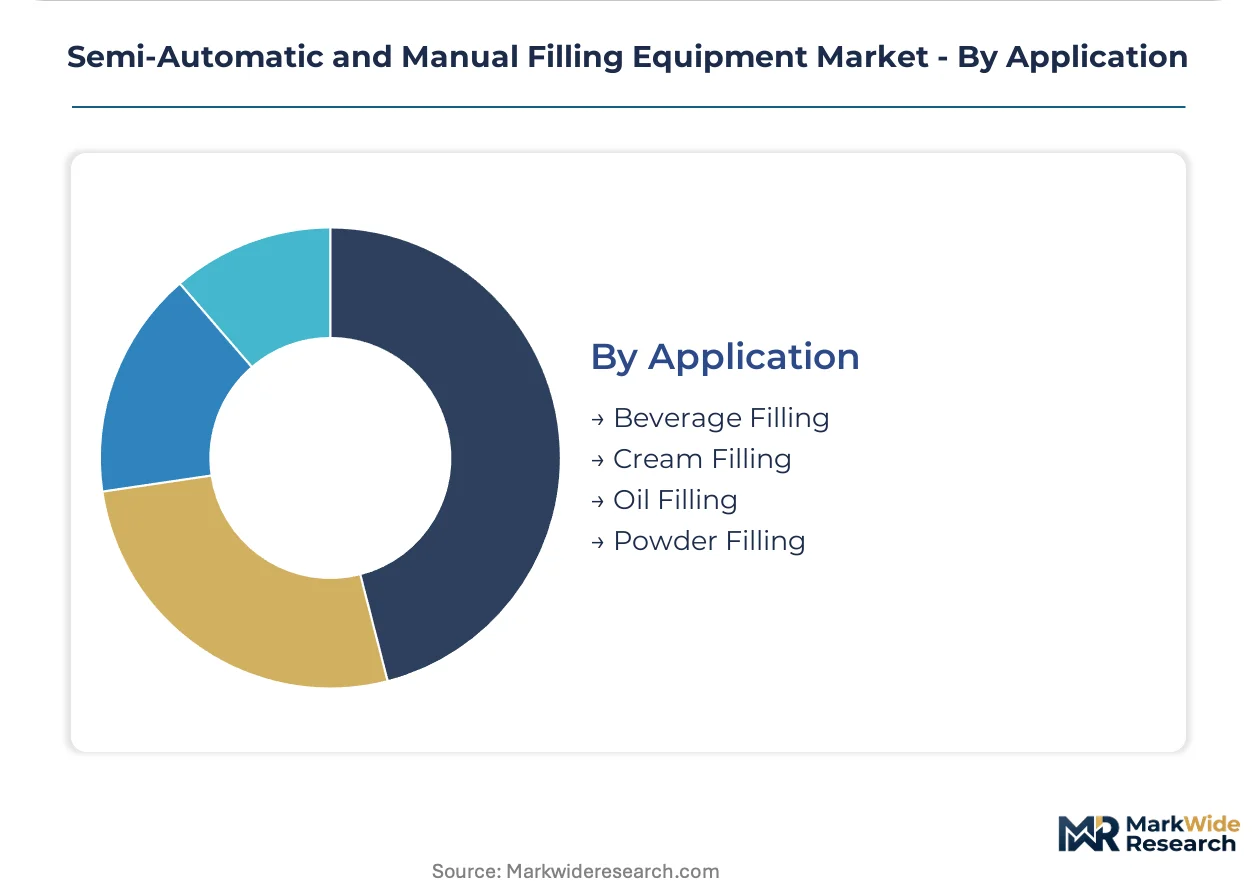
Application:
Product physical properties dictate mechanism selection and containment architecture across end-use segments.
- Beverage Filling:Carbonated and still liquid handling requires foam control and level consistency. Craft producers in North American markets favor configurable small-batch systems.
- Cream Filling:High-viscosity semi-solid dispensing demands heated hopper designs and positive displacement accuracy. Cosmetic manufacturers specify these for tube and jar packaging.
- Oil Filling:Lubricant and edible oil applications emphasize drip-free nozzles and spill containment. Chemical plants specify EPA-compliant designs for volatile formulations.
- Powder Filling:Dust containment and dose uniformity challenges favor auger mechanisms with isolator integration. Sterile powder processing in advanced therapy manufacturing opens specialized niches.
Beverage filling leads unit shipments, with powder filling posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered pharmaceutical-grade filling machinery in the post-war era, establishing precision engineering standards that shaped global equipment specifications. The industry's geographic footprint now spans manufacturing clusters across three continents.
United States
Contract manufacturers near Boston and Research Triangle Park are retrofitting semi-automatic lines for FDA 21 CFR Part 11 compliance. The EPA's National Emission Standards for Hazardous Air Pollutants shape containment designs for chemical filling operations. Craft beverage producers in Colorado and Oregon dominate demand for configurable small-batch systems.
Germany
EU MDR traceability mandates are compressing equipment procurement cycles for Baden-Württemberg pharmaceutical packaging corridors. The EU Green Deal's machinery efficiency standards create specification premiums for regenerative servo drive systems. Syntegon Technology anchors electromechanical platform positions in Stuttgart's validated manufacturing ecosystem.
India
CDSCO-regulated facilities in Hyderabad and Ahmedabad are scaling piston and auger capacity for export-oriented formulations. The Production-Linked Incentive scheme for pharmaceuticals accelerates capital equipment deployment. Contract manufacturers in these clusters prioritize modular skids that reconfigure without full automation overhauls.
China
NMPA serialization requirements are pulling electromechanical accuracy into mid-speed packaging lines previously served by pneumatic equipment. The country's dual carbon goals pressure energy efficiency specifications for new machinery installations. Yangtze River Delta pharmaceutical manufacturers represent the fastest-expanding demand concentration for validated semi-automatic systems.
Indonesia
Underpenetrated domestic formulation capacity and ASEAN regulatory harmonization create first-mover opportunities for equipment suppliers establishing local validation support. The national pharmaceutical regulator's GMP alignment initiatives compress adoption timelines for audit trail-capable systems. Jakarta and Bandung manufacturing zones are emerging as contract manufacturing hubs serving regional export markets.
Semi-Automatic and Manual Filling Equipment Market Competitive Environment
The competitive structure tilts toward diversified packaging machinery conglomerates with electromechanical platform depth. Tiered positioning separates validated pharmaceutical specialists from configurable small-batch generalists. Three archetypes dominate: European precision engineering houses, North American flexible automation providers, and Asian cost-optimized fabricators. M&A activity concentrates on electromechanical technology acquisitions, while geographic expansion targets underpenetrated ASEAN pharmaceutical corridors.
Among European precision engineering houses, Syntegon Technology and GEA Group exemplify the validated-platform archetype with deep electromechanical integration. Accutek Packaging Equipment represents North American specialization in configurable small-batch systems for craft producers and specialty chemical niches. These three anchors illustrate the geographic and technological fault lines shaping competitive positioning across regulatory corridors and batch-size economics.
| Leading Market Players |
|---|
| IMA Group |
| Syntegon Technology |
| GEA Group |
| Coesia |
| ProMach |
| Nordson Corp. |
| Graco Inc. |
| Accutek Packaging Equipment |
| JBT Corporation |
| Others |
Value Chain & Pricing Dynamics
Contract manufacturers in India's pharmaceutical corridors anchor pricing power for semi-automatic filling equipment, compressing procurement cycles through simultaneous FDA validation and EU MDR compliance demands. This buyer concentration forces three-tier pricing stratification across premium electromechanical platforms, mid-range pneumatic systems, and economy mechanical units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with certification grade and after-sales service bundling as primary differentiation drivers. Stainless steel input volatility and validation documentation burdens intensify cost compression in mid-range pneumatic tiers. Small-batch cosmetic manufacturers exhibit highest price sensitivity, while validated pharmaceutical facilities absorb premium electromechanical pricing for serialization compliance.
Supply Chain Analysis
Direct-to-OEM channels handle multi-format contract manufacturer demand, bypassing traditional distributor networks for embedded validation support. Component sourcing concentrates in Germany, China, and India for servo drives, precision machining, and stainless steel contact surfaces. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade servo actuators. Distribution runs through regional equipment fabricators with local qualification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between European validation premiums and Asian manufacturing cost bases, with EU MDR compliance timelines compressing procurement cycles in Stuttgart and Hyderabad simultaneously.
For Market Incumbents: Anticipate margin erosion from used equipment refurbishment markets by deepening backward integration into servo drive supply and establishing captive validation documentation services. Electromechanical platform differentiation and local qualification support in ASEAN corridors defend positioning against cost-optimized fabricators.
For New Entrants and Emerging Players: Launch via direct OEM relationships targeting Indonesia's underpenetrated pharmaceutical formulation capacity, leveraging ASEAN regulatory harmonization for first-mover advantage. Cell and gene therapy fill-finish niches offer penetrable entry points through isolator-integrated manual filling stations with specialized sterile processing capabilities.
For Investors and Strategic Acquirers: European precision engineering houses with electromechanical platform depth represent the most active acquirer category in this space, consolidating validated manufacturing corridor positions. Acquisition targets with regenerative servo drive technology and EU Green Deal machinery compliance readiness command structural premiums. Watch FDA 21 CFR Part 11 enforcement intensity as inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Supply | Captive sourcing of electromechanical actuators insulates margin from component volatility and single-source risk. |
| Local Validation Support Establishment | Embedded FDA and EU MDR qualification expertise in Jakarta and Bandung accelerates sales-to-revenue cycles. |
| Regenerative Drive Technology Adoption | EU Green Deal machinery standards create specification premiums for energy-efficient electromechanical platforms. |
| Isolator-Integrated Manual Station Development | Cell and gene therapy sterile processing requirements open specialized niches beyond traditional pharmaceutical lines. |
| Used Equipment Refurbishment Capability | Secondary market price anchoring in India demands counter-positioning through certified pre-owned programs with full validation documentation. |
Study Parameters
Direct dialogue with packaging line engineers, contract manufacturing procurement leads, FDA validation specialists, and aftermarket service directors grounded qualitative insights in operational reality. Secondary validation drew from CDSCO facility inspection records, EU MDR technical file databases, SEC filings of listed packaging machinery conglomerates, and customs trade data for pharmaceutical equipment imports. Bottom-up equipment shipment tallies and top-down end-use industry capex patterns were triangulated to anchor volume estimates.
Top-down macroeconomic filtering shaped the analytical lens, with bottom-up segment-level modeling across filling mechanism type, technology platform, end-use vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and compliance-driven upgrade timelines. Pharmaceutical serialization mandates and stainless steel price indices served as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios or abrupt FDA enforcement shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Loading Spout Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market