
 Stretch Wrappers Market | 2026-2036
Stretch Wrappers Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Wrappers Market Outlook
Third-party logistics providers is unwinding the historical dominance of food and beverage manufacturers as the primary stretch wrapper buyers. Berry Global leverages its resin backward integration to control input costs across North American operations. Paragon Films specializes in high-performance cast film formulations for automated lines. Lantech dominates stretch hood and orbital wrapper engineering with sustained R&D intensity in load containment systems.
Stretch wrappers are mechanical systems and films that apply tensioned polyethylene or cast polypropylene layers around palletized goods, typically achieving 150-300% pre-stretch ratios to secure loads for transit and storage. Their primary purpose is to unitize products, reduce shipping damage, and enable vertical warehouse stacking. Automatic stretch wrappers command the largest installed base but semi-automatic units are expanding fastest in mid-sized warehouses where capital constraints limit full automation. Rotary technology leads the equipment segment while orbit wrappers capture specialized applications for unstable or oversized loads.
FDA food-contact regulations and OSHA machine-guarding standards shape equipment design and film formulation requirements in the United States. The EU F-Gas Regulation and REACH compliance frameworks restrict certain film additives and drive converter investment in sustainable material pathways. Stakeholders must monitor how load stability specifications evolve alongside lighter-weight packaging mandates.
Market Dynamics
Automated palletizing lines are compressing the window for manual stretch wrapping operations as warehouse labor costs escalate and throughput requirements intensify across fulfillment networks.
Growth Catalysts
- EU Green Deal packaging directives:Thinner-gauge film specifications are accelerating converter investment in high-performance resin formulations and downgauging equipment upgrades.
- E-commerce fulfillment center expansion:Third-party logistics providers are scaling automated wrapper installations to meet pallet stability requirements for parcel sortation and last-mile distribution.
- Rotary arm technology:Mid-sized warehouses are adopting semi-automatic rotary systems to bridge the gap between manual wrapping and fully automated orbital lines.
Market Restraints
- Polyethylene resin price volatility:Crude oil indexation and refinery capacity constraints create margin compression for film converters and equipment lessors.
- German industrial corridor concentration:Demand clustering in Bavaria and North Rhine-Westphalia creates geographic vulnerability to regional logistics disruptions.
- Mechanical load containment limits:Orbital wrappers face technical ceilings with unstable or non-uniform pallet geometries that preclude standard film tension protocols.
Strategic Opportunities
- India warehouse automation:Cold chain infrastructure buildout and organized retail expansion create first-mover positions for cast film suppliers and semi-automatic equipment distributors.
- Stretch hood convergence with IoT:Integration of load sensors and cloud-based monitoring enables predictive maintenance contracts and film consumption optimization.
- REACH-compliant additive pathways:Bio-based plasticizers and recycled content mandates open formulation differentiation for converters with laboratory certification capabilities.
Industry Challenges
- Mechatronics technician scarcity:Automated wrapper deployment outpaces vocational training output for PLC programming and servo motor calibration.
- CE marking timeline compression:Machinery Directive conformity assessments and F-Gas Regulation compliance documentation extend product launch cycles for European market entry.
- Legacy warehouse management system integration:Proprietary protocols in existing facility software complicate API connections for new wrapper control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Wrappers Market |
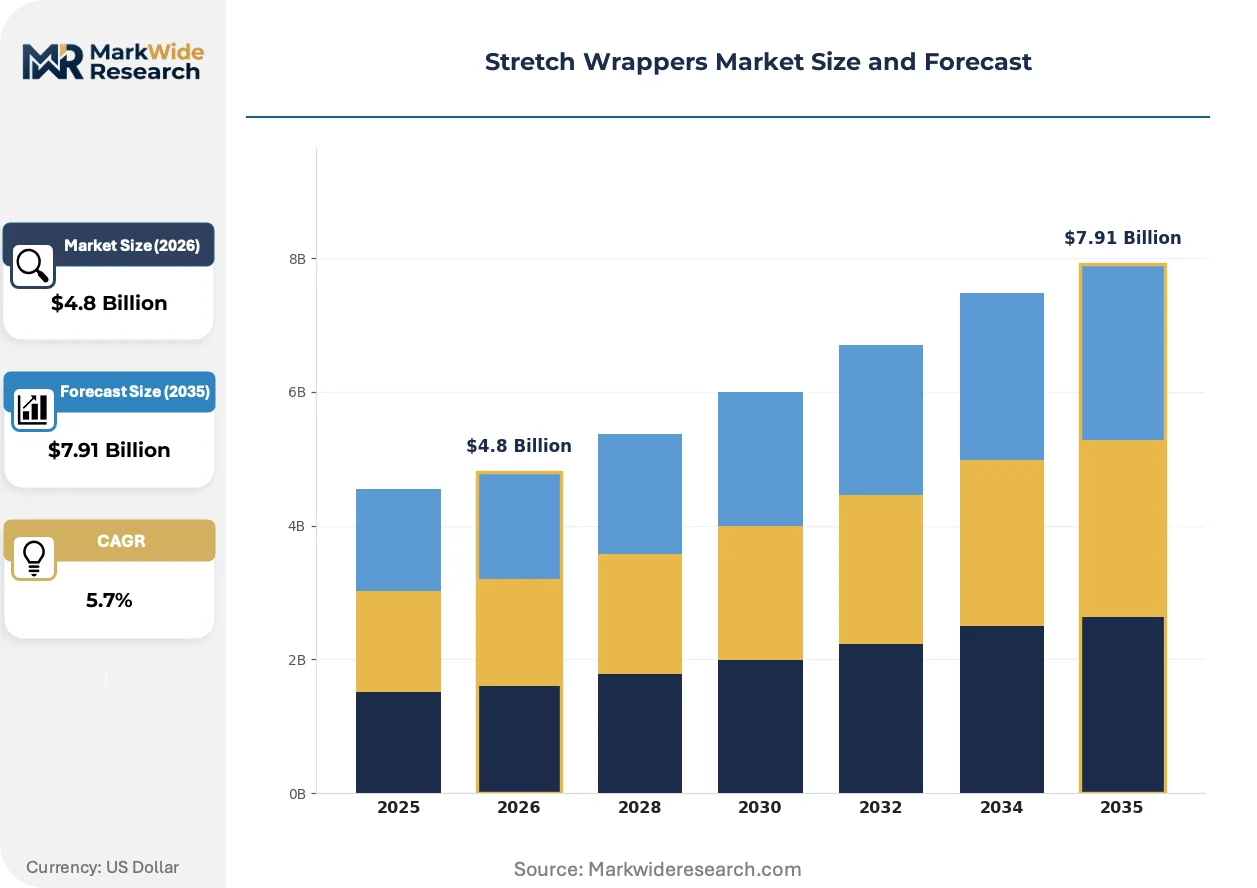
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, High-Speed End User: Food & Beverage, Pharmaceuticals, Electronics, Construction Technology: Rotary, Orbit, Turntable, Horizontal Application: Packaging, Palletizing, Shrink Wrapping, Transportation |
| Companies Covered | Inteplast Group, Paragon Films, Berry Global, Coveris, Dow, Intertape Polymer Group, Lantech, Orion Packaging, Sigma Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Wrappers Market Strategic Shifts
Film downgauging and automation convergence are redrawing equipment specifications and procurement criteria across material handling operations. Converter R&D priorities are pivoting toward performance retention at reduced caliper weights.
Cast polyethylene films with nano-layer coextrusion are supplanting conventional blown film in high-speed automated lines. Beverage distributors and consumer goods manufacturers are adopting these formulations to maintain load containment at 20-30% reduced material weights. The shift is compressing per-pallet film costs while extending pre-stretch ratios beyond 300%.
REACH authorization requirements for phthalate plasticizers are forcing reformulation investments across European converter operations. ECHA substance evaluations have restricted several legacy additives used in cling and slip properties. Film suppliers are accelerating migration to bio-based alternatives and recycled content verification protocols to maintain market access.
Third-party logistics operators are consolidating stretch wrapper procurement through national framework agreements rather than facility-level purchasing. Regional 3PL networks are centralizing equipment standardization and film supply contracts to leverage volume pricing and service uniformity. This concentration is most visible in Germany's automotive parts distribution corridors and Benelux e-commerce hubs.
Stretch Wrappers Market Segmentation
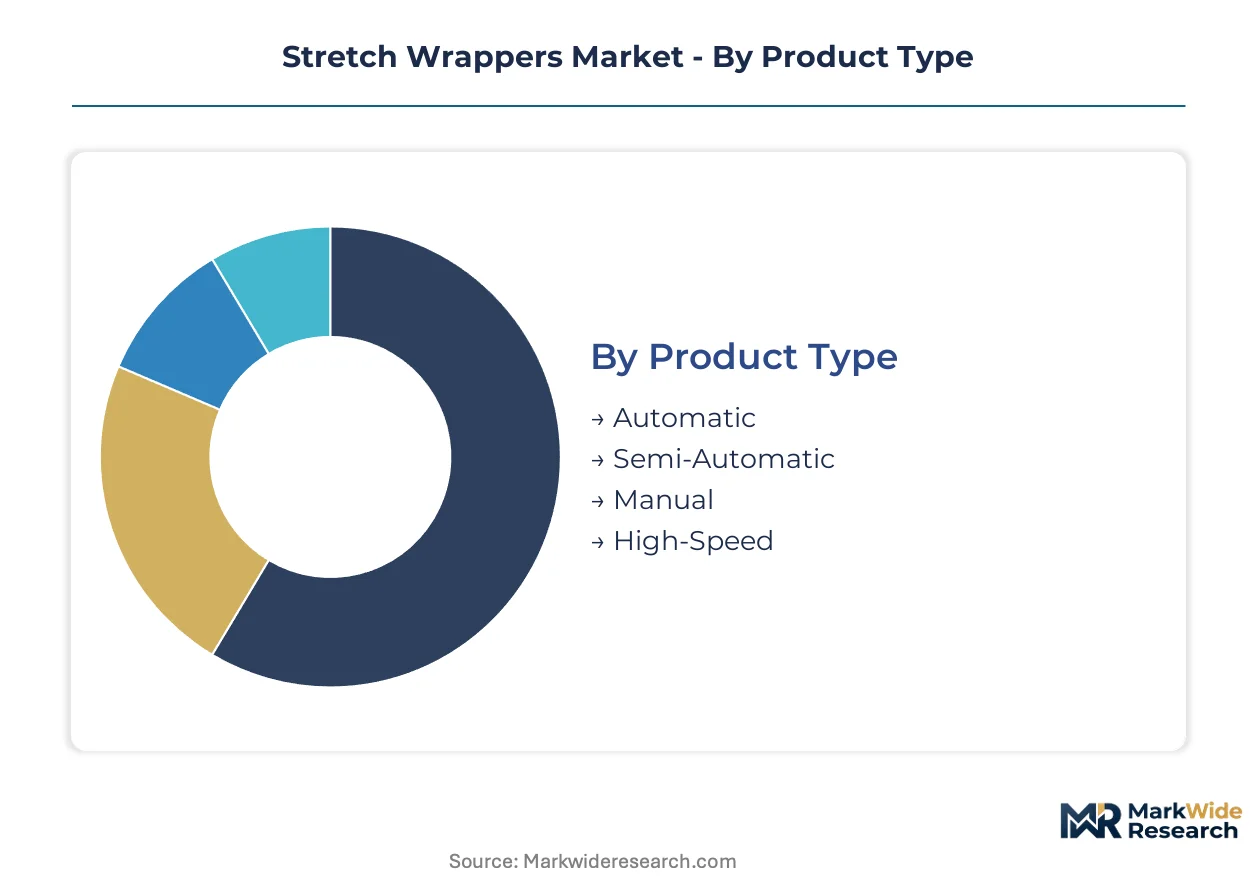
Stretch wrapper procurement patterns diverge sharply across operational scales and throughput requirements. Equipment specifications and film formulations align with distinct channel economics rather than uniform industry standards.
Product Type:
Channel economics favor automatic systems in high-volume distribution centers while semi-automatic units penetrate mid-tier warehouses through equipment leasing programs.
- Automatic:These systems integrate with conveyor networks and warehouse management software to achieve sustained throughput above 100 pallets per hour. Demand concentrates in German automotive parts distribution corridors where labor cost escalation justifies capital intensity. The EU Green Deal packaging directives accelerate adoption as automated lines optimize film consumption through precision tension control.
- Semi-Automatic:Rotary arm configurations bridge manual operations and full automation for facilities processing 20-60 pallets daily. Bavaria and North Rhine-Westphalia industrial clusters show strongest procurement as mid-sized manufacturers modernize legacy wrapping stations. Capital constraints limit penetration in smaller warehouses despite favorable total cost of ownership.
- Manual:Hand-held dispensers and mobile turntables serve micro-fulfillment operations and seasonal overflow capacity. Construction material yards and agricultural cooperatives represent core demand pockets.
- High-Speed:Orbital wrappers with servo-driven pre-stretch achieve 300%+ film extension ratios for beverage and consumer goods distribution. Cold chain infrastructure buildout in organized retail networks drives specification upgrades.
Automatic systems dominate installed base. Semi-automatic configurations are where expansion concentrates.
End User:
Application requirements shape margin structures across customer categories, with pharmaceutical and electronics segments commanding specification premiums.
- Food & Beverage:Pallet stability for liquid containers and temperature-sensitive products demands high-cling film formulations. FDA food-contact regulations govern film composition for US operations while EFSA frameworks apply across European dairy and meat processing facilities.
- Pharmaceuticals:Serialization compliance and contamination prevention drive investment in enclosed orbital systems with HEPA filtration options. German pharmaceutical distribution hubs specify CE-marked equipment with enhanced traceability documentation.
- Electronics:Anti-static film requirements and precision load containment protect high-value components during inter-facility transfers. Semiconductor supply chain security protocols influence wrapper selection criteria.
- Construction:Abrasive material handling and outdoor storage conditions prioritize puncture-resistant blown film over cast alternatives. Building materials distributors favor robust turntable designs with corrosion-resistant finishes.
Food and beverage anchors volume demand. Pharmaceuticals is climbing the fastest on specification intensity.
Technology:
Engineering differentiation separates equipment tiers, with rotary and orbital architectures serving fundamentally different load geometries.
- Rotary:Arm-based systems rotate around stationary pallets, enabling floor-level loading and stable containment of uniform loads. E-commerce fulfillment centers in Benelux hubs specify these for mixed-SKU pallet consolidation.
- Orbit:Ring-style wrappers handle unstable or oversized loads that preclude standard rotary protocols. Specialized applications in construction materials and irregular automotive components dominate adoption.
- Turntable:Rotating platform designs offer capital-efficient entry points for standard pallet dimensions. Mid-sized warehouses with predictable load profiles represent primary deployment.
- Horizontal:Side-sealing configurations accommodate long products such as lumber, piping, and textile rolls. Building products distribution networks specify these for unitizing non-standard dimensions.
Rotary technology commands the largest installed base. Orbit systems are gaining share fastest in specialized handling applications.
Application:
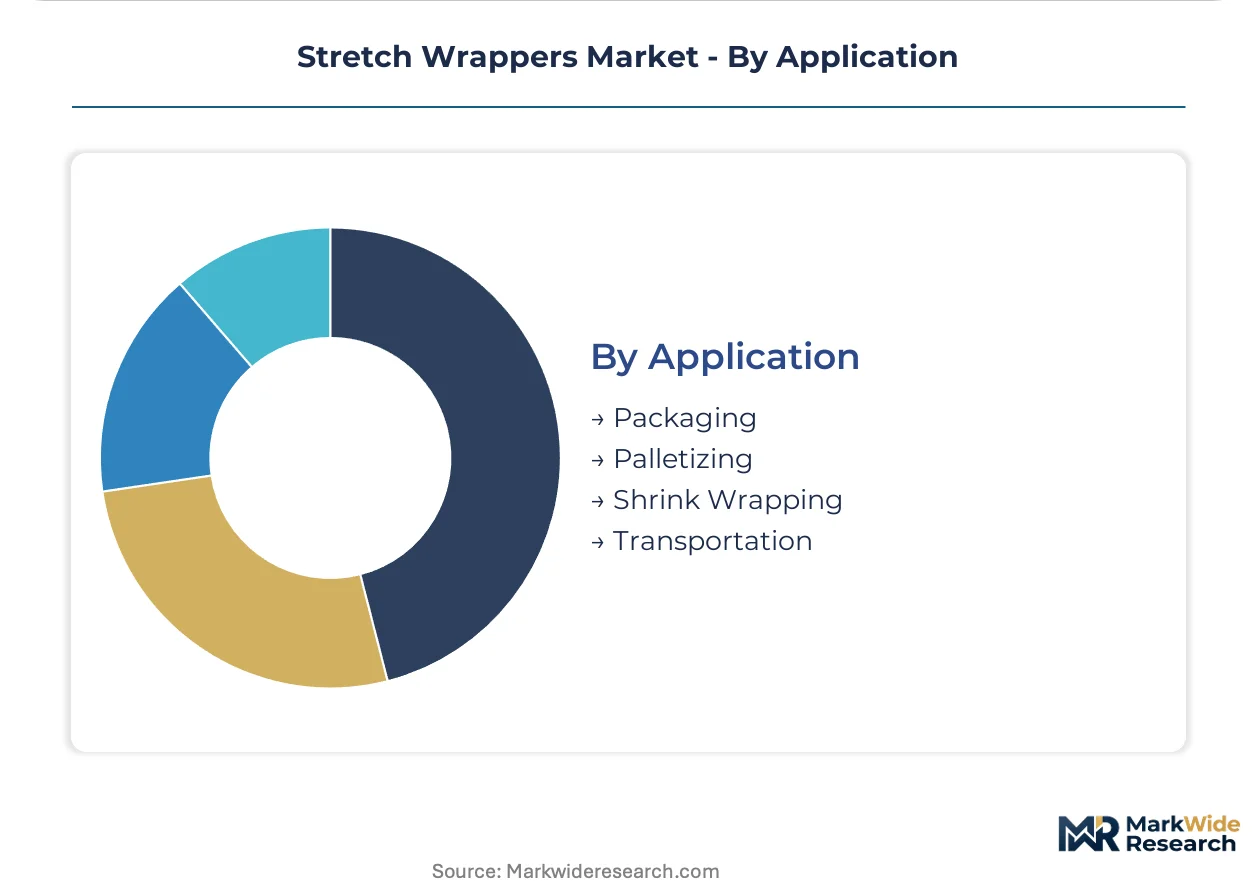
Functional deployment determines equipment specification, with packaging and palletizing representing distinct operational stages.
- Packaging:Primary film application secures individual items or case packs for downstream handling. Consumer goods manufacturers integrate stretch wrapping as the final production line stage before warehouse transfer.
- Palletizing:Unitization of mixed loads for storage efficiency and shipping damage reduction drives specification. Third-party logistics providers centralize procurement standards across multi-site palletizing operations.
- Shrink Wrapping:Heat-activated film systems serve distinct containment requirements alongside mechanical stretch alternatives. Beverage distributors deploy hybrid approaches for weatherproofing.
- Transportation:Load stabilization for over-the-road and intermodal transit demands enhanced containment force. REACH-compliant additive pathways influence film selection for European cross-border movements.
Palletizing dominates equipment deployment. Packaging applications are expanding most quickly through production line integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Benelux logistics demand for automated palletizing systems. Germany's Rhine-Ruhr rail corridor channels industrial goods through automated distribution hubs. India's Dedicated Freight Corridors are compressing transit times between manufacturing zones and cold chain warehouses.
United States
Third-party logistics providers in the Chicago-Indianapolis corridor are consolidating wrapper procurement through national framework agreements. FDA food-contact regulations govern film composition for dairy and meat distribution networks. The Southeast's e-commerce fulfillment expansion around Atlanta and Charlotte is driving specification upgrades for mixed-SKU pallet consolidation.
Germany
Automotive parts distributors in Bavaria and North Rhine-Westphalia specify CE-marked rotary systems with precision tension control. The EU Green Deal's packaging waste directives accelerate converter investment in high-performance resin formulations. Stuttgart's industrial logistics corridor shows strongest procurement intensity for semi-automatic configurations bridging manual and full automation.
China
Organized retail expansion in the Yangtze River Delta is scaling automated wrapper installations for temperature-sensitive product distribution. GB standards for packaging machinery shape equipment design requirements alongside SAMR market access protocols. Shanghai's cold chain infrastructure buildout creates first-mover positions for cast film suppliers serving pharmaceutical distribution.
India
Cold chain infrastructure buildout in Maharashtra and Gujarat is driving specification upgrades for high-cling film formulations. BIS certification requirements for packaging machinery extend product launch cycles for equipment market entry. The Delhi-Mumbai Industrial Corridor's warehouse automation push concentrates demand in Haryana and Rajasthan logistics hubs.
Netherlands
E-commerce fulfillment centers in the Randstad region specify rotary arm systems for Benelux distribution networks. REACH compliance frameworks restrict certain film additives and drive converter investment in sustainable material pathways. Rotterdam's port-centric logistics clusters show fastest adoption of IoT-integrated stretch hood systems for predictive maintenance contracts.
Stretch Wrappers Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and R&D scale. The vendor base spans resin producers, film converters, and equipment fabricators with overlapping but distinct margin structures. Three archetypes dominate: backward-integrated resin producers controlling input costs, specialized high-performance film formulators, and engineering-intensive equipment builders with sustained R&D programs. Competitive moves concentrate on national framework agreements for 3PL procurement and REACH-compliant additive pathway investments.
Among North American resin-integrated players, Berry Global exemplifies backward integration into polyethylene supply chains. Paragon Films occupies a specialist position in cast film formulation for automated lines. Lantech anchors the equipment-engineering tier with sustained investment in load containment system architecture. These three represent distinct competitive vectors: captive resin supply, performance formulation, and mechatronics integration.
| Leading Market Players |
|---|
| Inteplast Group |
| Paragon Films |
| Berry Global |
| Coveris |
| Dow |
| Intertape Polymer Group |
| Lantech |
| Orion Packaging |
| Sigma Plastics Group |
| Others |
Value Chain & Pricing Dynamics
CE marking and Machinery Directive conformity requirements gate both equipment qualification and price differentiation across European procurement channels, compressing launch timelines while stratifying vendor tiers by certification depth.
Pricing Analysis
Volume-discount tiering separates national framework agreements from facility-level purchasing across third-party logistics networks. Three-tier pricing structure across premium, standard, and economy levels reflects automation grade, after-sales service bundling, and REACH-compliant formulation certification. Cost compression in semi-automatic equipment is intensifying because resin backward integration advantages concentrate among North American resin-integrated players. Mid-sized warehouses show highest price sensitivity; pharmaceutical distributors demonstrate lowest.
Supply Chain Analysis
Just-in-time resin procurement dominates film converter operations, though strategic stockpiling of high-performance formulations buffers against polyethylene price volatility. Supply concentrates in Germany, the United States, and China for equipment fabrication; South Korea and Japan anchor specialty servo motor components. Raw material flows draw from crude oil indexation, refinery capacity allocation, and bio-based additive development programs. Single-source vulnerability runs through German automotive parts distribution corridors where demand clustering amplifies disruption risk. Distribution runs through national 3PL framework agreements rather than decentralized facility purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified mechatronics technicians for PLC programming and servo motor calibration are scarce relative to automated wrapper deployment rates, creating a capability bottleneck that shapes competitive durability across vendor tiers.
For Market Incumbents: Fortify national framework agreement positions through REACH-compliant additive pathway investments and predictive maintenance contract bundling. Resin price volatility threatens margin stability; backward integration into polyethylene supply chains or long-term offtake agreements with Gulf Coast refiners anchor input cost control. Prioritize certification depth in CE marking and FDA food-contact tiers to sustain specification premiums against emerging Asian equipment builders. For New Entrants and Emerging Players: Differentiate on IoT-integrated stretch hood systems with cloud-based load monitoring for predictive maintenance revenue streams. India's cold chain infrastructure buildout offers the most penetrable white space, particularly in Maharashtra and Gujarat warehouse automation clusters. Target semi-automatic rotary configurations for mid-sized manufacturers modernizing legacy wrapping stations, leveraging equipment leasing programs to bypass capital constraint barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-speed orbital wrapper engineering with sustained R&D requirements for 300%+ pre-stretch ratio achievement. Long-term viability favors converters with laboratory certification capabilities for bio-based plasticizer migration and recycled content verification. Watch for consolidation signals when national 3PL procurement frameworks reduce vendor counts below five qualified suppliers per geography.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Additive Pathway Investment | ECHA substance evaluations on phthalate restrictions force reformulation R&D to maintain European market access. |
| National 3PL Framework Agreement | Centralized procurement across Benelux e-commerce hubs compresses vendor margins while locking in volume commitments. |
| IoT-Integrated Stretch Hood Development | Rotterdam port-centric logistics clusters adopt cloud-based monitoring for predictive maintenance contract expansion. |
| Backward Integration into Resin Supply | Gulf Coast polyethylene production anchors input cost control for North American film converter operations. |
| Semi-Automatic Equipment Leasing Program | Bavaria and North Rhine-Westphalia mid-sized manufacturers bypass capital constraints through rotary system financing. |
Study Parameters
A spread of perspectives from equipment engineering directors, film converter procurement leads, third-party logistics operations managers, and aftermarket service technicians converged on the working assumptions. Primary fieldwork combined structured interviews with maintenance directors at German automotive distribution hubs and plant engineers at US dairy processing facilities. Secondary validation drew from EU F-Gas Regulation filings, ECHA substance evaluation databases, SEC 10-K disclosures from resin-integrated players, and customs trade data on polyethylene film imports. Bottom-up equipment shipment tallies and top-down end-use demand estimates were triangulated against converter capacity utilization rates.
Segmentation dimensions modeled include automation level, technology architecture, end-use industry, and geographic regulatory cluster across the analysis window. Load containment force specifications and pre-stretch ratio achievements by equipment tier informed unit economics. CAGRs were derived from elasticity modeling against e-commerce fulfillment center expansion rates and EU Green Deal packaging directive compliance timelines. Film downgauging penetration curves and cold chain infrastructure buildout trajectories served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained resin price stability and vocational training output expansion would require recalibration. Forecasts reflect documented assumptions on 3PL procurement consolidation velocity and REACH authorization timelines for legacy additives. Revision becomes warranted when mechatronics technician scarcity crosses thresholds that delay automated deployment schedules or when German industrial corridor demand clustering triggers regional logistics disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market