
 Coding and Marking Equipment Market | 2026-2036
Coding and Marking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Coding and Marking Equipment Market Intelligence
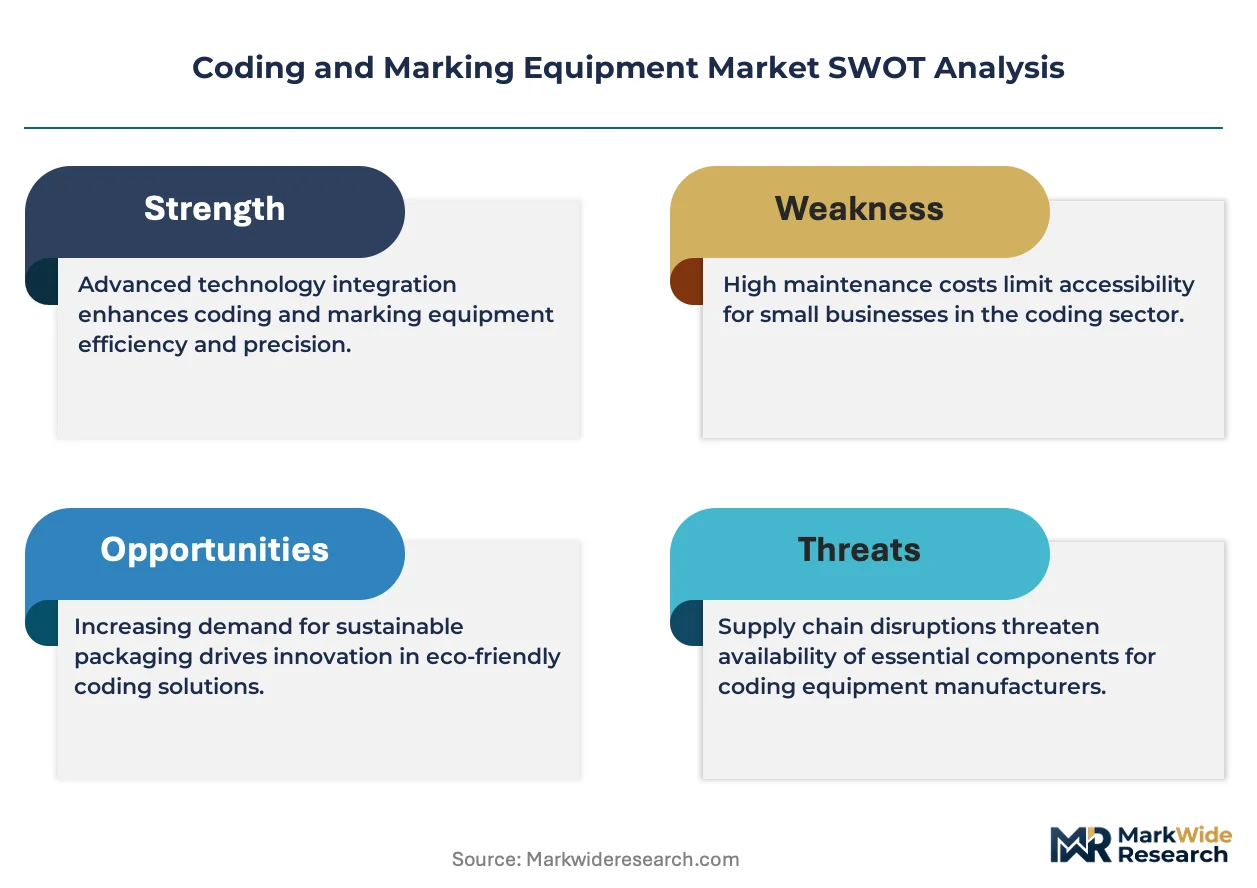
German industrial automation suppliers is recalibrating coding equipment output to match pharmaceutical serialization deadlines across the European Union. Videojet Technologies leverages its installed base in beverage bottling to sustain recurring ink and solvent revenue streams. Domino Printing Sciences anchors premium laser marking systems for electronics manufacturers requiring permanent, high-contrast identifiers on miniature components. Markem-Imaje competes through integrated track-and-trace software bundled with its continuous inkjet hardware.
Coding and marking equipment encompasses industrial systems that apply alphanumeric text, barcodes, QR codes, and graphics onto products, packaging, and labels using non-contact methods such as thermal transfer, laser ablation, or inkjet deposition at speeds exceeding 1,000 prints per minute. These systems serve traceability, anti-counterfeiting, and regulatory compliance functions across manufacturing supply chains. Laser marking technology leads in electronics and automotive applications where permanent, chemical-resistant identifiers withstand harsh operating environments. Inkjet printers dominate food and beverage lines where substrate variability and high moisture levels demand adaptable, fast-drying formulations. Thermal transfer printers occupy niche positions in flexible packaging where ribbon-based thermal transfer delivers precise edge definition on films and foils.
The EU Falsified Medicines Directive and its delegated regulation on safety features mandate unique identifier serialization across prescription drug packaging, directly expanding demand for integrated coding and verification systems. FDA's Drug Supply Chain Security Act imposes comparable traceability requirements on pharmaceutical manufacturers operating in or exporting to the United States. ISO 15415 and GS1 standards govern barcode print quality and data syntax, shaping equipment calibration protocols and service contract specifications. Stakeholders must monitor harmonization gaps between regional serialization deadlines and assess whether dual-compliance architectures or modular upgrade paths offer superior capital efficiency.
Market Dynamics
Pharmaceutical serialization mandates across the European Union are forcing equipment replacement cycles at manufacturing facilities, compressing decision timelines from typical five-year horizons to eighteen-month compliance windows.
Growth Catalysts
- EU Falsified Medicines Directive:Delegated regulations mandating unique identifiers on prescription packaging drive integrated coding and verification system deployments at pharmaceutical manufacturing sites.
- Continuous inkjet technology:High-speed beverage bottling lines in Germany and Italy are replacing thermal transfer systems to achieve print speeds exceeding 1,000 units per minute on curved glass and PET substrates.
- Electronics miniaturization:Laser marking systems capture demand from semiconductor and component manufacturers requiring permanent identifiers on sub-millimeter surfaces.
Market Restraints
- Specialized ink formulation costs:Solvent-based and UV-curable inks for food-contact applications carry raw material premiums of 40-60% above standard industrial grades, squeezing margin structures for high-volume users.
- Core component concentration:Precision piezoelectric printhead manufacturing concentrates in Japanese and German supplier bases, exposing buyers to extended lead times during capacity constraints.
- Thermal transfer ribbon substitution:Flexible packaging converters face competitive pressure from direct-to-film digital printing technologies that eliminate consumable ribbon requirements entirely.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO alignment with EU serialization standards creates retrofit demand at formulation facilities supplying regulated European markets.
- Battery cell traceability:Electric vehicle supply chain requirements for cell-level tracking open new application vectors for laser marking on cylindrical and prismatic lithium-ion formats.
- Cloud-based fleet management:Remote monitoring and predictive maintenance platforms enable equipment vendors to capture recurring software revenue alongside hardware sales.
Industry Challenges
- Multi-standard software integration:Pharmaceutical manufacturers must reconcile EU FMD, FDA DSCSA, and emerging national serialization frameworks within single production line architectures, complicating validation protocols.
- Field service technician scarcity:Mechatronics expertise combining fluid dynamics, electronics troubleshooting, and software configuration remains concentrated among veteran technicians approaching retirement cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coding and Marking Equipment Market |
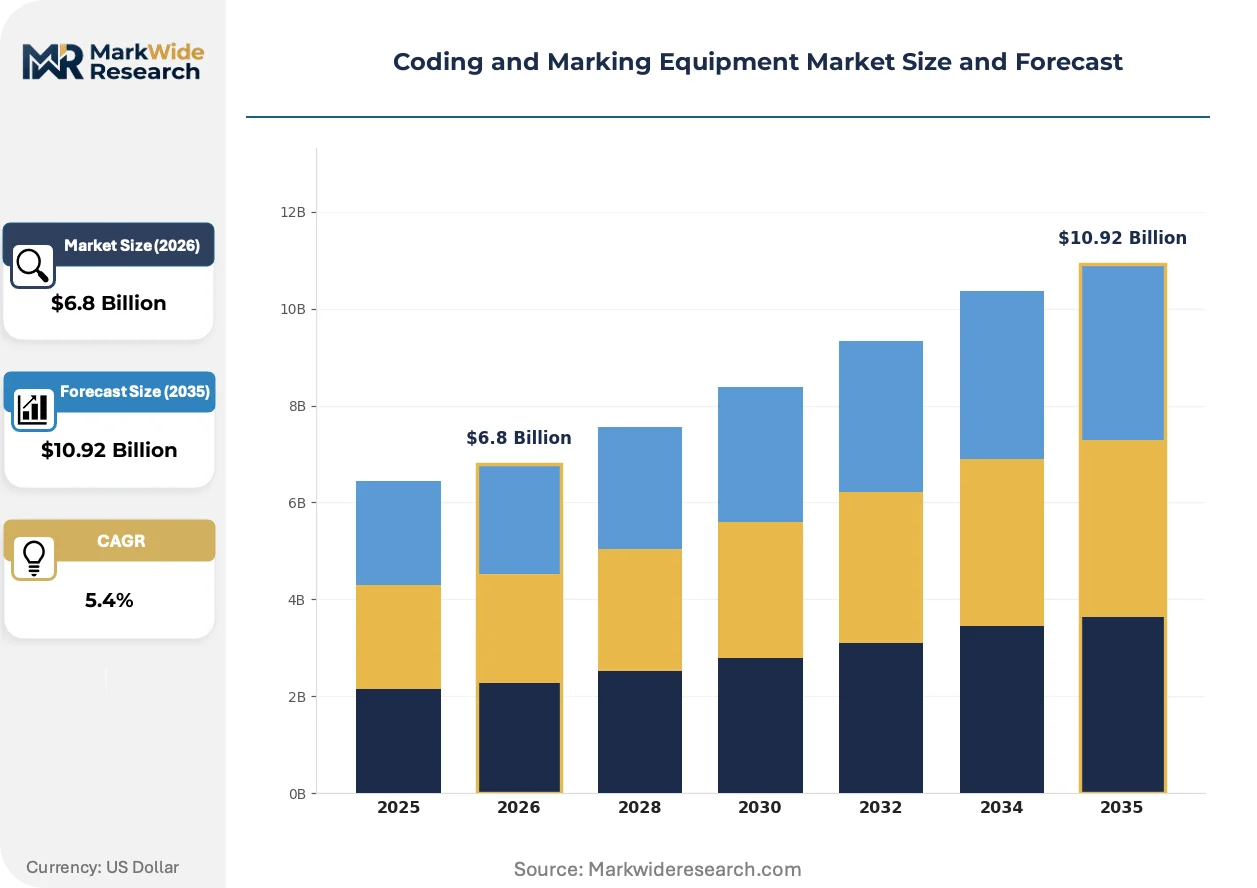
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, Thermal Transfer Printers, Labeling Machines Technology: Continuous Inkjet, Drop-On-Demand, Solid Ink, Laser Marking End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics Application: Product Identification, Expiry Date Printing, QR Code Generation, Brand Promotion |
| Companies Covered | Videojet Technologies, Markem-Imaje, Domino Printing Sciences, Danaher Corporation, Hitachi Ltd., Matthews International Corporation, Linx Printing Technologies, REA Elektronik GmbH, Leibinger Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coding and Marking Equipment Market Strategic Shifts & Innovations
Equipment architectures are pivoting from standalone printing units toward integrated traceability nodes that combine deposition hardware with vision verification and data management layers.
Ultraviolet LED curing systems are converging with inkjet print engines to enable instant polymerization on non-porous substrates without thermal damage. Food and dairy processors in the Netherlands and Denmark are adopting these configurations for direct marking on chilled packaging lines. This convergence is compressing drying tunnel footprints and eliminating heat-related substrate distortion defects.
REACH restrictions on solvent-based formulations are compelling ink suppliers to register bio-derived carrier alternatives through ECHA authorization pathways. Industrial laundries and chemical processors face reformulation costs exceeding EUR 50,000 per product line. German packaging equipment OEMs are responding by qualifying water-based and vegetable-oil ink systems for previously solvent-dependent applications.
Consolidated buying desks at multinational CPG conglomerates are unbundling hardware procurement from long-term consumables contracts. Category managers in Swiss and French headquarters now separate capital expenditure approvals from ongoing ink and solvent supply agreements. This behavioral shift is visible most acutely in beverage and personal care verticals where annual equipment volumes exceed 200 units per buyer.
Coding and Marking Equipment Market Segmentation
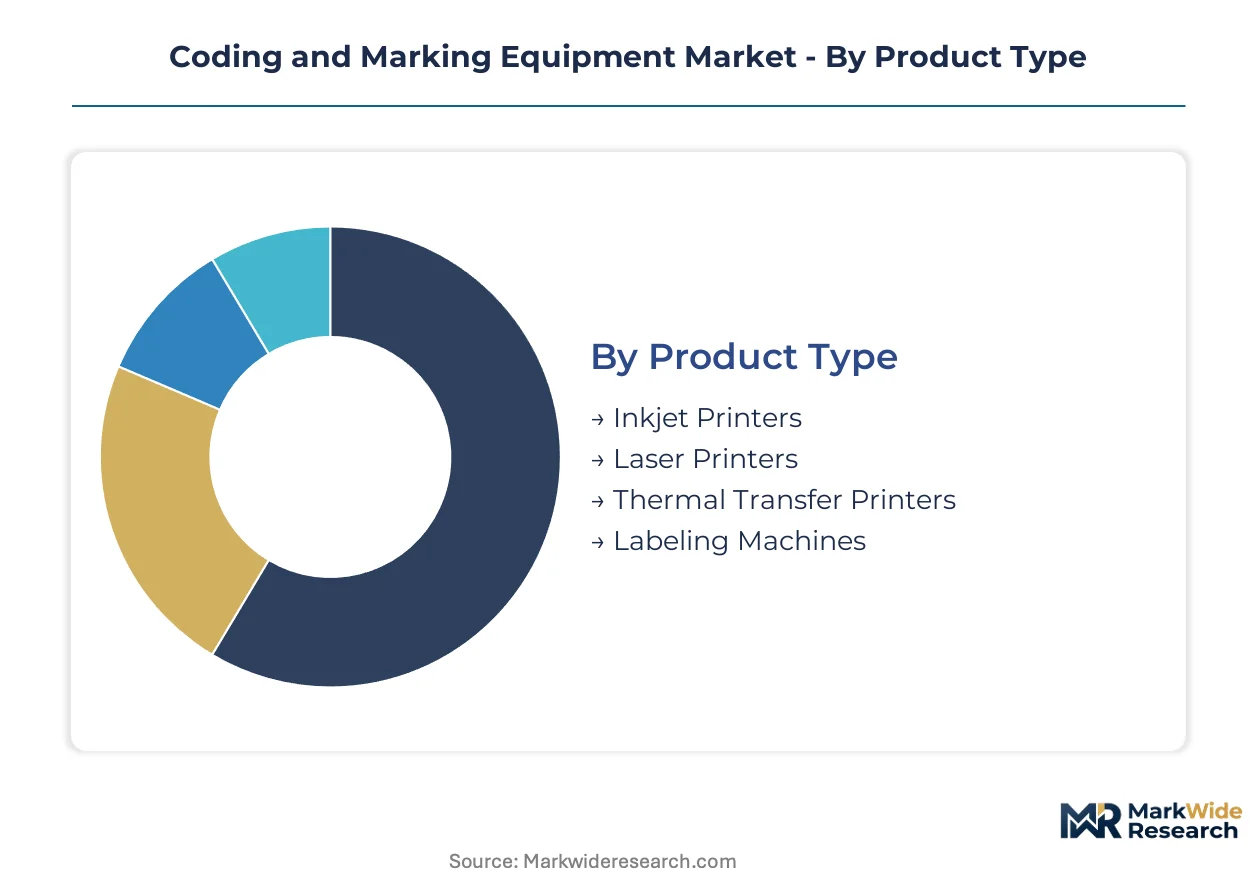
Equipment selection in coding and marking hinges on substrate compatibility, line speed requirements, and regulatory traceability mandates. Buyers segment procurement decisions across hardware technology, deposition method, target industry, and functional application to optimize total cost of ownership and compliance posture.
Product Type:
Capital intensity and consumables economics drive buyer selection between deposition technologies.
- Inkjet Printers:Continuous and drop-on-demand architectures deposit solvent-based or water-based formulations onto porous and non-porous surfaces at speeds exceeding 1,000 prints per minute. Beverage bottlers in Germany and Italy favor these systems for curved glass and PET substrates where rapid drying prevents smearing.
- Laser Printers:CO2 and fiber laser sources ablate permanent, chemical-resistant identifiers through thermal material modification without consumables. Electronics manufacturers in Japan and South Korea deploy these for miniature semiconductor components requiring lifetime traceability under harsh operating conditions.
- Thermal Transfer Printers:Ribbon-based thermal transfer delivers precise edge definition on flexible films and foils through wax-resin or resin formulations. European flexible packaging converters use these for batch coding on laminated snack pouches where ink adhesion challenges persist.
- Labeling Machines:Pressure-sensitive and shrink-sleeve applicators affix pre-printed labels to primary and secondary packaging. Pharmaceutical serialization lines integrate these with vision systems for EU Falsified Medicines Directive compliance.
Inkjet printers lead on installed base scale; laser printers lead on momentum in permanent marking applications.
Technology:
Deposition physics and curing mechanisms determine substrate range and operational cost structure.
- Continuous Inkjet:Pressurized fluid recirculation enables uninterrupted high-speed printing on irregular surfaces. German automotive suppliers apply these for under-hood component marking where oil contamination and temperature cycling demand robust formulation chemistry.
- Drop-On-Demand:Piezoelectric or thermal actuation ejects discrete droplets only when marking occurs, eliminating solvent evaporation losses. Cosmetics manufacturers in France select these for small-batch premium packaging lines requiring frequent changeovers.
- Solid Ink:Wax-based blocks melt on-demand and solidify instantly upon contact, producing durable marks without liquid solvent handling. Food processors in the Netherlands adopt these for chilled dairy packaging where moisture resistance and food-contact safety converge.
- Laser Marking:Photothermal ablation creates contrast through carbonization, foaming, or material removal depending on substrate composition. Battery cell manufacturers in China deploy fiber lasers for cylindrical lithium-ion formats to satisfy electric vehicle supply chain traceability mandates.
Continuous inkjet dominates high-volume throughput; laser marking expands most quickly in electronics and energy storage verticals.
End User:
Regulatory stringency and production velocity shape equipment specification requirements by vertical.
- Food & Beverage:Moisture-resistant formulations and high-speed deposition accommodate washdown environments and rapid line rates. Italian wine exporters and Dutch dairy cooperatives prioritize UV-curable systems for direct container marking.
- Pharmaceuticals:Serialization-ready architectures integrate printing, vision verification, and aggregation software for regulatory compliance. Indian formulation facilities serving European markets retrofit lines to meet CDSCO alignment with EU traceability standards.
- Electronics:Sub-millimeter precision and permanent marking withstand soldering fluxes, cleaning solvents, and thermal cycling. South Korean semiconductor fabs and Japanese component manufacturers specify laser systems for miniature surface-mount devices.
- Cosmetics:Premium aesthetic requirements and frequent SKU changeovers favor versatile deposition with quick-drying formulations. French and Swiss beauty brands invest in drop-on-demand inkjet for glass and plastic primary packaging.
Food and beverage commands the largest equipment volume; pharmaceuticals exhibits the steepest compliance-driven replacement cycle.
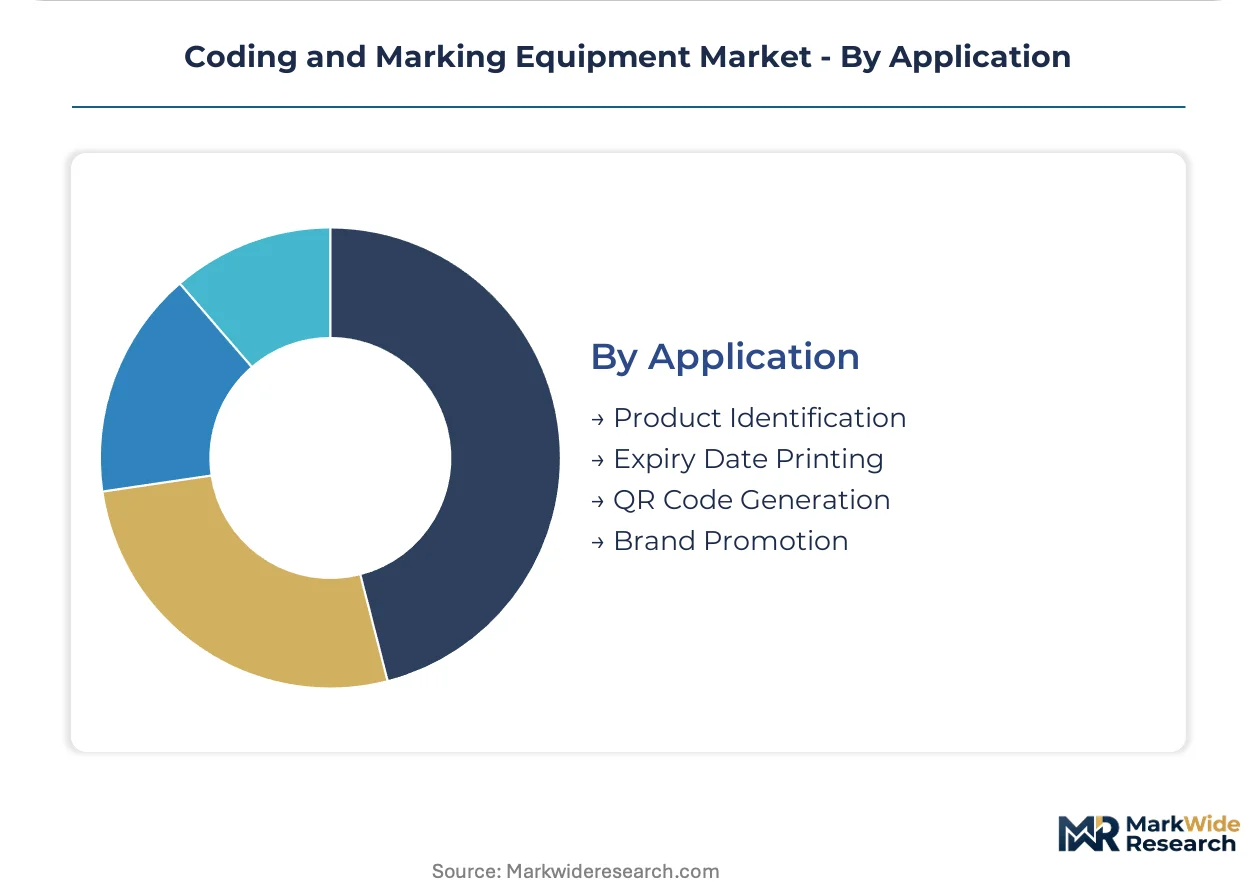
Application:
Information density and regulatory purpose determine hardware configuration and software integration depth.
- Product Identification:Alphanumeric text and linear barcodes communicate batch numbers, manufacturing dates, and origin data. Standard continuous inkjet configurations satisfy these requirements across commodity packaged goods.
- Expiry Date Printing:Legibility standards and contrast ratios ensure consumer-readable shelf-life information survives distribution handling. Thermal transfer and laser systems prevail where abrasion resistance proves critical.
- QR Code Generation:Two-dimensional matrix codes encode expanded datasets for supply chain visibility and consumer engagement. Pharmaceutical and electronics sectors mandate these for unit-level traceability and authentication.
- Brand Promotion:Logos, promotional messaging, and variable graphics enhance shelf presence and marketing personalization. Digital printing technologies enable versioned packaging for regional campaigns and limited editions.
Product identification represents the foundational use case; QR code generation gains share fastest as serialization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit cost-of-compliance gaps by relocating pharmaceutical packaging operations to jurisdictions with aligned regulatory deadlines but lower retrofit labor costs. This arbitrage reshapes equipment deployment patterns across production networks.
Germany
EU Falsified Medicines Directive enforcement compresses pharmaceutical equipment replacement cycles to eighteen-month windows. The Federal Institute for Drugs and Medical Devices validates serialization system deployments. Bavarian packaging automation clusters around Munich and Nuremberg drive continuous inkjet adoption for high-speed beverage bottling lines.
United States
FDA Drug Supply Chain Security Act traceability requirements expand demand for integrated coding and verification systems at pharmaceutical export facilities. The agency mandates unit-level serialization by 2023 enforcement deadlines. Midwestern dairy cooperatives in Wisconsin and Minnesota deploy UV-curable inkjet for direct container marking on chilled packaging lines.
China
Battery cell traceability mandates for electric vehicle supply chains open application vectors for laser marking on cylindrical lithium-ion formats. The National Medical Products Administration aligns pharmaceutical serialization standards with international frameworks. Yangtze River Delta manufacturing zones around Shanghai concentrate electronics miniaturization demand for permanent sub-millimeter identifiers.
India
CDSCO alignment with EU serialization standards creates retrofit demand at formulation facilities supplying regulated European markets. The Central Drugs Standard Control Organization mandates track-and-trace compliance for export-oriented pharmaceutical manufacturers. Gujarat and Maharashtra industrial corridors anchor contract manufacturing investments targeting compliance-driven equipment upgrades.
Japan
Semiconductor and component manufacturers specify laser systems for miniature surface-mount devices requiring lifetime traceability. The Ministry of Economy, Trade and Industry promotes manufacturing automation investments through subsidy programs. Kyushu and Chubu industrial zones concentrate precision electronics fabrication demanding permanent, chemical-resistant identifiers.
Coding and Marking Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-based fleet management and predictive maintenance software layers. The vendor base stratifies across three maturity tiers: integrated system architects bundling hardware with track-and-trace software, specialized deposition technology purists, and consumables-focused service operators. Dominant competitive moves include strategic partnerships between equipment OEMs and vision verification suppliers, plus geographic expansion into Indian pharmaceutical export corridors.
Among diversified technology conglomerates, Hitachi Ltd. and Danaher Corporation exemplify scale-driven diversification strategies spanning multiple industrial automation verticals. Matthews International Corporation represents the specialized marking systems archetype with concentrated exposure to funeral services and industrial identification segments. Videojet Technologies and Markem-Imaje occupy positions within the integrated solutions tier, anchoring recurring revenue models through consumables supply agreements. Domino Printing Sciences exemplifies the premium laser marking specialist archetype serving electronics and pharmaceutical compliance applications.
| Leading Market Players |
|---|
| Videojet Technologies |
| Markem-Imaje |
| Domino Printing Sciences |
| Danaher Corporation |
| Hitachi Ltd. |
| Matthews International Corporation |
| Linx Printing Technologies |
| REA Elektronik GmbH |
| Leibinger Group |
| Others |
Cost & Logistics Intelligence
Captive ink formulation capabilities at German and Japanese equipment OEMs anchor both supply security and pricing power in premium deposition segments. These integrated suppliers command margin premiums through proprietary solvent chemistry and printhead manufacturing, while third-party consumables vendors compete on price in standard-grade applications.
Pricing Analysis
Distributor margins of 15-25% separate factory gate pricing from end-user acquisition costs across European pharmaceutical and beverage verticals. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU FMD-compliant serialization systems commanding substantial premiums over basic batch-coding configurations. Cost compression in standard inkjet tiers is intensifying because consolidated CPG buying desks unbundle hardware from consumables contracts. Contract manufacturers in Indian pharmaceutical export corridors exhibit highest price sensitivity; electronics manufacturers in Japan and South Korea demonstrate lowest sensitivity due to permanent marking requirements and traceability mandates.
Supply Chain Analysis
Precision piezoelectric printhead manufacturing rests on Japanese and German specialty component suppliers, creating concentrated upstream dependency for deposition equipment assembly. Solvent-based ink formulations draw from petrochemical feedstocks and bio-derived carrier alternatives undergoing ECHA REACH authorization. Distribution runs through authorized equipment distributors in Europe and direct OEM sales teams in Asian manufacturing zones. Single-source vulnerability in specialty printhead supply exposes equipment lead times to capacity constraints at Kyocera and Konica Minolta production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in software-integrated traceability systems where recurring service revenue compounds hardware profitability. Cloud-based fleet management platforms enable vendors to capture subscription economics alongside traditional equipment sales.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty ink formulation and printhead refurbishment capabilities. Consolidate channel control by acquiring regional service providers in Indian pharmaceutical export corridors. Videojet Technologies and Markem-Imaje exemplify this path through captive consumables supply agreements that lock in recurring revenue streams. Threat from direct-to-film digital printing substitution in flexible packaging demands accelerated R&D investment in UV-LED curing convergence.
For New Entrants and Emerging Players: Launch via cloud-based predictive maintenance platforms targeting mid-tier pharmaceutical contract manufacturers lacking in-house mechatronics expertise. White-space opportunity concentrates in battery cell traceability for electric vehicle supply chains, where laser marking demand outpaces established vendor capacity. Target Indian CDSCO compliance retrofit wave at formulation facilities serving European export markets. Go-to-market angle: software-first subscription models that decouple capital expenditure from operational technology deployment.
For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics expertise scarcity intersects with retiring veteran technician cohorts. Long-term viability favors vendors with integrated software-hardware architectures capable of multi-standard pharmaceutical compliance. Acquisition target archetype: regional service operators with established pharmaceutical validation protocols and technician training infrastructure. Signal to watch: CDSCO enforcement acceleration triggering equipment replacement deadlines at Indian export-oriented formulation facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Formulation | Captive solvent chemistry secures margin capture and supply continuity against REACH regulatory shifts. |
| Cloud-Based Fleet Management Platform | Predictive maintenance subscriptions transform transactional hardware sales into recurring software revenue streams. |
| Multi-Standard Software Architecture | EU FMD, FDA DSCSA, and CDSCO compliance within single validation framework reduces pharmaceutical customer switching costs. |
| Battery Cell Traceability Specialization | Fiber laser marking on cylindrical lithium-ion formats captures electric vehicle supply chain expansion. |
| Regional Service Network Acquisition | Indian pharmaceutical corridor presence addresses CDSCO compliance retrofit demand with localized technician deployment. |
Research Approach
Bottom-up pharmaceutical and beverage manufacturing line modeling reconciled against top-down equipment supplier shipment tracking forms the analytical core of this study. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers at pharmaceutical manufacturers across Germany, India, and the United States combined with secondary validation from FDA DSCSA guidance documents, EMA delegated regulation texts, CDSCO circulars, and SEC 10-K filings from listed industrial automation conglomerates. Triangulation between demand-side capital expenditure plans and supply-side production capacity announcements ensures cross-verified volume estimates.
Input-output matrices map deposition technology adoption rates against substrate compatibility requirements, line speed specifications, and regulatory compliance deadlines across the projection horizon. Segmentation dimensions modeled include hardware technology type, deposition method physics, end-use vertical regulatory stringency, and functional application information density. CAGRs derive from equipment replacement cycle compression analysis and greenfield capacity addition tracking in pharmaceutical export corridors. Industry-specific forecast inputs incorporate EU FMD enforcement timeline acceleration and CDSCO alignment implementation pace.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalation affecting Japanese printhead component supply, abrupt REACH regulatory bans on solvent-based formulations without qualified bio-derived alternatives, and pandemic-scale manufacturing disruption compressing decision timelines beyond eighteen-month compliance windows. Forecasts reflect assumptions regarding harmonized international serialization standard adoption and sustained pharmaceutical export growth from Indian formulation facilities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Packer Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Global End-Of-Line Packaging Market