

Beverage Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Packaging Equipment Market Insights
The beverage packaging equipment sector is pivoting between high-speed aseptic lines for premium functional drinks and standardized mechanical fillers for commodity bottled water. Krones leverages its integrated blow-fill-seal platform to dominate aseptic dairy and juice segments. Sidel anchors its position through lightweight PET bottle handling systems that reduce material inputs for carbonated soft drink bottlers. KHS competes on rotary filler throughput rates exceeding 80,000 bottles per hour for large-scale mineral water operations.
Beverage packaging equipment encompasses machinery that forms, fills, seals, labels, and palletizes containers at speeds ranging from 1,000 to 120,000 units per hour, with aseptic variants maintaining sterile zones through hydrogen peroxide vapor barriers and laminar airflow isolation. Its primary purpose is to preserve product shelf stability while maximizing throughput and minimizing container weight. Bottle fillers occupy the largest installed base due to universal demand across water, carbonated, and alcoholic categories, though can sealers represent the fastest-growing segment as aluminum recycling economics improve and craft beverage startups adopt smaller-format canning lines. Automatic technology leads capital expenditure flows among multinational beverage manufacturers, while semi-automatic units sustain margin pools for co-packing companies serving regional craft brands with shorter production runs.
The EPA enforces emissions standards for refrigerants used in cold-fill systems, compelling equipment upgrades across US-based dairy and juice bottling facilities. The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon cooling agents, reshaping chiller specifications for European carbonated drink producers. China's MEE enforces GB standards for energy consumption in packaging machinery, affecting import eligibility for foreign equipment suppliers. Stakeholders must monitor how refrigerant phaseout timelines intersect with capital replacement cycles to avoid stranded asset risk in filling line investments.
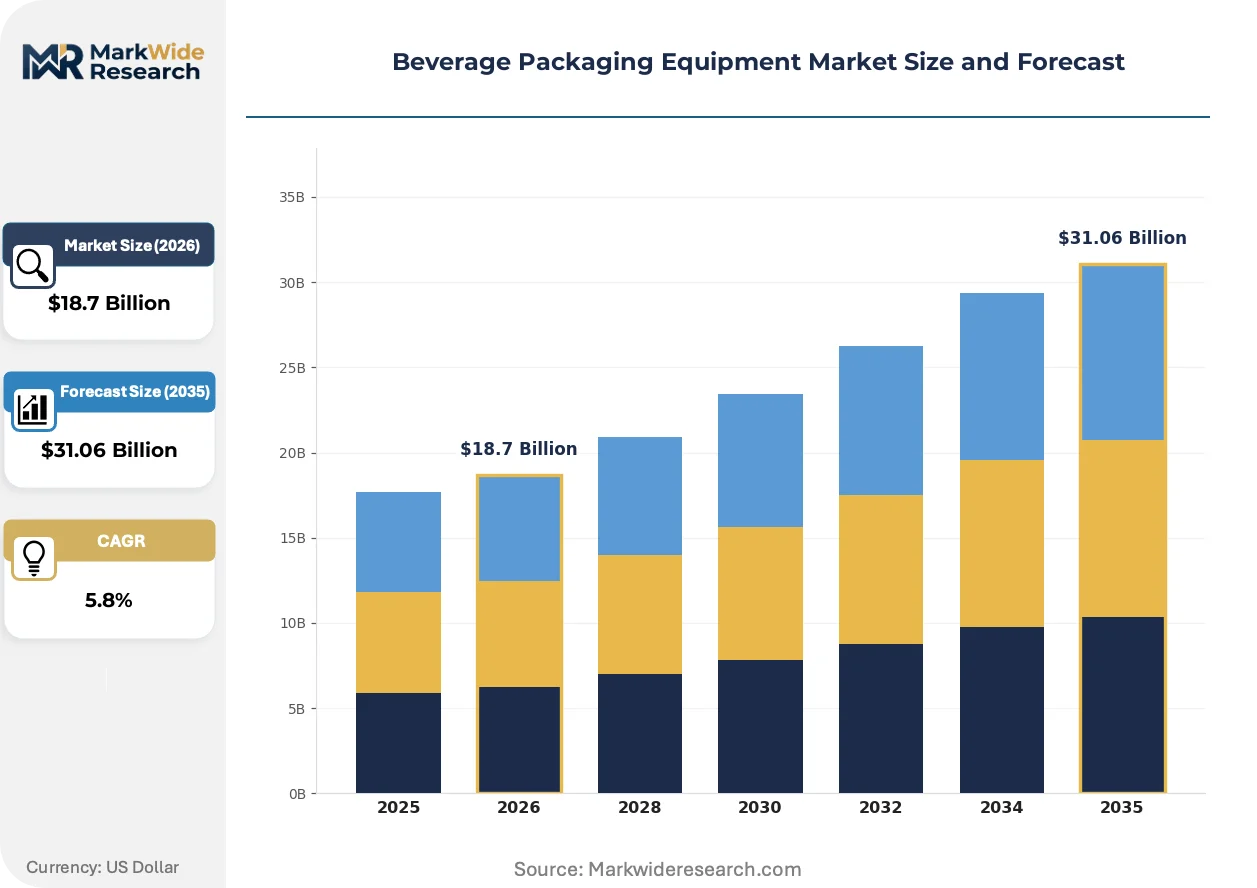
Market Dynamics
Refrigerant phaseout mandates under the EU F-Gas Regulation and EPA emissions standards are compressing capital replacement cycles for filling line cooling systems, forcing beverage producers to synchronize equipment upgrades with regulatory timelines rather than operational wear.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon cooling agents is accelerating retrofits in European carbonated drink production facilities, pulling forward demand for compliant chiller-integrated filling equipment.
- Southeast Asia contract bottling:Vietnam and Indonesia are scaling automated bottling lines as regional supply networks consolidate, creating concentrated demand for high-throughput rotary fillers.
- Aluminum recycling economics:Improved scrap recovery rates are lowering can production costs, enabling craft beverage startups to adopt smaller-format canning lines and expand packaging format diversity.
Market Restraints
- Stainless steel input volatility:Filler frame and contact surface fabrication depends on nickel-alloy steel grades subject to commodity price swings, compressing margin visibility for equipment manufacturers.
- Specialized component supply concentration:Precision servo motors and hydrogen peroxide vapor generators for aseptic barriers concentrate among German and Japanese suppliers, creating single-source vulnerability.
- Technical limitation in lightweighting:PET bottle wall thickness reduction below 8 grams for carbonated applications risks burst failure during high-speed rotary filling above 60,000 bottles per hour.
Strategic Opportunities
- Indonesia regional hub potential:Contract bottlers are establishing multi-brand filling campuses in Java to serve ASEAN markets, creating demand for flexible line configurations handling multiple beverage categories.
- US Inflation Reduction Act incentives:Energy-efficient packaging machinery investments qualify for tax credits under clean manufacturing provisions, improving project IRRs for dairy and juice bottlers.
- Digital twin convergence:Virtual commissioning of filling lines using physics simulation is reducing installation downtime by enabling offline operator training and recipe validation.
Industry Challenges
- Aseptic certification timeline:FDA validation for hydrogen peroxide-based sterile barrier systems requires 12-18 month qualification periods, delaying new line startups for functional beverage entrants.
- Legacy PLC integration friction:Brownfield dairy plants running Allen-Bradley SLC 500 controllers face protocol incompatibility with modern Ethernet/IP filling line networks, requiring costly gateway architectures.
- Multipack format complexity:Shrink-wrapped, carton-based, and clip-style carriers demand rapid changeover capability that mechanical collation systems struggle to execute below 3-minute intervals.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Packaging Equipment Market Trends and Innovations
Active packaging sterilization methods and predictive maintenance architectures are compressing the technical gap between aseptic and cold-fill lines while reshaping how producers justify capital expenditure on filling equipment.
Blow-fill-seal integration for aseptic PET bottles is consolidating the forming, sterilization, and filling functions into single-frame systems. Premium functional beverage producers in North America and Western Europe are adopting these platforms to eliminate intermediate warehousing of preforms. This consolidation is compressing the capital intensity gap between dairy aseptic lines and standard carbonated fillers.
The EU F-Gas Regulation mandates refrigerant containment and leak detection systems for cooling equipment above 40 kW cooling capacity. European carbonated soft drink bottlers must retrofit or replace glycol chillers on existing lines to maintain operating permits. Smaller regional bottlers in Poland and Romania face disproportionate compliance costs relative to line throughput, accelerating cooperative purchasing arrangements.
Equipment-as-a-service contracting is displacing outright purchase for mid-scale craft beverage producers. Third-party financing entities now own filling line assets and charge per-unit throughput fees, transferring utilization risk from brewers to capital providers. This model is most visible in the US Pacific Northwest and Colorado craft brewing clusters where production volume uncertainty deters traditional capex commitments.
Beverage Packaging Equipment Market Segmentation
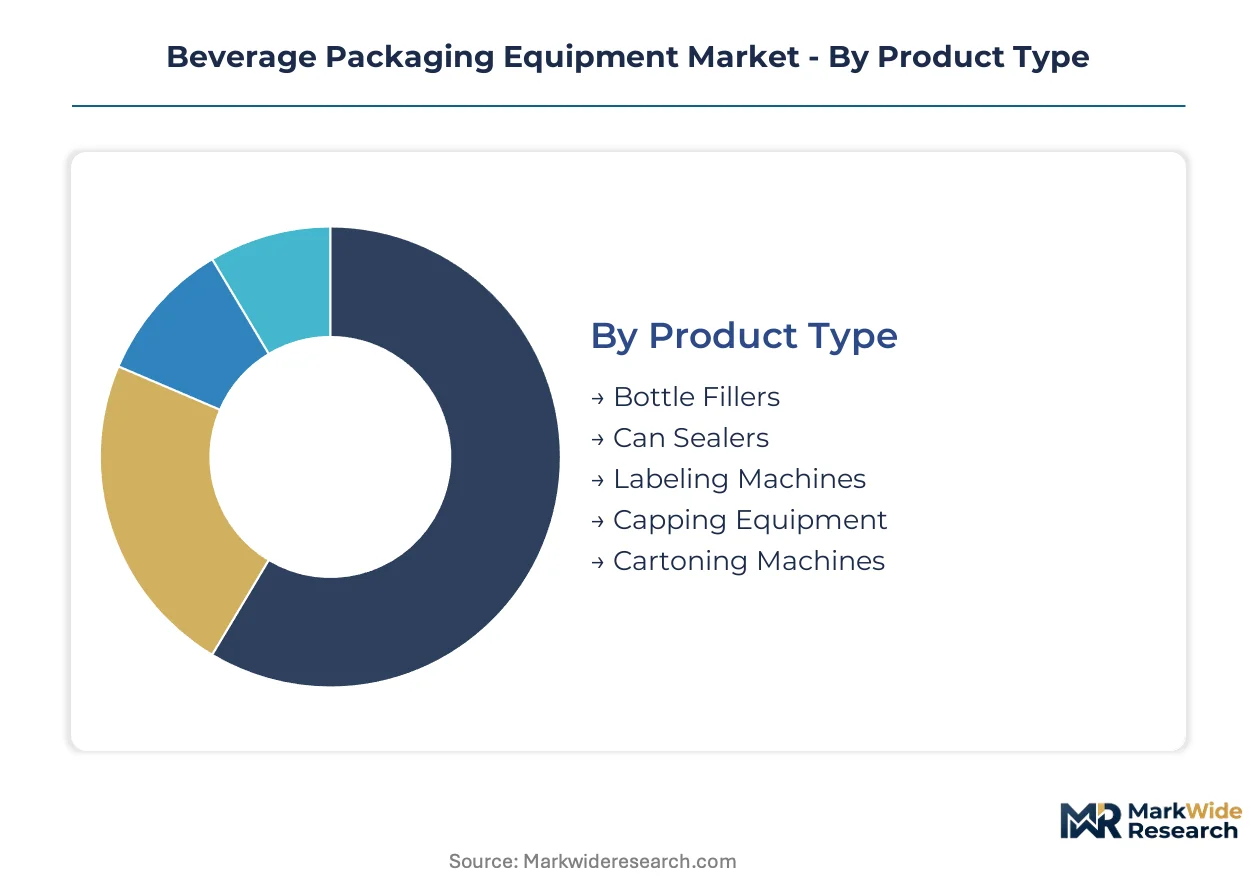
Beverage packaging equipment procurement hinges on throughput requirements, regulatory compliance timelines, and container format flexibility. Equipment buyers prioritize line integration depth over standalone unit economics when scaling multi-brand operations.
Product Type:
Capital allocation intensity varies by container handling complexity and sterile barrier requirements.
- Bottle Fillers:Rotary gravity and pressure fillers dominate carbonated and still water operations, handling PET and glass formats at speeds exceeding 60,000 units per hour. Demand concentrates among Southeast Asian contract bottlers retrofitting lines for EU F-Gas refrigerant compliance. Stainless steel contact surfaces and servo-driven valve timing systems define technical specifications.
- Can Sealers:Double-seam rotary seamers for aluminum beverage cans are gaining traction as craft breweries and seltzer producers adopt smaller-format packaging. Aluminum recycling economics in North America and Western Europe are compressing per-unit packaging costs for regional beverage startups.
- Labeling Machines:Pressure-sensitive and sleeve applicators handle wraparound and full-body decoration for premium functional drinks.
- Capping Equipment:Magnetic torque systems ensure seal integrity for carbonated products under internal pressure.
- Cartoning Machines:Wraparound and tray-forming systems consolidate multipacks for retail distribution.
Bottle fillers lead on scale; can sealers lead on momentum.
Technology:
Automation depth determines labor substitution economics and changeover flexibility.
- Automatic:Fully integrated lines with PLC-controlled servo drives and HMI recipe management dominate multinational beverage manufacturer capex. These systems synchronize blow molding, filling, and labeling through Ethernet/IP networks, reducing changeover intervals below 15 minutes for high-SKU portfolios.
- Semi-Automatic:Operator-assisted units sustain margin pools for co-packing companies serving regional craft brands with shorter production runs and volatile demand patterns. Lower capital thresholds and modular upgrade paths appeal to beverage startups testing market traction.
- Rotary:Circular carousel configurations maximize throughput for high-volume carbonated and water operations.
- Linear:Straight-line layouts suit lower-speed applications with frequent format changes.
- Inline:Compact footprint systems fit constrained brownfield dairy and juice facilities.
Automatic technology commands the largest capital flows; semi-automatic units are expanding most quickly in craft beverage clusters.
Application:
Shelf stability requirements and filling temperature regimes dictate equipment sterilization architecture.
- Carbonated Drinks:Cold-fill rotary systems with glycol chilling maintain dissolved CO2 retention during high-speed bottling. EU F-Gas refrigerant phaseout mandates are accelerating chiller retrofits among Polish and Romanian regional bottlers facing disproportionate compliance costs.
- Bottled Water:Non-carbonated mineral and purified water lines prioritize lightweight PET handling and cap torque consistency over sterile barriers. Large-scale operations in Vietnam and Indonesia are scaling automated lines as contract bottlers consolidate ASEAN supply networks.
- Juices:Aseptic hydrogen peroxide vapor barriers extend shelf life for ambient distribution.
- Alcoholic Beverages:Beer and spirits fillers manage foam control and oxygen pickup sensitivity.
- Dairy Drinks:Extended shelf-life aseptic lines require FDA-validated sterile zones.
Carbonated drinks anchor installed base value; bottled water applications are climbing the fastest in emerging Asian markets.
End User:
Volume predictability and brand ownership structure shape financing and equipment configuration decisions.
- Beverage Manufacturers:Multinational brand owners specify integrated blow-fill-seal platforms for premium functional drinks, eliminating intermediate preform warehousing. These buyers prioritize throughput rates exceeding 80,000 bottles per hour and digital twin commissioning to compress installation timelines.
- Co-Packing Companies:Third-party operators serving multiple brands demand rapid changeover capability across container formats and beverage categories. Equipment-as-a-service contracting is displacing outright purchase in US Pacific Northwest and Colorado craft brewing clusters.
- Contract Bottlers:Dedicated filling campuses in Java, Indonesia are emerging as ASEAN regional hubs.
- Beverage Startups:Early-stage producers favor semi-automatic canning lines with lower capital thresholds.
Beverage manufacturers lead on absolute equipment spend; co-packing companies are gaining share fastest through service model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany's mechanical belt and Vietnam's industrial zones anchor equipment deployment decisions. Regional demand patterns diverge sharply between mature markets retrofitting for refrigerant compliance and emerging economies building greenfield capacity.
United States
Contract bottlers in Colorado and the Pacific Northwest are scaling semi-automatic canning lines for craft beverage startups. EPA emissions standards for refrigerants in cold-fill systems are compelling dairy and juice facilities to accelerate chiller upgrades. Equipment-as-a-service contracting is displacing outright purchase in these craft brewing clusters.
Germany
Precision servo motor and hydrogen peroxide vapor generator suppliers concentrate in Baden-Württemberg and Bavaria, creating single-source vulnerability for aseptic barrier components. The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon cooling agents, reshaping chiller specifications for carbonated drink producers. Krones leverages its integrated blow-fill-seal platform from headquarters operations to dominate regional dairy and juice segments.
Vietnam
Regional supply network consolidation is driving automated bottling line expansion among contract bottlers serving ASEAN markets. The country's national standards body enforces energy consumption benchmarks for imported packaging machinery, affecting eligibility for foreign equipment suppliers. Ho Chi Minh City industrial zones are seeing concentrated demand for high-throughput rotary fillers exceeding 60,000 bottles per hour.
Indonesia
Multi-brand filling campuses are emerging in Java to serve ASEAN markets, creating demand for flexible line configurations across beverage categories. The Ministry of Industry promotes domestic manufacturing incentives for capital equipment procurement. Surabaya and Jakarta industrial corridors are attracting regional hub investments from multinational beverage manufacturers.
China
GB standards for energy consumption in packaging machinery enforced by MEE are affecting import eligibility for foreign equipment suppliers. Domestic blow-fill-seal platform adoption is compressing the capital intensity gap between dairy aseptic lines and standard carbonated fillers. Yangtze River Delta manufacturing zones are retrofitting legacy filling lines to meet dual carbon goals.
Beverage Packaging Equipment Market Competitive Landscape
Top-tier vendors anchor integrated system supply, while mid-scale fabricators compete on modular component specialization. The vendor base stratifies between full-line integrators commanding premium pricing for aseptic platforms and regional specialists serving shorter production runs. Three archetypes dominate: blow-fill-seal integrators, lightweight PET handling specialists, and rotary throughput maximizers. Competitive moves concentrate on digital twin commissioning capabilities and equipment-as-a-service financing structures.
Within the integrated platform tier, Krones AG and KHS GmbH exemplify full-line system architecture, while Sidel S.A. occupies a position emphasizing PET bottle handling specialization. These European-based entities represent contrasting strategic postures—Krones anchors aseptic dairy and juice segments through consolidated forming-filling-sealing functions, KHS exemplifies scale-driven rotary filler throughput maximization, and Sidel situates within lightweighting technology corridors for carbonated soft drink applications. Their collective positioning illustrates how geographic proximity to precision component suppliers in Germany and Switzerland reinforces technical specification leadership.
| Leading Market Players |
|---|
| Krones |
| KHS |
| Sidel |
| Tetra Pak |
| Syntegon Technology |
| GEA Group |
| Coesia |
| SACMI |
| Barry-Wehmiller |
| Others |
Pricing and Supply Chain Analysis
Precision mechanical engineering talent clusters in Baden-Württemberg and Bavaria compress labor-cost differentials between German-built aseptic platforms and Asian-assembled standardized fillers, widening pricing-tier spreads across premium blow-fill-seal systems and economy rotary lines.
Pricing Analysis
Bundled equipment-as-a-service contracts are displacing unbundled outright purchase across mid-scale craft beverage producers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Price erosion runs through economy rotary fillers as Vietnamese and Indonesian contract bottlers consolidate procurement volumes. Co-packing companies serving regional craft brands exhibit highest price sensitivity, while multinational beverage manufacturers prioritize throughput rates over unit economics.
Supply Chain Analysis
Stainless steel contact surface fabrication draws from German and Japanese specialty metal suppliers, with precision servo motors and hydrogen peroxide vapor generators for aseptic barriers anchoring in Baden-Württemberg component clusters. Nickel-alloy steel grades and precision electromechanical subsystems constitute critical input dependencies. Single-source vulnerability in hydrogen peroxide vapor generator supply creates structural risk for aseptic line builders. Distribution runs through direct OEM sales for multinational accounts and regional distributor networks for mid-scale craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas refrigerant phasedown timeline compresses capital replacement cycles faster than wear-based depreciation in European carbonated bottling, while Southeast Asian greenfield expansion offers cost-arbitrage opportunities absent legacy compliance burdens.
For Market Incumbents: Hedge refrigerant-phaseout stranded asset risk by accelerating chiller-integrated filling equipment R&D ahead of EU enforcement timelines. Secure captive supply of precision servo motors through backward integration into German component clusters. Prioritize digital twin commissioning capabilities to compress installation timelines for multinational beverage manufacturer accounts.
For New Entrants and Emerging Players: The US Inflation Reduction Act clean manufacturing tax credits open a window for energy-efficient packaging machinery entrants targeting dairy and juice bottlers in Colorado and Pacific Northwest craft brewing clusters. Target semi-automatic canning line segments where equipment-as-a-service contracting displaces traditional capex. Pursue modular upgrade path positioning to capture beverage startup volume uncertainty.
For Investors and Strategic Acquirers: Contract bottlers establishing ASEAN regional hubs are the most active acquirer in this space, consolidating multi-brand filling campuses in Java. Long-term viability hinges on exposure to emerging market greenfield expansion rather than mature market retrofit cycles. Watch FDA aseptic certification timeline delays as inflection indicator for functional beverage entrant demand compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Transfers utilization risk from craft brewers to capital providers in US Pacific Northwest clusters. |
| Digital Twin Commissioning | Reduces installation downtime through offline operator training and recipe validation. |
| Backward Integration into Servo Motors | Secures supply of precision components concentrated among German and Japanese suppliers. |
| Flexible Line Configuration Development | Enables multi-brand filling campuses in Indonesia to handle diverse beverage categories. |
| Refrigerant-Compliant Chiller Retrofit | Maintains operating permits for European carbonated soft drink bottlers under EU F-Gas Regulation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and contract bottler operations directors with secondary validation through SEC filings, customs and trade data, equipment manufacturer technical specifications, and regulatory filings from EPA and EU F-Gas implementing bodies. Bottom-up installed base modeling and top-down capital expenditure flow analysis provided cross-verification.
Historical reference periods anchored projections across the analysis window, with segmentation dimensions spanning equipment type, automation depth, application temperature regime, and end-user ownership structure. CAGRs derived from regression against macroeconomic indicators and industry-specific drivers including refrigerant phaseout timelines, aluminum recycling economics, and contract bottling network consolidation patterns.
Revisions become necessary when regulatory enforcement timelines shift, stainless steel commodity volatility exceeds historical bands, or aseptic certification backlogs extend beyond standard qualification periods. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.