
 Triangle Tea Bag Packaging Machinery Market | 2026-2036
Triangle Tea Bag Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Triangle Tea Bag Packaging Machinery Market Outlook
Direct-to-brand equipment financing is rewriting how mid-sized tea processors acquire packaging lines. IMA S.p.A. leverages its European service network to sustain long-term contracts with Italian and German specialty tea houses. Tecpacking Group anchors its position through integrated after-sales support across Southeast Asian markets. Xiamen Sengong Packing Equipment Co., Ltd competes aggressively on delivery speed for automatic systems destined for domestic Chinese brands.
Triangle tea bag packaging machinery forms, fills, and seals pyramid-shaped sachets using heat-sealed nonwoven or filter paper webs at speeds ranging from 60 to 400 bags per minute depending on automation tier. These machines serve commercial tea processors seeking shelf differentiation and optimized infusion geometry in premium product tiers. Automatic systems command the widest installed base due to labor cost pressures at scale, while biodegradable film compatibility requirements are pushing fastest upgrade demand across European food manufacturers. Vertical form fill seal technology dominates throughput-intensive operations, though heat sealing architectures retain margin strength in specialty and organic certification segments where seal integrity validation carries regulatory weight.
FDA food contact substance notifications govern nylon and PLA film approvals for US-bound tea products, while EU REACH and F-Gas Regulation constrain solvent-based adhesive and refrigerant choices in sealing subsystem design. China's SAMR enforces GB standards for food machinery hygiene that export-oriented builders must satisfy for domestic sale. Machinery buyers should monitor how divergent biodegradable film certification timelines across FDA, EFSA, and China's national food safety regulator reshape equipment specification requirements and retrofit obligations.
Market Dynamics
Biodegradable packaging mandates across the European Union and Japan are forcing machinery replacement cycles faster than historical depreciation schedules, while PLA film compatibility requirements reshape equipment specifications at the component level.
Growth Catalysts
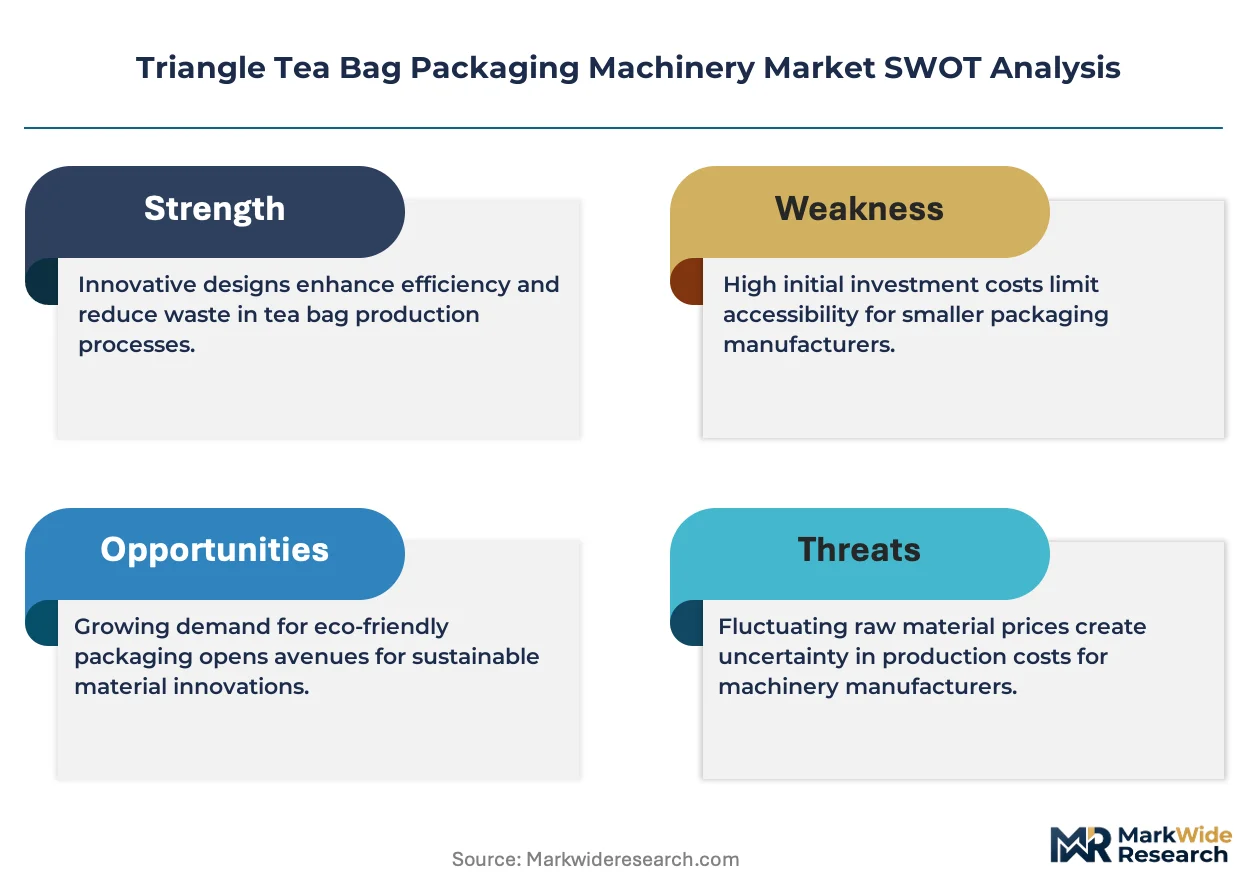
- EU F-Gas Regulation:Refrigerant constraints in sealing subsystems accelerate heat-sealing technology upgrades across German and Italian specialty tea houses.
- Fujian-Zhejiang manufacturing cluster:Contract manufacturers in these provinces serve export-oriented private labelers with integrated packaging and logistics capabilities.
- Pyramid geometry optimization:Shelf differentiation and infusion performance advantages pull premium tea brands toward automated triangle-forming equipment.
Market Restraints
- PLA film supply concentration:Biodegradable film availability constrains through Chinese and Thai resin suppliers, creating input cost volatility for machinery retrofits.
- Seal integrity validation costs:Organic certification segments require documented thermal profiling that adds compliance overhead to smaller processor operations.
- Speed-throughput tradeoffs:Vertical form fill seal architectures sacrifice seal precision at rates above 300 bags per minute, limiting adoption in regulatory-heavy markets.
Strategic Opportunities
- India FSSAI biodegradable mandates:Pending food packaging regulations create whitespace for equipment financing models targeting mid-sized Assam and Darjeeling processors.
- Direct-to-brand equipment leasing:Non-traditional financing channels bypass traditional banking constraints for Southeast Asian contract manufacturers.
- Servo-driven heat sealing + IoT monitoring convergence:Real-time seal validation enables predictive maintenance contracts that extend machinery lifecycle revenue.
Industry Challenges
- Multi-jurisdiction certification timelines:Divergent FDA, EFSA, and SAMR biodegradable film approvals force equipment builders to maintain parallel specification tracks.
- Legacy pneumatic system integration:Southeast Asian tea processors face retrofit complexity when upgrading from mechanical to servo-controlled sealing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triangle Tea Bag Packaging Machinery Market |
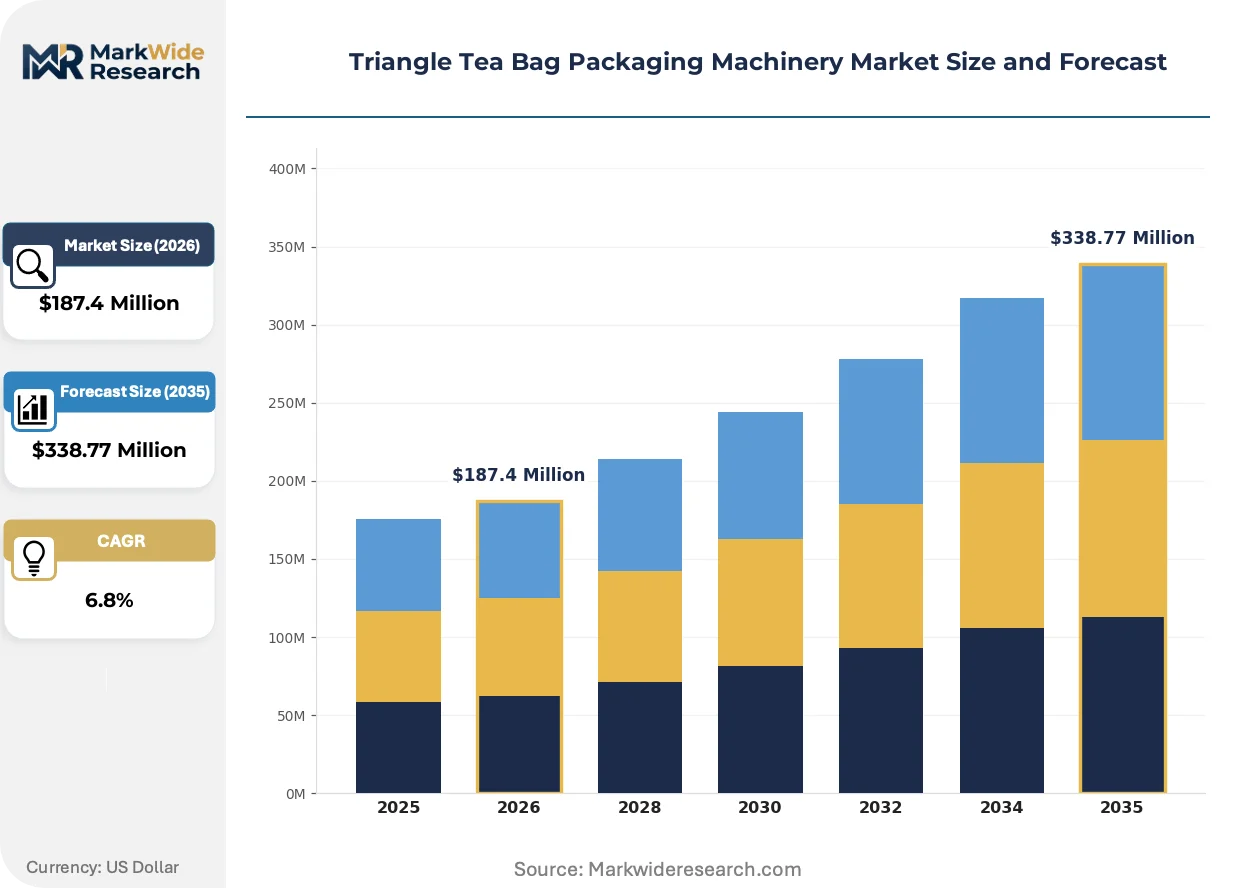
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Specialized Technology: Vertical Form Fill Seal, Horizontal Flow Wrapper, Heat Sealing, Vacuum Packing End User: Food Manufacturers, Tea Distributors, Private Labelers, Retailers Packaging Material: Paper, Nylon, Cotton, Biodegradable Film |
| Companies Covered | CAMA (LuoYang) Electromechanic Co., Ltd, E.C. Packtech Machines Pvt. Ltd, Grace Food Processing & Packaging Machinery, Fuso International, Tecpacking Group, Xiamen Sengong Packing Equipment Co., Ltd, Sidsam Formilan Machines Pvt. Ltd, IMA S.p.A., Dph International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triangle Tea Bag Packaging Machinery Market Strategic Shifts
Digital thread technologies are compressing the gap between equipment specification and operational validation, while regulatory divergence across food contact substance frameworks forces builders toward modular, jurisdiction-swappable subsystems.
Ultrasonic sealing modules are virtualizing the traditional heat-bar architecture in high-throughput lines. Japanese and German premium tea processors are adopting these systems at pilot scale before full line replacement. The technology is virtualizing thermal validation documentation, compressing organic certification audit cycles from weeks to days.
EU REACH substance restrictions on solvent-based adhesives are forcing sealant formulation changes that alter heat-sealing temperature profiles. Machinery builders must recalibrate thermal control algorithms to accommodate lower-temperature sealant activation thresholds. Specialty organic certification segments in Germany and Switzerland are most affected, with processors pre-qualifying equipment against anticipated 2026 substance list expansions.
After-sales service unbundling is fragmenting traditional maintenance contracts into component-level subscription tiers. Southeast Asian contract manufacturers are purchasing sealing subsystem monitoring separately from mechanical maintenance, displacing bundled OEM service agreements. This pattern is most visible in Vietnam and Indonesia, where third-party technical service networks have matured faster than manufacturer-direct coverage.
Triangle Tea Bag Packaging Machinery Market Segmentation
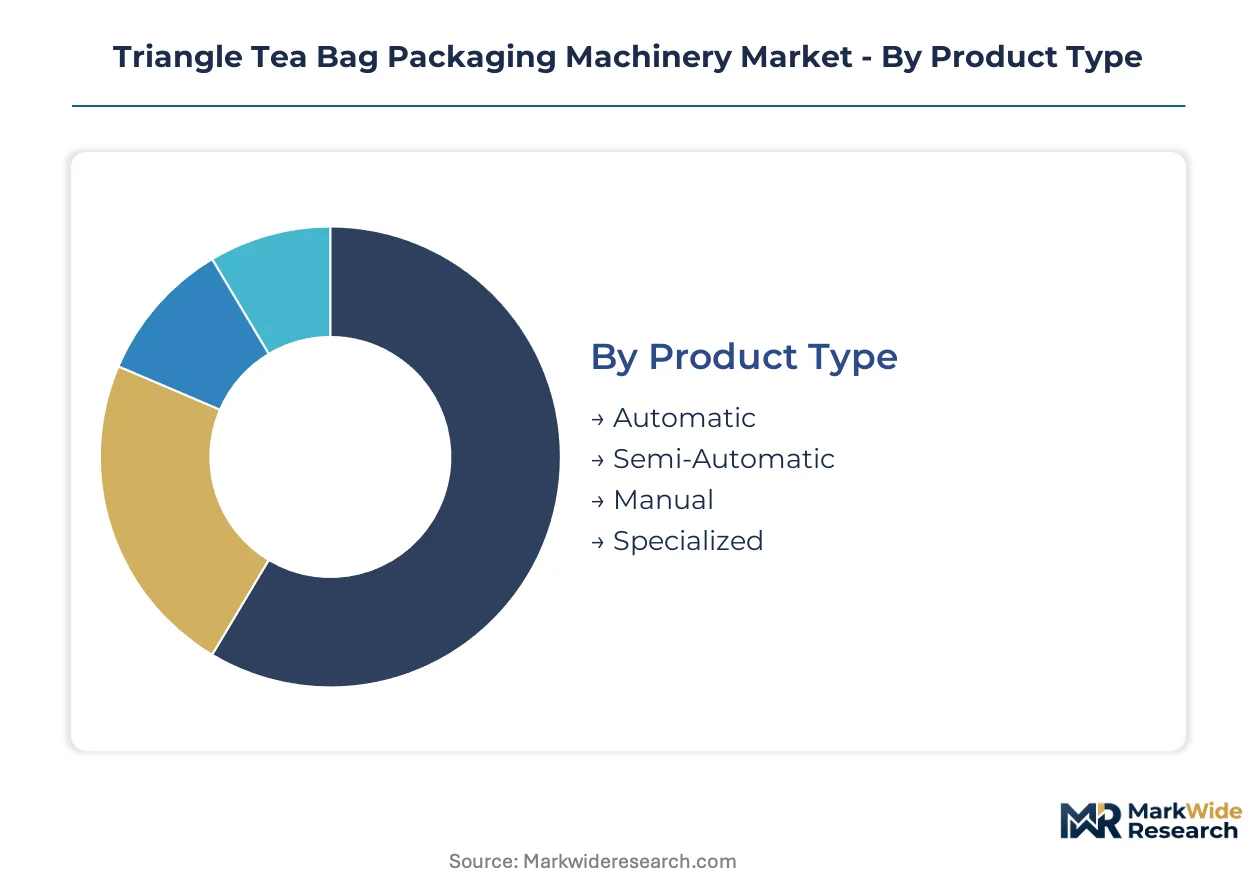
Segmentation in triangle tea bag packaging machinery reveals how automation tier, sealing architecture, and material compatibility reshape procurement patterns across specialty tea processors. Equipment specification diverges sharply between export-oriented contract manufacturers and domestic premium brands, with regulatory compliance requirements driving specification fragmentation.
Product Type:
Cost tier determines installed base distribution and replacement cycle velocity across tea processing operations.
- Automatic:Servo-controlled systems form, fill, and seal 200-400 bags per minute using programmable logic controllers. Labor cost pressures at scale in China's Fujian province pull contract manufacturers toward these configurations.
- Semi-Automatic:Operator-fed machines achieve 60-120 bags per minute with manual web loading. Mid-sized Assam and Darjeeling processors in India favor this tier for flexibility across small-batch specialty runs.
- Manual:Foot-pedal or hand-cranked units serve micro-roasters and tea house retail operations. Japanese specialty tea houses deploy these for ceremonial-grade product lines.
- Specialized:Custom-configured systems accommodate non-standard pyramid geometries or dual-chamber sachets. German organic certification segments specify these for seal integrity documentation requirements.
Automatic systems command the established base. The steepest expansion runs through specialized configurations.
Technology:
Sealing architecture selection hinges on throughput requirements against regulatory validation burdens.
- Vertical Form Fill Seal:Continuous web-fed systems maximize output for high-volume export operations. Fujian-Zhejiang cluster manufacturers deploy these for private label contracts serving European retailers.
- Heat Sealing:Thermal-bar architectures deliver precise temperature profiling for organic certification segments. Swiss and German specialty tea houses specify these for documented seal integrity.
- Horizontal Flow Wrapper:Pillow-pack configurations serve secondary overwrapping applications. Italian premium brands use these for gift-box presentation layers.
- Vacuum Packing:Modified atmosphere sealing extends shelf life for sensitive botanical blends. Japanese matcha processors favor these for oxidation-sensitive products.
Heat sealing retains margin strength in certification-heavy segments. Vertical form fill seal gains share fastest in throughput-intensive operations.
End User:
Customer type shapes equipment financing approach and after-sales service expectations.
- Food Manufacturers:Integrated beverage companies specify fully automated lines with IoT-enabled predictive maintenance. EU F-Gas Regulation compliance drives replacement cycles among German and Italian operators.
- Tea Distributors:Consolidators serving multiple origin sources prioritize quick-changeover flexibility. Southeast Asian contract manufacturers in Vietnam and Indonesia dominate this segment.
- Private Labelers:White-label producers for retail chains require rapid format switching across SKUs. China's export-oriented manufacturers in Zhejiang anchor this demand.
- Retailers:Direct-store-brand operators favor compact footprint systems for captive production. Japanese department store tea counters specify these for in-house blending operations.
Food manufacturers anchor equipment revenue. Private labelers are expanding most quickly as retail consolidation accelerates.
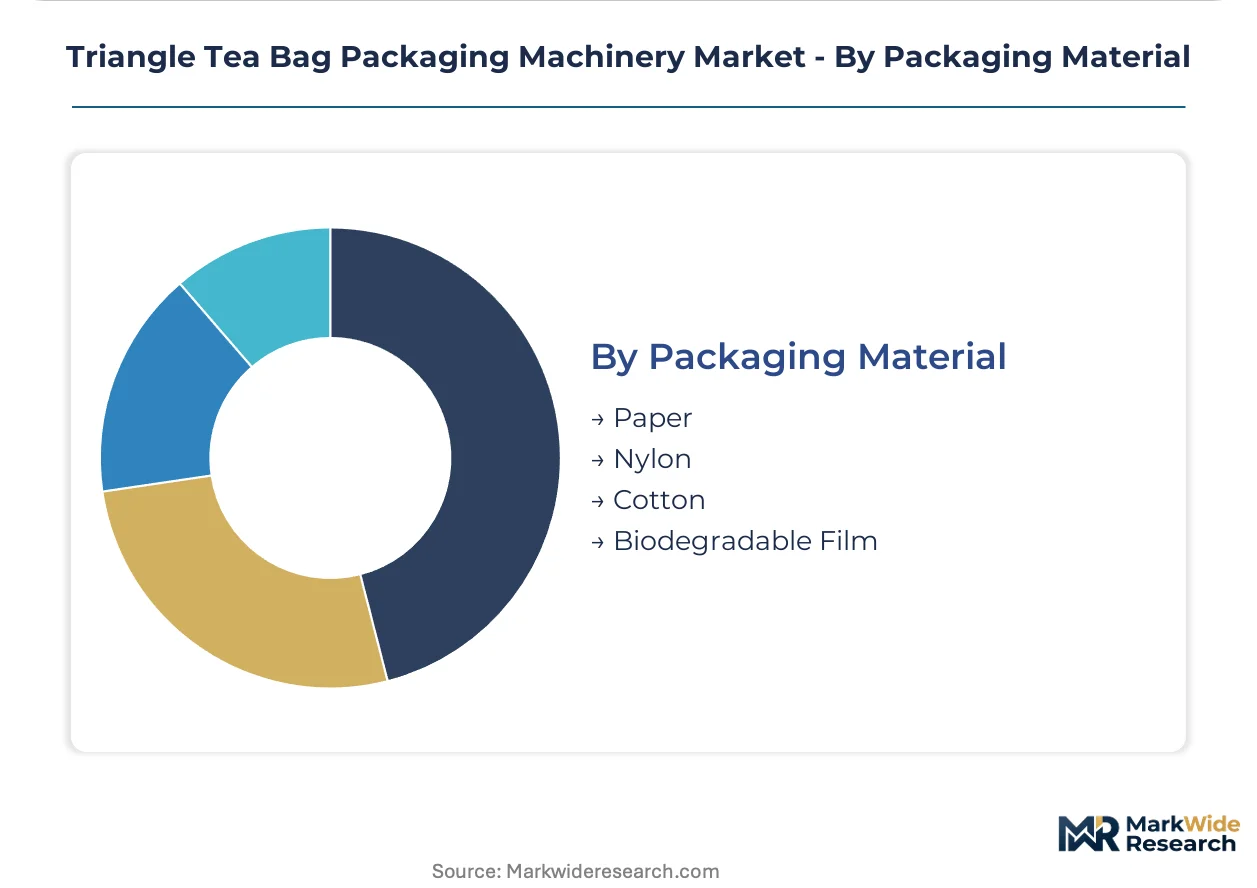
Packaging Material:
Material specification determines sealing subsystem calibration and regulatory pre-qualification burden.
- Biodegradable Film:PLA and cellulose-based webs require modified temperature profiles and dwell times. EU REACH substance restrictions force equipment recalibration among German and Swiss processors.
- Paper:Filter paper webs remain standard for conventional pyramid sachets. China's domestic premium brands specify these for cost-controlled automatic lines.
- Nylon:Synthetic mesh delivers visual transparency for whole-leaf presentation. FDA food contact substance notifications govern US-bound deployments.
- Cotton:Natural fiber webs serve organic certification segments requiring plastic-free claims. Japanese specialty tea houses specify these for ceremonial product tiers.
Paper commands the established base. Biodegradable film climbs the fastest as mandates spread across European and Japanese markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics corridors underwrite Europe's role as the primary machinery import gateway for biodegradable packaging retrofits. Rail links connecting China's Yangtze River Delta manufacturing clusters to European terminals compress delivery timelines for automated sealing systems.
Germany
Specialty tea houses in Bavaria and Baden-Württemberg are retrofitting heat-sealing lines to meet EU F-Gas Regulation refrigerant constraints. ECHA substance restrictions under REACH force sealant formulation changes that alter equipment thermal profiles. Stuttgart-based machinery service networks support predictive maintenance contracts for organic certification segments.
China
Fujian and Zhejiang provinces anchor contract manufacturing for export-oriented private labelers serving European retailers. SAMR enforces GB standards for food machinery hygiene that domestic builders must satisfy. Xiamen's port infrastructure enables rapid deployment of automatic systems to Southeast Asian distributors.
Japan
METI biodegradable packaging mandates accelerate replacement cycles among Tokyo and Osaka premium tea processors. JIS standards govern thermal validation documentation for ceremonial-grade product lines. Nagoya industrial corridors concentrate servo-driven sealing subsystem fabrication for domestic brands.
India
FSSAI pending regulations create equipment financing whitespace for Assam and Darjeeling mid-sized processors. BIS certification requirements shape import specifications for heat-sealing architectures. Mumbai's financial infrastructure supports direct-to-brand leasing models bypassing traditional banking constraints.
Italy
Organic certification segments in Lombardy and Piedmont specify heat-sealing equipment for documented seal integrity. EU Green Deal packaging directives force machinery builders toward PLA film compatibility. Milan's design engineering clusters specialize in custom pyramid geometry configurations for gift-box presentation tiers.
Triangle Tea Bag Packaging Machinery Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying sealing subsystems and servo modules. The vendor base organizes around three strategic archetypes: European full-line builders with service networks, Chinese fabricators competing on delivery velocity, and Japanese precision specialists targeting premium certification segments. Competitive moves concentrate on geographic expansion through distributor partnerships and technology licensing for biodegradable film compatibility.
Among European platform integrators, IMA S.p.A. and Dph International GmbH exemplify the service-network-dependent archetype, while Tecpacking Group anchors the Southeast Asian contract manufacturing support tier. Xiamen Sengong Packing Equipment Co., Ltd occupies a position within the China-based delivery-speed competitive vector.
| Leading Market Players |
|---|
| CAMA (LuoYang) Electromechanic Co., Ltd |
| E.C. Packtech Machines Pvt. Ltd |
| Grace Food Processing & Packaging Machinery |
| Fuso International |
| Tecpacking Group |
| Xiamen Sengong Packing Equipment Co., Ltd |
| Sidsam Formilan Machines Pvt. Ltd |
| IMA S.p.A. |
| Dph International GmbH |
| Others |
Value Chain & Pricing Dynamics
Chinese servo motor and PLC controller suppliers anchor upstream cost structures, concentrating margin capture in sealing subsystem fabrication where Japanese and German component specialists command premium positioning. Equipment builders in Fujian and Zhejiang provinces compete on delivery velocity while European integrators extract value through long-term service bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-line European integrators from Chinese fabricators and manual-equipment micro-providers. Price differentiation hinges on after-sales service bundling and biodegradable film compatibility certification, with EU REACH compliance tiers commanding substantial premiums. Pricing pressure stems from PLA resin supply volatility forcing equipment retrofit cost absorption. Private labelers in Southeast Asia exhibit highest price sensitivity; German organic certification segments show lowest.
Supply Chain Analysis
Export-control restrictions on precision servo drives and thermal control modules limit technology flows from Japan and Germany to Chinese equipment builders, fragmenting component sourcing strategies. Manufacturing concentrates in China, Germany, and Italy, with sealing subsystem fabrication drawing from Taiwanese sensor suppliers and Swiss thermal profiling instrumentation. Single-source vulnerability runs through Chinese PLA film resin channels. Distribution runs through regional machinery service networks rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as biodegradable packaging mandates splinter equipment specifications across regulatory jurisdictions, preventing scale concentration by any single builder archetype.
For Market Incumbents: Insulate installed base revenue through predictive maintenance contract expansion and biodegradable film compatibility pre-certification. Threat from Chinese delivery-speed competitors intensifies in Southeast Asian contract manufacturing segments. Leverage vertical integration into sealing subsystem servicing to displace third-party technical networks in Vietnam and Indonesia.
For New Entrants and Emerging Players: India's Assam and Darjeeling processing corridors offer underpenetrated whitespace as FSSAI biodegradable mandates pending approval force equipment replacement cycles. Target mid-sized processors with direct-to-brand financing models bypassing traditional banking constraints. Lead with servo-driven heat sealing architectures featuring IoT-enabled seal validation to differentiate from legacy pneumatic retrofits.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European platform integrators holding dense service networks but lagging PLA compatibility roadmaps. Long-term viability centers on regulatory divergence management capability across FDA, EFSA, and SAMR certification timelines. Watch for ultrasonic sealing module adoption inflection among Japanese and German premium processors as signal of technology substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Compatibility Certification | EU REACH substance restrictions force equipment recalibration investments among German organic processors. |
| Sealing Subsystem Vertical Integration | In-house thermal profiling instrumentation production captures margin from Swiss component suppliers. |
| Predictive Maintenance Service Expansion | IoT-enabled seal validation contracts extend lifecycle revenue from Fujian-Zhejiang contract manufacturers. |
| Direct-to-Brand Equipment Financing | Non-traditional leasing channels unlock mid-sized Assam and Darjeeling processor procurement. |
| Ultrasonic Sealing Technology Licensing | Japanese pilot-scale adoption signals disruption potential for traditional heat-bar architectures. |
Study Parameters
Cross-validation between machinery procurement managers at Southeast Asian contract manufacturers and regulatory affairs leads at European specialty tea houses anchors the qualitative findings. Primary interviews with plant engineers, aftermarket service heads, OEM procurement teams, and biodegradable film suppliers combined with secondary analysis of SAMR GB standards documentation, EU F-Gas Regulation filings, FDA food contact substance notifications, and Japanese METI mandate schedules. Bottom-up equipment shipment tracking and top-down tea processing capacity modeling provided triangulation.
Calibration against historical replacement cycle data and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include automation tier, sealing architecture, material compatibility, and end-user procurement sophistication. CAGRs derived from equipment unit economics and input cost trajectory analysis, with PLA film supply elasticity and certification timeline divergence as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese delivery-speed specialists or European service-network consolidators would shift outcomes. Material shifts in biodegradable film regulatory approval timelines or servo drive export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Confectionery Packaging Machine Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Lipstick Molding Machines Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Multi-Head Filling Machines Market