
 Global Pack Conveyors Market | 2026-2036
Global Pack Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pack Conveyors Market Intelligence
The performance gap between custom-engineered, automated systems and standardized, modular conveyor units is broadening, creating distinct tiers within the market. Premium solutions integrate advanced robotics and software for high-throughput sorting in e-commerce and parcel handling. Siemens AG specializes in the control systems and automation software that power these complex installations. In contrast, Dematic Corp. competes by offering integrated systems that combine conveyance with automated storage and retrieval solutions for large-scale distribution centers.
Pack conveyors are material handling systems engineered to transport individual packages, totes, or cartons within a facility. These systems often utilize modular designs with belt or roller surfaces, capable of operating at speeds exceeding two meters per second to meet throughput requirements. Their primary purpose is to automate the movement, sorting, and accumulation of goods in logistics and manufacturing environments. Roller conveyors command a significant share due to their versatility, while automated technology is prioritized by the e-commerce and logistics provider end-user segments.
Compliance with machinery safety standards, such as CE marking in Europe and OSHA guidelines in the United States, is mandatory for market access. National regulations, including China's GB standards, also influence design specifications for electrical components and structural integrity. These frameworks ensure operator safety and system reliability, directly impacting equipment design and material choices. System integrators and end-users must prioritize modularity and software compatibility to future-proof their material handling investments against evolving operational needs.
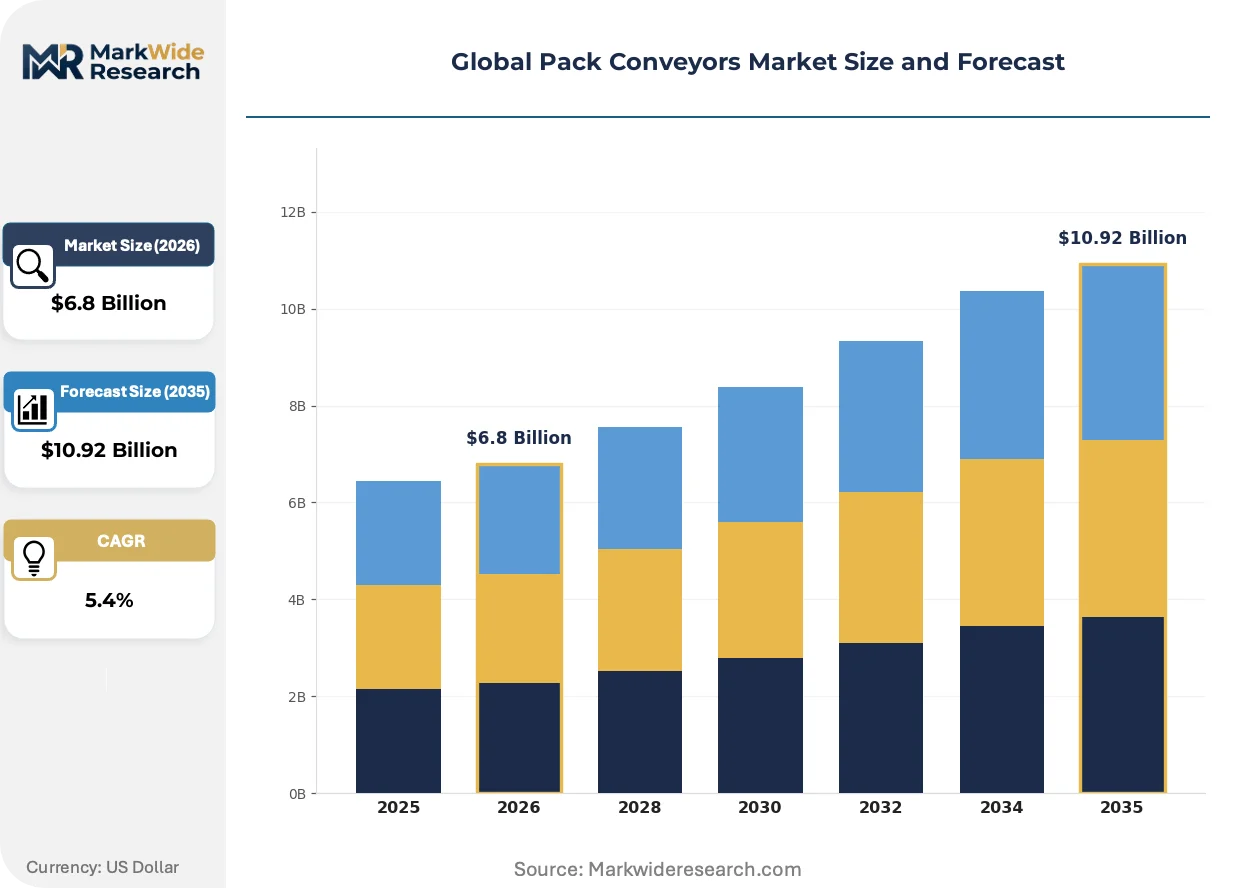
Market Dynamics
The pack conveyors market is defined by the performance divergence between standardized modular units and custom-engineered automated systems. This gap creates distinct market tiers, with demand for high-throughput, software-driven solutions concentrating in e-commerce fulfillment and parcel handling hubs.
Growth Catalysts
- E-commerce Expansion:The build-out of logistics and fulfillment centers, particularly in major hubs across Germany, the United States, and China, necessitates high-speed automated conveyor systems to manage escalating parcel volumes.
- Advanced Sorting Technology:The integration of advanced sensor technology and software controls into conveyor systems enables the high-throughput, automated sorting required by large-scale logistics providers and postal services.
- Warehouse Automation Initiatives:National industrial strategies, including a focus on logistics efficiency in China, encourage investment in automated material handling equipment as a strategic priority for enhancing supply chain competitiveness.
Market Restraints
- High Capital Investment:The significant upfront cost of sophisticated automated conveyor systems, including robotics and advanced software, presents a major barrier for small and medium-sized enterprises.
- System Integration Complexity:Integrating new automated conveyors with existing legacy Warehouse Management Systems and other material handling equipment is technically challenging, often causing delays and cost overruns.
- Regulatory Compliance Burden:Adherence to a fragmented landscape of safety standards, such as CE marking in Europe and OSHA guidelines in the US, adds complexity and cost to equipment design and market access.
Strategic Opportunities
- Service-Based Models:The development of leasing or "Conveying-as-a-Service" (CaaS) financial models can lower the adoption barrier for customers by shifting expenditure from capex to opex.
- AI and Machine Vision Integration:Converging AI-powered vision systems with roller or belt conveyors creates opportunities for intelligent sorting, dimensioning, and damage detection without manual intervention or barcode scanning.
- Niche Application Development:Engineering specialized conveyor solutions for temperature-sensitive supply chains, such as pharmaceuticals and fresh food e-commerce, addresses unmet needs for gentle handling and hygienic design.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and engineers with expertise in mechatronics, robotics, and PLC programming hinders the installation, maintenance, and optimization of complex automated systems.
- Lack of Interoperability Standards:The absence of universal communication protocols between equipment from different vendors complicates the creation of cohesive, multi-vendor automated environments, leading to vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pack Conveyors Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyors, Roller Conveyors, Chain Conveyors, Screw Conveyors, Overhead Conveyors Technology: Automated, Semi-Automated, Manual, Pneumatic, Hydraulic Application: Food Processing, Parcel Handling, Packaging, Sorting, Manufacturing End User Industry: Logistics Providers, Warehousing, E-commerce, Pharmaceuticals, Electronics |
| Companies Covered | Daifuku Co. Ltd., Dematic Corp., Siemens AG, SSI Schaefer Systems International, Fives Group S.A., Honeywell International Inc., Vanderlande Industries B.V., TGW Logistics Group GmbH, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pack Conveyors Market Strategic Shifts & Innovations
Technological advancements are pushing pack conveyor systems beyond simple material transport toward becoming intelligent, data-generating nodes within a connected logistics ecosystem. This evolution is driven by software, sensor fusion, and a demand for greater operational flexibility and visibility.
Artificial intelligence-powered machine vision represents a significant product evolution. These systems use cameras and deep learning algorithms to identify and classify parcels based on visual features, eliminating the need for barcodes. E-commerce and parcel handling operators are rapidly adopting this for high-speed sortation. This technology is electrifying the sorting process, enabling dynamic routing and data capture at speeds that far exceed manual or scanner-based capabilities.
Mandatory compliance with machinery safety standards directly shapes equipment design and material selection. Regulations like Europe's CE marking framework and OSHA guidelines in the United States dictate requirements for electrical safety, emergency stops, and physical guarding. This forces manufacturers to engineer safety features into the core design of their products. System integrators are most impacted, as they must ensure the final assembled system is fully compliant, influencing component choices and engineering practices.
A notable behavioral shift is the move away from purchasing discrete hardware components toward procuring fully integrated, turnkey solutions. This trend disrupts the business model for component-only suppliers, favoring system integrators who can manage a project from design through software integration and commissioning. This preference for single-source responsibility is most pronounced in large-scale greenfield distribution center projects within the United States and Germany, where logistics providers seek to minimize project risk.
Global Pack Conveyors Market Segmentation
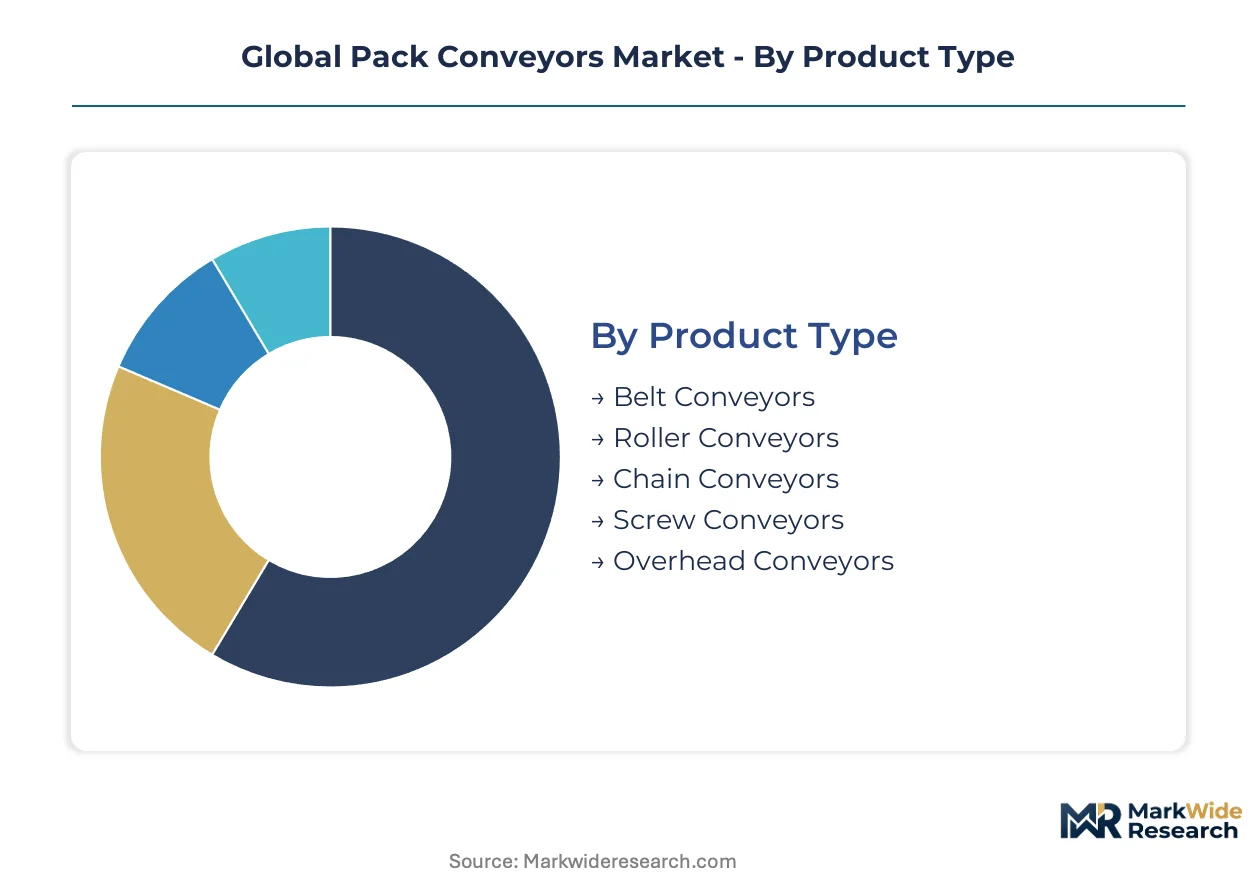
The global pack conveyors market segmentation reflects the diverse operational demands and technological requirements across various industrial and logistical environments. Understanding these distinct segments allows for targeted product development and strategic investment in specialized material handling solutions.
Product Type:
Pack conveyor product types exhibit varying integration depths, from standalone units to components embedded within larger automated systems.
- Belt Conveyors:Belt conveyors employ a continuous loop of material, typically rubber or fabric, stretched over two or more pulleys to transport items. E-commerce fulfillment operations in China prioritize belt conveyors for their consistent speed and ability to handle diverse package sizes on inclines.
- Roller Conveyors:Roller conveyors utilize rotating cylinders to move packages, often employing gravity or motor-driven mechanisms for transport. Demand concentrates in large distribution centers across the United States and Germany, where high-volume parcel sorting requires robust, versatile systems.
- Chain Conveyors:Chain conveyors use a continuous chain mechanism to pull or carry loads, suitable for robust industrial applications.
- Screw Conveyors:Screw conveyors feature a rotating helical screw blade within a tube, primarily used for moving granular or powdered materials.
- Overhead Conveyors:Overhead conveyors suspend items from an overhead track system, optimizing floor space in manufacturing and assembly lines.
Volume placements concentrate in Roller Conveyors; the faster expansion belongs to Belt Conveyors.
Technology:
Technology segmentation reflects the varying levels of operational sophistication and labor integration within pack conveyor systems.
- Automated:Automated conveyor systems integrate sensors, software, and robotics to manage package flow, sorting, and accumulation without human intervention. Logistics hubs in the United States increasingly deploy automated systems to process millions of parcels daily, driven by labor efficiency and speed requirements.
- Semi-Automated:Semi-automated conveyors combine mechanical transport with human oversight or manual loading/unloading stages. Warehousing facilities in Germany utilize semi-automated solutions to balance capital expenditure with increased throughput for medium-volume operations.
- Manual:Manual conveyor systems rely entirely on human effort for package movement, offering flexibility for low-volume or specialized tasks.
- Pneumatic:Pneumatic conveyors use air pressure differentials to move items through enclosed tubes, suitable for lightweight packages or documents.
- Hydraulic:Hydraulic conveyor systems employ fluid power for heavy-duty transport, providing robust force for demanding industrial material handling.
The demand for efficiency drives investment towards automated solutions, while manual systems retain utility in specialized, low-throughput environments.
Application:
Pack conveyor applications span diverse industrial sectors, each demanding specific throughput capabilities and handling characteristics.
- Parcel Handling:Parcel handling applications involve the high-speed movement, sorting, and routing of individual packages within logistics and postal networks. E-commerce giants in China and the United States require advanced parcel handling systems to manage escalating delivery volumes and tight schedules.
- Sorting:Sorting applications utilize conveyor systems to direct packages to specific destinations based on predefined criteria, often employing automated recognition. Logistics providers in Germany prioritize intelligent sorting systems to optimize route planning and accelerate package distribution across their networks.
- Food Processing:Food processing applications require hygienic conveyor designs for safe and efficient movement of raw ingredients and finished food products.
- Packaging:Packaging applications integrate conveyors into automated lines for filling, sealing, and labeling products within manufacturing facilities.
- Manufacturing:Manufacturing applications deploy conveyors for assembly line processes and inter-stage material transfer in diverse industrial settings.
Strategic investment in pack conveyor systems primarily targets parcel handling and sorting, reflecting their critical role in modern logistics infrastructure.
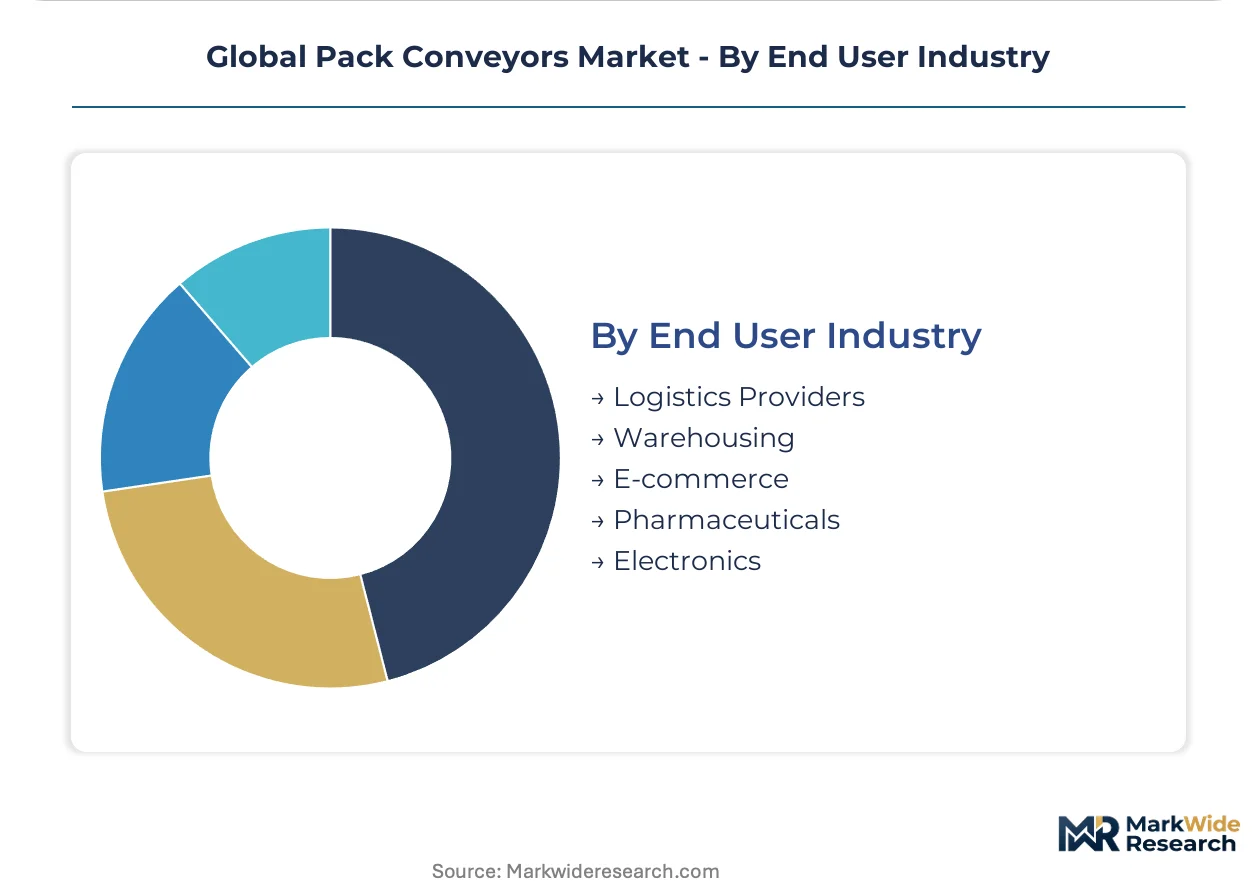
End User Industry:
End-user industries adopt pack conveyors to address distinct operational challenges, ranging from high-volume distribution to specialized product handling.
- Logistics Providers:Logistics providers leverage pack conveyors for efficient material flow, cross-docking, and consolidation of goods across their extensive supply chain networks. Major logistics companies in Germany integrate advanced conveyor systems to enhance throughput and optimize operational costs in their parcel sorting facilities.
- E-commerce:The e-commerce industry utilizes pack conveyors for rapid order fulfillment, including picking, packing, and shipping processes within large distribution centers. Online retailers in the United States and China invest heavily in automated conveyor solutions to meet customer expectations for fast, accurate deliveries.
- Warehousing:Warehousing operations deploy conveyors for internal transport, inventory management, and staging of goods within storage facilities.
- Pharmaceuticals:The pharmaceuticals sector requires specialized conveyors for sterile environments and gentle handling of sensitive medical products.
- Electronics:The electronics industry uses conveyors for precise assembly, testing, and packaging of delicate components with electrostatic discharge protection.
E-commerce and Logistics Providers drive significant demand, while Pharmaceuticals and Electronics exhibit specialized requirements for system design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major logistics hubs, such as those near Chicago in the United States, drive significant investment in pack conveyor systems. These key distribution centers demand high-throughput solutions for escalating parcel volumes. Regional regulatory frameworks also influence system design and market access for manufacturers.
United States
E-commerce expansion in the United States necessitates advanced automated conveyor systems for rapid order fulfillment. OSHA guidelines mandate specific safety features, influencing equipment design and installation practices. Major distribution centers in states like California and Texas are continuously upgrading their material handling infrastructure.
Germany
Logistics providers in Germany prioritize intelligent sorting systems to optimize route planning and accelerate package distribution. CE marking ensures compliance with European health, safety, and environmental protection directives. Industrial regions like North Rhine-Westphalia are hubs for warehouse automation technology adoption.
China
China's e-commerce giants require advanced parcel handling systems to manage escalating delivery volumes and tight schedules. National GB standards dictate design specifications for electrical components and structural integrity. Key logistics centers in the Yangtze River Delta are seeing substantial investment in automated sorting capabilities.
Japan
Advanced manufacturing and precise logistics operations in Japan demand highly reliable and efficient conveyor solutions. JIS standards ensure product quality and interchangeability across various industrial applications. The Tokyo Bay Area, with its extensive port facilities, represents a significant market for sophisticated material handling equipment.
Global Pack Conveyors Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a diverse market structure for pack conveyors. The market exhibits distinct tiers, with premium solutions integrating advanced robotics for high-throughput sorting. Strategic archetypes include specialized automation providers, integrated system integrators, and component manufacturers. Companies are pursuing strategic partnerships and technology licensing to enhance their offerings.
Within the premium-tier vector, Siemens AG represents a significant player specializing in control systems and automation software that power complex, high-throughput installations. Dematic Corp. exemplifies integrated systems, combining conveyance with automated storage and retrieval solutions for large-scale distribution centers across various geographies. Daifuku Co. Ltd. occupies a position as a global leader in material handling equipment, anchoring significant market share across diverse applications and providing comprehensive solutions for logistics and manufacturing environments. These companies continuously innovate to meet the escalating demands of e-commerce fulfillment.
| Leading Market Players |
|---|
| Daifuku Co. Ltd. |
| Dematic Corp. |
| Siemens AG |
| SSI Schaefer Systems International |
| Fives Group S.A. |
| Honeywell International Inc. |
| Vanderlande Industries B.V. |
| TGW Logistics Group GmbH |
| KUKA AG |
Cost & Logistics Intelligence
Private equity-backed system integrators often dictate pricing across automated pack conveyor solutions, influencing both component sourcing and final equipment costs through strategic supplier relationships and project-based contracts.
Pricing Analysis
Value-based pricing for automated pack conveyor systems ties directly to guaranteed throughput and uptime, reflecting operational efficiencies for logistics providers. Customization level and after-sales service, including maintenance contracts, drive significant price differentiation. Pricing softness stems from intense competition among system integrators for large greenfield projects in Germany and the United States. Small and medium-sized enterprises exhibit the highest price sensitivity for modular units, while large e-commerce operators prioritize performance over upfront cost.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of pack conveyor systems, especially for large modular units shipped across continents. Geographic supply concentration centers on China for electronic components and basic steel, with Germany providing precision engineering and advanced automation hardware. The supply chain relies on electric motors, advanced sensors, and control software. Single-source vulnerability for specialized automation components presents a structural risk. Distribution runs through direct sales channels for complex integrated systems and established distributor networks for standardized modular units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
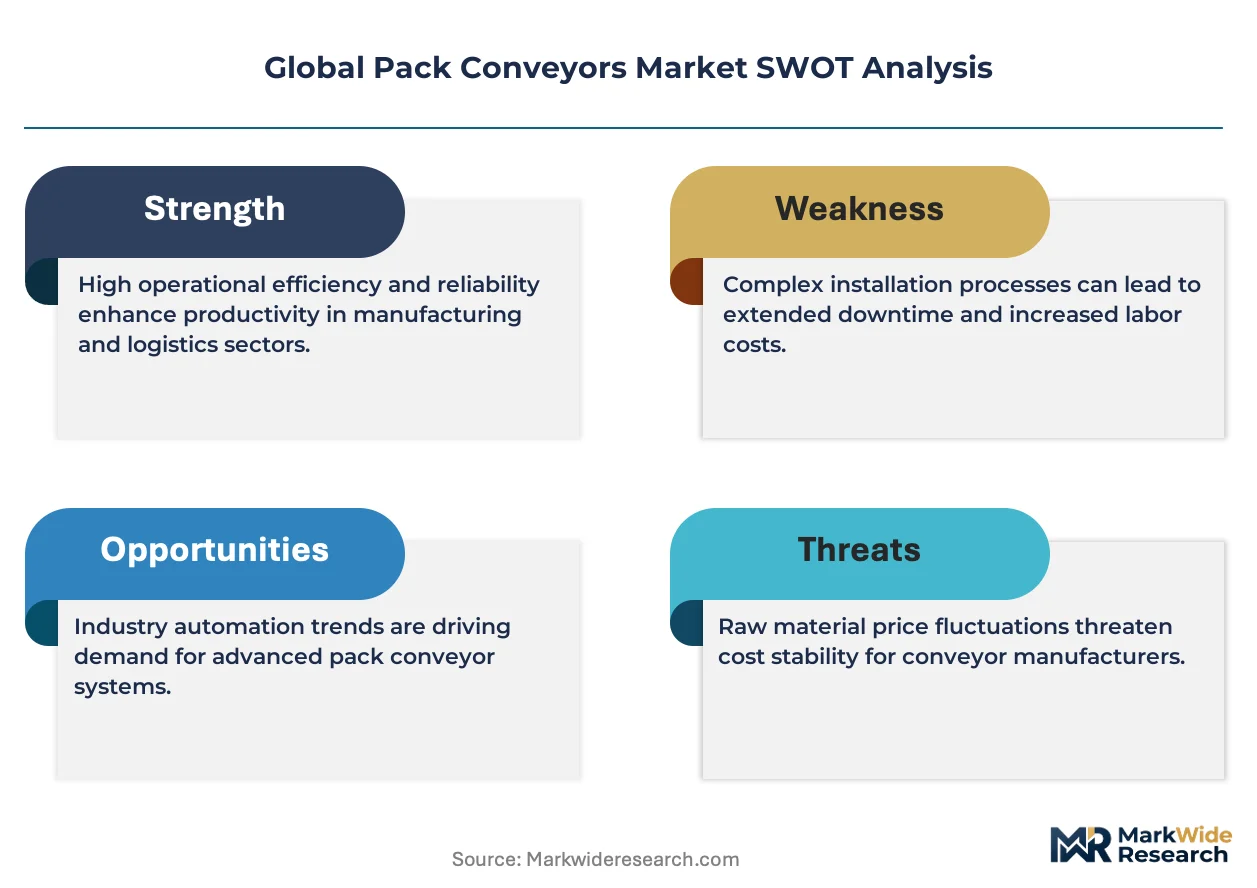
The pack conveyors market presents a significant cost-of-compliance story, where adherence to machinery safety standards like Europe's CE marking creates a substantial barrier-to-entry moat for established system integrators.
For Market Incumbents: Anticipate increased investment in software and AI integration to maintain a performance lead against emerging automation threats. Consolidate market share by acquiring specialized component manufacturers to control critical sensor and robotics supply. Focus R&D on predictive maintenance and energy efficiency for complex installations, leveraging existing customer relationships. Invest in certification for national GB standards to reinforce market access in China.
For New Entrants and Emerging Players: Begin with niche application development for temperature-sensitive logistics, leveraging hygienic design and gentle handling capabilities. Target medium-volume warehousing facilities in Germany with modular, semi-automated solutions to balance capital expenditure. A service-based "Conveying-as-a-Service" model offers a compelling go-to-market angle, reducing upfront investment for customers. Focus on software compatibility to integrate with diverse legacy systems.
For Investors and Strategic Acquirers: The rapid build-out of new e-commerce fulfillment centers is the leading indicator that long-term viability for pack conveyor systems remains strong over the next decade. Identify acquisition targets among software-centric automation providers specializing in machine vision or advanced PLC programming. Watch for consolidation among regional system integrators as a key M&A signal. Prioritize companies with strong intellectual property in sensor technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Build out regional manufacturing hubs to reduce logistics costs for large distribution centers. |
| AI Integration | Embed machine vision systems into belt conveyors for dynamic parcel routing without barcodes. |
| Service-Based Models | Offer Conveying-as-a-Service to lower capital expenditure barriers for small and medium-sized enterprises. |
| Strategic Partnerships | Collaborate with robotics manufacturers to offer fully integrated picking and packing solutions. |
| Compliance Certification | Invest in achieving GB standards for electrical components to expand market access in China. |
Research Approach
Industry association reports, government trade statistics, and SEC 10-K filings formed the secondary backbone, complemented by primary interviews. We engaged with logistics directors, warehouse automation engineers, system integrators, and component suppliers. This data underwent bottom-up aggregation and top-down validation, ensuring comprehensive market understanding across diverse geographies.
Historical trendline analysis across the modeling period informed the projection horizon for pack conveyor market growth. Segmentation dimensions modeled included product type, technology, application, and end-user industry, alongside regional logistics infrastructure development. Compound annual growth rates were derived from a multi-factor regression analysis, incorporating e-commerce penetration rates and warehouse build-out schedules.
Underlying measurement precision varies by segment; automated systems and e-commerce applications carry tighter precision than others due to data availability. Forecasts reflect assumptions regarding global economic stability and continued investment in supply chain automation. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Linear Net Weighing Machines Market