
 Shipping Container Liners Market | 2026-2036
Shipping Container Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Container Liners Market Analysis
Polypropylene is broadening its share against polyethylene in container liner fabrication as processors seek better chemical resistance and thermal stability at comparable cost points. A.P. Moller-Maersk leverages its integrated logistics network to specify custom liner configurations across reefer and dry container fleets. CMA CGM sustains procurement scale through long-term supply agreements with Asian textile and chemical shippers. COSCO Shipping Lines anchors liner demand through captive container volumes on Asia-Europe and transpacific corridors.
Shipping container liners are protective inserts installed inside standard ISO containers to create a sealed barrier between cargo and container walls, typically fabricated from woven polypropylene or multi-layer polyethylene films with load ratings from 15 to 30 metric tons and discharge spout configurations for bulk handling. Their primary purpose is to prevent contamination, moisture ingress, and cross-contact during multimodal transport of powders, granules, and liquid-sensitive goods. Flexible liners dominate volume shipments for agricultural commodities and polymer resins where cost-per-unit and storage efficiency matter, while insulated liners command premium positioning in pharmaceutical cold chains where temperature excursion tolerance narrows to two to eight degrees Celsius. Rigid and semi-rigid formats occupy niche roles in chemical logistics where structural sidewall support prevents bag deformation under high stacking loads.
The European Chemicals Agency enforces REACH substance restrictions on liner materials contacting hazardous cargo, forcing reformulation of PVC-based products and expanding testing documentation burdens for exporters. The U.S. Food and Drug Administration maintains migration limits for food-contact polymers under 21 CFR, directly shaping material selection for liners serving agricultural and processed food trade lanes. China's Ministry of Ecology and Environment implements dual carbon goals that pressure domestic liner manufacturers toward recycled content thresholds and energy-efficient extrusion processes. Stakeholders must monitor evolving material certification requirements across jurisdictions while evaluating whether backward integration into resin compounding or partnerships with specialized converters offers more durable margin protection.
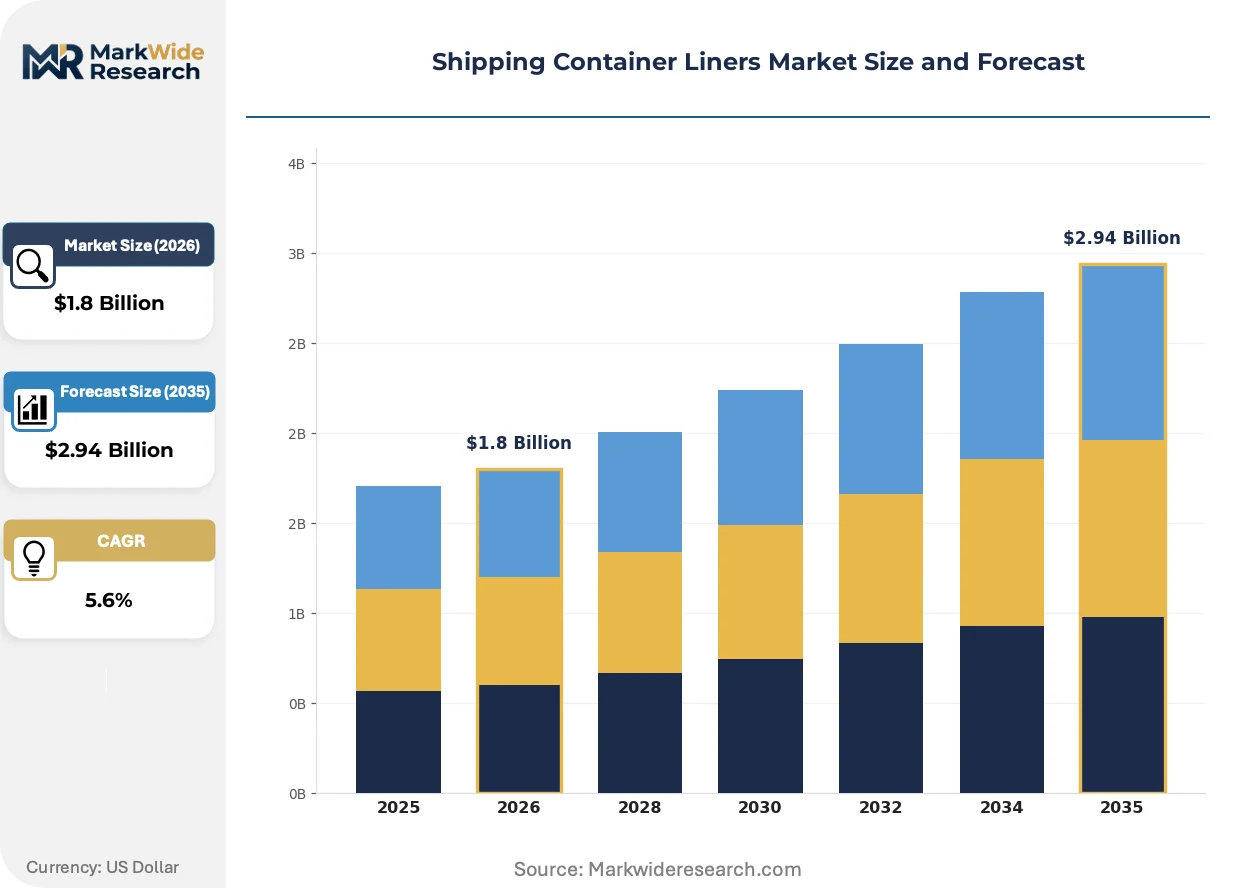
Market Dynamics
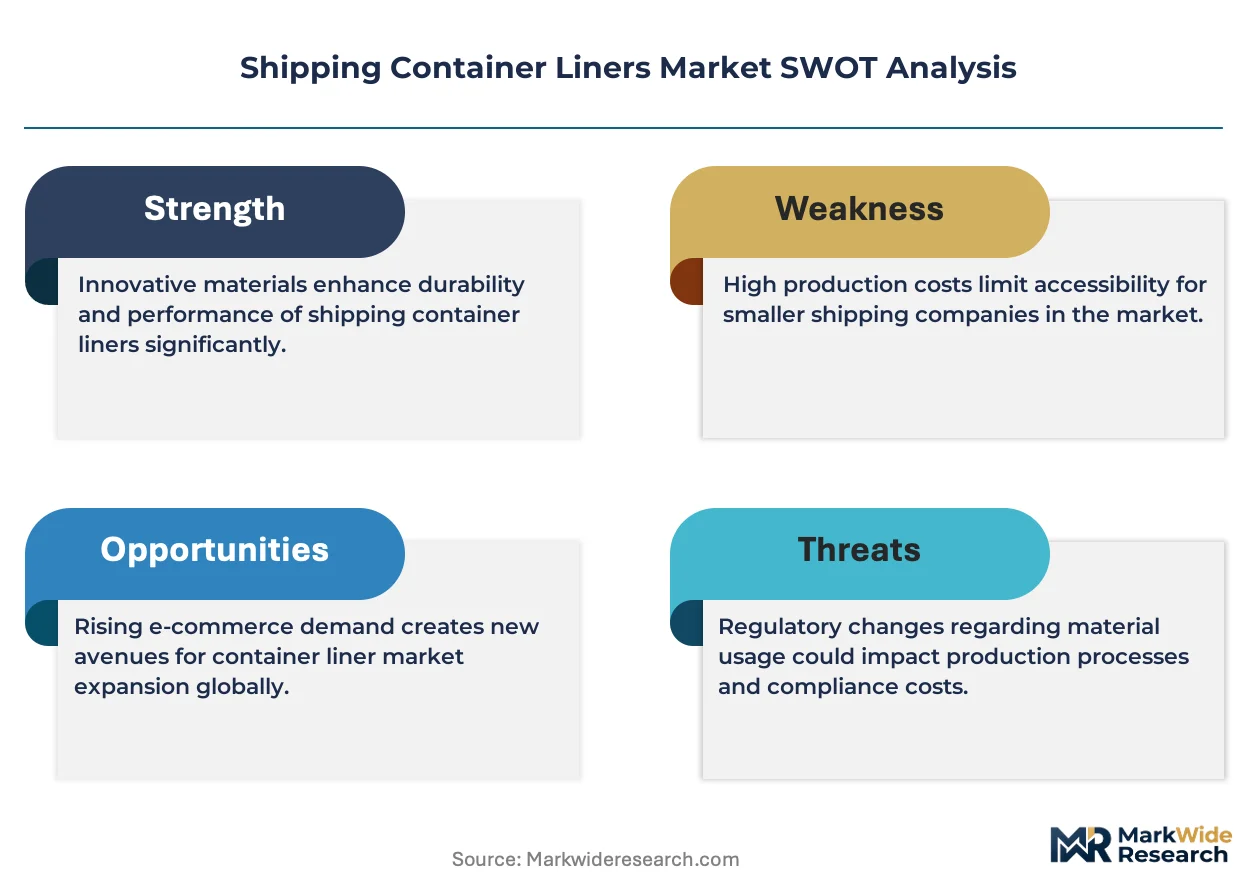
REACH substance restrictions in Europe are forcing rapid material reformulation across the liner supply base, compressing development cycles and elevating testing documentation burdens for exporters serving chemical and food-contact applications.
Growth Catalysts
- Food-contact migration limits:FDA 21 CFR standards for agricultural and processed food trade lanes are accelerating liner replacement cycles as shippers upgrade to certified barrier films.
- China's export manufacturing scale:Domestic liner demand concentrates in coastal manufacturing clusters serving Asia-Europe and transpacific container volumes.
- Reefer fleet expansion:Pharmaceutical cold chains require insulated liners with temperature excursion tolerance of two to eight degrees Celsius, opening premium specification tiers.
Market Restraints
- Resin input volatility:Polypropylene and polyethylene feedstock costs fluctuate with crude oil and natural gas pricing, squeezing converter margins on fixed-price annual contracts.
- Supply concentration in East Asian weaving:Woven fabric production clusters in Zhejiang and Jiangsu provinces create geographic single-point vulnerability for global liner supply.
- REACH compliance friction:PVC-based liner reformulation requires 12-18 month testing documentation cycles before European chemical cargo authorization.
Strategic Opportunities
- Recycled content mandates:China's Ministry of Ecology and Environment dual carbon goals pressure domestic manufacturers toward post-industrial recycled polypropylene thresholds.
- Pharmaceutical distribution channels:Direct-to-manufacturer liner procurement bypasses traditional freight forwarder intermediaries in temperature-controlled logistics.
- Multi-layer barrier convergence:Co-extruded EVOH and aluminum oxide film lamination is unifying oxygen and moisture protection in single-liner configurations for polymer resin shippers.
Industry Challenges
- Compounder technical talent scarcity:Formulation chemists with REACH food-contact and chemical barrier expertise command premium wages in European and North American labor markets.
- Extrusion line capex intensity:Multi-layer blown film equipment for 3-meter wide liner fabrication requires capital deployment exceeding mid-tier converter balance sheet capacity.
- ISO tank substitution threat:Stainless steel intermediate bulk containers capture bulk liquid chemical volumes previously served by lined dry containers on certain trade lanes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Container Liners Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Liners, Rigid Liners, Semi-Rigid Liners, Insulated Liners Material: Polyethylene, Polypropylene, PVC, Polyester Application: Food & Beverage, Chemicals, Pharmaceuticals, Textiles End User: Logistics Companies, Freight Forwarders, Exporters, Importers |
| Companies Covered | Mediterranean Shipping Company (MSC), A.P. Moller-Maersk, CMA CGM, COSCO Shipping Lines, Hapag-Lloyd, Ocean Network Express (ONE), Evergreen Marine Corporation, HMM Co. Ltd., Pacific International Lines (PIL), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Container Liners Market Emerging Trajectories
Material science advances and regulatory stringency are compressing product development timelines while expanding the addressable application set for high-performance barrier liners.
Co-extruded barrier films incorporating EVOH and metallized polyethylene terephthalate layers are unifying oxygen transmission resistance and moisture vapor protection in single-fabric configurations. Pharmaceutical distributors and specialty chemical shippers are adopting these specifications for ocean transit exceeding 21 days. This unification eliminates separate desiccant placement and reduces total cost per container by consolidating protection functions.
REACH substance restrictions enforced by the European Chemicals Agency are compelling PVC phase-out in chemical-contact liners and expanding third-party migration testing requirements. Converter operations serving European export lanes must maintain dual formulation inventories or abandon PVC-dependent product lines entirely. Agricultural commodity shippers to Rotterdam and Hamburg are accelerating polypropylene and polyethylene migration testing to preempt customs detention.
Freight forwarder consolidation is compressing liner procurement decision cycles as larger logistics platforms centralize container equipment purchasing. Direct manufacturer relationships are displacing distributor-mediated transactions for agricultural and polymer resin exporters in North American and European markets. Container lines including A.P. Moller-Maersk and CMA CGM are specifying custom liner configurations through captive procurement teams rather than shipper-directed spot purchases.
Shipping Container Liners Market Segmentation
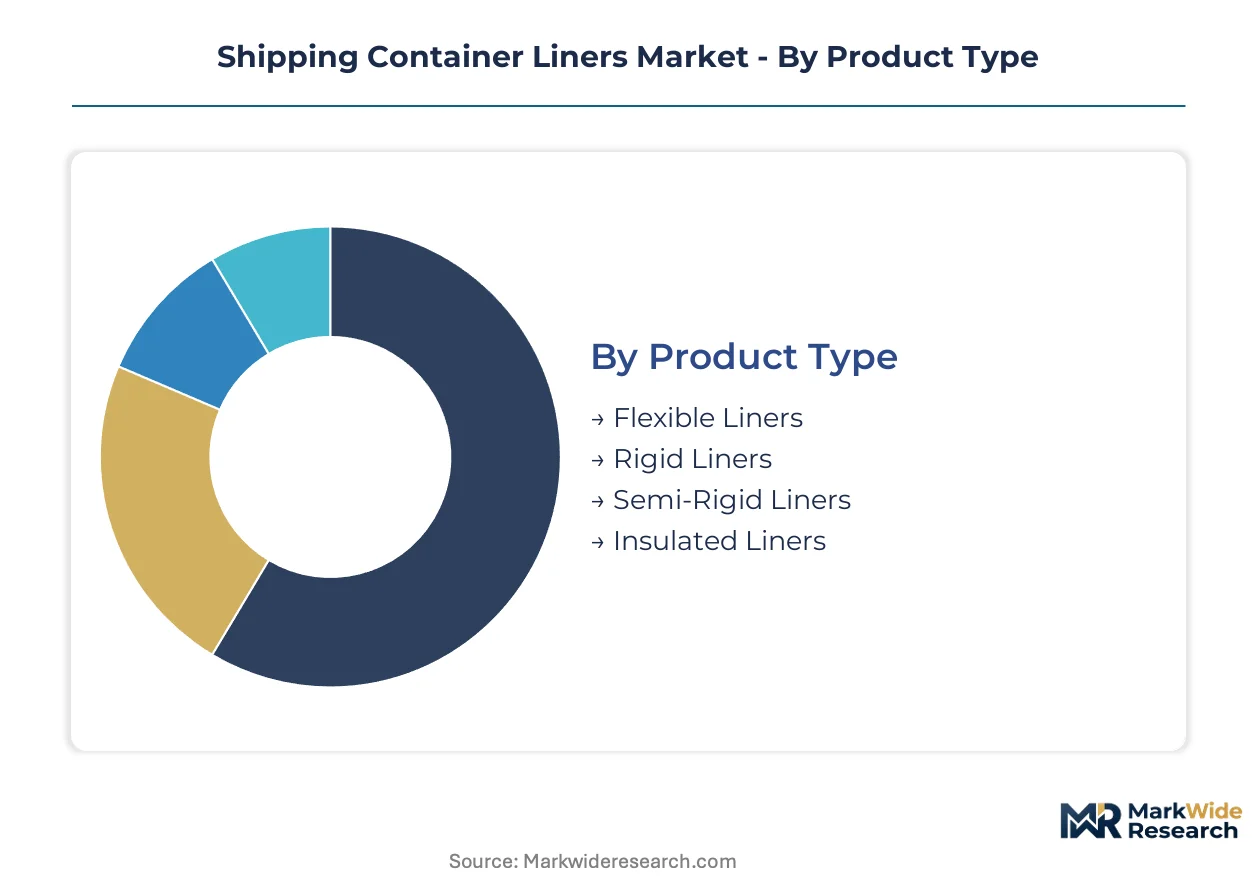
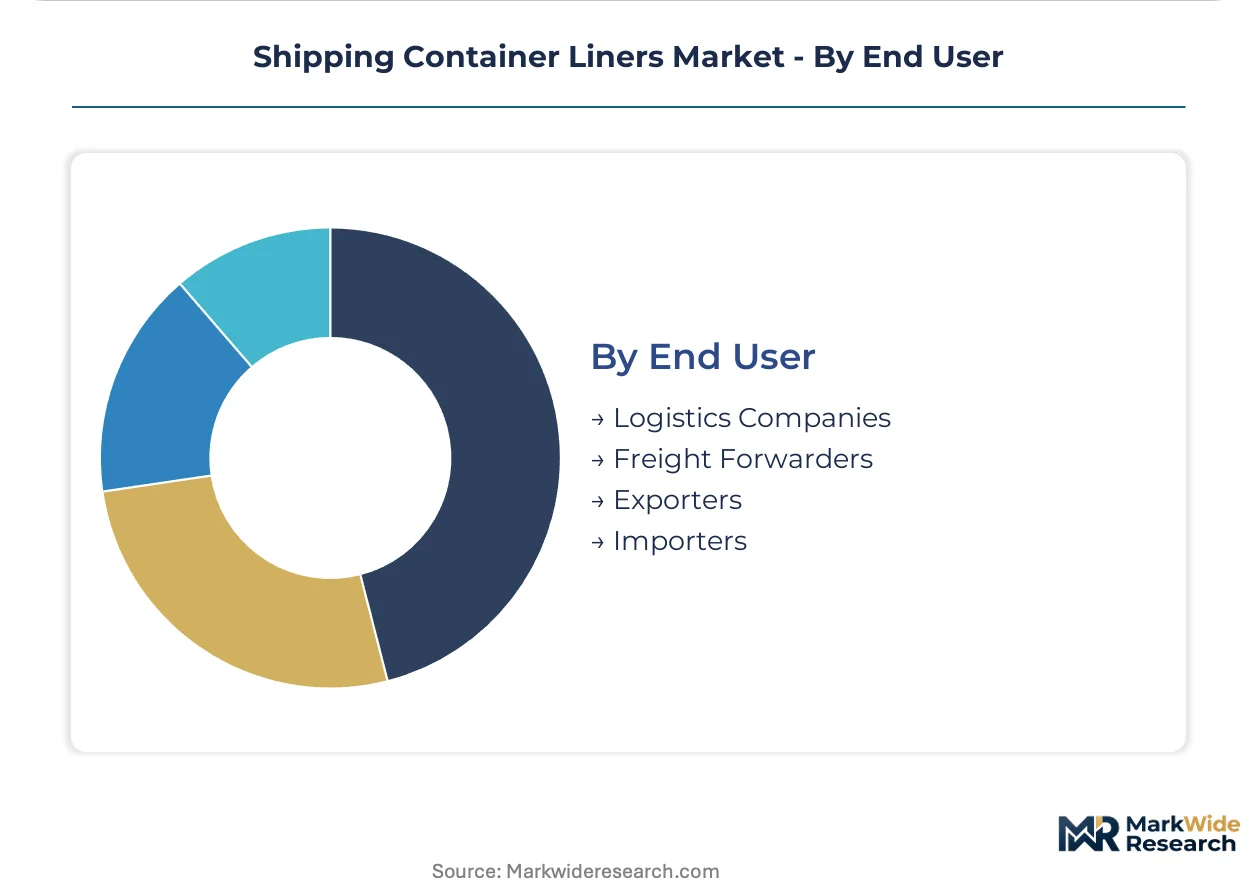
Container liner segmentation reveals divergent margin structures across material technologies and customer procurement models. Product format and end-use application determine whether converters compete on unit economics or specification premiums.
Product Type:
Volume shipments concentrate in commodity formats while premium specifications capture cold-chain and hazardous cargo premiums.
- Flexible Liners:Woven polypropylene or multi-layer polyethylene films rated for 15-30 metric ton loads with spout discharge configurations. Agricultural commodity exporters in Brazil and polymer resin shippers in Saudi Arabia drive procurement scale where cost-per-container dominates supplier selection.
- Insulated Liners:Multi-layer assemblies with thermal barriers maintaining 2-8°C excursion tolerance for pharmaceutical cold chains. EMA temperature compliance documentation and WHO prequalification requirements elevate specification complexity and extend sales cycles for European and Gulf distributor channels.
- Rigid Liners:Structural sidewall supports preventing deformation under high stacking loads for chemical logistics.
- Semi-Rigid Liners:Hybrid formats balancing collapse resistance with storage efficiency for specialty polymer applications.
Mature deployment sits with flexible formats in agricultural bulk trade. Newer deployment is concentrated in insulated specifications for temperature-sensitive pharmaceutical distribution.
Material:
Feedstock selection determines chemical resistance profiles and regulatory compliance pathways across destination markets.
- Polypropylene:Superior thermal stability and chemical resistance at comparable cost points to polyethylene. REACH-compliant grades are displacing PVC in European chemical-contact applications as ECHA substance restrictions tighten migration testing documentation.
- Polyethylene:Dominates volume production through multi-layer blown film extrusion for moisture barrier applications. China's MEE dual carbon goals are pressuring domestic converters toward post-industrial recycled content thresholds in Zhejiang and Jiangsu production clusters.
- PVC:Facing phased reduction in European chemical cargo applications due to ECHA authorization requirements.
- Polyester:Niche positioning for high-temperature stability in specialized chemical transport.
Polyethylene retains volume leadership in cost-sensitive agricultural lanes. Polypropylene is climbing the fastest in chemical and food-contact segments requiring thermal performance.
Application:
Regulatory stringency varies sharply across end-use verticals, fragmenting formulation and certification requirements.
- Food & Beverage:FDA 21 CFR migration limits and FSSAI food-contact standards shape material selection for agricultural and processed food trade lanes. Exporters to US and Indian markets accelerate liner replacement cycles to maintain customs clearance velocity.
- Pharmaceuticals:Temperature excursion tolerance requirements and GDP compliance documentation create specification premiums. Direct-to-manufacturer procurement is displacing freight forwarder intermediaries in temperature-controlled logistics channels.
- Chemicals:REACH substance restrictions and hazardous cargo classification drive barrier film complexity.
- Textiles:Moisture protection for fiber and fabric shipments on extended ocean transits.
Food and beverage applications anchor procurement volume. Pharmaceutical specifications command the steepest margin expansion trajectory.
End User:
Procurement centralization is restructuring channel relationships and compressing decision cycles across customer categories.
- Logistics Companies:Integrated container lines including A.P. Moller-Maersk specify custom liner configurations through captive procurement teams rather than shipper-directed spot purchases. Scale concentration enables multi-year supply agreements with Asian textile and chemical shippers.
- Freight Forwarders:Consolidation across North American and European markets is centralizing container equipment purchasing. Larger platforms are displacing distributor-mediated transactions for agricultural and polymer resin exporters.
- Exporters:Direct manufacturer relationships emerging for pharmaceutical and specialty chemical cargo requiring documentation traceability.
- Importers:Reactive procurement patterns in commodity agricultural trade with limited specification influence.
Freight forwarder procurement represents established channel volume. Logistics company direct sourcing is expanding most quickly as container lines integrate equipment purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates container liner procurement through coastal manufacturing clusters serving Asia-Europe and transpacific trade corridors. Domestic weaving capacity in Zhejiang and Jiangsu provinces supplies fabric for both captive container line demand and third-party export orders. Regulatory pressure from China's Ministry of Ecology and Environment dual carbon goals is accelerating recycled content adoption among domestic converters.
United States
Food and beverage exporters drive liner specification upgrades to meet FDA 21 CFR migration limits for agricultural trade lanes. The FDA maintains strict polymer certification requirements that compress replacement cycles for customs clearance velocity. Gulf Coast petrochemical corridors and Midwest grain terminals anchor procurement concentration for bulk agricultural and polymer resin shipments.
Germany
Chemical shippers to Hamburg and Rotterdam accelerate REACH-compliant liner adoption as ECHA substance restrictions tighten on PVC-based products. The European Chemicals Agency enforces 12-18 month testing documentation cycles that elevate barrier film complexity. Industrial clusters along the Rhine-Ruhr corridor concentrate demand for high-performance liners serving hazardous cargo classifications.
India
Pharmaceutical cold chain expansion generates insulated liner demand with WHO prequalification requirements for temperature excursion tolerance. FSSAI food-contact standards shape material selection for processed food exporters to Middle Eastern and African markets. Gujarat and Maharashtra coastal manufacturing zones concentrate liner procurement for textile and chemical export volumes.
Brazil
Agricultural commodity exporters in São Paulo and Paraná states drive flexible liner procurement scale for soybean and corn bulk shipments. Cost-per-container economics dominate supplier selection for extended ocean transits to Asian and European markets. Santos port infrastructure investments are expanding liner installation capacity for seasonal harvest peaks.
Shipping Container Liners Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with container lines centralizing procurement through captive supply agreements. The vendor base organizes around three archetypes: integrated logistics platforms with specification authority, regional weaving converters serving spot demand, and barrier film specialists targeting pharmaceutical cold chains. Competitive positioning hardens through multi-year supply agreements and backward integration into resin compounding. Geographic expansion and technology licensing represent the dominant competitive moves as converters seek to escape East Asian supply concentration.
Among integrated container line operators, A.P. Moller-Maersk, CMA CGM, and COSCO Shipping Lines exemplify the procurement-centralization archetype. These entities leverage fleet scale to specify custom liner configurations across reefer and dry container operations. Their position reflects the broader shift from shipper-directed spot purchasing toward captive equipment management. Regional weaving specialists occupy a fragmented tier below, supplying commodity flexible formats where cost-per-unit determines supplier selection.
| Leading Market Players |
|---|
| Mediterranean Shipping Company (MSC) |
| A.P. Moller-Maersk |
| CMA CGM |
| COSCO Shipping Lines |
| Hapag-Lloyd |
| Ocean Network Express (ONE) |
| Evergreen Marine Corporation |
| HMM Co. Ltd. |
| Pacific International Lines (PIL) |
| Others |
Supply Flow & Price Mechanics
Integrated container lines including A.P. Moller-Maersk and CMA CGM concentrate procurement authority through captive equipment teams, compressing supplier margins and shifting pricing power toward volume-based contract structures with multi-year terms.
Pricing Analysis
Volume shipments of commodity flexible liners for agricultural bulk trade compress margins to cost-plus levels, while insulated pharmaceutical specifications sustain premium positioning through EMA compliance documentation and WHO prequalification requirements. Price differentiation separates certified barrier films meeting FDA 21 CFR migration limits from uncertified commodity grades. Pricing pressure stems from polypropylene and polyethylene feedstock volatility tied to crude oil and natural gas benchmarks. Agricultural exporters in Brazil and polymer resin shippers in Saudi Arabia exhibit the highest price sensitivity, whereas pharmaceutical distributors prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight costs from Zhejiang and Jiangsu weaving clusters to European and North American ports represent a material share of delivered liner costs, amplifying geographic concentration risk. Supply concentrates in China for woven polypropylene fabric, South Korea for specialized co-extrusion equipment, and Germany for REACH-compliant formulation chemistry. Raw material dependencies include virgin and recycled polypropylene resin, multi-layer blown film equipment, and EVOH barrier polymers. Single-source vulnerability in East Asian weaving capacity creates disruption exposure from regional logistics chokepoints or trade policy shifts. Distribution runs through container line captive procurement teams and consolidated freight forwarder platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shipping container liners market is transitioning from commodity polyethylene formats toward multi-layer barrier films incorporating EVOH and metallized layers, displacing legacy single-film constructions in extended ocean transit applications.
For Market Incumbents: Cement market position through backward integration into resin compounding for REACH-compliant polypropylene grades, insulating margin from feedstock volatility. Defend against ISO tank substitution in bulk liquid chemical lanes by expanding co-extruded barrier film capabilities that unify oxygen and moisture protection. Prioritize certification investment in EMA temperature compliance documentation for pharmaceutical cold chain specifications.
For New Entrants and Emerging Players: Launch via direct-to-manufacturer distribution models in pharmaceutical temperature-controlled logistics, bypassing freight forwarder intermediaries that incumbent container lines already control. Target insulated liner specifications for WHO prequalification requirements in India and Gulf markets, where EMA compliance documentation creates specification premiums. White-space exists in post-industrial recycled polypropylene thresholds for Chinese domestic converters under MEE dual carbon goals.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional weaving specialists with REACH food-contact formulation capabilities in European and North American labor markets, where compounder technical talent scarcity commands premium wages. Long-term viability over a multi-year horizon rests on converters escaping East Asian supply concentration through technology licensing or geographic expansion. Watch for inflection signals in pharmaceutical direct procurement volumes displacing freight forwarder channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of REACH-compliant polypropylene grades reduces feedstock cost volatility exposure for European chemical cargo specifications. |
| Multi-Layer Barrier Film Capacity Expansion | Co-extruded EVOH and aluminum oxide lamination unifies protection functions for polymer resin shippers on transits exceeding 21 days. |
| Pharmaceutical Cold Chain Certification Investment | EMA temperature compliance documentation and WHO prequalification open premium specification tiers in Gulf and Indian distributor channels. |
| Recycled Content Threshold Compliance | Post-industrial recycled polypropylene adoption aligns with China's MEE dual carbon goals for Zhejiang and Jiangsu production clusters. |
| Direct-to-Manufacturer Distribution Launch | Bypassing freight forwarder intermediaries captures margin in temperature-controlled logistics where documentation traceability matters. |
Methodological Framework
Document review covered customs and trade flow databases, SEC filings from integrated logistics platforms, and ECHA regulatory guidance documents, complemented by interviews with plant managers at woven fabric converters, procurement leads at container line equipment divisions, technical R&D directors at barrier film specialists, and distribution channel partners serving agricultural commodity exporters. Secondary validation drew from FDA 21 CFR food-contact standards, REACH substance restriction updates, and China's MEE dual carbon policy implementation notices. Bottom-up demand modeling from end-use application volumes was triangulated against top-down supply capacity assessments across Zhejiang and Jiangsu production clusters.
Market size and growth trajectory outputs across the analysis window reflect segmentation by product format, material technology, end-use vertical, and procurement channel. The analytical framework modeled flexible, insulated, rigid, and semi-rigid liner formats separately, with cross-elasticity between pharmaceutical cold chain specifications and commodity agricultural applications. CAGRs were derived from installed base replacement cycles, reefer fleet expansion rates, and trade lane volume projections. Key forecast inputs included REACH compliance timeline assumptions for PVC phase-out and China's domestic manufacturing scale effects on Asia-Europe and transpacific container volumes.
Feedstock cost volatility, regulatory enforcement intensity variations across jurisdictions, and ISO tank substitution rates in bulk liquid chemicals are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about liner replacement cycle acceleration under FDA and FSSAI migration limit tightening. Stakeholders should weight assumptions against their own operating context and procurement contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
EPS Container Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Cylindrical Cans Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
EMEA Container Technology Market
Containers
Container Stacking Machine Market
Containers
Thermoformed Containers Market
Containers
Car Lube Container Market
Containers
Clear Hinged Container Market
Containers
Die Cut Display Container Market
Containers
Aluminum Foil Containers Market
Containers
Container Mouth Inner Seal Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Twist Up Stick Container Market
Containers
Global Food Storage Container Market
Containers
Container Coating Market