
 Tissue Roll Unwinders Market | 2026-2036
Tissue Roll Unwinders Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Roll Unwinders Market Analytics
Direct-drive servo technology replacing mechanical shaft unwinders is narrowing the performance gap between entry-level and premium equipment tiers. Valmet sustains technology leadership through integrated automation platforms that span pulp-to-converting workflows. Fabio Perini anchors the European installed base with specialized unwind solutions for kitchen roll and towel applications. A.Celli Paper differentiates through modular unwind architectures that let converters reconfigure line layouts without greenfield investment.
A tissue roll unwinder is a converting machine that decelerates and tensions parent rolls of tissue paper, typically handling roll diameters up to three meters and weights exceeding several tons, to feed continuous web into downstream folding, cutting, or packaging operations. The equipment maintains precise web tension through dancer rolls, load cells, or electronic feedback systems to prevent wrinkles, breaks, or registration errors during high-speed processing. Automatic unwinders command the dominant share of new capital expenditure as converters prioritize labor reduction and changeover speed, while high-speed unwinders represent the fastest-expanding category driven by investments in lines exceeding 600 meters per minute. Mechanical technology still occupies the largest installed base, though electric and pneumatic systems are displacing hydraulic alternatives in greenfield projects due to cleaner operation and lower maintenance burden.
FDA regulations on paper product contact surfaces influence material selection for unwind components in North American tissue operations, while CE marking and EU Machinery Directive compliance shape design standards for equipment sold across European markets. ISO 9001 and ISO 14001 certifications function as baseline qualification criteria for OEMs bidding on multinational converter tenders, effectively filtering out smaller suppliers lacking documented quality and environmental management systems. Stakeholders must weigh total cost of ownership against upfront capital outlay as energy efficiency and automation depth increasingly determine competitive viability in converter procurement decisions.
Market Dynamics
Direct-drive servo technology is collapsing the historical performance gap between entry-level and premium unwinder tiers, forcing converters to reevaluate capital allocation strategies across equipment replacement cycles. This mechanical-electrical transition sits at the center of current market restructuring.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:OEMs face binding mandates to reduce energy draw and material waste in converting equipment, accelerating R&D investment in regenerative drive systems and lightweight frame architectures.
- Lightweight tissue grades:North American converters handling sub-12 gsm basis weights require precision tension control that legacy mechanical shaft systems cannot deliver, pulling demand toward electronic feedback architectures.
- Retailer sustainability audits:German mid-sized converters are modernizing aging unwind fleets to secure private-label contracts with major retail chains that now mandate documented carbon footprint reductions across supply chains.
Market Restraints
- Steel and copper price volatility:Frame fabrication and motor windings constitute 35-40% of bill-of-materials costs, exposing OEM margins to commodity swings that converter procurement teams resist absorbing through escalation clauses.
- Specialized servo drive supplier concentration:Precision motion control components for three-meter diameter roll handling originate from a narrow base of German and Japanese suppliers, creating single-source vulnerability for tier-two OEMs.
- Hydraulic system legacy lock-in:Converters with 1990s-era unwind fleets face stranded asset risk as hydraulic fluid disposal regulations tighten and qualified maintenance technicians retire from the workforce.
Strategic Opportunities
- Modular reconfiguration architectures:A.Celli Paper's platform approach allows converters to reorient line layouts without greenfield construction, unlocking capacity expansion in constrained European industrial zones.
- Kitchen roll specialty applications:Perforation pattern complexity and embossed texture requirements create demand for unwind systems with micron-level registration accuracy that commodity suppliers cannot match.
- CE marking harmonization:Streamlined EU Machinery Directive compliance pathways reduce certification timelines for OEMs, accelerating market entry for innovative pneumatic braking systems that displace hydraulic alternatives.
Industry Challenges
- Mechatronics technician scarcity:Integration of servo drives, load cells, and PLC networks requires cross-functional expertise that vocational training programs have not scaled to match equipment complexity growth.
- Legacy control system interoperability:Brownfield installations demand protocol translation layers between 1990s-era proprietary networks and modern Ethernet-based automation platforms, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Roll Unwinders Market |
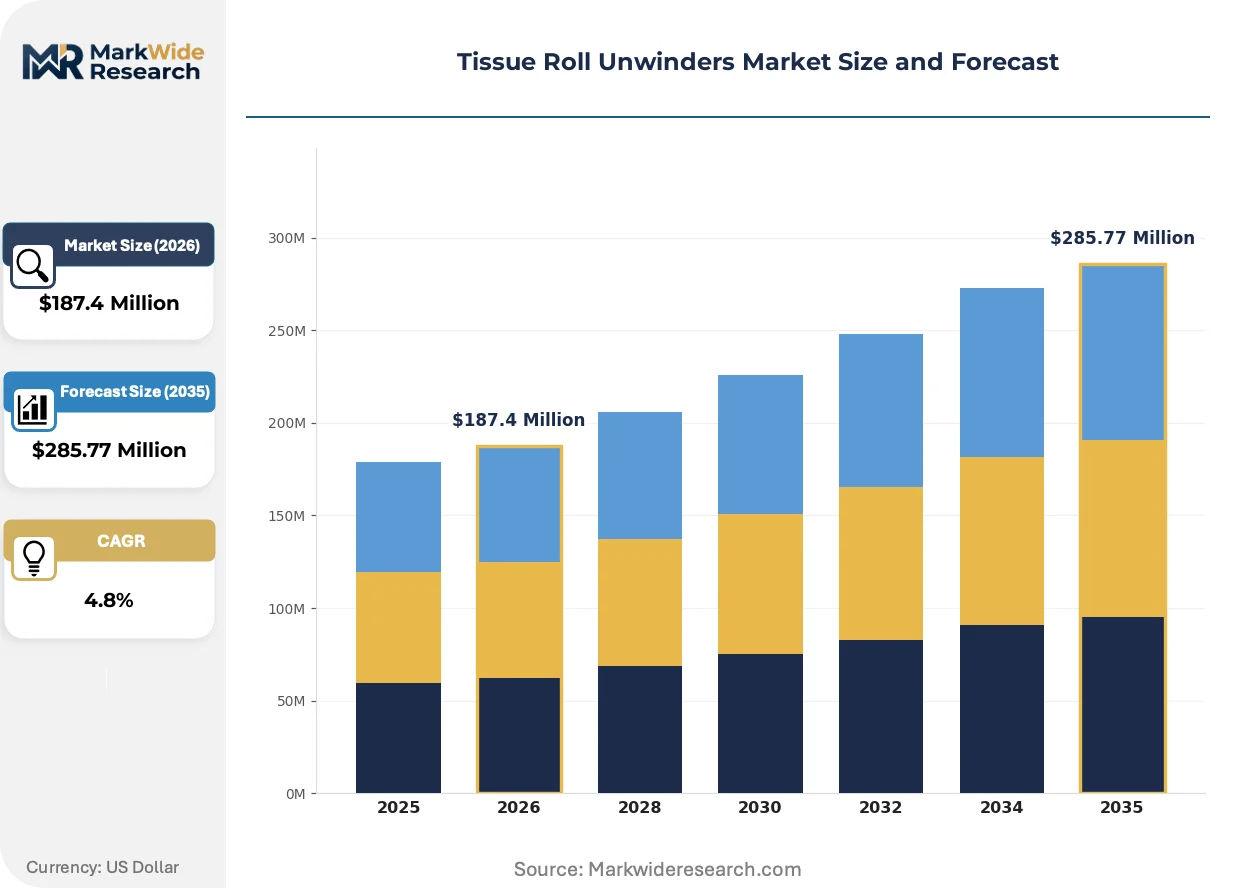
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Unwinders, Automatic Unwinders, Semi-Automatic Unwinders, High-Speed Unwinders Technology: Mechanical, Pneumatic, Electric, Hydraulic End User: Manufacturers, Converters, Retailers, Wholesalers Application: Toilet Tissue, Kitchen Roll, Paper Towels, Other Paper Products |
| Companies Covered | M.Torres, Valmet, Fabio Perini, Toscotec, STEPA, CFE Nordic, Gambini, A.Celli Paper, Paper Converting Machine Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Roll Unwinders Market Evolving Landscape
Automation depth and energy recovery systems are redefining competitive differentiation in tissue converting, with line speed capabilities now table stakes rather than premium features. Equipment buyers increasingly weight operational expenditure profiles against capital outlay in procurement decisions.
Direct-drive servo unwinders are collapsing the historical three-tier equipment hierarchy that separated mechanical shaft, pneumatic brake, and fully electronic systems into distinct price-performance categories. Mid-sized converters in Italy and Spain are adopting servo architectures at twice the pace of the prior decade, compressing payback period calculations from seven years to under four and eroding the installed base advantage of legacy hydraulic OEMs.
REACH restrictions on hydraulic fluid formulations are forcing European OEMs to redesign brake systems around water-glycol or purely electric alternatives, eliminating the maintenance cost advantage that hydraulic technology previously held in high-torque applications. The regulation most acutely affects unwinders handling parent rolls exceeding two tons, where friction braking thermal loads previously mandated oil-based cooling circuits.
Converter procurement teams are unbundling after-sales service contracts from equipment purchases, demanding itemized pricing for spare parts and remote diagnostics rather than bundled maintenance agreements. This behavioral shift is most pronounced in the Nordic countries, where tissue converters operate centralized engineering functions that prefer in-house technician deployment over OEM field service dependence.
Tissue Roll Unwinders Market Segmentation
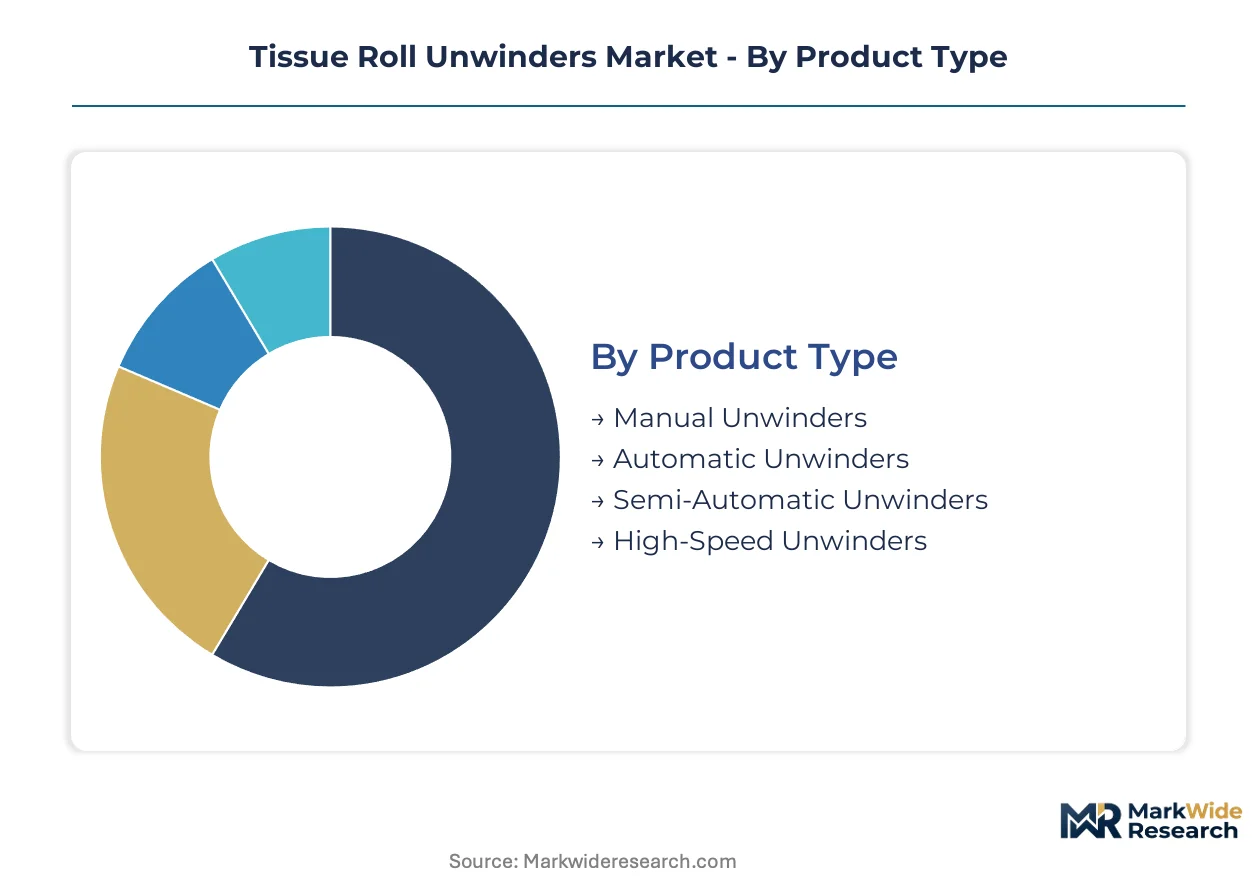
Equipment segmentation in tissue converting reveals distinct capital replacement cycles and margin profiles across automation tiers. Procurement patterns diverge sharply between volume-driven commodity producers and specialty converters seeking registration precision.
Product Type:
Automatic unwinders turn over fastest in capital planning cycles, while manual systems persist longest in installed bases. High-speed variants command premium replacement frequency due to wear-intensive duty cycles.
- Automatic Unwinders:Electronic feedback systems eliminate manual tension adjustment, cutting changeover intervals to under three minutes. German mid-sized converters prioritize these units to satisfy retailer sustainability audits demanding documented labor reduction and throughput gains.
- High-Speed Unwinders:Servo-driven architectures handle line speeds exceeding 600 meters per minute with micron-level web stability. Italian and Spanish converters adopt these at twice prior-decade rates, compressing payback calculations from seven years to under four.
- Manual Unwinders:Mechanical shaft systems dominate legacy installed bases in emerging markets with limited capital access.
- Semi-Automatic Unwinders:Hybrid pneumatic-mechanical braking serves budget-constrained converters upgrading from purely manual operations.
Automatic unwinders anchor the volume base while high-speed unwinders gain share at the steepest rate.
Technology:
Cost tiers separate clean-operation electric systems from maintenance-intensive hydraulic alternatives. Pneumatic architectures occupy the mid-market position where capital constraints meet regulatory pressure.
- Electric:Direct-drive servo motors with regenerative braking recover energy during deceleration cycles. REACH restrictions on hydraulic fluid formulations accelerate displacement of oil-based systems in European installations handling parent rolls exceeding two tons.
- Mechanical:Shaft-driven friction brakes rely on operator skill for tension management. These systems persist in North American operations running heavier basis weights where legacy technician expertise offsets automation premiums.
- Pneumatic:Air-actuated braking delivers cleaner operation than hydraulic alternatives without servo cost premiums. CE marking harmonization streamlines certification for these systems across EU Machinery Directive compliance pathways.
- Hydraulic:Oil-cooled high-torque braking faces stranded asset risk as fluid disposal regulations tighten and qualified maintenance technicians retire from workforce pools.
Mechanical technology retains the largest installed base while electric systems climb the fastest in new capital expenditure.
End User:
Customer type determines specification depth, with converters demanding precision registration that manufacturers often bypass for throughput maximization.
- Converters:Independent tissue processors require unwind systems compatible with diverse parent roll sources and frequent grade changes. These operators drive demand for modular reconfiguration architectures that permit line layout changes without greenfield construction.
- Manufacturers:Integrated pulp-to-tissue producers prioritize automation platforms spanning multiple process stages. Valmet sustains leadership here through integrated control systems that unify pulp preparation with converting workflows.
- Retailers:Private-label contract holders specify equipment standards through supply chain sustainability mandates.
- Wholesalers:Distribution-focused entities emphasize spare parts availability and remote diagnostic capability over performance specifications.
Converters anchor the volume base while manufacturers gain share at the steepest rate.
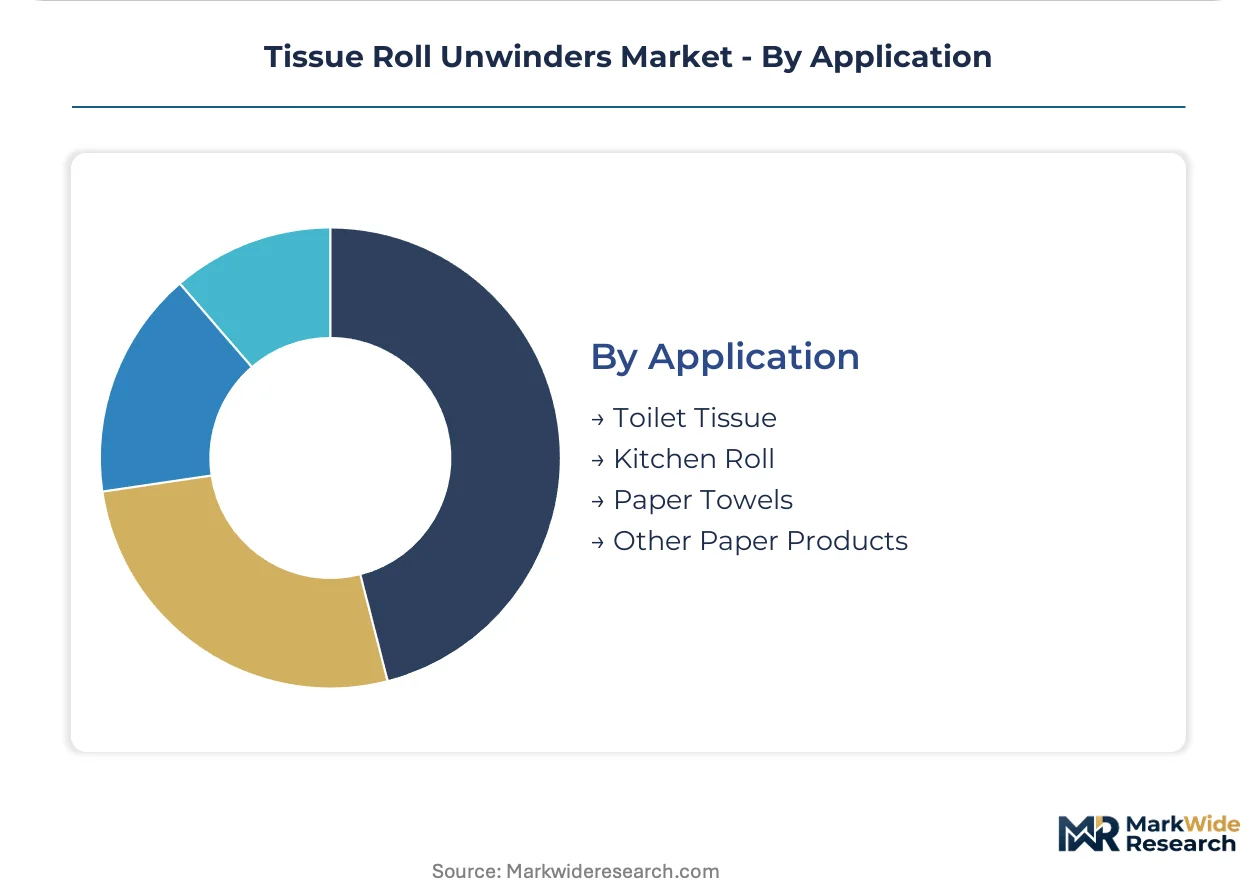
Application:
Application maturity varies, with kitchen roll demanding registration complexity that toilet tissue specifications rarely require.
- Kitchen Roll:Perforation pattern complexity and embossed texture requirements demand unwind systems with micron-level registration accuracy. Fabio Perini anchors European supply for this segment with specialized unwind solutions purpose-built for towel applications.
- Toilet Tissue:Standardized folding and cutting operations permit simpler tension control architectures. FDA regulations on paper product contact surfaces influence component material selection in North American installations serving this mass-market category.
- Paper Towels:Industrial and commercial grades prioritize absorbency consistency over aesthetic registration precision.
- Other Paper Products:Niche specialty grades including facial tissue and napkin stocks require customized unwind configurations.
Toilet tissue anchors the volume base while kitchen roll gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian unwind equipment exports flow primarily to German and Spanish converters modernizing aging production lines. North American tissue processors source European servo-drive systems to handle sub-12 gsm basis weights. Asian markets absorb refurbished mechanical units from decommissioned European mills.
Germany
Mid-sized converters in Baden-Württemberg and North Rhine-Westphalia drive replacement demand for aging hydraulic unwind fleets. EU Ecodesign for Sustainable Products Regulation mandates documented energy draw reductions, pressuring OEMs to deliver regenerative drive architectures. Stuttgart industrial clusters host retrofit programs targeting 1990s-era equipment for retailer sustainability audit compliance.
United States
Southeast tissue corridors in Georgia and South Carolina pursue line speed upgrades exceeding 600 meters per minute. FDA regulations on paper product contact surfaces govern material selection for unwind components serving consumer tissue grades. Charlotte and Greenville manufacturing zones concentrate parent roll handling capacity for private-label retail supply.
Italy
Lombardy and Tuscany converters adopt servo-driven unwinders at twice prior-decade rates, compressing capital recovery timelines. REACH restrictions on hydraulic fluid formulations accelerate displacement of oil-cooled brake systems in Lucca paper districts. Bologna-area equipment fabricators specialize in kitchen roll registration systems for embossed texture applications.
Spain
Catalonia and Valencia tissue processors prioritize modular reconfiguration architectures to expand capacity without greenfield construction. CE marking harmonization under EU Machinery Directive streamlines certification for pneumatic braking alternatives. Barcelona industrial zones concentrate mid-market converter operations seeking flexible line layouts.
China
Yangtze River Delta tissue manufacturers integrate unwind systems into pulp-to-converting workflows for throughput maximization. GB standards and MIIT industrial efficiency directives shape equipment specification for domestic procurement. Shanghai and Jiangsu province clusters absorb both European premium systems and domestically fabricated mechanical alternatives.
Tissue Roll Unwinders Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated automation platforms command premium positioning against modular specialists. The vendor base separates into three strategic archetypes: pulp-to-converting integrators, application-specific unwind specialists, and regional fabrication houses serving price-sensitive markets. Dominant competitive moves include portfolio diversification into adjacent converting equipment and geographic expansion through distribution partnerships in emerging tissue markets.
Within the integrated automation tier, Valmet exemplifies cross-process platform control spanning pulp preparation through converting workflows. Fabio Perini and A.Celli Paper occupy distinct specialist positions, with the former anchoring European kitchen roll applications and the latter representing modular architecture approaches for flexible line reconfiguration. These three entities collectively illustrate the competitive spectrum from full-process integration to targeted application expertise.
| Leading Market Players |
|---|
| M.Torres |
| Valmet |
| Fabio Perini |
| Toscotec |
| STEPA |
| CFE Nordic |
| Gambini |
| A.Celli Paper |
| Paper Converting Machine Company |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine Corridor freight rates shape cost-to-serve dynamics for Italian unwind equipment bound for German converters, compressing margins on mid-tier pneumatic systems while amplifying price premiums for regenerative electric architectures that offset landed cost through energy recovery.
Pricing Analysis
Next-generation direct-drive servo unwinders command 40-60% premiums over prior-generation hydraulic equivalents, while entry-level mechanical shaft systems anchor the economy tier. Three-tier pricing structure across premium, standard, and economy levels separates regenerative electric architectures from pneumatic-mechanical hybrids from legacy hydraulic units. Price differentiation rests on CE marking tier and after-sales service bundling, with Nordic buyers unbundling maintenance contracts to drive component-level transparency. Cost compression in the hydraulic tier is intensifying because REACH fluid disposal regulations strand aging installed bases. Commodity converters in Spain exhibit highest price sensitivity, while German mid-sized operators pursuing retailer sustainability audits show lowest sensitivity to upfront capital outlay.
Supply Chain Analysis
Bologna-area fabrication clusters and Stuttgart industrial zones concentrate contract manufacturing capacity for precision unwind frames and servo integration modules. Component sourcing draws from German and Japanese precision motion control suppliers for three-meter roll handling systems, Chinese steel mills for frame fabrication, and Italian foundries for dancer roll castings. Single-source vulnerability for specialized servo drives creates supply chain risk for tier-two OEMs lacking dual-qualified component pipelines. Distribution runs through direct OEM-converter relationships for large installations, with regional distributors handling aftermarket spare parts and retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as digital twin-based predictive maintenance platforms threaten to commoditize traditional unwinder hardware through performance-guarantee service models.
For Market Incumbents: Harden installed base retention by embedding remote diagnostic capabilities that lock converters into proprietary automation ecosystems, countering modular competitors. Deepen backward integration into servo drive calibration and regenerative braking subsystems to capture margin pools currently flowing to German and Japanese component suppliers. Prioritize certification investment in EU Ecodesign compliance documentation to preempt retailer audit requirements.
For New Entrants and Emerging Players: Establish a beachhead in kitchen roll specialty unwinders where perforation registration complexity creates defensible technical moats against commodity suppliers. Target Spanish mid-market converters seeking modular reconfiguration architectures without greenfield construction permits. Pursue go-to-market partnerships with Bologna-area equipment fabricators possessing established CE marking pathways and regional converter relationships.
For Investors and Strategic Acquirers: Application-specific unwind specialists with captive intellectual property in embossed texture registration systems represent priority acquisition targets given kitchen roll segment growth trajectories. Long-term viability frames around 5-10 year equipment replacement cycles accelerating as EU Ecodesign mandates harden and hydraulic technician pools contract. Monitor German retailer sustainability audit scope expansion as inflection signal for regenerative drive demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Systems | Captures margin pools from German and Japanese component suppliers while securing supply continuity. |
| Modular Reconfiguration Architecture Launch | Enables Spanish and Italian converters to expand capacity without greenfield construction permits. |
| EU Ecodesign Compliance Certification | Unlocks German mid-sized converter procurement decisions tied to retailer sustainability audits. |
| Remote Diagnostics Platform Deployment | Locks Nordic converters into proprietary ecosystems as they unbundle traditional maintenance contracts. |
| Kitchen Roll Specialty Unwinder Development | Addresses perforation complexity requirements that commodity suppliers cannot satisfy at scale. |
Research Methodology
Cross-validation between primary interviews with tissue converting plant engineers, OEM product managers, and aftermarket service directors anchors the qualitative findings against secondary validation from EU Ecodesign regulatory filings, CE marking certification databases, and customs trade records for unwind equipment imports. Bottom-up triangulation across converter capital expenditure surveys and top-down reconciliation with OEM order book disclosures ensures demand-side and supply-side figures converge. Secondary sources include machinery directive compliance registries, REACH restriction impact assessments, and regional industrial cluster development reports.
Calibration against historical replacement cycle patterns and technology transition timelines shapes the analytical framework across the analysis window. Segmentation dimensions modeled include automation tier, braking technology architecture, end-user integration depth, and application-specific registration requirements. CAGRs derive from equipment shipment trajectories weighted by average selling price evolution and regional procurement intensity indices. Forecast inputs incorporate EU Ecodesign implementation phase timelines and REACH hydraulic fluid restriction enforcement schedules.
Sensitivities concentrate around steel and copper commodity price volatility, German-Japanese servo supplier concentration risk, and retailer sustainability audit scope expansion timing. Forecasts reflect assumptions regarding technology transition velocity and regulatory enforcement consistency without guaranteeing outcome realization. Quarterly review of OEM order backlogs, converter capital commitment announcements, and EU implementing act publications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Multihead Weighers Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Table Top Band Sealer Market