
 Volumetric Filing Lines Market | 2026-2036
Volumetric Filing Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Volumetric Filing Lines Market Analytics
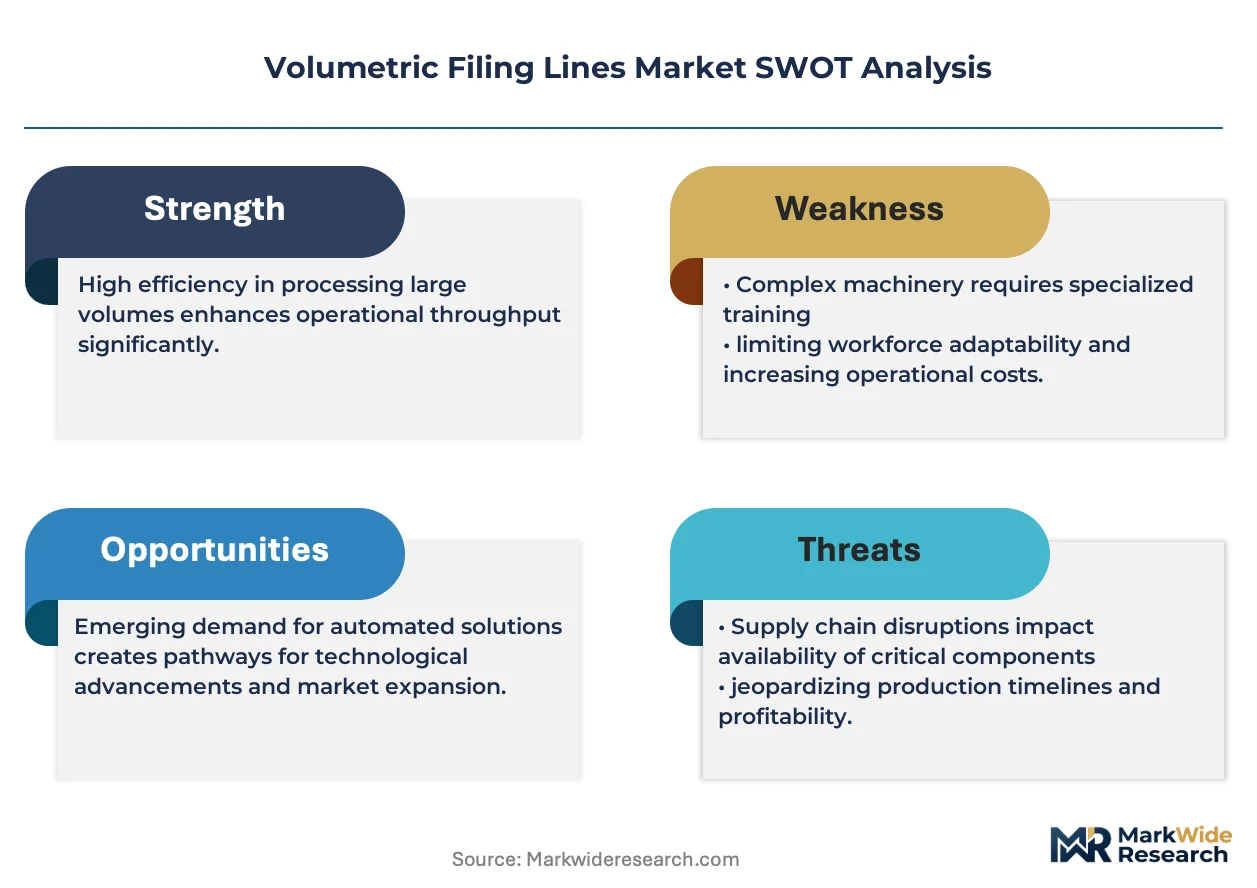
REACH compliance is broadening the cost-of-entry calculus for European suppliers of volumetric filling equipment. Krones AG leverages its captive engineering base in Neutraubling to sustain premium positioning in aseptic liquid filling. GEA Group anchors pharmaceutical-grade system sales through its Freund subsidiary, while Tetra Pak competes aggressively on dairy and beverage carton integration.
Volumetric filling lines are precision-engineered systems that dispense predetermined liquid volumes into containers using piston pumps, flow meters, or gravity-fed nozzles with accuracy tolerances typically within plus or minus 0.5 percent. Their primary industrial purpose centers on high-throughput packaging of pharmaceuticals, beverages, and personal care products where dosage consistency directly affects product safety and regulatory compliance. Fully automatic systems command the dominant share of capital deployment as manufacturers prioritize throughput rates exceeding 600 units per minute. Fluid dynamics technology leads equipment differentiation, though IoT integration represents the fastest-growing capability segment as remote diagnostics and predictive maintenance reshape service revenue models.
FDA cGMP standards, EU MDR device classification rules, and ISO 15378 primary packaging materials requirements collectively determine product design specifications and market access pathways for equipment vendors. EMA inspections of filling line validation protocols are intensifying across contract manufacturing organizations, directly stimulating replacement demand for compliant systems. Stakeholders must monitor evolving serialization mandates and their hardware implications for line retrofit decisions.
Market Dynamics
FDA cGMP guideline revisions for sterile drug products are forcing pharmaceutical manufacturers to retire legacy filling infrastructure ahead of depreciation schedules. This regulatory compression is reshaping capital allocation across contract manufacturing organizations and multinational drug makers.
Growth Catalysts
- EU MDR device classification rules:Stricter validation protocols for pharmaceutical packaging equipment are accelerating replacement cycles among European contract manufacturers.
- Biologics manufacturing expansion:mRNA vaccine production facilities require aseptic filling lines with single-use fluid path technologies, driving specialized equipment procurement.
- German precision engineering clusters:Concentrated supplier ecosystems around Bavaria and Baden-Württemberg enable rapid customization for pharmaceutical-grade applications.
Market Restraints
- Stainless steel alloy price volatility:316L pharmaceutical-grade steel input costs fluctuate with nickel market conditions, compressing margin visibility for equipment fabricators.
- Validation protocol complexity:FDA cGMP sterile product guidelines extend commissioning timelines by 40-60 percent versus non-sterile applications, freezing working capital.
- Peristaltic pump substitution:Lower-capital alternatives for low-viscosity liquids threaten entry-level volumetric system demand in personal care segments.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO quality mandate enforcement is driving domestic capacity upgrades for export-compliant filling infrastructure.
- Cell and gene therapy:Personalized medicine batch sizes below 1,000 units demand flexible, rapid-changeover filling platforms absent from current product portfolios.
- IoT-enabled predictive maintenance:Convergence of edge computing and vibration sensing creates recurring revenue streams through remote diagnostics subscriptions.
Industry Challenges
- Commissioning engineer scarcity:Qualified FAT/SAT validation specialists for aseptic pharmaceutical lines command premium compensation, constraining deployment velocity.
- Legacy SCADA integration:Brownfield facilities running Rockwell or Siemens S7-300 architectures face protocol translation complexity when retrofitting modern filling modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volumetric Filing Lines Market |
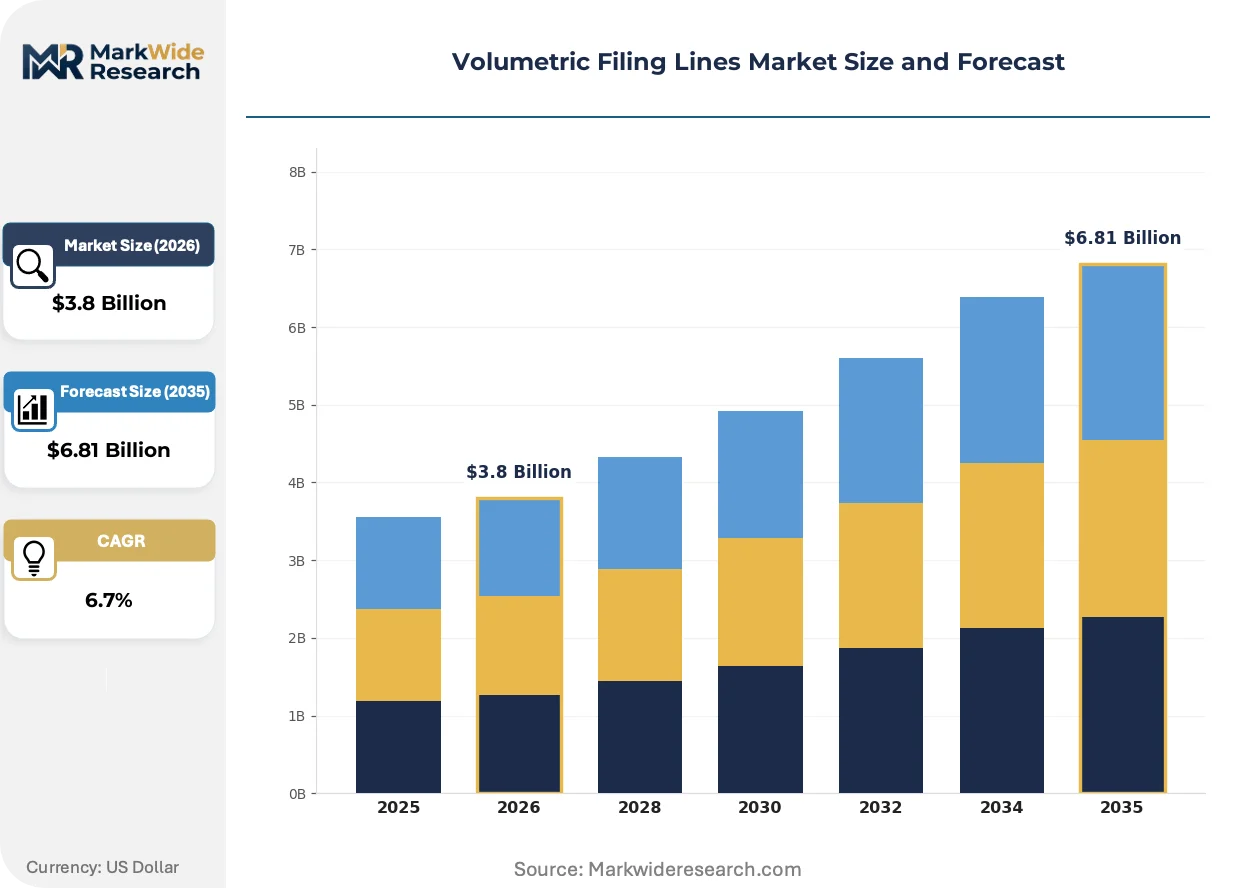
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Robotic Industry Vertical: Pharmaceutical, Food & Beverage, Cosmetics, Chemicals End User: Manufacturers, Distributors, Retailers, Contract Packagers Technology: Fluid Dynamics, Weighing Technology, Camera Systems, IoT Integration |
| Companies Covered | Krones AG, Tetra Pak, GEA Group, Bosch Packaging Technology, Coesia S.p.A., KHS GmbH, All-Fill, Accutek Packaging Equipment, CFT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volumetric Filing Lines Market Evolving Landscape
Fluid dynamics engineering and digital thread architectures are converging to redefine equipment differentiation. Vendors now compete on validation data integrity and line integration speed rather than mechanical throughput alone.
Single-use disposable fluid paths are consolidating aseptic processing workflows by eliminating CIP/SIP cycles between product changeovers. Biologics manufacturers adopt these systems for multi-product facilities where cross-contamination risk outweighs consumable costs. This technology is consolidating market share among flexible, lower-volume production environments previously served by stainless steel systems.
EMA inspection intensity for filling line validation protocols has intensified across European contract manufacturing organizations. The regulator's focus on data integrity and computerized system validation is forcing equipment vendors to pre-qualify software architectures before shipment. German and Swiss pharmaceutical packaging specialists are responding with embedded audit trail functionality as standard configuration.
Service contract unbundling is fragmenting traditional vendor-customer relationships. Pharmaceutical buyers now separate hardware procurement from validation support and spare parts agreements, treating each as distinct sourcing decisions. This pattern is most visible among mid-cap generic drug manufacturers in India and Eastern Europe seeking to optimize total cost of ownership.
Volumetric Filing Lines Market Segmentation
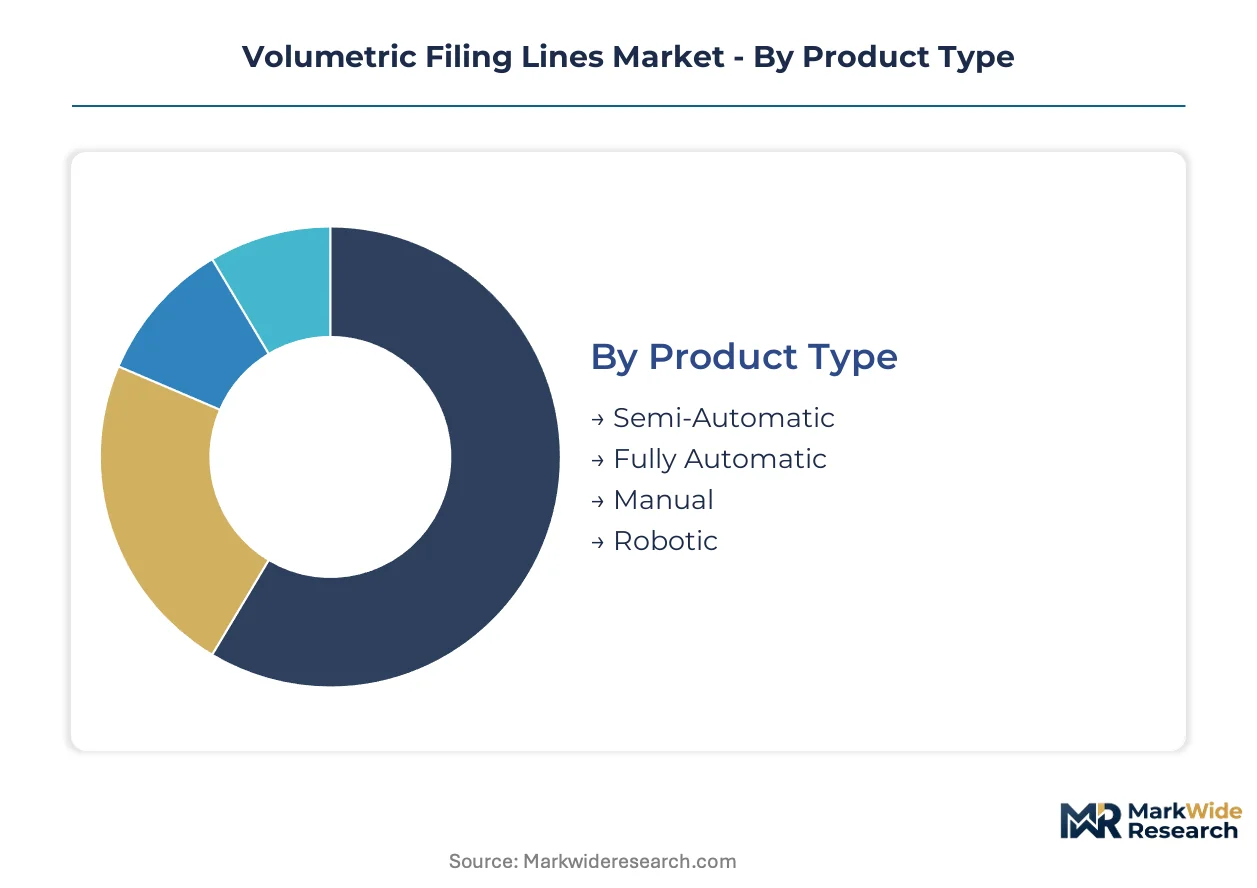
Equipment segmentation in the volumetric filling lines market reveals distinct upgrade cycles across automation tiers and end-use applications. Pharmaceutical manufacturers drive replacement demand through regulatory compliance mandates, while beverage and cosmetics sectors prioritize throughput economics over validation intensity.
Product Type:
Replacement cycles diverge sharply between automation tiers, with legacy semi-automatic systems facing accelerated retirement in regulated environments.
- Fully Automatic:Systems integrate piston pumps, flow meters, and servo-driven nozzles achieving throughput rates exceeding 600 units per minute with plus or minus 0.5 percent accuracy tolerance. Pharmaceutical manufacturers in Germany and Switzerland deploy these lines for aseptic sterile drug products under FDA cGMP and EMA inspection protocols, where validation documentation requirements extend commissioning timelines substantially.
- Semi-Automatic:Equipment combines operator-assisted loading with automated dispensing cycles, occupying the mid-tier for batch production below 10,000 units. Food and beverage processors in India favor these systems for seasonal product runs where capital constraints limit full automation investment, though CDSCO quality mandate enforcement is gradually tightening acceptable equipment standards.
- Manual:Hand-operated piston fillers serve micro-batch production below 1,000 units, prevalent in artisanal cosmetics and specialty chemical compounding where product variety exceeds volume scale.
- Robotic:Collaborative robot arms with vision-guided picking enable rapid container handling and changeover sequences, gaining traction in cell and gene therapy facilities requiring flexible batch sizes.
Volume placements concentrate in fully automatic configurations; the faster expansion belongs to robotic systems.
Industry Vertical:
Margin structures and validation burdens create divergent procurement patterns across end-use sectors.
- Pharmaceutical:Aseptic filling lines for injectables, ophthalmics, and biologics demand stainless steel 316L construction, single-use fluid path options, and embedded audit trail functionality. EMA inspection intensity across European contract manufacturing organizations accelerates replacement of legacy infrastructure lacking computerized system validation compliance.
- Food & Beverage:High-speed rotary fillers for dairy, juices, and carbonated drinks prioritize clean-in-place cycles and carton integration capabilities. Tetra Pak competes aggressively in this segment through beverage carton integration expertise.
- Cosmetics:Viscous product handling for creams, lotions, and serums requires heated hopper systems and piston pump configurations, with personal care manufacturers balancing peristaltic pump substitution threats against volumetric precision requirements.
- Chemicals:Corrosive-resistant materials and explosion-proof electrical enclosures dominate specifications for agrochemical and industrial solvent filling, with REACH compliance broadening supplier qualification burdens in Europe.
Revenue concentration sits with pharmaceutical applications; cosmetics and chemicals are climbing the fastest as emerging market manufacturing scales.
End User:
Procurement authority fragmentation reshapes vendor engagement models across the customer base.
- Contract Packagers:Multi-product facilities demand rapid changeover capabilities and flexible line configurations, driving single-use disposable fluid path adoption to eliminate cross-contamination risks between biologics campaigns.
- Manufacturers:Captive production operations prioritize total cost of ownership optimization through IoT-enabled predictive maintenance subscriptions and unbundled service contracts separating hardware from validation support.
- Distributors:Regional equipment resellers focus on spare parts availability and local commissioning engineer networks, particularly constrained in India and Eastern Europe where qualified FAT/SAT validation specialists command premium compensation.
- Retailers:Private-label packaging operations favor lower-capital semi-automatic systems for seasonal and promotional product lines with uncertain volume continuity.
Contract packagers anchor equipment demand; manufacturers represent the steepest expansion trajectory as in-house biologics capacity expands.
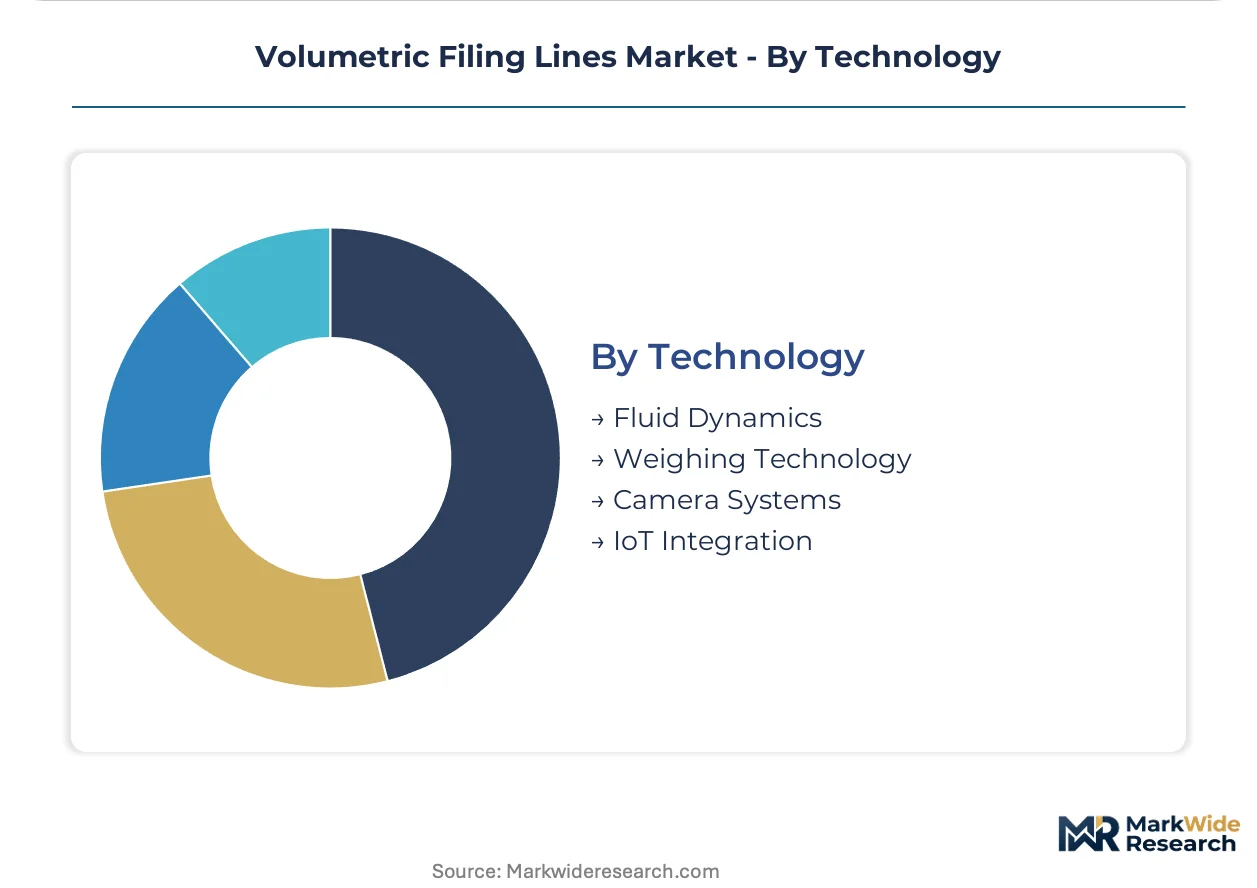
Technology:
Digital capability integration now determines competitive differentiation beyond mechanical throughput specifications.
- Fluid Dynamics:Precision-engineered nozzle geometries and laminar flow control minimize foaming and splashing in high-speed liquid dispensing, remaining the foundational engineering discipline for equipment vendors.
- IoT Integration:Edge computing architectures with vibration sensing and remote diagnostics capabilities create recurring revenue streams through subscription-based maintenance models, expanding most quickly among pharmaceutical buyers seeking predictive failure avoidance.
- Weighing Technology:In-line checkweighing feedback loops enable real-time volume correction, prevalent in high-value pharmaceutical applications where dosage accuracy directly affects patient safety.
- Camera Systems:Machine vision inspection for fill level verification, cap placement confirmation, and label alignment supports automated rejection protocols, increasingly bundled as standard rather than optional configuration.
Fluid dynamics retains the largest installed base; IoT integration is gaining share fastest as service revenue models reshape vendor economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's precision engineering clusters around Neutraubling concentrate German filling equipment manufacturing, while Swiss pharmaceutical packaging specialists anchor Alpine supply chains for aseptic systems.
Germany
Pharmaceutical-grade stainless steel fabrication and FDA cGMP validation expertise concentrate equipment demand in Bavaria and Baden-Württemberg. REACH compliance broadens supplier qualification burdens for European chemical processors. The Neutraubling engineering base sustains captive development of servo-driven piston pump architectures for biologics manufacturers.
Switzerland
Swissmedic inspection protocols for sterile drug products drive replacement of legacy filling infrastructure across contract manufacturing organizations. Embedded audit trail functionality becomes standard configuration as computerized system validation requirements tighten. Basel and Zurich pharmaceutical packaging specialists integrate single-use fluid paths for multi-product biologics facilities.
United States
FDA cGMP guideline revisions for sterile drug products accelerate capital deployment among multinational drug makers and CDMOs. The IRA's domestic manufacturing incentives reshape biologics capacity expansion timelines. Greater Boston and Research Triangle Park biotech clusters demand rapid-changeover filling platforms for personalized medicine batch production.
India
CDSCO quality mandate enforcement drives domestic capacity upgrades for export-compliant filling infrastructure among generic drug manufacturers. Maharashtra and Gujarat pharmaceutical manufacturing zones prioritize IoT-enabled predictive maintenance subscriptions to optimize total cost of ownership. Pune and Ahmedabad contract packagers adopt single-use disposable fluid paths to eliminate cross-contamination risks.
China
NMPA alignment with international GMP standards accelerates replacement cycles for legacy semi-automatic systems in biologics manufacturing. Yangtze River Delta pharmaceutical clusters demand aseptic filling lines with remote diagnostics capabilities. Shanghai and Suzhou equipment procurement concentrates on validation data integrity for EMA-inspected export production.
Volumetric Filing Lines Market Competitive Landscape
German producers anchor one tier; Swiss and Italian specialists hold differentiated positions in pharmaceutical-grade applications. The vendor structure concentrates around precision engineering clusters with deep captive fabrication capabilities. Three archetypes dominate: integrated packaging conglomerates with beverage-to-pharma breadth; pure-play filling equipment specialists; and diversified industrial automation vendors extending into liquid handling. Competitive moves center on unbundled service contract architectures and predictive maintenance subscription models.
Among German-based fabricators, Krones AG exemplifies the integrated packaging conglomerate archetype through its Neutraubling engineering base. GEA Group occupies a position within pharmaceutical-grade system supply, while Tetra Pak represents beverage carton integration specialization. Bosch Packaging Technology anchors diversified industrial automation extension into aseptic liquid filling. These entities collectively illustrate how geographic concentration in Central European engineering clusters shapes competitive positioning through proximity to pharmaceutical validation expertise and stainless steel supply chains.
| Leading Market Players |
|---|
| Krones AG |
| Tetra Pak |
| GEA Group |
| Bosch Packaging Technology |
| Coesia S.p.A. |
| KHS GmbH |
| All-Fill |
| Accutek Packaging Equipment |
| CFT Group |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification ladders separate premium aseptic filling systems from commodity beverage lines, with FDA cGMP validation tiers commanding substantial price premiums while concentrating supply chain control among Bavarian and Swiss engineering clusters capable of embedded audit trail architectures.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid delivery with premium positioning, as German and Swiss manufacturers extract 15-25 percent markups for validated systems shipping under compressed commissioning schedules. Three-tier pricing structure across pharmaceutical-grade, food-beverage, and personal care levels reflects certification intensity, with stainless steel 316L construction and single-use fluid path options driving differentiation. Pricing pressure stems from Indian generic manufacturers unbundling hardware procurement from validation support to optimize total cost of ownership. Contract packagers exhibit highest price sensitivity, while biologics manufacturers prioritize validation data integrity over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Neutraubling, Basel, and Shanghai anchor hub-and-spoke patterns for spare parts and commissioning engineer deployment. Supply concentration rests on Germany, Switzerland, and China, with Bavarian precision engineering clusters feeding pharmaceutical-grade fabrication and Yangtze River Delta facilities serving domestic biologics capacity expansion. Raw material dependencies center on 316L stainless steel, servo-drive components, and single-use polymer consumables. Single-source vulnerability in qualified FAT/SAT validation specialists constrains deployment velocity. Distribution runs through OEM-direct channels for pharmaceutical applications and regional resellers for beverage and personal care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance capabilities, with FDA cGMP guideline revisions and EMA inspection intensity forcing capital-constrained mid-tier vendors toward exit or acquisition.
For Market Incumbents: Hedge against peristaltic pump substitution in personal care segments by deepening captive engineering control over single-use fluid path technologies. Incumbents should anchor pharmaceutical-grade positioning through embedded audit trail functionality as standard configuration, while building predictive maintenance subscription revenue to offset hardware margin compression from unbundled procurement patterns. For New Entrants and Emerging Players: Contract packagers in India and Eastern Europe represent the most penetrable channel partner type, given scarcity of qualified commissioning engineers and appetite for rapid-changeover flexible platforms. New entrants should target cell and gene therapy batch production below 1,000 units, where robotic collaborative systems address unmet flexibility requirements. A validation-support-led go-to-market model differentiates against hardware-centric incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing captive stainless steel fabrication and FDA cGMP validation expertise, given IRA domestic manufacturing incentives and biologics capacity expansion timelines. Long-term viability over the analysis window favors vendors with recurring service revenue exceeding 35 percent of total mix. The signal to watch is CDSCO enforcement intensity driving replacement demand among Indian generic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Fluid Path Integration | Eliminates CIP/SIP cycles for biologics manufacturers running multi-product campaigns. |
| IoT Predictive Maintenance Platform | Converts vibration sensing data into subscription revenue streams with pharmaceutical buyers. |
| Validation Support Unbundling | Addresses Indian generic manufacturer procurement patterns optimizing total cost of ownership. |
| Robotic Flexible Batch Platform | Captures cell and gene therapy demand for rapid-changeover production below 1,000 units. |
| Embedded Audit Trail Architecture | Pre-qualifies software systems for EMA inspection protocols before shipment. |
Research Methodology
Regulatory filings with FDA and EMA, pharmaceutical equipment trade association databases, and stainless steel commodity price indices formed the secondary backbone for this analysis. Primary interviews with filling line engineering directors, contract manufacturing organization procurement leads, validation specialists, and aftermarket service heads combined with secondary validation through SEC filings and customs records. Bottom-up and top-down triangulation cross-checked equipment shipment data against pharmaceutical manufacturing capacity expansion announcements.
Bottom-up modeling anchored forecasts to unit economics across automation tiers, while top-down validation checked aggregate figures against pharmaceutical capital expenditure surveys. Segmentation dimensions included automation level, industry vertical, end-user archetype, and technology integration intensity across the projection horizon. CAGRs were derived from regression analysis against regulatory enforcement timelines and biologics manufacturing capacity buildouts, with inputs from REACH compliance cost assessments and CDSCO quality mandate implementation schedules.
Caveats apply where NMPA alignment timelines, nickel price volatility, or commissioning engineer availability constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and biologics manufacturing expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Tray Loader Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Die-Cutter Market