
 Kraftliner Market | 2026-2036
Kraftliner Market Size, Share, and Industry Trends Forecast 2026-2036
Kraftliner Market Intelligence
North American production capacity for virgin kraftliner is consolidating among large, integrated pulp and paper mills. International Paper leverages its vast forestry assets for consistent fiber supply. WestRock dominates high-performance grades for demanding packaging applications, while Stora Enso specializes in renewable packaging solutions for European markets.
Kraftliner is a paperboard material characterized by its high strength-to-weight ratio, derived from virgin softwood pulp using the Kraft process. Its primary function is to serve as the linerboard layers in the manufacture of corrugated fiberboard. While uncoated kraftliner remains the volume leader for standard boxes, coated and white top liner grades are gaining share in consumer goods packaging. The food & beverage segment drives demand for specialized grades that meet food-contact safety requirements.
Regulatory frameworks directly influence material specification and market access. In the United States, the FDA sets standards for kraftliner used in food packaging, while in Europe, compliance with EFSA guidelines and the EU's Packaging and Packaging Waste Regulation is mandatory. Global trade often relies on adherence to ISO standards for material performance. Producers must now navigate diverging regional requirements for recycled content and chemical safety.
Market Dynamics
The central tension shaping the kraftliner market is the conflict between sustainability-driven demand for recyclable packaging and the finite supply of certified virgin softwood fiber. This dynamic forces producers to balance performance, cost, and compliance with evolving circular economy mandates like the EU Green Deal.
Growth Catalysts
- E-commerce Packaging Demand:The expansion of e-commerce, particularly for food, beverages, and consumer electronics, requires strong, durable, and lightweight packaging, a core application for virgin kraftliner grades.
- Plastics Substitution Policies:Regulatory frameworks such as the EU Green Deal and various national single-use plastic bans encourage brand owners to shift to fiber-based packaging alternatives, favoring kraftliner for its recyclability.
- Industrialization in Southeast Asia:Rapid manufacturing and export-oriented growth in countries like Vietnam and Indonesia drives substantial consumption of kraftliner for corrugated boxes used in global supply chains.
Market Restraints
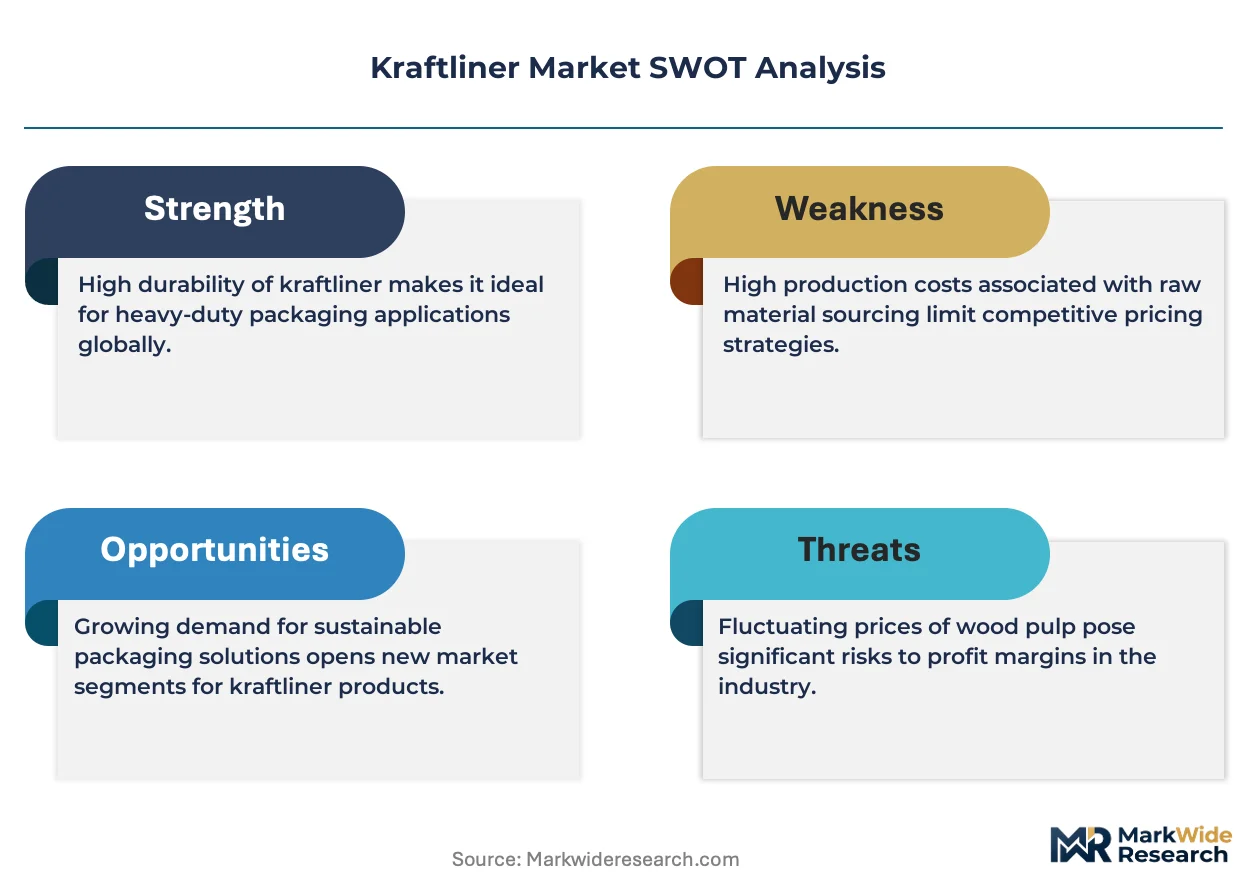
- Volatile Pulp Prices:As the primary raw material, virgin softwood pulp is subject to significant price fluctuations driven by energy costs, forestry management policies, and global supply-demand imbalances, impacting producer margins.
- Competition from Recycled Grades:Advances in testliner and recycled fluting are creating high-performance alternatives that compete with virgin kraftliner in certain applications, especially where cost is prioritized over maximum strength.
- High Capital Intensity:The construction of new integrated pulp and kraftliner mills requires massive capital investment and long lead times, creating a high barrier to entry and limiting supply elasticity.
Strategic Opportunities
- Food-Contact Grade Innovation:Development of specialized coatings and barrier technologies for kraftliner opens new applications in fresh produce and frozen food packaging, displacing less sustainable materials.
- Lightweighting for Performance:Engineering kraftliner with higher strength-to-weight ratios presents an opportunity to reduce material usage and transportation costs for customers, creating a clear value proposition.
- Digital Printing Compatibility:Enhancing the surface properties of white top and coated kraftliner to support high-quality digital printing allows for late-stage customization, serving the growing demand for personalized packaging.
Industry Challenges
- Navigating Divergent Regulations:Producers selling globally face the complex challenge of ensuring their products comply with a patchwork of regional standards, such as FDA rules in the US and EFSA guidelines in Europe.
- Energy and Water Consumption:The energy-intensive Kraft pulping process presents an ongoing operational challenge, requiring continuous investment in efficiency and renewable energy sources to manage costs and meet sustainability goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraftliner Market |
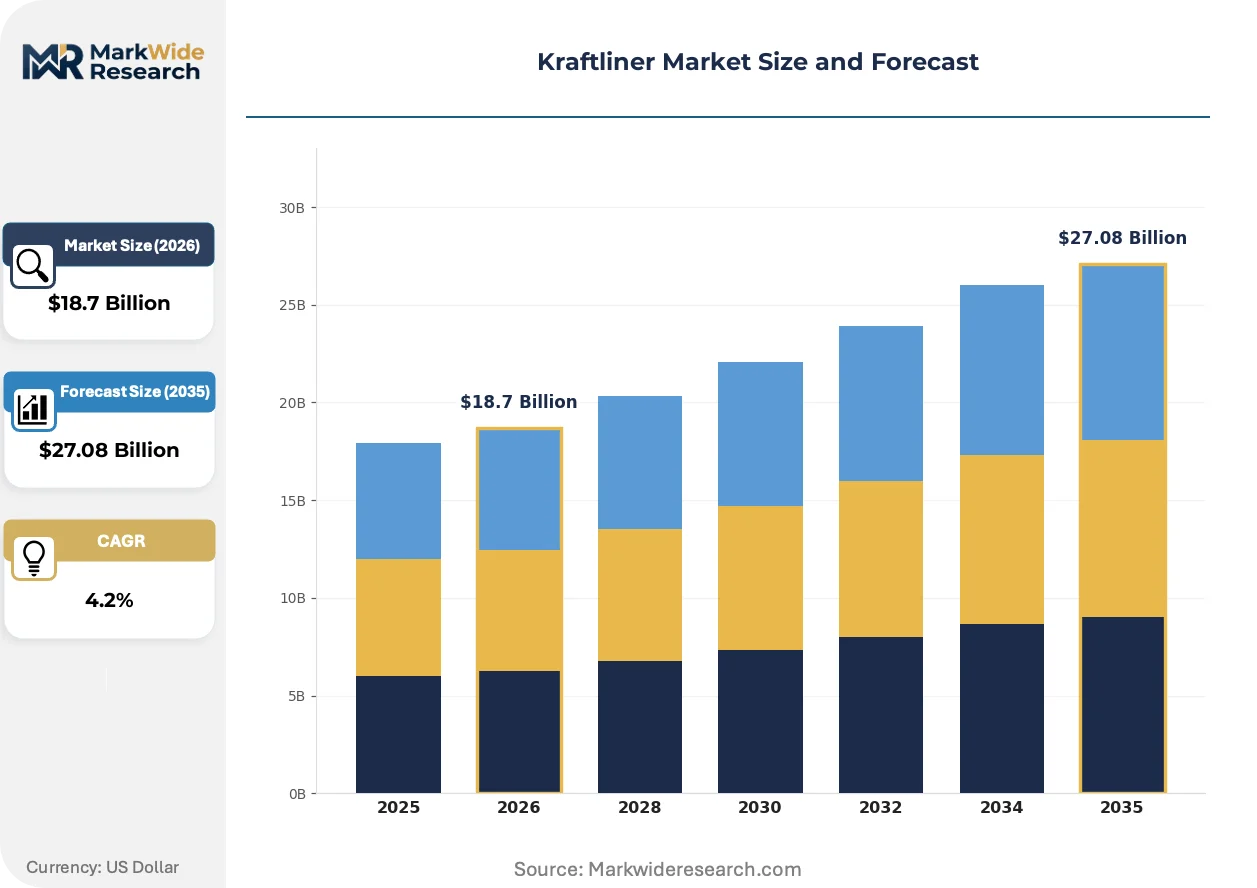
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
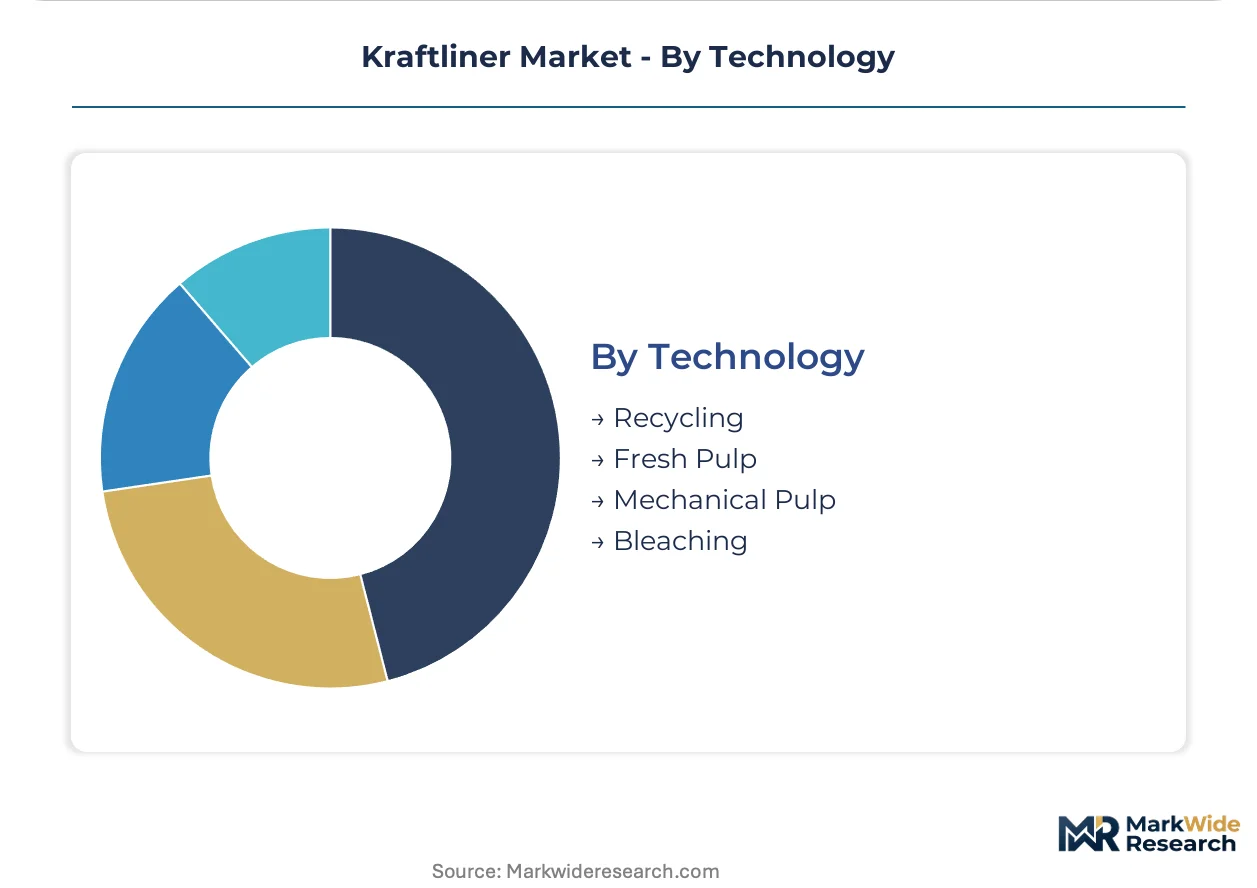
| Segmentation | Product Type: Test Liner, White Top Liner, Coated Kraftliner, Uncoated Kraftliner End User: Packaging Industry, Food & Beverage, Consumer Goods, Electronics Application: Boxes, Bags, Cartons, Pallets Technology: Recycling, Fresh Pulp, Mechanical Pulp, Bleaching |
| Companies Covered | International Paper, Georgia-Pacific, SCA, Mondi, Stora Enso, WestRock, DS Smith, Sappi, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraftliner Market Strategic Shifts & Innovations
Product evolution is focused on embedding functional value directly into the linerboard itself. Kraftliner is transitioning from a passive structural material to an active component in the supply chain, enhanced by specialized coatings and surface treatments that improve performance and traceability.
Functional barrier coatings are a key area of product development. These advanced polymer or bio-based layers are applied to the kraftliner surface to provide resistance to moisture, grease, and oxygen, extending the potential use into direct food contact for a wider range of goods. The food and beverage sector is rapidly adopting these grades for fresh produce and chilled food packaging. This innovation is automating the need for separate plastic bags or wraps inside corrugated boxes, simplifying packaging and reducing waste.
The European Union's Packaging and Packaging Waste Regulation (PPWR) is a significant regulatory driver. Its stringent targets for recyclability and minimum recycled content are compelling producers to re-evaluate their material furnish and product design. This affects white top and coated grades most acutely, as they must now balance aesthetic and print performance with the need to ensure coatings do not hinder the repulping process, pushing investment into new recyclable barrier solutions.
A notable shift in purchasing behavior is the move from specifying material by its basis weight to defining it by performance metrics. Buyers in demanding sectors now issue specifications based on Edge Crush Test (ECT) or Box Compression Test (BCT) values, forcing suppliers to guarantee real-world strength. This disrupts the traditional cost-per-ton procurement model. The trend is most prominent in North American and European supply chains for electronics and automated warehousing systems.
Kraftliner Market Segmentation
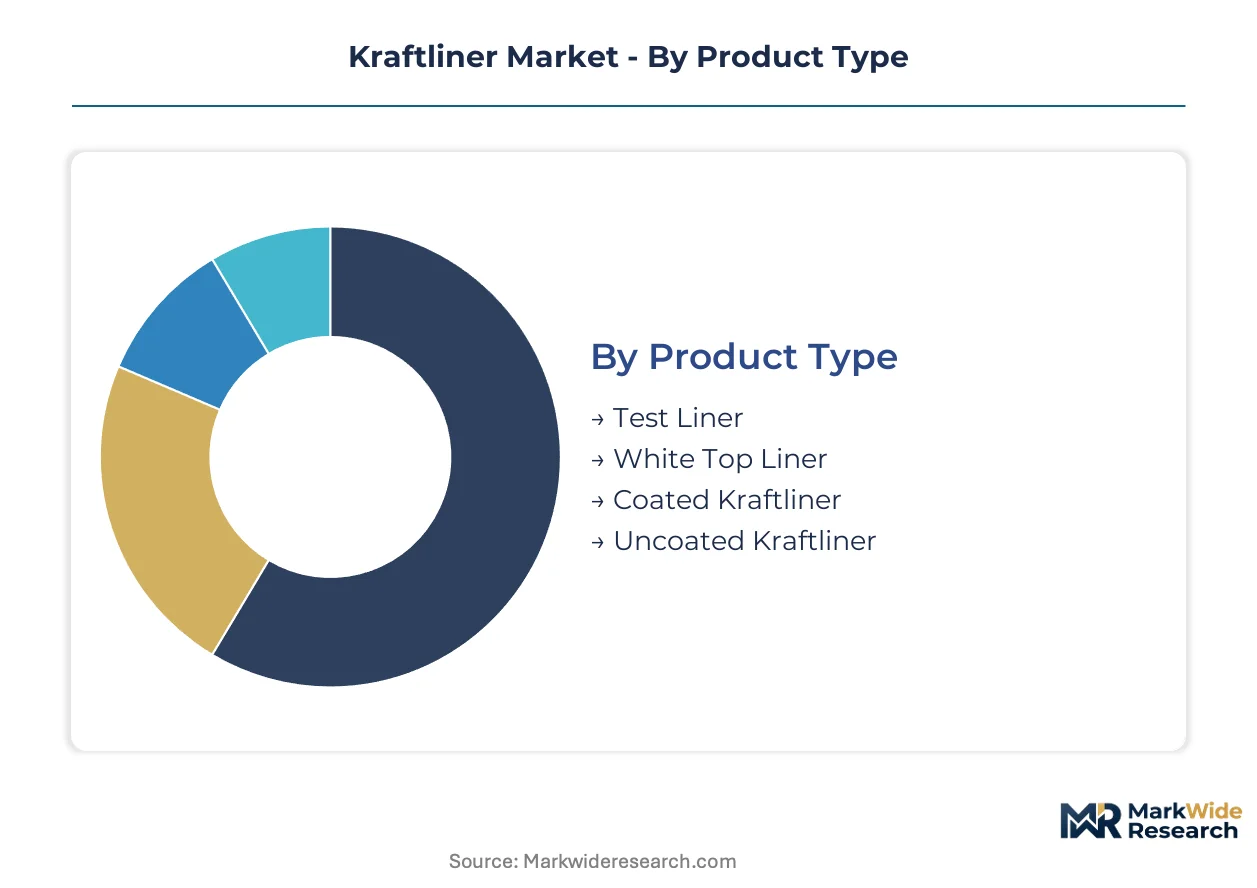
Understanding the Kraftliner market's segmentation reveals how diverse customer needs drive product innovation and material specification. Different industrial applications and end-user requirements dictate specific performance attributes for linerboard. This granular analysis highlights where value is created across the supply chain.
Product Type:
Buyers in the kraftliner market differentiate their procurement based on specific performance requirements, aesthetic needs, and cost considerations for their corrugated packaging solutions.
- Uncoated Kraftliner:
Uncoated kraftliner is a natural brown, strong paperboard made from virgin softwood fibers, offering high burst strength and tear resistance for standard packaging. Demand concentrates in industrial packaging and shipping boxes, driven by its cost-effectiveness and structural integrity for bulk goods transport globally.
- Coated Kraftliner:
Coated kraftliner features a surface layer, often clay-based, applied to virgin fibers, enhancing printability, moisture resistance, and visual appeal for consumer goods. Its adoption is expanding rapidly in food & beverage and electronics packaging, where brand differentiation and product protection are critical for market access.
- White Top Liner:
White top liner consists of a bleached or pigment-coated top layer over a natural kraft base, providing a clean, bright surface for high-quality graphics and branding.
- Test Liner:
Test liner is a recycled fiber-based linerboard, offering a cost-effective and sustainable alternative to virgin kraftliner for less demanding packaging applications.
Volume sits with Uncoated Kraftliner; growth tilts toward Coated Kraftliner.
End User:
The diverse end-user landscape dictates specific functional requirements, from protective packaging for electronics to food-safe materials for consumables.
- Food & Beverage:
The food & beverage sector requires kraftliner grades that meet stringent food-contact safety regulations, often incorporating barrier coatings for moisture or grease resistance. Demand is concentrating in e-commerce grocery and fresh produce packaging, driven by consumer preference for sustainable, single-material solutions over multi-material plastics.
- Electronics:
Electronics manufacturers demand kraftliner with high Box Compression Test (BCT) values and smooth surfaces to protect delicate components during transit and storage. Consumption is significant in North America and Asia-Pacific, propelled by the need for durable, lightweight packaging that can withstand complex logistics chains and automated warehousing.
- Packaging Industry:
The broader packaging industry utilizes kraftliner for a wide array of corrugated solutions, serving diverse sectors beyond direct consumer goods.
- Consumer Goods:
Consumer goods brands leverage kraftliner for its printability and protective qualities, enhancing shelf appeal and product integrity for retail environments.
Specialized requirements for food safety and product protection define the end-user landscape.
Application:
The physical form factor of the final packaging product determines the specific structural and aesthetic properties required from the kraftliner material.
- Boxes:
Kraftliner is predominantly used as the linerboard for corrugated boxes, forming the strong outer and inner layers that provide structural rigidity and stacking strength. This application dominates consumption across all geographies, driven by the universal need for robust shipping containers for manufacturing and retail supply chains.
- Cartons:
Cartons, particularly those for consumer goods, utilize kraftliner with enhanced printability and surface smoothness, often requiring white top or coated grades for branding. Growth in this segment is accelerating in European and North American markets as brands seek sustainable, high-impact packaging solutions for premium products.
- Bags:
Kraftliner-based bags, though less common than boxes, find use in heavy-duty industrial applications requiring high tear resistance and durability.
- Pallets:
Corrugated pallets, a lighter alternative to wood, employ kraftliner for their structural components, reducing shipping weight and improving recyclability.
Efficiency in logistics and brand presentation are key considerations across these applications.
Technology:
The underlying production technology for kraftliner is defined by the source of fiber and the processing methods employed, influencing material properties and environmental footprint.
- Fresh Pulp:
Fresh pulp technology uses virgin softwood fibers, processed via the Kraft pulping method, to produce kraftliner known for its superior strength, consistency, and purity. This technology is central to high-performance kraftliner grades required for demanding applications like heavy-duty industrial packaging and food contact, especially in North America.
- Recycling:
Recycling technology processes post-consumer and post-industrial paper waste into testliner and other recycled fiber-based linerboards, reducing reliance on virgin resources. Its adoption is expanding rapidly, particularly in Europe, driven by stringent regulatory mandates for recycled content and brand owner commitments to circular economy principles.
- Bleaching:
Bleaching technology is applied to fresh pulp to produce white or light-colored kraftliner, essential for white top and coated grades requiring a bright surface.
- Mechanical Pulp:
Mechanical pulp technology produces fibers through physical grinding, resulting in lower strength but higher yield, occasionally blended for specific linerboard properties.
Balancing strength attributes with sustainability goals is a critical factor influencing technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America's extensive virgin softwood forests anchor the global kraftliner supply chain, providing a consistent raw material base for major producers. This region, alongside key manufacturing hubs in Asia and Europe, drives both production and consumption. Evolving regulatory landscapes across these geographies shape market development.
United States
E-commerce expansion for consumer electronics and food items drives substantial demand for durable packaging solutions. The FDA sets rigorous standards for kraftliner used in food-contact applications, influencing material innovation. Major integrated mills in the Southeast, such as those operated by International Paper, focus on high-performance virgin grades.
Germany
The EU Green Deal and its circular economy mandates strongly influence material choices, favoring recyclable fiber-based packaging. Demand for consumer goods packaging requires high-quality coated and white top kraftliner grades. Packaging converters in the Rhine-Ruhr region actively seek sustainable and compliant kraftliner inputs.
China
Rapid industrialization and its role as a global manufacturing and export hub generate immense demand for corrugated boxes. Compliance with GB standards for packaging materials is essential for market access. Industrial clusters in the Pearl River Delta and Yangtze River Delta consume vast quantities of kraftliner for export goods.
Brazil
The burgeoning food and beverage sector, particularly for fresh produce exports, requires specialized kraftliner grades with barrier properties. Environmental regulations concerning sustainable forestry management impact local pulp sourcing and production practices. Pulp and paper operations in the southern states contribute significantly to virgin fiber supply.
India
The expanding e-commerce sector and a growing middle class fuel demand for consumer goods packaging. BIS standards guide material specifications for various packaging applications, ensuring quality and performance. Manufacturing zones around Delhi-NCR and Mumbai see increased consumption for domestic and international distribution.
Kraftliner Market Key Industry Players
Global majors compete with regional champions across fiber sourcing and market reach, defining the competitive dynamics. The kraftliner market exhibits consolidation among large, integrated pulp and paper producers. Strategic archetypes include vertically integrated fiber producers, specialized high-performance packaging providers, and regional commodity suppliers. Dominant competitive moves involve continuous capacity expansion and strategic portfolio diversification into value-added grades.
Within the integrated pulp and paper giant archetype, International Paper exemplifies vast forestry assets and consistent fiber supply for its global operations. WestRock, a US-based corporation, occupies a position as a dominant supplier of high-performance grades for demanding packaging applications, particularly for e-commerce. Stora Enso, a Finnish-Swedish company, sits within the specialized renewable packaging solutions segment, primarily serving European markets with its innovative fiber-based materials that align with circular economy principles.
| Leading Market Players |
|---|
| International Paper |
| Georgia-Pacific |
| SCA |
| Mondi |
| Stora Enso |
| WestRock |
| DS Smith |
| Sappi |
| Smurfit Kappa |
| Others |
Cost & Logistics Intelligence
Vertical integration into forestry assets anchors the global kraftliner supply position, enabling consistent fiber access and influencing pricing power for major producers. This structure mitigates raw material volatility and supports stable market dynamics.
Pricing Analysis
Unbundled value-added services, such as specialized coatings or just-in-time delivery, supplement the core product price for kraftliner. The dominant pricing model combines long-term contract-based offtake agreements for base grades with commodity spot pricing for marginal volumes. Price differentiation stems from specific performance attributes like Box Compression Test (BCT) values, food-contact certifications (FDA, EFSA), and regional logistics costs. Pricing softness reflects intense competition from recycled grades in cost-sensitive industrial packaging segments. Buyers in high-performance electronics packaging exhibit lower price sensitivity due to critical protection requirements.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns facilitate efficient delivery of kraftliner rolls to corrugated converters across major industrial zones. Virgin kraftliner supply concentrates in the United States and Brazil, drawing heavily from extensive softwood fiber resources. The supply chain relies on consistent availability of virgin softwood pulp, making it vulnerable to commodity price volatility driven by energy costs. Downstream distribution typically involves direct sales to large packaging manufacturers, with smaller volumes routed through specialized paper merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kraftliner market remains a supply-constrained story, where the high capital intensity and long lead times for new integrated mill construction create a significant capacity bottleneck. This structural limitation helps sustain pricing power for established producers.
For Market Incumbents: Cement long-term customer relationships through joint product development for specialized food-contact grades. Invest in advanced barrier coating technologies to counter the threat from less sustainable plastic packaging. Expand integrated forestry assets in North America to secure consistent virgin fiber supply amidst global demand. Diversify product portfolios to include lightweighting solutions that address customer cost pressures.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for innovative fiber-based barrier solutions that meet stringent recyclability mandates. Target the rapidly expanding e-commerce food and beverage packaging segment with white top liner grades compatible with digital printing. Focus on Southeast Asian manufacturing hubs, offering compliant materials for export-oriented goods. A go-to-market strategy emphasizing sustainable material certification can differentiate offerings.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated pulp and paper mills with strong fiber supply and established market channels. Long-term viability for this market over the next decade is strong, driven by sustained e-commerce growth and plastics substitution. Target mid-sized specialty producers with proprietary coating technologies or unique food-contact grade capabilities. The signal to watch is the rate of new capacity additions for high-performance recycled liner grades.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Virgin Kraftliner | Addresses rising global demand for durable packaging and leverages abundant softwood fiber resources in North America. |
| Investment in Barrier Coating R&D | Enables kraftliner to displace plastic in food and beverage applications, meeting evolving consumer and regulatory demands. |
| Acquisition of Digital Printing Specialists | Enhances white top liner appeal for consumer goods brands seeking personalized and high-impact packaging solutions. |
| Geographic Diversification into Southeast Asia | Captures growth from rapid industrialization and export-oriented manufacturing in countries like Vietnam and Indonesia. |
| Compliance with EU PPWR Standards | Ensures market access and strengthens brand reputation in European markets prioritizing circular economy principles. |
Research Approach
Document review covered SEC filings, industry association reports (e.g., AF&PA, CEPI), and customs trade data, complemented by interviews with pulp mill managers, packaging converters, brand procurement leads, and logistics specialists. This approach combined primary insights with secondary validation. Bottom-up data collection from production capacities was triangulated with top-down market sizing based on end-use consumption.
The quantitative model produced volume and value forecasts across the analysis window, segmented by product type, end-user industry, application, and processing technology. Compound Annual Growth Rates (CAGRs) were derived from historical data analysis and projected demand drivers. Key industry-specific forecast inputs included e-commerce growth projections and regulatory shifts impacting plastics substitution.
Caveats apply where significant macroeconomic downturns or unforeseen technological breakthroughs in alternative materials could materially shift the outlook. Forecasts reflect assumptions regarding stable raw material supply and consistent regulatory enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Postal Papers Market