
 Egg Cartons Market | 2026-2036
Egg Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Cartons Market Intelligence
Margin capture from high-volume, standard carton production is tilting toward customized, sustainable packaging solutions for premium egg brands. Huhtamaki Oyj leverages its global manufacturing footprint to serve large-scale egg producers with consistent quality. Smurfit Kappa Group plc differentiates through its integrated paper and packaging model, ensuring raw material security. Meanwhile, Brodrene Hartmann AS specializes in molded fiber technology, leading innovation in recyclable and compostable cartons.
Egg cartons are protective packaging containers designed to cushion eggs during transport and storage, preventing breakage. They are commonly manufactured from molded fiber pulp or plastics like polystyrene, engineered with individual cells to cradle each egg. Molded fiber remains the dominant material type due to its recyclability, while demand for biodegradable plastics is rising. Among capacity segments, the 12-egg format holds the largest share, but larger formats like 18-egg and 24-egg cartons are gaining traction in wholesale channels.
Regulations governing food-contact materials, such as those from the US FDA and the European Food Safety Authority (EFSA), dictate material safety and composition. Additionally, extended producer responsibility schemes and single-use plastic directives in Europe and China's State Administration for Market Regulation (SAMR) policies are accelerating the shift to fiber-based materials. Stakeholder success will depend on navigating material science innovations against a backdrop of evolving circular economy regulations.
Market Dynamics
The central dynamic in the egg carton market is the material science transition compelled by circular economy principles. This shift is moving the industry's value proposition from purely functional protection to encompassing end-of-life responsibility and sustainable sourcing.
Growth Catalysts
- Regulatory Mandates:Policies like the European Union's Single-Use Plastics Directive directly penalize plastic packaging, creating a powerful incentive for retailers and egg producers to switch to molded fiber or other biodegradable alternatives.
- Premiumization of Egg Products:Consumer demand for organic, free-range, and pasture-raised eggs supports the use of customized, higher-cost sustainable packaging that reinforces the product's premium positioning on retail shelves.
- Retail Infrastructure Expansion:The rapid build-out of modern supermarkets and hypermarkets in countries like China and India increases the need for standardized, shelf-ready egg packaging, replacing loose-egg sales formats.
Market Restraints
- Raw Material Volatility:The price and availability of recycled paper pulp, the primary input for molded fiber cartons, are subject to significant fluctuations based on global collection rates and demand from other paper-based industries.
- Performance Gaps:Polystyrene offers superior moisture barrier properties and structural rigidity, which remains a critical performance advantage over some fiber-based options in humid climates or long, complex cold chains.
- Substitution from Bulk Formats:In food service and institutional channels, the use of large, reusable plastic trays and crates for egg distribution can eliminate the need for individual consumer-grade cartons, representing a form of substitution.
Strategic Opportunities
- Smart Packaging Integration:Incorporating technologies like QR codes for traceability or time-temperature indicators onto cartons offers a value-added service for brands focused on food safety, transparency, and consumer engagement.
- Geographic Expansion:Markets in Southeast Asia and Latin America with growing middle-class populations and formalizing retail sectors represent significant untapped volume for standardized egg carton producers.
- Molded Fiber Diversification:Manufacturers can leverage their expertise and equipment in molded fiber to produce protective packaging for other delicate, high-value items, such as avocados, light bulbs, or medical vials.
Industry Challenges
- Capital Investment Cycles:Shifting production from polystyrene to molded fiber requires significant capital expenditure for new molding machinery and drying systems, posing a barrier for smaller, undercapitalized manufacturers.
- Navigating Food-Contact Laws:Ensuring that new bio-based plastics or recycled fiber materials comply with the distinct food-contact regulations of bodies like the US FDA and EFSA is a complex and time-consuming process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Cartons Market |
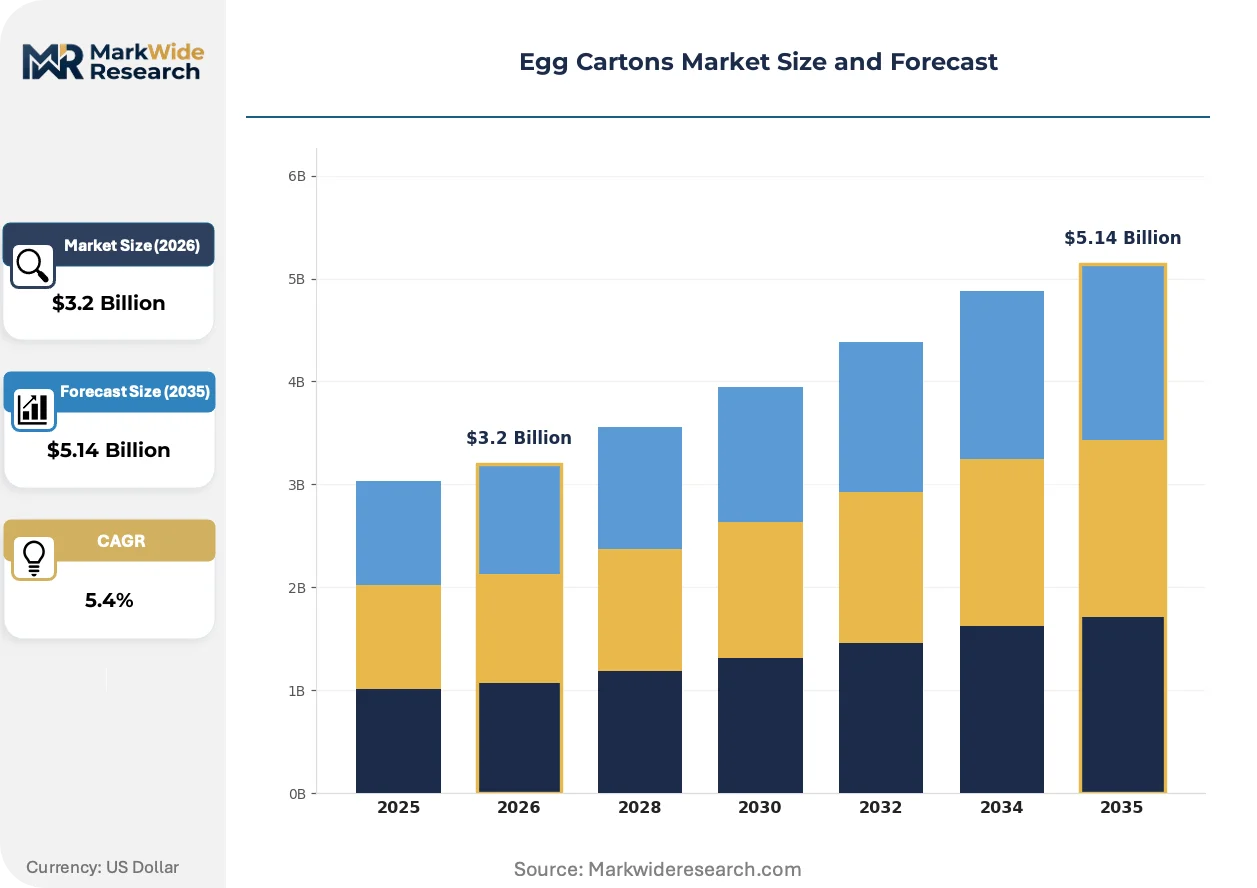
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
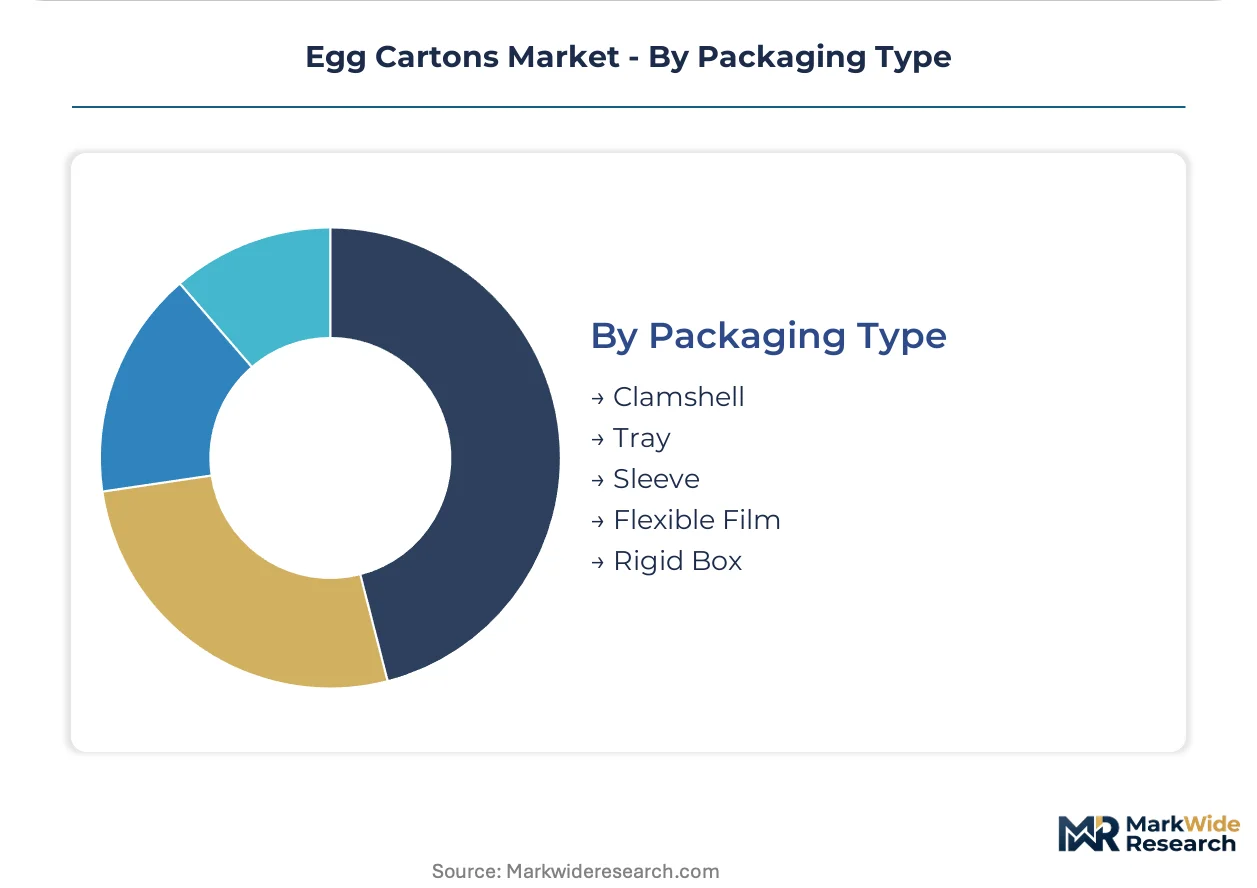
| Segmentation | Material Type: Paper Pulp, Polystyrene Foam, Polyethylene, Molded Fiber, Biodegradable Plastics Capacity: 6 Eggs, 12 Eggs, 18 Eggs, 24 Eggs, 30 Eggs End User: Retail Stores, Foodservice Providers, Wholesale Distributors, Egg Producers Packaging Type: Clamshell, Tray, Sleeve, Flexible Film, Rigid Box |
| Companies Covered | Brodrene Hartmann AS, Huhtamaki Oyj, Cascades Inc., Tekni-Plex, Pactiv Evergreen, Smurfit Kappa Group plc, DS Smith Plc, Mondi plc, DFM Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Cartons Market Strategic Shifts & Innovations
Material science innovation, driven by the dual pressures of regulation and consumer ethics, is the primary theme. The market is evolving from a focus on breakage prevention to a more holistic view that incorporates material origin, recyclability, and compostability into the product design.
Molded fiber technology provides a cushioned, porous structure for egg protection. Premium egg producers and large retailers with corporate sustainability goals are rapidly adopting advanced fiber-based designs. Consequently, the market's core material preference is migrating from conventional plastics like polystyrene toward recycled paper pulp and other compostable fiber solutions.
European regulations, including the Single-Use Plastics Directive and various national Extended Producer Responsibility (EPR) schemes, are fundamentally altering packaging economics. These policies assign the financial burden of post-consumer waste management directly to producers, creating a strong incentive to design for recyclability. The high-volume food packaging segment is most affected, spurring investment in fiber-based material sourcing and recycling infrastructure across the continent.
A notable shift in consumer behavior involves the active scrutiny of on-pack sustainability claims and material sourcing information. This preference for transparently eco-friendly products is disrupting traditional procurement models that prioritized cost above all else, turning packaging into a brand differentiator. This trend is most visible in North American and Western European grocery markets, where private-label brands often use sustainable cartons to signal quality.
Egg Cartons Market Segmentation

Segmentation of the egg cartons market reveals how material choices, capacity formats, and end-user demands shape product development. Understanding these distinct segments helps manufacturers align their offerings with specific market needs. This analysis highlights critical differentiators influencing purchasing decisions across the supply chain.
Material Type:
The material type segment demonstrates varying cycle times, with traditional options offering stability while innovative materials experience rapid shifts. Molded fiber and biodegradable plastics are seeing accelerated adoption due to sustainability pressures.
- Molded Fiber:This material provides a cushioned, porous structure essential for egg protection and ventilation. Demand for molded fiber cartons concentrates in North America and Western Europe, driven by corporate sustainability goals and consumer preference for eco-friendly packaging.
- Biodegradable Plastics:These plastics are derived from plant-based sources or petroleum, engineered to decompose naturally in specific environments. Demand for biodegradable plastic egg cartons is concentrating in Europe, spurred by the European Union's Single-Use Plastics Directive and evolving consumer ethics.
- Paper Pulp:Recycled paper pulp serves as the fundamental raw material for many fiber-based egg cartons, valued for its recyclability.
- Polystyrene Foam:This lightweight, insulating plastic offers superior moisture barrier properties and structural rigidity, particularly advantageous in humid climates.
- Polyethylene:Polyethylene is utilized in certain specialized or reusable egg packaging applications, providing durability and moisture resistance.
Paper Pulp anchors the volume base while Biodegradable Plastics gains share at the steepest rate.
Capacity:
The capacity segment reflects the diverse volume requirements of consumers and commercial entities, dictating packaging dimensions and material usage. Different formats cater to distinct purchasing behaviors.
- 12 Eggs:This capacity format holds the largest share, serving as the standard consumer purchase size that balances convenience and household consumption. Demand concentrates in retail stores across the United States and Germany, where it dominates shelf space for everyday egg sales.
- 18 Eggs:This larger capacity format caters to households with higher consumption or smaller families seeking increased value. Demand is gaining traction in supermarket chains in Canada and the United Kingdom, reflecting evolving consumer purchasing habits.
- 6 Eggs:Smaller 6-egg cartons target single-person households or specialty and premium egg products.
- 24 Eggs:These cartons primarily serve wholesale clubs and larger family formats, offering bulk value to consumers.
- 30 Eggs:The 30-egg tray format is typical for foodservice providers and institutional buyers, prioritizing bulk handling.
The diversity in capacity formats reflects varied consumer purchasing patterns and distribution channel requirements.
End User:
The end-user segment highlights how different customer types necessitate specific packaging attributes, from consumer-facing aesthetics to bulk handling functionality. Each channel has unique demands for egg cartons.
- Retail Stores:These entities represent the primary channel for direct consumer sales, requiring shelf-ready and aesthetically appealing packaging. Demand is particularly high in modern supermarket chains in China and India, driven by expanding infrastructure and consumer preference for packaged goods.
- Wholesale Distributors:These intermediaries manage bulk volumes and supply to various smaller businesses, requiring durable and stackable cartons for efficient logistics. Demand for wholesale distribution packaging is robust in urban centers across Brazil and Indonesia, supporting local markets and smaller retailers.
- Foodservice Providers:Restaurants, hotels, and cafeterias utilize bulk egg packaging designed for efficiency in commercial kitchens and high-volume use.
- Egg Producers:Producers often use specialized cartons for internal handling, grading, and direct-to-consumer sales channels.
Each end-user segment presents distinct requirements for carton design, durability, and logistical efficiency.
Packaging Type:
The packaging type segment showcases how different structural designs serve distinct applications, from direct consumer display to bulk logistical efficiency. Each type offers specific advantages for egg protection and presentation.
- Clamshell:This hinged, one-piece container securely encloses eggs, widely used for consumer-facing retail packaging due to its robust protection and display capabilities. Demand is strong in North American and European grocery markets, where it supports brand differentiation for premium egg products.
- Tray:Open-top trays, often made of molded fiber, are primarily designed for bulk transport and internal handling within the egg supply chain. Demand is particularly high in Asian markets like Japan and South Korea for efficient logistics and secondary packaging.
- Sleeve:Paperboard sleeves are used to bundle multiple cartons or provide branding over basic egg trays, enhancing shelf appeal.
- Flexible Film:This lightweight packaging type is sometimes used for small egg packs or specialty applications, offering product visibility.
- Rigid Box:Sturdy rigid boxes are employed for high-end or specialty egg packaging, offering premium presentation and enhanced protection.
The choice of packaging type hinges on the desired level of protection, branding, and channel-specific handling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The egg carton market's manufacturing capacity is shifting in response to material science innovations and regulatory mandates. Production concentration is moving towards regions with advanced fiber-based material supply chains. This transition supports the global demand for sustainable packaging solutions, impacting regional supply dynamics.
United States
United States demand for egg cartons stems from premiumization of organic and free-range egg products. US FDA regulations dictate material safety and composition for all food-contact packaging. Manufacturers in California's agricultural regions are increasingly investing in molded fiber technologies for local producers.
Germany
Germany's market for egg cartons is shaped by strong consumer preference for sustainable options and corporate sustainability goals. The EU Single-Use Plastics Directive directly penalizes plastic packaging, creating powerful incentives for fiber-based alternatives. Packaging manufacturers in Bavaria are leading innovation in recyclable and compostable carton designs.
China
China exhibits significant demand for standardized egg packaging due to expanding supermarket infrastructure and increasing consumer protein intake. SAMR policies accelerate the transition towards fiber-based materials across the packaging sector. The Yangtze River Delta region is experiencing rapid build-out of modern egg carton manufacturing facilities to meet this demand.
Brazil
Brazil's market is expanding with a growing middle-class population and formalizing retail sectors. ANVISA regulations for food-contact materials influence the adoption of new, compliant packaging solutions. Urban centers in São Paulo demonstrate robust demand for durable and stackable cartons for efficient logistics across various retail formats.
Egg Cartons Market Key Industry Players
Global packaging conglomerates and specialized molded fiber innovators split the egg cartons market. Large-scale players leverage extensive manufacturing footprints to serve high-volume producers with consistent quality. Smaller, agile firms differentiate through material science innovation and sustainable product development for premium brands. Competitive moves include significant capital expenditure for new production lines and strategic partnerships to secure sustainable raw material supply.
At the scale-driven end, Huhtamaki Oyj and Smurfit Kappa Group plc exemplify vertically integrated packaging solutions providers. Huhtamaki, a Finnish company, leverages its global manufacturing footprint to serve large-scale egg producers with consistent quality. Smurfit Kappa, an Irish-based Group plc, differentiates through its integrated paper and packaging model, ensuring raw material security and supply chain stability. Brodrene Hartmann AS, a Danish company, represents the specialized segment, focusing on molded fiber technology and leading innovation in recyclable and compostable cartons for premium markets. These players collectively anchor the market's strategic direction.
| Leading Market Players |
|---|
| Brodrene Hartmann AS |
| Huhtamaki Oyj |
| Cascades Inc. |
| Tekni-Plex |
| Pactiv Evergreen |
| Smurfit Kappa Group plc |
| DS Smith Plc |
| Mondi plc |
| DFM Packaging |
| Others |
Cost & Logistics Intelligence
Recycled paper pulp availability and cost volatility significantly influence downstream carton pricing, impacting profit margins for both manufacturers and retailers. This material concentration dictates the overall economic structure.
Pricing Analysis
The European Union's Single-Use Plastics Directive dictates the pricing tier structure, favoring fiber-based solutions. Pricing stratifies across premium, standard, and economy tiers, driven by material choice and customization levels. Cost compression intensifies for conventional plastic options due to regulatory pressure. Retail stores purchasing high-volume, standard cartons exhibit high price sensitivity, while premium egg brands prioritize sustainable packaging.
Supply Chain Analysis
Huhtamaki Oyj and Smurfit Kappa Group plc, as large-scale manufacturers, concentrate significant egg carton production capacity globally. Supply draws from China, Europe, and North America for both finished goods and raw materials. Recycled paper pulp and various plastics represent key input dependencies. Commodity price volatility for pulp introduces a structural risk. Distribution runs through wholesale distributors to various retail and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The egg carton market presents a significant opportunity for players who can bridge the gap in advanced material science capabilities. Expertise in developing and scaling fiber-based solutions remains a critical asset scarcity.
For Market Incumbents: Pre-empt market share erosion by accelerating capital expenditure into molded fiber production lines, particularly in regions with stringent single-use plastic directives. Secure long-term contracts for recycled paper pulp to mitigate raw material volatility, which threatens profitability for standard carton production. Huhtamaki and Smurfit Kappa can leverage global footprints to offer consistent quality against emerging sustainable packaging threats.
For New Entrants and Emerging Players: Build out specialized molded fiber production capabilities to target premium egg producers seeking custom, sustainable packaging solutions. Penetrate emerging markets in Southeast Asia by offering standardized, shelf-ready cartons that meet expanding retail infrastructure needs. Differentiate through material science innovations, such as advanced bio-based plastics, and integrate smart packaging features for enhanced consumer engagement.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized molded fiber technology firms and bio-plastic innovators that possess strong intellectual property in sustainable packaging. The long-term viability of this market, spanning the next decade, centers on the accelerating transition to circular economy principles. A key signal to watch is the expansion of single-use plastic directives into new high-volume markets, indicating future growth areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Molded Fiber Capacity | Huhtamaki and Smurfit Kappa can strengthen their position against plastic packaging with new production lines. |
| Secure Recycled Pulp Supply | Mitigates raw material volatility, ensuring stable production costs for fiber-based egg carton manufacturers. |
| Develop Bio-based Plastic Solutions | Brodrene Hartmann and other innovators can address regulatory mandates and consumer demand for sustainable alternatives. |
| Expand into Asian Retail Markets | Captures demand from China's and India's expanding supermarket infrastructure and protein consumption. |
| Integrate Smart Packaging Features | Enhances brand differentiation and consumer engagement for premium egg products through traceability and transparency. |
Research Approach
Operator-level perspectives from packaging engineers, procurement managers, and sustainability officers anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary research, including US FDA regulations, EFSA guidelines, and China SAMR policies. This approach combined bottom-up market insights with top-down validation from industry reports and company filings.
Scenario-based modeling, bracketing high and low growth possibilities, informed the market forecasts over the projection horizon. The analytical framework integrated historical data with expert judgment across material type, capacity, end-user, packaging type, and regional regulatory stringency. Compound Annual Growth Rates were derived from projected growth drivers and market penetration rates. Forecast inputs included recycled paper pulp pricing trends and new supermarket infrastructure build-out rates.
Stress conditions across raw material availability, regulatory enforcement timelines, and consumer preference shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, but unforeseen geopolitical events or rapid technological disruption could revise projections. Quarterly review of regulatory updates and key material input costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Ready Meals Packaging Market
Food Packaging
Bamboo Plate Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
North America Food Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Seafood Packaging Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Chilled Food Packaging Market