
 Paperboard Mailer Market | 2026-2036
Paperboard Mailer Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Mailer Market Analytics
Fragmentation among direct-to-consumer brands is repositioning procurement patterns across the paperboard mailer supply chain. WestRock Company leverages its integrated containerboard mills to control fiber sourcing for mailer substrates. Mondi Group anchors European supply through kraft paper specialization in Central European mills. Smurfit Kappa competes on corrugated-adjacent rigid formats that bridge parcel and letter post categories.
Paperboard mailers are fiber-based envelopes and sleeves engineered from 200–400 gsm solid bleached or unbleached sulfate board, often scored for fold integrity and sealed with hot-melt or self-adhesive closures; they function as lightweight, printable alternatives to polybags for documents, apparel, and flat goods. Rigid mailers dominate premium electronics and document segments where bend resistance commands price premiums. Padded mailers incorporating recycled fiber cushioning are gaining fastest in subscription box fulfillment where unboxing experience drives repeat purchase rates. Kraft paper grades sustain margin pools in bulk shipping company contracts where brown-field aesthetics signal sustainability claims.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that reshape material grade sourcing across European converters. The US EPA guides state-level extended producer responsibility frameworks that affect mailer recyclability labeling and end-of-life collection infrastructure. Stakeholders must monitor how divergent regional compliance timelines fragment mold and die specifications for multi-market production runs.
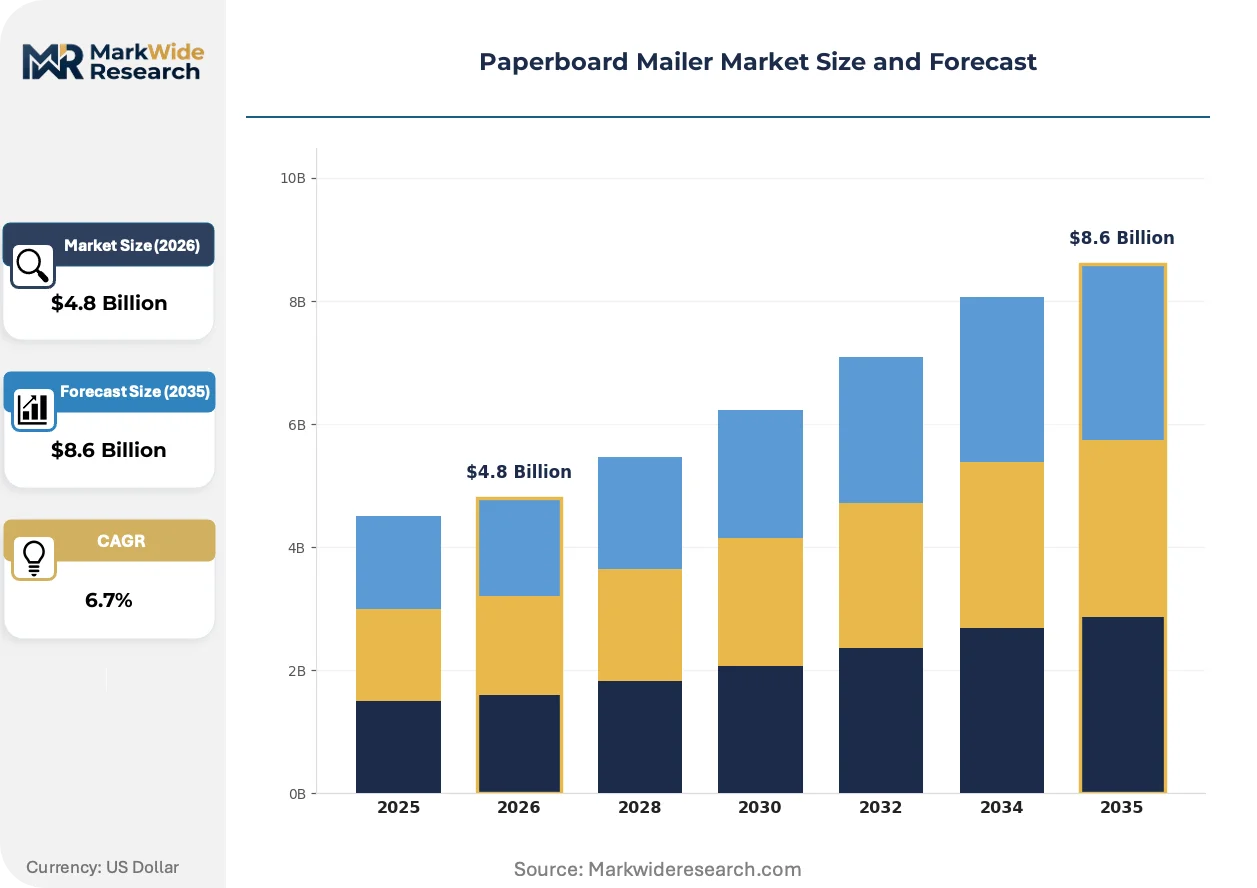
Market Dynamics
E-commerce fulfillment networks are compressing packaging specifications toward lighter, fiber-based alternatives that satisfy dimensional weight pricing while meeting tightening recycled content mandates from Brussels to Sacramento.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled fiber thresholds are redirecting converter procurement toward post-consumer kraft sources across German, French, and Polish mill networks.
- Subscription box fulfillment:Unboxing experience requirements from direct-to-consumer apparel brands are accelerating padded mailer specifications with printed interior surfaces.
- Rigid mailer formats:Document and electronics segments command bend-resistance premiums that sustain margin pools unavailable in standard corrugated alternatives.
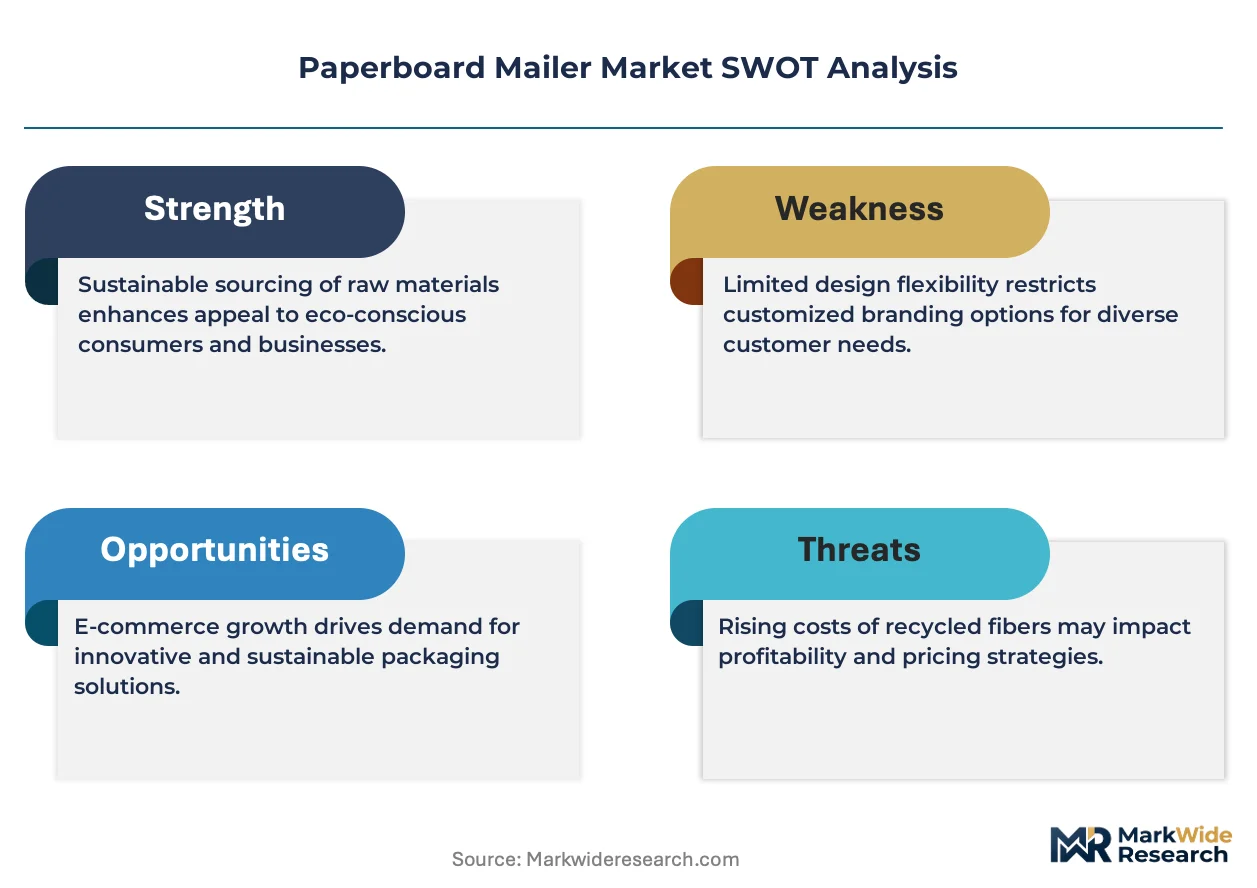
Market Restraints
- OCC price volatility:Old corrugated container input costs swing with Chinese import quota policies, squeezing converter margins on fixed-price annual contracts.
- Polybag substitution resilience:Lightweight polyethylene mailers retain cost advantages below 8-ounce shipment thresholds, particularly in humid climates where fiberboard strength degrades.
- Mold specification fragmentation:Divergent EU and US recyclability labeling requirements force redundant die investments for multi-market production runs.
Strategic Opportunities
- Indian e-commerce corridors:Domestic platform fulfillment centers in Bangalore and Mumbai remain underpenetrated by rigid mailer formats optimized for electronics returns.
- Digital print integration:Hybrid inkjet systems enable variable-data exterior branding that transforms mailers into mobile advertising surfaces for seasonal campaigns.
- Extended producer responsibility frameworks:State-level US EPA guidance on mailer recyclability labeling creates first-mover advantages for converters with certified fiber chain-of-custody documentation.
Industry Challenges
- Hot-melt adhesive qualification:Repulpability testing protocols vary between German and Nordic paper mills, delaying product approvals for cross-border suppliers.
- Score-to-fold precision:Automated fulfillment lines demand tighter dimensional tolerances than legacy converting equipment achieves without capital-intensive press retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Mailer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Mailers, Padded Mailers, Flat Mailers, Custom Shapes Material Grade: Recycled Paper, Virgin Fiber, Coated Paper, Kraft Paper End User: E-commerce, Retail, Shipping Companies, Subscription Boxes Distribution Channel: Online Sales, Retail Stores, Distributors, Direct Sales |
| Companies Covered | WestRock Company, International Paper Company, Georgia-Pacific LLC, Sealed Air Corporation, Pregis LLC, Mondi Group, DS Smith Plc, Packaging Corporation of America, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Mailer Market Evolving Landscape
Material science advances and regulatory sequencing are compressing format innovation cycles, with fiber-based cushioning systems and digital print integration emerging as primary vectors of competitive differentiation.
Water-based barrier coatings are overtaking polyethylene laminates in moisture-sensitive applications. Food-grade wax emulsions and silicate treatments now achieve comparable vapor transmission rates without compromising repulpability. Electronics fulfillment networks in the Netherlands and California are specifying these coatings for coastal distribution hubs where humidity exposure previously mandated plastic films. The structural consequence is a compression in poly-laminated mailer volumes that previously dominated premium segments.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-grease-resistance treatments that long protected documents during transit. The European Chemicals Agency enforcement timeline is forcing converters to qualify alternative fluorine-free chemistries by 2026. German mailer producers are accelerating pilot programs with bio-based sizing agents derived from agricultural residues, though performance gaps persist in high-temperature transport corridors.
Consolidated buying desks at major e-commerce platforms are compressing supplier rosters and demanding outcome-based performance guarantees rather than unit-price contracts. Tier-one fulfillment operators now specify damage-rate thresholds and recyclability certification as contract conditions. This pattern concentrates procurement volume with converters capable of integrated design-to-die production in Poland, the Czech Republic, and Ohio.
Paperboard Mailer Market Segmentation
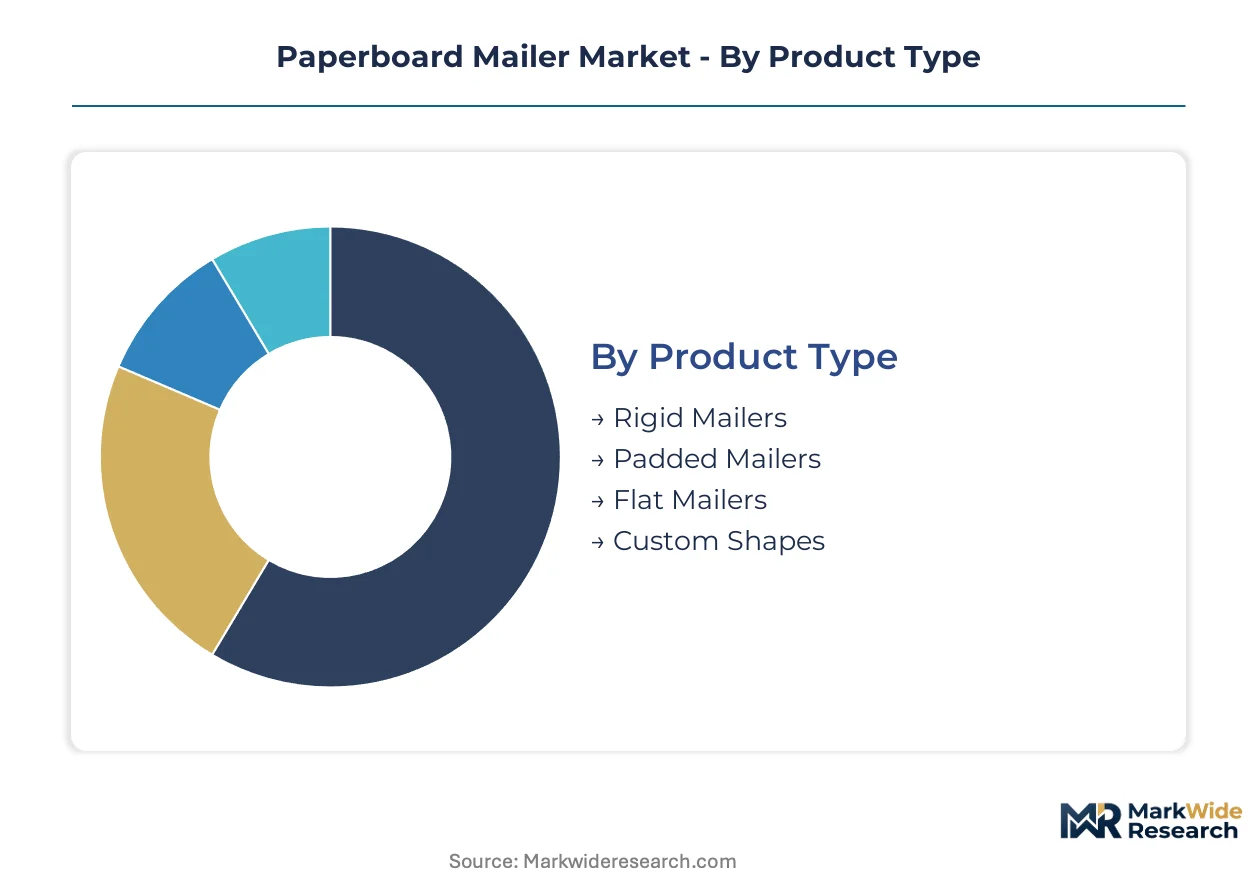
Format selection in paperboard mailers determines fulfillment economics, damage tolerance, and brand presentation simultaneously. Procurement teams weight dimensional weight pricing against unboxing experience requirements across e-commerce corridors. Material grade choices cascade through converter margins, regulatory compliance thresholds, and end-of-life collection infrastructure.
Product Type:
Buyers select formats based on bend resistance needs and premium positioning against polybag alternatives.
- Rigid Mailers:Constructed from 300–400 gsm solid bleached sulfate board with scored fold lines and stay-flat properties. Document and electronics fulfillment networks in Germany specify these for high-value shipments where dimensional stability commands price premiums above standard fiber alternatives.
- Padded Mailers:Integrate corrugated fiber cushioning or recycled pulp padding between kraft paper outer layers. Subscription box operators in California and the Netherlands are specifying printed interior surfaces where unboxing experience drives repeat purchase rates.
- Flat Mailers:Single-ply 200–250 gsm constructions for documents and apparel where minimal weight satisfies postal rate thresholds. Retail pharmacy chains utilize these for prescription delivery programs.
- Custom Shapes:Die-cut configurations for irregular product geometries including books, framed prints, and promotional kits. Marketing fulfillment agencies specify these for seasonal campaign materials requiring unique silhouette recognition.
Volume sits with rigid formats in established corridors; growth tilts toward padded specifications in direct-to-consumer apparel.
Material Grade:
Converter procurement tracks OCC price volatility against EU Packaging and Packaging Waste Regulation recycled content floors.
- Recycled Paper:Post-consumer fiber streams from municipal collection systems, typically 80–100 gsm kraft grades. German and Polish mill networks are expanding de-inking capacity to meet Brussels-mandated thresholds.
- Virgin Fiber:Fresh sulfate pulp delivering superior print surface and structural consistency. Premium electronics brands specify these for exterior branding where color fidelity matters.
- Coated Paper:Clay or polymer surface treatments for high-resolution photographic reproduction. Luxury cosmetics direct-to-consumer channels utilize coated exteriors for campaign-specific imagery.
- Kraft Paper:Unbleached natural fiber delivering brown-field sustainability signaling. Bulk shipping contracts with logistics aggregators concentrate procurement here for cost positioning.
Margin pools concentrate in virgin fiber for premium positioning; regulatory pressure accelerates recycled grade expansion.
End User:
Application-specific damage tolerances and branding requirements fragment procurement specifications across buyer categories.
- E-commerce:Platform fulfillment centers specifying damage-rate thresholds and dimensional weight optimization. Amazon and Zalando buying desks demand certified fiber chain-of-custody documentation.
- Retail:In-store pickup and ship-from-store operations requiring inventory-compatible formats. Apparel chains with omnichannel fulfillment utilize rigid mailers for premium positioning.
- Shipping Companies:Postal operators and parcel aggregators procuring at volume scale with standardized specifications. Deutsche Post and DHL contracts emphasize kraft paper grades for cost efficiency.
- Subscription Boxes:Curated product delivery services prioritizing interior print surfaces and opening ceremony design. Beauty and wellness brands drive padded mailer specifications here.
Procurement volume concentrates with e-commerce platforms; subscription services expand specification diversity fastest.
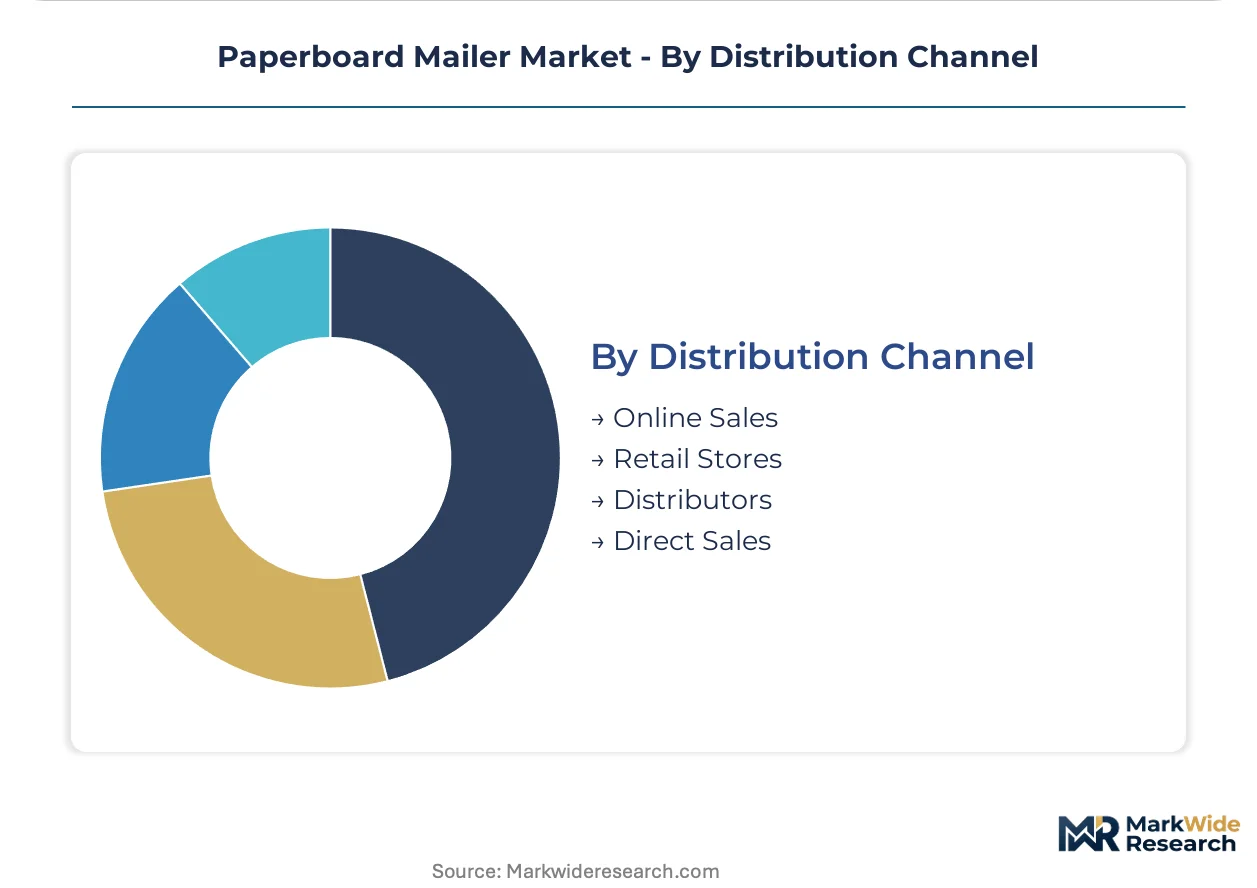
Distribution Channel:
Channel selection reflects order scale, customization requirements, and converter technical support needs.
- Online Sales:Digital procurement platforms enabling specification comparison and rapid sampling. Mid-market direct-to-consumer brands utilize these for smaller production runs with variable print.
- Retail Stores:Big-box office supply and packaging specialty chains for immediate availability. Small business shippers purchase rigid formats here for document protection.
- Distributors:Industrial packaging intermediaries consolidating multi-converter portfolios. Third-party logistics providers source through distributors for multi-site fulfillment networks.
- Direct Sales:Converter account teams engaging enterprise buyers with design-to-die integration. Tier-one e-commerce platforms negotiate direct for outcome-based performance guarantees.
Enterprise volume flows through direct relationships; online channels capture long-tail fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform fulfillment networks concentrate procurement volume in corridors where dimensional weight pricing and recycled content mandates intersect most aggressively. The analysis tracks five national markets where converter capacity, regulatory sequencing, and e-commerce infrastructure density create distinct competitive environments.
Germany
Deutsche Post and DHL contracts anchor European demand for kraft paper grades in bulk shipping applications. The EU Packaging and Packaging Waste Regulation mandates minimum recycled fiber thresholds that redirect converter procurement toward post-consumer sources. Mill networks in North Rhine-Westphalia and Bavaria expand de-inking capacity to serve cross-border online retail corridors.
United States
Amazon and Walmart fulfillment centers specify damage-rate thresholds and certified fiber chain-of-custody documentation in supplier contracts. EPA guidance on extended producer responsibility frameworks affects mailer recyclability labeling requirements state by state. Converting clusters in Ohio and the Pacific Northwest integrate hybrid inkjet systems for variable-data exterior branding.
China
Domestic platform operators Alibaba and JD.com compress packaging specifications toward lighter fiber-based alternatives for last-mile efficiency. SAMR standards on packaging waste reduction create compliance timelines for express delivery operators. Manufacturing concentration in the Yangtze River Delta serves electronics export corridors with rigid mailer formats.
India
Flipkart and Amazon India fulfillment centers in Bangalore and Mumbai remain underpenetrated by rigid mailer formats optimized for electronics returns. BIS certification requirements for paper-based packaging materials create qualification barriers for imported substrates. Converter capacity in Maharashtra and Gujarat scales to serve domestic e-commerce growth.
Netherlands
Rotterdam distribution hubs specify water-based barrier coatings for coastal humidity exposure without polyethylene laminates. REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy oil-grease-resistance treatments by 2026. Dutch converters pilot bio-based sizing agents for electronics fulfillment networks serving Northern European markets.
Paperboard Mailer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital print integration and fiber-based cushioning systems as differentiation vectors. The vendor base organizes around three maturity tiers: integrated containerboard mills controlling upstream fiber sourcing, specialized converters with design-to-die capabilities, and regional fabricators serving long-tail procurement. Strategic archetypes include backward-integrated fiber controllers, premium-format specialists, and scale-driven commodity suppliers. Competitive moves concentrate on M&A for geographic coverage and capacity expansion in Central European mill networks.
Among North American integrated producers, WestRock Company and International Paper Company exemplify fiber-control archetypes with captive containerboard supply. Mondi Group anchors European positioning through kraft paper specialization. These three represent distinct strategic postures: WestRock exemplifies backward-integrated substrate control, International Paper occupies scale-driven commodity positioning, and Mondi Group sits within premium-grade European specialization.
| Leading Market Players |
|---|
| WestRock Company |
| International Paper Company |
| Georgia-Pacific LLC |
| Sealed Air Corporation |
| Pregis LLC |
| Mondi Group |
| DS Smith Plc |
| Packaging Corporation of America |
| Smurfit Kappa |
| Others |
Value Network & Pricing Analysis
OCC price volatility cascades through German and Polish mill networks into three-tier pricing structures across premium, standard, and economy levels, with Amazon and Zalando buying desks extracting volume discounts that compress converter margins on fixed-price annual contracts.
Pricing Analysis
Volume concentrates in kraft paper grades for bulk shipping contracts where Deutsche Post and DHL procurement emphasizes cost efficiency, while margin pools sit with virgin fiber rigid mailers for premium electronics brands demanding color fidelity. Price differentiation hinges on certification grade—FSC chain-of-custody documentation commands premiums—and volume scale, with hyperscale e-commerce platforms negotiating outcome-based performance guarantees. Pricing pressure stems from Chinese import quota policies on recovered fiber, squeezing converters locked into annual agreements. Small business shippers through retail channels exhibit highest price sensitivity; luxury cosmetics direct-to-consumer channels show least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and Walmart fulfillment centers, while distributor networks serve fragmented mid-market procurement. Supply concentrates in Germany, Poland, and the Czech Republic where integrated containerboard mills control upstream fiber sourcing. Raw material dependencies center on OCC streams from municipal collection systems, sulfate pulp from Nordic producers, and hot-melt adhesives qualified for repulpability. Single-source vulnerability sits with German mill networks supplying cross-border EU corridors. Distribution runs through converter account teams for enterprise buyers and digital procurement platforms for long-tail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive containerboard supply determines procurement access to hyperscale e-commerce platforms, with fiber sourcing control emerging as the decisive competitive lever.
For Market Incumbents: Hedge against polybag substitution resilience by accelerating water-based barrier coating qualification for coastal humidity exposure, while securing post-consumer kraft sources ahead of EU Packaging and Packaging Waste Regulation recycled content thresholds. Capacity addition in Ohio and Pacific Northwest clusters captures Amazon and Walmart direct contract flows. Certification investment in FSC chain-of-custody documentation defends position against emerging entrants lacking audit infrastructure. For New Entrants and Emerging Players: Mid-market direct-to-consumer brands in Indian e-commerce corridors represent the most penetrable buyer archetype, with Bangalore and Mumbai fulfillment centers underpenetrated by rigid mailer formats optimized for electronics returns. White-space targets include subscription box operators demanding printed interior surfaces and Dutch converters piloting bio-based sizing agents ahead of REACH fluorine-free deadlines. Digital print integration for variable-data exterior branding offers a differentiated go-to-market angle against commodity suppliers. For Investors and Strategic Acquirers: Consolidated buying desk compression at major e-commerce platforms is the leading indicator that scale advantages are concentrating with design-to-die converters in Poland and the Czech Republic. Long-term viability favors acquisition targets with integrated fiber sourcing and certified sustainability documentation. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines for early signals of converter consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Mills | Captive fiber supply secures Amazon and Zalando contract access against OCC price swings. |
| Digital Print System Deployment | Hybrid inkjet enables variable-data branding that transforms mailers into mobile advertising surfaces. |
| Water-Based Barrier Coating Qualification | Silicate treatments satisfy Netherlands humidity specifications without polyethylene laminate repulpability penalties. |
| Central European Capacity Expansion | Polish and Czech mill networks serve cross-border EU corridors with Brussels-mandated recycled content compliance. |
| FSC Chain-of-Custody Certification | Certified documentation meets tier-one fulfillment operator requirements for outcome-based performance guarantees. |
Research Methodology
Document review covered EU Packaging and Packaging Waste Regulation filings, EPA extended producer responsibility guidance, and customs trade data on OCC import flows, complemented by interviews with converter procurement directors, e-commerce platform packaging engineers, and kraft paper mill operations managers. Secondary sources included SEC 10-K disclosures from integrated producers, FSC certification databases, and REACH substance restriction timelines. Bottom-up shipment volume estimates from fulfillment center specifications triangulated against top-down market sizing from fiber grade consumption patterns.
Segmentation outputs across product type, material grade, end user, and distribution channel dimensions were modeled over the projection horizon, with CAGRs derived from regression analysis of e-commerce penetration rates and regulatory compliance cost trajectories. Forecast inputs incorporated dimensional weight pricing adoption curves and recycled content mandate phase-in schedules without year-specific anchors.
Revisions become necessary when Chinese OCC import quota policies shift, EU member state enforcement timelines diverge, or humidity-resistant coating performance gaps persist in high-temperature transport corridors. Practitioners should monitor Brussels recycled content threshold announcements and SAMR packaging waste reduction standards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market