
 Morocco Corrugated Board Market | 2026-2036
Morocco Corrugated Board Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Corrugated Board Market Insights
Modular box configurations with variable-depth scoring and partition inserts are restructuring how Moroccan manufacturers specify corrugated packaging for export-bound electronics and pharmaceuticals. Smurfit Kappa leverages its integrated containerboard-to-box plant network near Kenitra to secure volume contracts with multinational FMCG brands. Gharb Papier et Carton anchors domestic supply through recycled-content specialization, while CMCP-International Paper competes on linerboard quality grades suited for high-humidity agricultural exports.
Corrugated board consists of one or more fluted medium sheets adhesively bonded to flat linerboard facings, with flute heights ranging from A-flute to F-flute and basis weights typically spanning 125–350 gsm per ply. This engineered paper structure provides compressive strength, cushioning, and printable surfaces for secondary and tertiary packaging across industrial supply chains. Single wall configurations dominate volume production for routine shipping cases, though die-cut formats are gaining traction among cosmetics and pharmaceutical end users seeking retail-ready presentation with reduced assembly labor. Double wall grades sustain premium pricing in the electronics segment where stacking strength requirements exceed standard test protocols.
Morocco's packaging sector operates under CEMAC conformity requirements for intra-regional trade, while BSI-equivalent national standards govern edge crush test certification for export eligibility to EU markets. The country's environmental ministry enforces extended producer responsibility frameworks that elevate recycled fiber content thresholds and reshape converter sourcing from virgin to post-consumer furnish streams. Stakeholders must monitor how pending EU packaging and packaging waste regulation amendments will cascade into Moroccan supplier audit protocols and capital allocation decisions.
Market Dynamics
Extended producer responsibility frameworks from Morocco's environmental ministry are compressing converter margins while forcing capital reallocation toward recycled fiber processing systems and fluting innovation lines.
Growth Catalysts
- Agri-food export compliance:European retail chains now mandate edge crush test certification for Moroccan citrus and tomato shipments, pulling volume toward certified double-wall grades.
- REACH-equivalent recyclability mandates:National standards body enforcement of packaging recyclability thresholds is accelerating linerboard-to-medium substitution ratios in converter specifications.
- Automotive cluster concentration:Renault-Nissan supplier parks near Tangier-Med are generating dedicated demand for just-in-time corrugated dunnage and returnable packaging systems.
Market Restraints
- Recovered paper import dependency:Morocco lacks domestic wastepaper collection infrastructure, exposing converters to Baltic and Turkish furnish price volatility.
- Natural gas cost structure:Drying energy represents 35-40% of linerboard production costs, with no alternative fuel substitution pathway certified for food-contact grades.
- CEMAC border friction:Intra-regional corrugated trade faces non-tariff barriers at Algerian and Mauritanian crossings, fragmenting scale economies for multi-country suppliers.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Insulated corrugated box formats with phase-change material integration are penetrating vaccine distribution networks serving sub-Saharan Africa.
- Fez-Meknes industrial corridor:Underdeveloped converter capacity in this olive oil and leather goods cluster offers first-mover positioning for automated box plants.
- Digital print convergence:Single-pass inkjet systems are enabling run-of-one customization for promotional packaging, collapsing minimum order quantities for cosmetics brands.
Industry Challenges
- Skilled die-cut tooling specialists:Shortage of technicians capable of maintaining rotary die accuracy below 0.3mm tolerance is extending new product qualification timelines.
- Legacy ERP integration:Converter order-to-delivery systems lack API connectivity with multinational FMCG procurement portals, forcing manual order re-entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Corrugated Board Market |
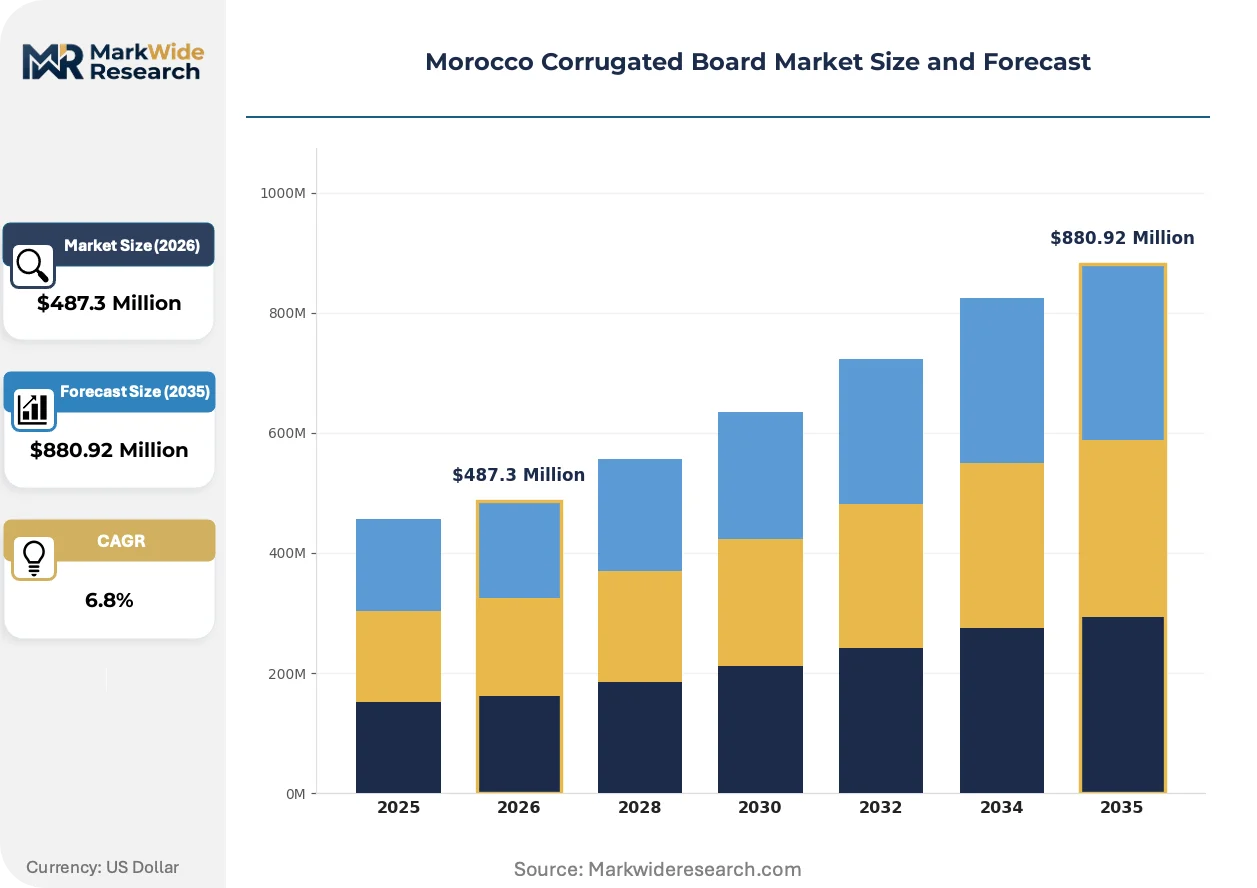
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Die-Cut Application: Packaging, Display, Transportation, Furniture End User: Food & Beverage, Electronics, Pharmaceuticals, Textile Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | International Paper, Smurfit Kappa, Mondi PLC, DS Smith, GharbPaper and Cardboard, CMCP-International Paper, Gharb Papier et Carton, CMCP, GPC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Corrugated Board Market Trends and Innovations
Digital workflow integration and material science advances are compressing design-to-delivery cycles while elevating performance specifications for humidity-resistant agricultural exports.
Micro-flute F and G profiles bonded to high-performance linerboard are absorbing moisture vapor transmission requirements that previously demanded plastic corrugated substitution. Pharmaceutical exporters in the Casablanca-Settat corridor are adopting these formats for temperature-sensitive shipments to Gulf markets. The technology is absorbing market share from extruded polypropylene in applications where fiber-based recyclability carries buyer preference weight.
Morocco's environmental ministry is tightening extended producer responsibility enforcement timelines, requiring converters to document post-consumer fiber content percentages in quarterly compliance filings. This policy compression is reshaping raw material procurement toward certified recovered paper streams with chain-of-custody documentation. Agricultural exporters to EU markets are experiencing the steepest audit intensity, with some suppliers losing retail shelf access over incomplete packaging passport data.
Consolidated procurement through multinational FMCG category managers is displacing fragmented spot purchasing that historically dominated Moroccan converter order books. Regional supply chain directors now mandate supplier sustainability scorecards with third-party verified recycled content claims. This behavioral shift is most visible in the personal care segment, where Unilever and Procter & Gamble joint ventures are consolidating corrugated spend under two-year framework agreements with integrated producers.
Morocco Corrugated Board Market Segmentation
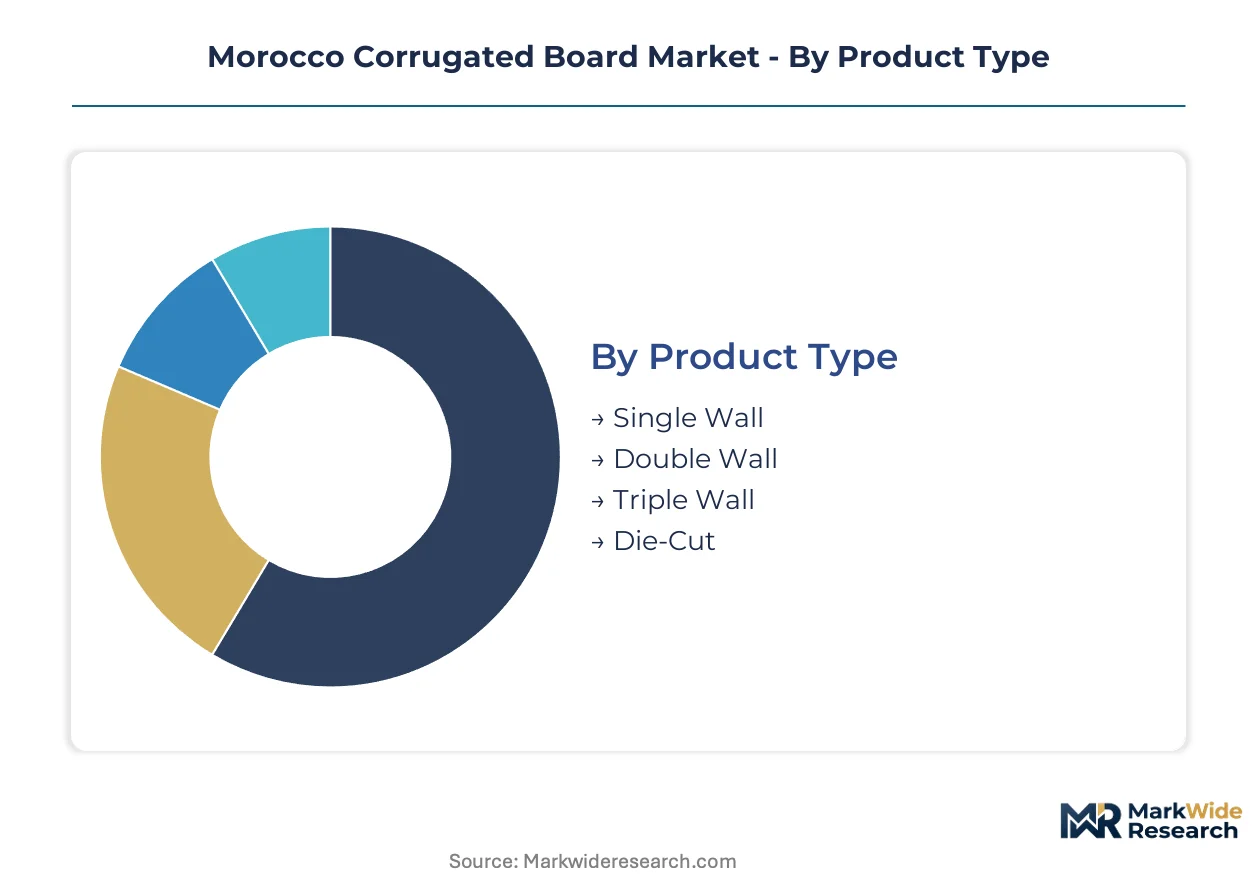
Segmentation in the Morocco corrugated board market reveals how converter capacity aligns with export compliance requirements and domestic industrial clustering. Distinct product specifications serve divergent end-use priorities across agri-food, automotive, and pharmaceutical supply chains.
Product Type:
Single wall configurations dominate volume production, while double and triple wall grades command premium positioning through enhanced stacking performance.
- Single Wall:One fluted medium sheet bonded between two linerboard facings, typically A-flute or C-flute profiles with basis weights of 125–200 gsm. Casablanca-Settat automotive suppliers specify this grade for just-in-time component dunnage where handling cycles remain moderate.
- Double Wall:Two fluted mediums separated by an intermediate liner, combining B-flute and C-flute layers for edge crush test ratings exceeding 7,000 N/m. European retail chains mandate this construction for Moroccan citrus exports requiring 14-day humidity exposure resistance.
- Triple Wall:Heavy-duty format with three fluted layers for bulk agricultural machinery parts and industrial equipment crating.
- Die-Cut:Precision-scored formats with variable-depth creasing for retail-ready cosmetics and pharmaceutical presentation boxes.
Mature deployment sits with Single Wall. Newer deployment is concentrated in Die-Cut as cosmetics brands adopt run-of-one customization.
Application:
Functional requirements diverge sharply between protective shipping functions and point-of-sale display priorities.
- Packaging:Secondary and tertiary containment for finished goods transit, spanning routine RSC cases to specialized moisture-barrier formats. Food and beverage exporters in the Gharb plain drive specification toward recycled-content compliance with EU packaging waste directives.
- Display:Shelf-ready corrugated structures with litho-laminated graphics for hypermarket placement. Personal care joint ventures in Kenitra industrial zones are collapsing traditional packaging-display boundaries through integrated procurement.
- Transportation:Palletized unit load containment with slip-sheet integration for Tangier-Med port logistics.
- Furniture:Flat-pack corrugated frameworks replacing expanded polystyrene in e-commerce mattress and modular seating shipments.
Transportation applications anchor volume throughput at integrated mills. Display formats are climbing the fastest as multinational FMCG category managers consolidate shelf-ready specifications.
End User:
Export eligibility requirements create tiered specification intensity across customer segments.
- Food & Beverage:Dominant demand concentration spanning citrus, tomatoes, olive oil, and processed seafood. CEMAC conformity requirements for intra-regional trade combine with BSI-equivalent edge crush certification for EU market access, forcing dual-standard converter compliance.
- Electronics:Anti-static and humidity-resistant formats for semiconductor and consumer device re-export through Tangier-Med free zone. Renault-Nissan supplier parks generate dedicated demand for returnable packaging systems with specified cycle life.
- Pharmaceuticals:Cold-chain formats with phase-change material integration for vaccine distribution to sub-Saharan Africa.
- Textile:Garment-on-hanger and flat-packed formats for fast fashion export consolidation.
Food and beverage commands mature converter relationships with certified recovered paper streams. Pharmaceutical cold-chain represents the steepest specification escalation as Morocco's environmental ministry tightens extended producer responsibility enforcement.
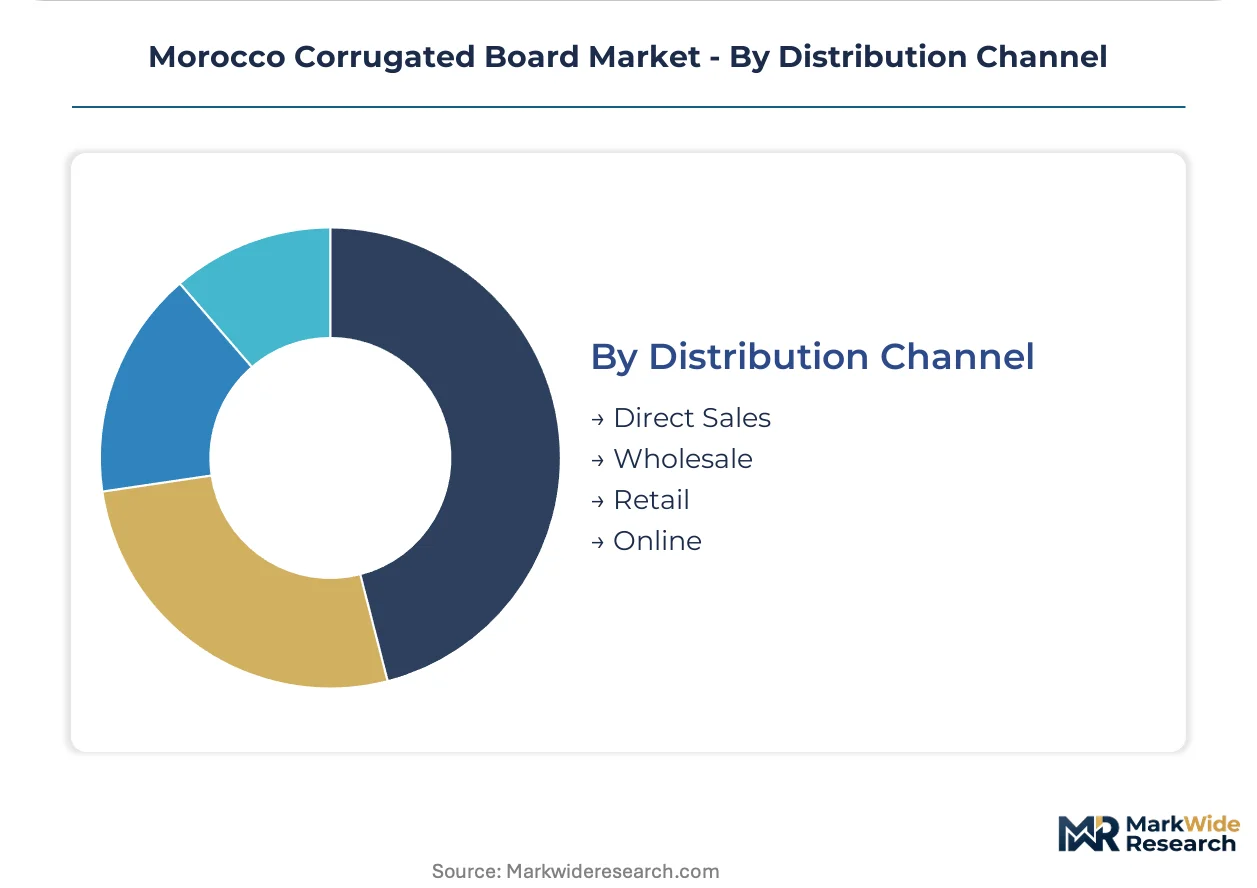
Distribution Channel:
Channel structure reflects the displacement of fragmented spot purchasing by consolidated multinational procurement.
- Direct Sales:Framework agreements between integrated producers and multinational FMCG category managers. Smurfit Kappa's Kenitra network secures two-year contracts with joint ventures specifying sustainability scorecards and third-party verified recycled content claims.
- Wholesale:Converter-to-distributor relationships serving mid-tier agri-food exporters lacking dedicated packaging procurement functions.
- Retail:Limited penetration given industrial end-use dominance; primarily serves small cosmetics and artisanal food producers.
- Online:Emerging channel for standardized box specifications with collapsed minimum order quantities through digital print convergence.
Direct sales infrastructure is deepening through API integration investments. Online channels are gaining share fastest among cosmetics brands seeking promotional packaging agility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tangier-Med port special economic zone anchors corrugated demand through automotive and logistics clustering, while Casablanca-Settat industrial corridor concentrates agri-food and pharmaceutical packaging procurement.
Casablanca-Settat
Citrus exporters and pharmaceutical cold-chain operators drive specification intensity toward double-wall humidity-resistant grades. Morocco's environmental ministry enforces quarterly extended producer responsibility filings that reshape converter sourcing. Kenitra industrial zones host integrated containerboard-to-box plants serving multinational FMCG framework agreements.
Tanger-Tetouan-Al Hoceima
Renault-Nissan supplier parks generate dedicated demand for returnable corrugated dunnage and just-in-time packaging systems. National standards body edge crush certification aligns with BSI-equivalent protocols for EU market access. Tangier-Med port logistics clusters concentrate transportation-grade palletized unit load containment.
Fez-Meknes
Olive oil processors and leather goods exporters create underdeveloped converter capacity opportunities. Recovered paper import dependency exposes producers to Baltic and Turkish furnish price volatility. Automated box plant investment remains limited despite promotional packaging agility demand from cosmetics brands.
Rabat-Sale-Kenitra
Personal care joint ventures consolidate shelf-ready corrugated specifications through two-year procurement frameworks. Digital print convergence enables run-of-one customization collapsing minimum order quantities. Smurfit Kappa's integrated network secures volume contracts with sustainability scorecard requirements.
Marrakech-Safi
Processed seafood exporters and artisanal food producers sustain wholesale distribution channel relationships. Natural gas cost structure pressures drying energy representing 35-40% of linerboard production costs. Limited API connectivity between converter ERP systems and multinational procurement portals forces manual order re-entry.
Morocco Corrugated Board Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Morocco's corrugated board market, creating a tiered structure where integrated producers command premium positioning. The vendor base clusters around three strategic archetypes: multinational integrated producers with captive containerboard supply, domestic recycled-content specialists serving compliance-driven exporters, and regional converters targeting spot purchasing fragmentation. Capacity expansion and sustainability certification investments represent the dominant competitive moves reshaping procurement relationships.
Among multinational integrated producers, Smurfit Kappa and International Paper exemplify scale-driven positioning through Kenitra corridor infrastructure. Gharb Papier et Carton occupies a specialist tier representing domestic recycled-content capabilities. CMCP-International Paper sits within the joint-venture archetype combining international linerboard quality with local market access. These anchors reflect how competitive positioning stratifies across premium certified grades, standard volume contracts, and economy spot purchasing tiers.
| Leading Market Players |
|---|
| International Paper |
| Smurfit Kappa |
| Mondi PLC |
| DS Smith |
| GharbPaper and Cardboard |
| CMCP-International Paper |
| Gharb Papier et Carton |
| CMCP |
| GPC |
| Others |
Pricing and Supply Chain Analysis
European retail chain consolidation around sustainability scorecards is forcing Moroccan converters toward certified recovered paper streams, compressing margins and elevating input cost volatility. This procurement shift elevates pricing power for integrated producers with captive linerboard supply while squeezing spot-market converters dependent on Baltic and Turkish furnish imports.
Pricing Analysis
Short lead-time premiums dominate converter-customer negotiations, with just-in-time automotive dunnage commanding 15-20% markups over standard volume contracts. Three-tier pricing structure across premium certified grades, standard double-wall export specifications, and economy single-wall domestic tiers reflects certification investment and fiber content verification. Cost compression in the economy tier is intensifying because natural gas drying expenses represent 35-40% of production costs with no certified alternative fuel pathway. Mid-tier agri-food exporters exhibit highest price sensitivity, while pharmaceutical cold-chain operators prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Baltic and Turkish recovered paper suppliers, as Morocco lacks domestic wastepaper collection infrastructure. Raw material procurement draws from Turkish OCC mills, Baltic kraft pulp traders, and Spanish linerboard exporters, creating exposure to currency fluctuation and shipping rate volatility. Tariff exposure at Algerian and Mauritanian CEMAC border crossings fragments scale economies for multi-country suppliers. Distribution runs through Tangier-Med port logistics clusters and direct mill-to-plant framework agreements with multinational FMCG category managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converter capacity constraints around certified recovered paper processing and skilled die-cut tooling specialists are propping pricing power for integrated producers. Supply scarcity in these capability layers creates defensive moats for incumbents with upstream control.
For Market Incumbents: Hedge margin exposure by securing long-term offtake agreements with Baltic recovered paper traders before EU packaging waste regulation amendments cascade into Moroccan audit protocols. Prioritize automated box plant investment in the Fez-Meknes corridor to capture olive oil and leather goods demand currently served by wholesale distributors with manual order re-entry systems.
For New Entrants and Emerging Players: Digital print convergence routes offer lowest barrier-to-entry positioning for cosmetics promotional packaging with collapsed minimum order quantities. Target the Rabat-Sale-Kenitra personal care joint venture cluster where shelf-ready specifications are consolidating under two-year framework agreements. Lead with run-of-one customization capabilities and API-enabled order portals that bypass legacy ERP integration gaps plaguing incumbent converters.
For Investors and Strategic Acquirers: The window for entry favors domestic recycled-content specialists with chain-of-custody documentation and established relationships with agri-food exporters facing EU extended producer responsibility enforcement. Monitor quarterly compliance filing intensity from Morocco's environmental ministry as the inflection indicator for regulatory-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Paper Processing | Captures margin from Baltic furnish volatility while satisfying EPR documentation requirements. |
| Automated Box Plant Deployment | Addresses Fez-Meknes corridor capacity scarcity for olive oil export packaging. |
| Digital Print System Installation | Enables run-of-one cosmetics promotional packaging with collapsed MOQs. |
| API-Enabled Order Portal Development | Bypasses legacy ERP gaps blocking multinational FMCG procurement integration. |
| Phase-Change Material Cold-Chain Format Launch | Penetrates vaccine distribution networks serving sub-Saharan Africa from Casablanca-Settat. |
Research Methodology
Document review covered trade customs data, national standards body filings, and EU packaging waste directive amendments, complemented by interviews with converter operations directors, multinational FMCG category managers, automotive Tier 1 supplier procurement leads, and pharmaceutical cold-chain logistics coordinators. Secondary sources included Moroccan environmental ministry EPR enforcement records, Tangier-Med port throughput statistics, and linerboard producer SEC disclosures. Bottom-up volume modeling triangulated against top-down industrial clustering analysis across the Casablanca-Settat and Tanger-Tetouan corridors.
Historical capacity utilization patterns cross-referenced against panel input from plant managers and equipment suppliers shaped the projection framework. Segmentation modeling spanned product type, application function, end-user industry, and distribution channel across the analysis window. CAGRs derived from fitted trend extrapolation adjusted for regulatory phase-in timelines and automotive cluster expansion schedules. Forecast inputs incorporated natural gas cost trajectories and recovered paper import price elasticity assumptions.
The model holds under stable EU-Morocco trade compliance frameworks; deviation in EPR enforcement intensity or CEMAC border tariff implementation would shift volume and value outlooks materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market