
 Paper Based Consumer Bags Market | 2026-2036
Paper Based Consumer Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Based Consumer Bags Market Intelligence
The apparel retailers segment is expanding its share within the paper based consumer bags market, driven by brand image and sustainability initiatives. Smurfit Kappa leverages its integrated network of recycled fiber collection and paper mills to supply this vertical. International Paper anchors its position in the North American food service sector with high-strength virgin kraft paper bags. Meanwhile, Mondi Group specializes in premium, coated paper bags for luxury goods and beauty retail.
Paper based consumer bags are lightweight, foldable containers primarily manufactured from materials like kraft or recycled paper. These products, often specified by grammage and burst strength, serve as a primary packaging and carrying solution in retail environments. Within product types, handle bags dominate due to their utility in grocery and fashion retail. A notable shift in material type shows recycled paper gaining share from virgin paper, influenced by corporate ESG commitments and cost.
Frameworks like the EU's Single-Use Plastics Directive and similar state-level mandates in the United States directly prohibit or tax plastic alternatives. Simultaneously, standards from bodies such as the Forest Stewardship Council (FSC) and India's Bureau of Indian Standards (BIS) govern fiber sourcing and product quality. Navigating the complex landscape of material certifications and recycled content verification is now a central strategic challenge for all manufacturers.
Market Dynamics
The paper based consumer bags market is fundamentally shaped by a global regulatory pivot away from single-use plastics. This legislative pressure, combined with heightened consumer environmental awareness, creates a powerful and sustained demand driver that defines competitive and strategic priorities for all manufacturers.
Growth Catalysts
- Regulatory Mandates:Directives like the European Union's Single-Use Plastics Directive and numerous state-level bans in the United States actively phase out plastic competitors, creating a direct substitution-driven expansion for paper alternatives.
- Brand Image Enhancement:In the apparel and luxury retail sectors, premium paper bags with high-quality printing and sustainable certifications serve as a tangible extension of a brand's commitment to environmental responsibility.
- Corporate ESG Policies:A corporate focus on Environmental, Social, and Governance metrics is compelling large retailers and food service chains to increase their procurement of bags made from recycled and FSC-certified paper fibers.
Market Restraints
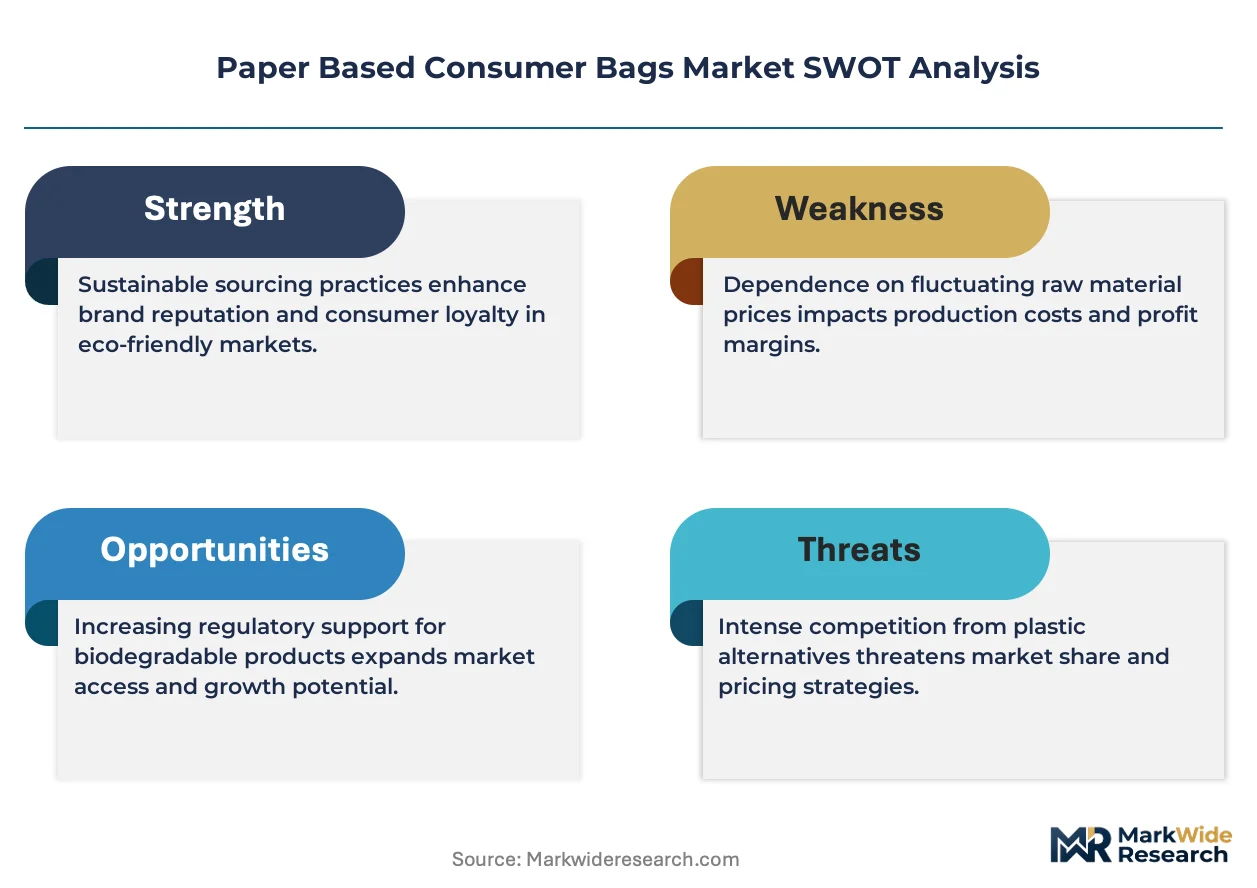
- Raw Material Price Volatility:The market is exposed to significant price fluctuations in key inputs like wood pulp and recycled fiber, which can compress manufacturer margins and create uncertainty in supply contracts.
- Performance Limitations:Compared to plastic alternatives, standard paper bags exhibit lower durability, tear resistance, and a critical vulnerability to moisture, limiting their application in certain heavy-duty or weather-exposed conditions.
- Competition from Reusables:The rise of durable, multi-use bags made from materials like non-woven polypropylene or cotton presents a significant substitution threat, as they compete on a long-term sustainability and cost-per-use basis.
Strategic Opportunities
- E-commerce and Food Delivery Packaging:Developing specialized paper bags with features like tamper-evident seals, thermal insulation properties, or robust handles for online order fulfillment and food delivery represents a significant growth avenue.
- Emerging Market Plastic Bans:As countries in Latin America and Southeast Asia begin to implement their own restrictions on single-use plastics, there is a substantial opportunity for early market entry and establishing supply chains.
- Biodegradable Barrier Coatings:Innovations in water-based and compostable coatings that improve the grease and moisture resistance of paper can unlock new applications in the fresh food and quick-service restaurant sectors.
Industry Challenges
- Certification and Compliance Complexity:Manufacturers face the operational challenge of navigating a fragmented landscape of material certifications, such as FSC and PEFC, alongside varying state and national laws on recycled content verification.
- Fiber Sourcing Consistency:Securing a consistent, high-quality supply of certified or post-consumer recycled fiber at scale is a persistent logistical challenge that can constrain production capacity and impact costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Based Consumer Bags Market |
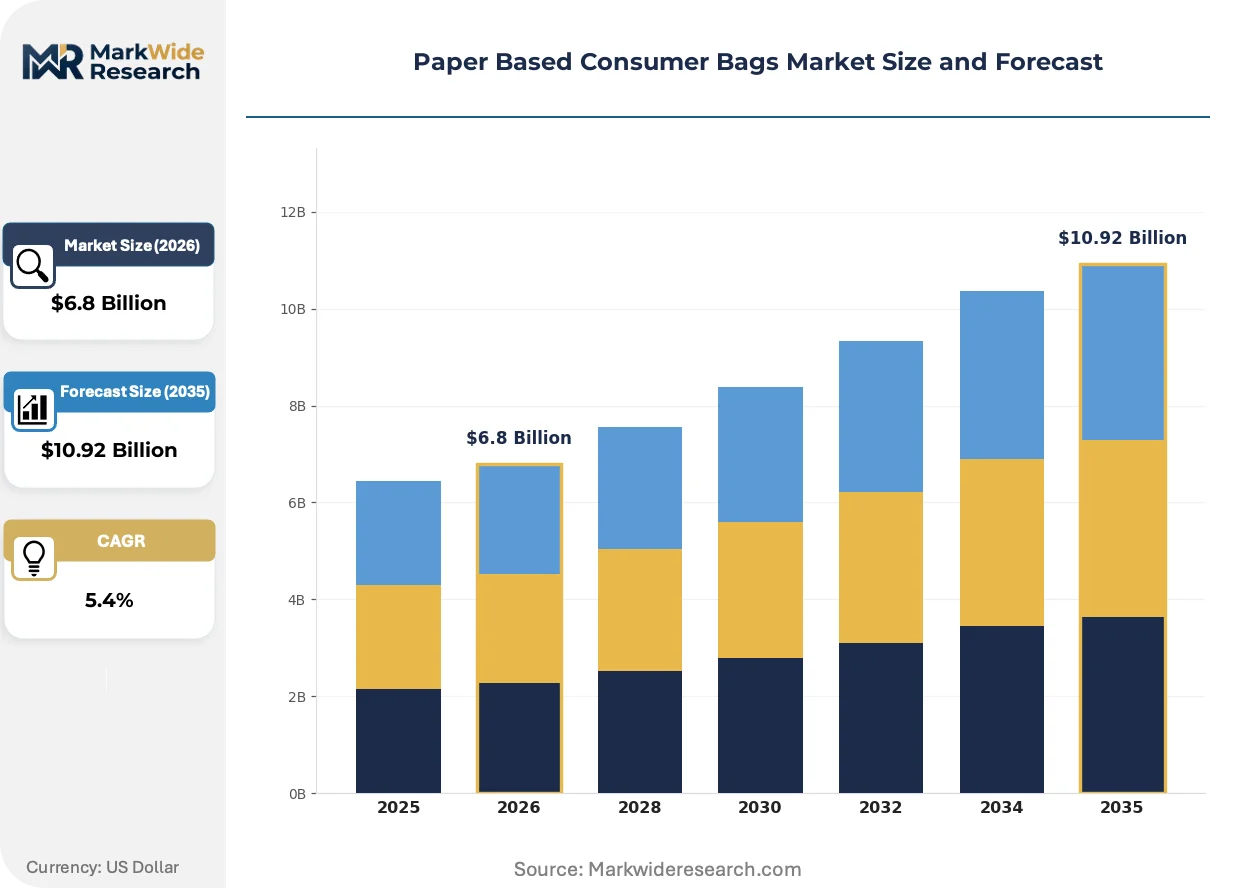
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Virgin Paper, Recycled Paper, Laminated Paper, Art Paper Product Type: Handle Bags, Flat Bags, Gusseted Bags, Envelope Bags, Patch Handle Bags End User: Food & Beverage, Apparel Retailers, Electronics Stores, Beauty & Personal Care, Bookstores Distribution Channel: Supermarkets, Online Stores, Specialty Shops, Hypermarkets, Convenience Stores |
| Companies Covered | Mondi Group, International Paper, Smurfit Kappa, WestRock, DS Smith, Stora Enso, Oji Holdings Corporation, Novolex, BillerudKorsnäs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Based Consumer Bags Market Strategic Shifts & Innovations
Innovation in the paper bag market is driven by the dual objectives of matching the functional performance of plastic while amplifying sustainability credentials. This forces advancements in material science, particularly concerning barrier properties and end-of-life recyclability, which are reshaping product design and application scope.
Water-based barrier coatings provide grease, oil, and moisture resistance without compromising the recyclability of the final product. The food service and grocery sectors are rapidly adopting bags with these coatings to package prepared foods and baked goods. This advanced coating technology is overtaking traditional polyethylene-laminated paper, which poses significant challenges for recycling streams and is increasingly restricted by municipal waste programs.
India's Bureau of Indian Standards (BIS) has implemented specific standards governing the quality and grammage of paper bags. This regulation creates a mandatory baseline for product performance, impacting everything from fiber sourcing to production line quality control. The primary effect is a consolidation pressure on the market, as smaller, unorganized producers struggle to meet the capital investment and testing requirements for BIS compliance.
A distinct shift in buyer behavior elevates the paper bag from a simple utility item to a critical component of brand marketing. Procurement decisions in fashion and beauty retail now weigh factors like paper texture, handle material, and print fidelity alongside cost and strength. This trend is most visible in North American and European markets, where the bag's visual appeal for social media sharing directly influences consumer perception of the brand.
Paper Based Consumer Bags Market Segmentation
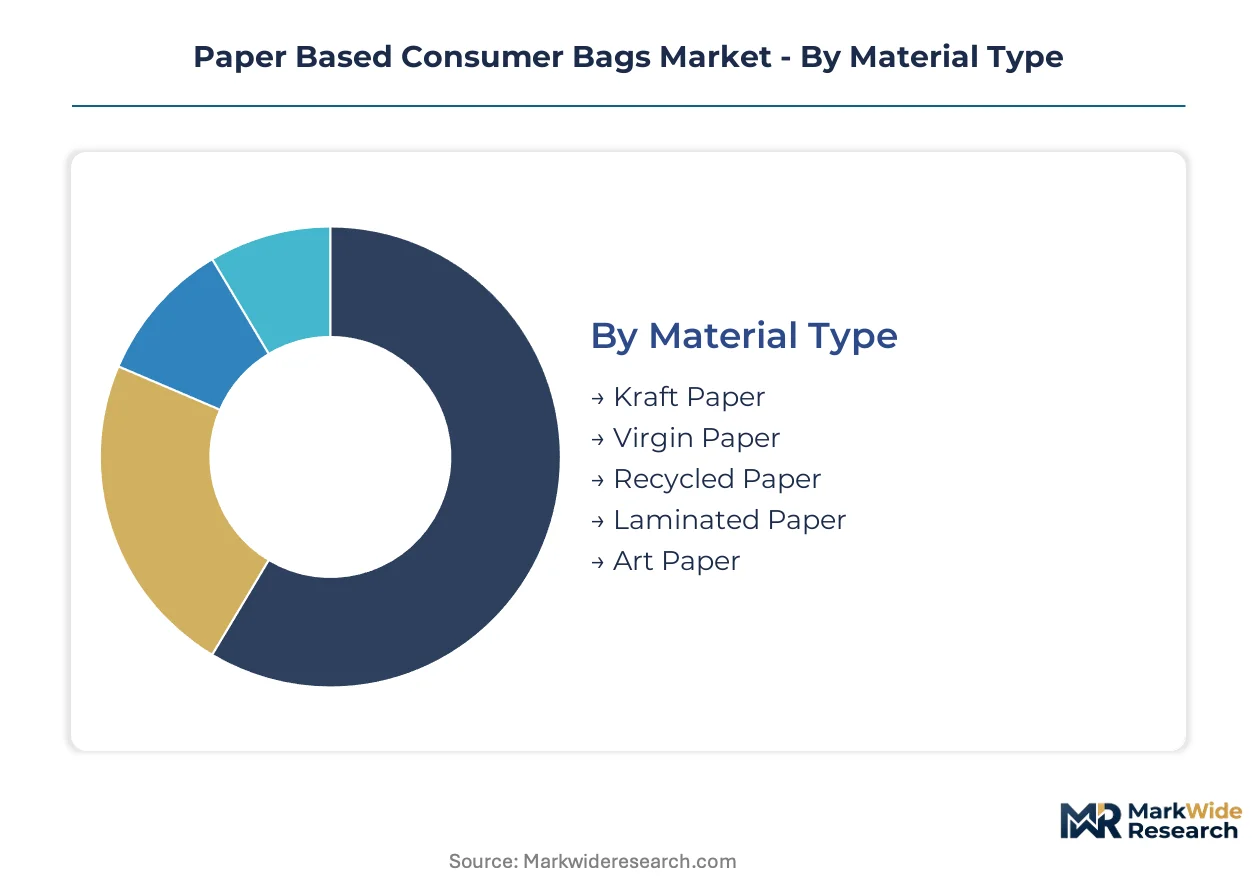
The segmentation of the paper based consumer bags market reveals distinct product characteristics and diverse end-user applications. Understanding these segments provides clarity on where demand originates and how material innovations are being adopted across different retail environments. This granular view helps manufacturers tailor product offerings and optimize supply chain strategies.
Material Type:
Supply concentration in the paper based consumer bags market is increasingly influenced by the availability and cost of specific raw materials, particularly recycled fibers. Manufacturers prioritize materials that balance performance with environmental credentials.
- Recycled Paper:This material consists of post-consumer waste paper and pre-consumer scrap, processed into new paper pulp. Demand for recycled paper bags is high in Europe, driven by corporate ESG commitments and the EU's Single-Use Plastics Directive.
- Kraft Paper:Known for its high tear resistance and strength, kraft paper is produced from wood pulp through the kraft process. Its versatility makes it a staple in grocery and general merchandise retail, especially in North American markets where durability is valued.
- Virgin Paper:Sourced directly from wood pulp, virgin paper offers superior print quality and brightness. Luxury brands often select virgin paper for its aesthetic appeal, particularly in fashion and beauty retail.
- Laminated Paper:This material combines paper with a thin layer of plastic or other barrier material for enhanced moisture or grease resistance. Applications include food service packaging where product integrity is critical, though recycling challenges persist.
- Art Paper:Featuring a smooth, coated surface, art paper is primarily used for high-end packaging requiring intricate printing and a premium finish. This segment caters to specialized retail sectors like jewelry and high-end cosmetics.
Today's leader: Recycled Paper. Tomorrow's challenger: Kraft Paper.
Product Type:
The application range of paper based consumer bags is defined by their structural design and utility in various retail scenarios. Each product type serves specific carrying and presentation needs for consumers.
- Handle Bags:These bags incorporate integrated handles, typically made from twisted paper, flat paper, or cotton cord. Their utility in grocery, fashion, and general retail makes them ubiquitous, particularly in European supermarkets and specialty stores.
- Gusseted Bags:Characterized by side folds that expand to accommodate bulkier items, gusseted bags offer increased volume and stability. They find widespread use in food service for takeout orders and in various retail settings for larger purchases.
- Flat Bags:Simple, flat pouches without gussets or handles, often used for small, lightweight items or as secondary packaging. Bakeries and small retail outlets frequently utilize flat bags for individual product wrapping.
- Envelope Bags:Designed with a flap closure, these bags resemble envelopes and are often used for documents, books, or delicate apparel. Bookstores and boutique clothing stores commonly employ envelope bags for a refined presentation.
- Patch Handle Bags:Featuring a reinforced patch on the inside to strengthen the handle area, these bags combine durability with a clean aesthetic. Apparel retailers and gift shops often choose patch handle bags for a premium feel.
Handle Bags are expanding most quickly, while Gusseted Bags show a steep expansion trajectory.
End User:
Consumer bag procurement patterns are significantly influenced by the customer type and their specific operational requirements. Different retail sectors prioritize distinct attributes in their packaging solutions.
- Apparel Retailers:This segment demands paper bags that reflect brand aesthetics and sustainability commitments, often featuring high-quality printing and premium finishes. Retailers in countries like France and Germany leverage paper bags to enhance brand image and comply with local plastic reduction mandates.
- Food & Beverage:The food and beverage sector requires bags with specific barrier properties for hygiene and product preservation. Fast-food chains and cafes in the United States increasingly adopt paper bags with grease-resistant coatings for takeout and delivery services.
- Electronics Stores:These stores require durable bags capable of carrying potentially heavy or fragile electronic items, often with branding. Large electronics retailers use robust paper bags for consumer purchases.
- Beauty & Personal Care:This segment favors aesthetically pleasing bags that align with luxury branding and product presentation. Premium paper bags with specialized finishes are common in high-end beauty boutiques.
- Bookstores:Bookstores utilize paper bags for carrying books, prioritizing strength and often featuring literary-themed designs. Independent bookstores and large chains both rely on paper bags for customer purchases.
Apparel Retailers hold the largest share, with Food & Beverage gaining share fastest.
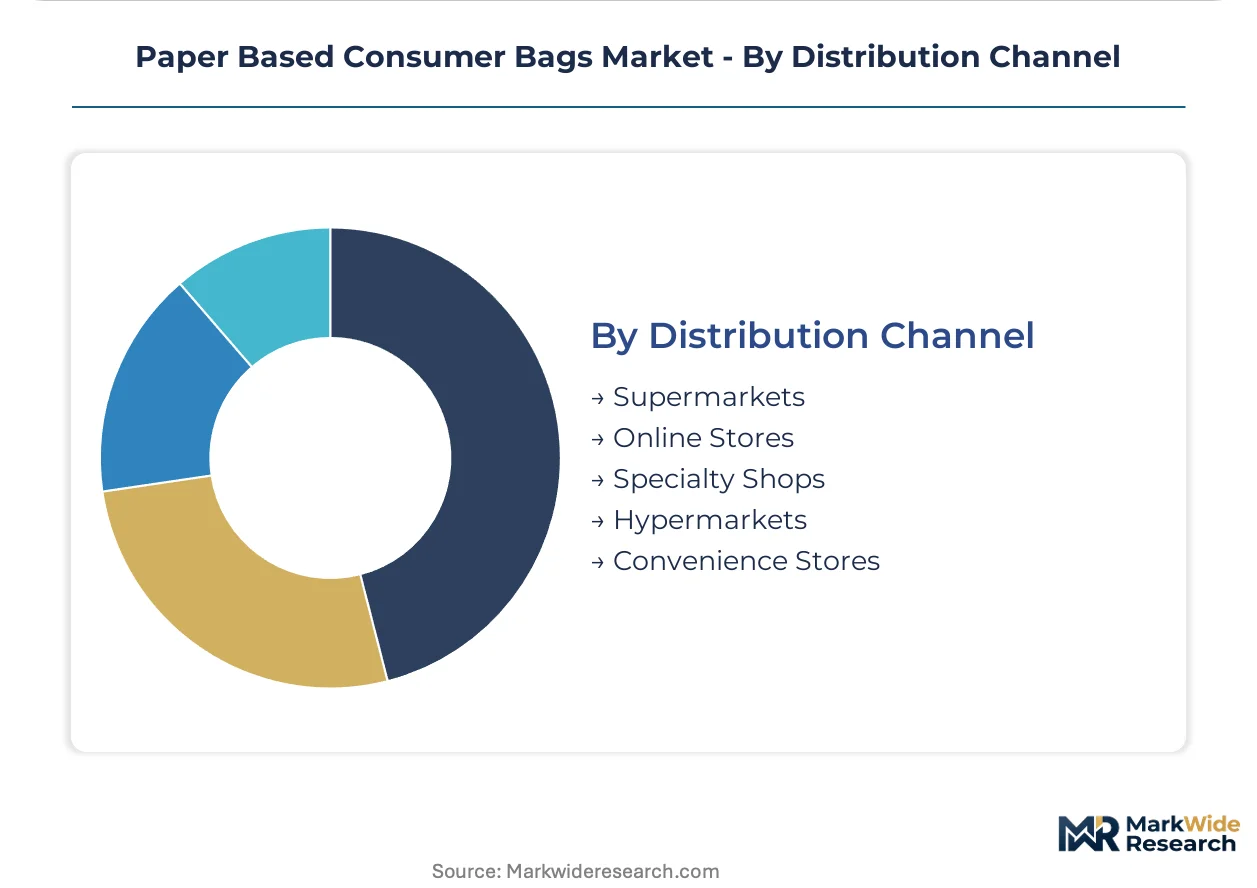
Distribution Channel:
The volume of paper based consumer bags distributed through various channels reflects the scale and nature of retail operations. Each channel presents unique logistical and packaging demands.
- Supermarkets:These large-volume retailers require vast quantities of sturdy, often handle-equipped, paper bags for daily grocery purchases. The shift away from plastic bags in countries like Italy and Spain has significantly boosted paper bag demand in supermarkets.
- Online Stores:The e-commerce sector demands specialized paper bags for shipping, often with tamper-evident features or enhanced durability. Growth in online food delivery platforms has accelerated the use of paper bags for last-mile logistics.
- Specialty Shops:These smaller, niche retailers often seek customized or premium paper bags that align with their brand identity. Boutique clothing stores and gift shops frequently procure bespoke paper bags.
- Hypermarkets:Similar to supermarkets but on a larger scale, hypermarkets require high volumes of robust paper bags for diverse product ranges. These outlets manage high transaction volumes requiring efficient bagging solutions.
- Convenience Stores:These smaller retail formats use paper bags for quick purchases and single items. Their demand is for functional, readily available bags suitable for impulse buys.
Supermarkets dominate, while Online Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing capabilities, combined with strict environmental regulations, drive significant innovation in the paper based consumer bags market. This focus on sustainability positions the country as a key regional hub for packaging solutions. Consumer awareness further propels demand for eco-friendly alternatives.
United States
State-level mandates in the United States actively phase out plastic bags, creating a direct expansion for paper alternatives. The Environmental Protection Agency (EPA) encourages sustainable packaging practices across the country. Major retail chains in New York and California actively procure paper bags, emphasizing recycled content.
Germany
Germany's robust recycling infrastructure supports high demand for recycled paper bags, driven by corporate ESG commitments. The EU Green Deal and national packaging laws enforce stringent sustainability requirements. Major retailers in Berlin and Munich lead efforts to adopt FSC-certified paper bags for brand image and compliance.
France
French consumer environmental awareness, coupled with national plastic reduction mandates, drives substantial paper bag adoption. The Agence de l'Environnement et de la Maîtrise de l'Énergie (ADEME) promotes circular economy principles for all packaging. Luxury brands in Paris integrate premium paper bags into their marketing strategies, reflecting environmental values.
India
India's Bureau of Indian Standards (BIS) has implemented specific quality and grammage standards governing paper bags. These regulations ensure a mandatory baseline for product performance and consolidate market players. Urban centers like Mumbai and Delhi see increasing adoption of compliant paper bags in retail.
Italy
Italian supermarkets and specialty shops significantly boost demand for sturdy, handle-equipped paper bags. The country's strong commitment to phasing out single-use plastics aligns with EU directives, accelerating market transition. Retail hubs in Milan and Rome are rapidly transitioning to paper-based packaging solutions.
Paper Based Consumer Bags Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the escalating demand for sustainable packaging solutions. The market exhibits a tiered structure, from large integrated paper manufacturers to specialized bag converters serving specific end-use segments. Strategic archetypes include global scale players focused on volume, regional specialists catering to local regulatory nuances, and innovation-focused niche providers developing barrier coatings. Dominant competitive moves involve significant investments in new production lines and strategic partnerships to secure consistent, high-quality recycled fiber supply.
Within the integrated packaging solutions archetype, Mondi Group exemplifies a premium-focused approach, particularly for luxury and beauty retail segments across Europe. International Paper occupies a position as a North American leader, anchoring the food service sector with its high-strength virgin kraft paper bags. Smurfit Kappa represents a strong European presence, leveraging its integrated network for recycled fiber collection and paper mills to supply the apparel sector with sustainable options. These entities collectively demonstrate the market's reliance on established players with extensive production capabilities and diverse product portfolios.
| Leading Market Players |
|---|
| Mondi Group |
| International Paper |
| Smurfit Kappa |
| WestRock |
| DS Smith |
| Stora Enso |
| Oji Holdings Corporation |
| Novolex |
| BillerudKorsnäs |
| Others |
Cost & Logistics Intelligence
Corporate ESG policies are compelling large retailers to increase procurement of recycled and FSC-certified paper bags. This demand directly influences supply chain investments, impacting overall market pricing structures.
Pricing Analysis
Raw material price volatility significantly influences paper bag pricing as manufacturers pass through increased costs for wood pulp and recycled fiber. The dominant pricing model is contract-based long-term offtake for large volume buyers. Price differentiation stems from quality grade, such as virgin versus recycled paper, and specific certifications like FSC or BIS compliance. Pricing pressure is generally upward due to investments in advanced barrier coatings and regulatory compliance, with the Food & Beverage sector exhibiting higher price sensitivity compared to luxury apparel retailers.
Supply Chain Analysis
Distribution channels for paper based consumer bags primarily run through large-volume retailers like supermarkets and rapidly expanding online stores. Geographic supply concentrates in Europe, particularly Germany and France, and North America, driven by regulatory shifts and established manufacturing. The supply chain relies on consistent access to wood pulp and high-quality recycled fiber. A structural risk involves the logistical challenge of securing certified or post-consumer recycled fiber at scale, impacting production capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper based consumer bags market presents a geographic-arbitrage opportunity, particularly given the regulatory divergence between Europe's strict plastic bans and varied adoption rates in emerging markets. Manufacturers can leverage distinct cost structures across regions.
For Market Incumbents: Hedge against raw material price volatility by deepening upstream control over recycled fiber collection and processing. Invest significantly in R&D for water-based barrier coatings to match plastic performance and mitigate the threat from reusable bags. Prioritize certification investments, such as FSC and BIS compliance, to reinforce market position against emerging entrants. Control over distribution channels in key European and North American markets remains crucial.
For New Entrants and Emerging Players: Begin with targeted market entry in emerging economies like those in Latin America and Southeast Asia, capitalizing on early plastic ban implementations. Focus on specialized e-commerce and food delivery packaging, offering features like tamper-evident seals or thermal insulation. The most penetrable segment includes small to mid-sized specialty shops seeking customized, premium paper bags. A go-to-market angle emphasizing rapid innovation in biodegradable barrier coatings offers a distinct advantage.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists demonstrating strong capabilities in sustainable material science or vertically integrated recycled fiber networks. The long-term viability of this market, spanning a 5-10 year window, is underpinned by global plastic reduction mandates and consumer preference shifts. Target acquisition profiles include companies with patented water-based barrier coating technologies or established supply chains in high-demand regions. The widespread adoption of compostable barrier coatings in quick-service restaurants serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Europe | Addresses surging demand from EU plastic bans and strengthens regional supply. |
| Biodegradable Barrier Coating Development | Unlocks new applications in food service by enhancing moisture and grease resistance. |
| Long-term Recycled Fiber Supply Agreements | Secures consistent raw material input and mitigates price volatility for manufacturers. |
| E-commerce Packaging Solution Launch | Captures growth in online retail and food delivery with specialized, durable bags. |
| FSC Certification Investment | Enhances brand image and ensures compliance with corporate ESG procurement policies. |
Research Approach
Direct dialogue with packaging procurement managers, paper mill executives, retail sustainability officers, and waste management specialists informed qualitative insights. This primary research was validated against secondary sources including regulatory filings, industry association reports, and corporate sustainability disclosures. A bottom-up data collection approach was triangulated with top-down market sizing. This ensured robust data integrity across the analysis.
A bottom-up analytical framework projected market volume and value across the analysis window. Segmentation dimensions included material type, product type, end user, distribution channel, and regional regulatory intensity. Compound annual growth rates were derived from historical data extrapolation and future growth projections. Key industry-specific inputs included plastic ban implementation timelines and the availability of certified recycled fiber.
Several conditions sit outside the modeled scope, including unforeseen macroeconomic shocks or rapid technological breakthroughs in non-paper alternatives. Forecasts reflect assumptions regarding regulatory stability and raw material supply. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Greyboard Market