
 Pre-Impregnated Paper Market | 2026-2036
Pre-Impregnated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Impregnated Paper Market Analytics
Multi-source procurement among decorative laminate manufacturers is hardening as supply security concerns reshape purchasing behavior. Koehler Paper leverages integrated pulp-to-paper operations to secure raw material continuity across European operations. Ahlstrom-Munksjö anchors its position through specialized fiber blending capabilities that serve aerospace and electrical insulation segments. Schattdecor AG dominates decorative print applications with extensive design libraries and close coordination with laminating equipment partners.
Pre-impregnated paper consists of base papers saturated with thermosetting resins, typically melamine, phenol, or epoxy formulations, then partially cured to a B-stage state for subsequent hot-press lamination. The material functions as a surface and core layer substrate in high-pressure and low-pressure laminate systems where resin flow, volatile content, and pre-cure degree determine final panel performance. Wood fiber substrates retain the largest share in decorative laminate applications where print clarity and resin absorption uniformity define grade premiums. Glass fiber variants command specialized positions in electrical insulation and aerospace components where thermal stability and dielectric strength requirements exceed cellulose capabilities. Synthetic fiber grades, including aramid options, occupy emerging niches in marine and transportation composites seeking weight reduction with fire-retardant properties.
REACH registration requirements in Europe govern formaldehyde emission thresholds and resin chemistry disclosures for construction material applications. EPA regulations under the Toxic Substances Control Act affect phenolic resin imports and domestic manufacturing compliance costs in the United States. China's GB standards for laminate flooring and decorative panels establish mandatory testing protocols that pre-impregnated paper suppliers must certify against for market access. Stakeholders must monitor evolving fire-classification standards across building codes and transportation safety frameworks, as these specifications increasingly dictate fiber selection and resin formulation investments.
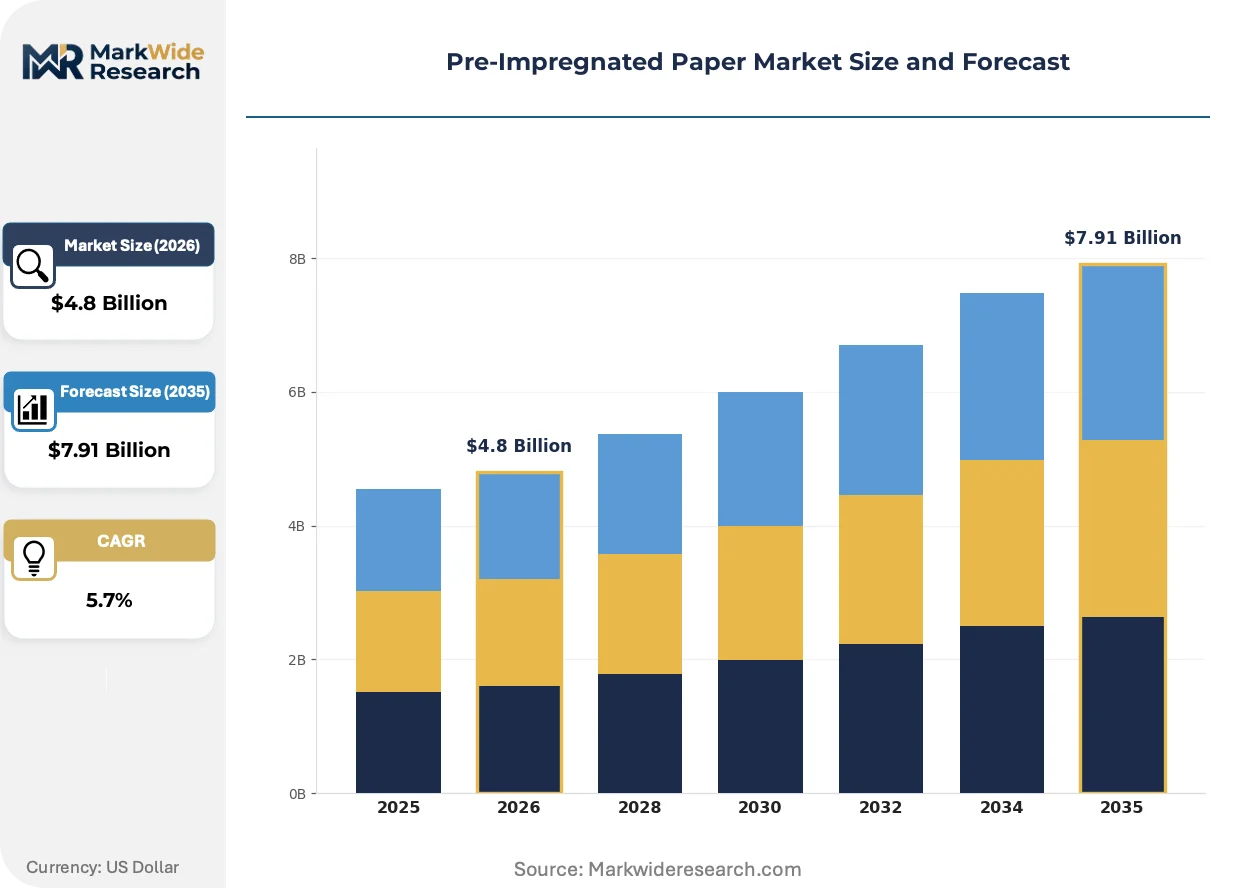
Market Dynamics
Decorative laminate manufacturers are consolidating supplier relationships around resin-saturation consistency as REACH compliance deadlines compress certification timelines and Chinese production clusters absorb incremental global capacity.
Growth Catalysts
- GB Standard Certification:China's mandatory testing protocols for laminate flooring and decorative panels are pulling pre-impregnated paper volumes into domestic manufacturing clusters. Suppliers achieving GB compliance capture preferential procurement status from state-backed construction programs.
- Melamine Resin Formulation Advances:Improved volatile-content control during B-stage curing is expanding application ranges into high-gloss furniture surfaces. Technical-grade papers with sub-3% volatile variance command grade premiums in European decorative laminate contracts.
- Furniture Export Manufacturing:Vietnamese and Indonesian furniture exporters are scaling laminate component production to serve North American retail channels. These facilities source pre-impregnated paper through regional distributors with bonded warehouse arrangements.
Market Restraints
- Formaldehyde Emission Thresholds:REACH registration requirements for construction material applications are forcing reformulation of phenolic resin chemistries. Compliance testing adds 8-14 weeks to product qualification cycles for European market entry.
- Wood Fiber Supply Concentration:Nordic pulp suppliers control specialty-grade fiber blending capabilities for aerospace and electrical insulation segments. Alternative fiber sourcing from South American plantations requires 18-24 month qualification timelines.
- Thermoset Substitution Pressure:Thermoplastic composite prepregs are displacing melamine-saturated papers in transportation interior panels where recyclability mandates apply. Automotive OEMs in Germany and Japan are piloting PP-based alternatives for seat back substrates.
Strategic Opportunities
- Aramid Fiber Grades:Marine and rail transportation composites seeking fire-retardant weight reduction represent untapped demand for synthetic fiber pre-preg papers. Classification society approvals from Lloyd's Register and DNV would unlock yacht and ferry interior contracts.
- India Construction Materials:BIS certification requirements for laminate flooring are creating first-mover advantages for suppliers establishing local testing partnerships. Domestic laminate production capacity is expanding 12-15% annually in Gujarat and Maharashtra industrial corridors.
- Digital Print Compatibility:Water-based ink adhesion on modified resin surfaces is enabling short-run decorative pattern production. Print-on-demand laminate manufacturers in Italy and Spain are sourcing papers with optimized surface energy profiles.
Industry Challenges
- Resin Chemist Talent Scarcity:Formulation expertise for thermoset-wood fiber interface engineering is concentrated among retiring specialists in German and Austrian paper mills. Technical training programs require 4-6 year development cycles.
- Hot-Press Integration Complexity:Pre-impregnated paper performance varies significantly across laminating equipment vintages. Retrofitting 1990s-era presses for modern resin flow characteristics demands mechanical and control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Impregnated Paper Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber, Wood Fiber, Synthetic Fiber, Kevlar End User: Aerospace, Automotive, Construction, Marine Application: Composites, Electrical Insulation, Decorative Laminates, Aerospace Components Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Koehler Paper, Ahlstrom-Munksjö, Impress, Felix Schoeller, SURTECO GmbH, Schattdecor AG, Toppan Printing Co Ltd, AICA Kogyo Co Ltd, Interprint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Impregnated Paper Market Evolving Landscape
Digital workflow integration is compressing design-to-lamination cycles while regulatory chemistry disclosures are reshaping resin formulation transparency requirements across construction material supply chains.
Water-based digital printing systems are decentralizing decorative pattern production for short-run laminate batches. Italian furniture manufacturers are adopting these systems to serve customized hospitality interior contracts with 48-hour turnaround requirements. The technology is decentralizing design control from centralized print houses to regional laminating facilities.
REACH formaldehyde emission thresholds are mandating resin chemistry disclosures for construction material applications. European laminate producers must document phenol and melamine content through supply chain tiers. Decorative panel manufacturers serving German residential construction are qualifying alternative resin systems 18 months ahead of 2026 enforcement deadlines.
Consolidated procurement contracts are compressing supplier switching cycles among large laminate producers. Tier-one furniture OEMs in China are consolidating annual pre-impregnated paper volumes under single-source agreements with resin-saturation guarantees. This pattern is most visible in Guangdong province where export-oriented laminate clusters serve North American retail distribution networks.
Pre-Impregnated Paper Market Segmentation
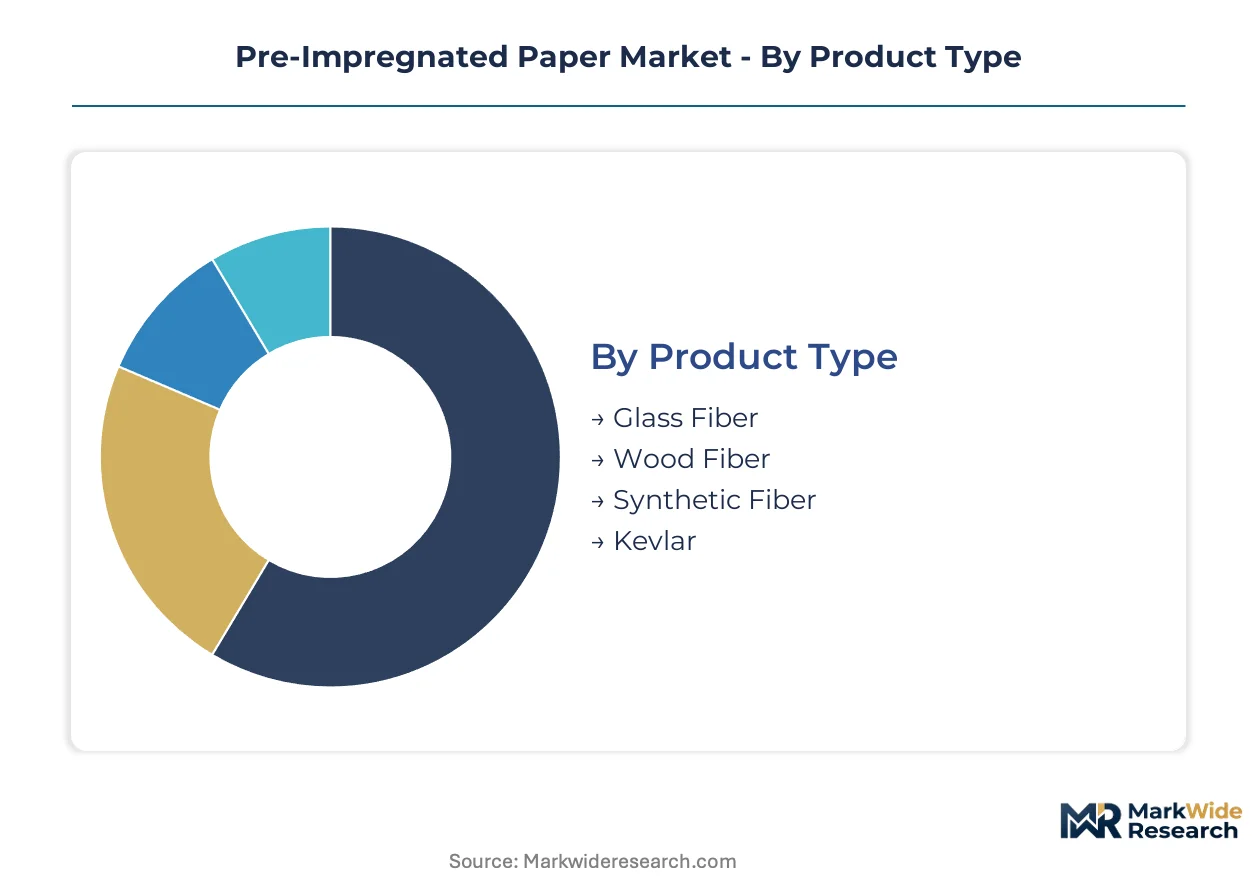
Pre-impregnated paper segmentation reflects divergent technical requirements across fiber substrates and end-use specifications. Manufacturers configure production lines around resin-saturation chemistry and cure-state control to match application-specific performance thresholds.
Product Type:
Upgrade cycles in laminating equipment are pulling fiber selection toward higher-performance substrates as hot-press operators replace aging cellulose-dominant lines.
- Wood Fiber:Cellulose-based substrates saturated with melamine or phenolic resins dominate decorative laminate production where print clarity and resin absorption uniformity determine grade classification. Demand concentrates in Chinese manufacturing clusters serving furniture export programs, though REACH formaldehyde thresholds are compressing qualification timelines for European market entry.
- Glass Fiber:Woven or non-woven glass mat substrates provide thermal stability and dielectric strength for electrical insulation and aerospace applications where cellulose performance limits are exceeded. Volume concentrates in German and Japanese electrical equipment supply chains, with laminating equipment retrofits driving specification upgrades in aging transformer manufacturing facilities.
- Synthetic Fiber:Polyester and polypropylene-based papers occupy emerging transportation interior niches seeking weight reduction with modified fire properties.
- Kevlar:Aramid fiber grades serve marine and rail composites requiring ballistic resistance and fire-retardant certification from classification societies.
Volume placements concentrate in Wood Fiber; the faster expansion belongs to Glass Fiber.
End User:
Cost-tier stratification separates specification-grade aerospace demand from price-sensitive construction volumes.
- Construction:Decorative laminate manufacturers represent the largest consumption tier, sourcing pre-impregnated paper for high-pressure and low-pressure laminate systems in residential and commercial surfacing. Procurement concentrates in Chinese state-backed building programs and Vietnamese furniture export facilities serving North American retail channels.
- Aerospace:Tier-one airframers and their subcontractors specify glass fiber and aramid pre-preg papers for interior panels, cargo liners, and structural components where FAA and EASA fire-smoke-toxicity certifications apply. Qualification cycles extend 24-36 months, locking supplier relationships around resin-saturation consistency guarantees.
- Automotive:Seat back substrates and interior panels drive phenolic-saturated paper consumption, though thermoplastic composite substitution is accelerating in German and Japanese OEM pilot programs.
- Marine:Yacht and ferry interior contracts require Lloyd's Register and DNV approval for fire-retardant synthetic fiber grades.
Construction absorbs the highest tonnage; aerospace commands the steepest expansion trajectory.
Application:
Application segmentation tracks the divergence between commodity surfacing volumes and specialized technical-grade specifications.
- Decorative Laminates:Surface and core layer papers for furniture, flooring, and interior paneling represent the foundational demand segment. Chinese laminate clusters in Guangdong province drive volume consumption, with digital print compatibility emerging as a specification differentiator for short-run production.
- Electrical Insulation:Transformer and motor winding applications require glass fiber substrates with controlled resin pre-cure and volatile content. German electrical equipment manufacturers anchor demand, with grid infrastructure investment programs in India expanding addressable market scope.
- Composites:Marine, rail, and industrial transportation applications seek fire-retardant synthetic fiber grades.
- Aerospace Components:Structural and non-structural airframe applications command premium positioning through extended qualification protocols.
Decorative laminates dominate placement volumes; electrical insulation is gaining share fastest.
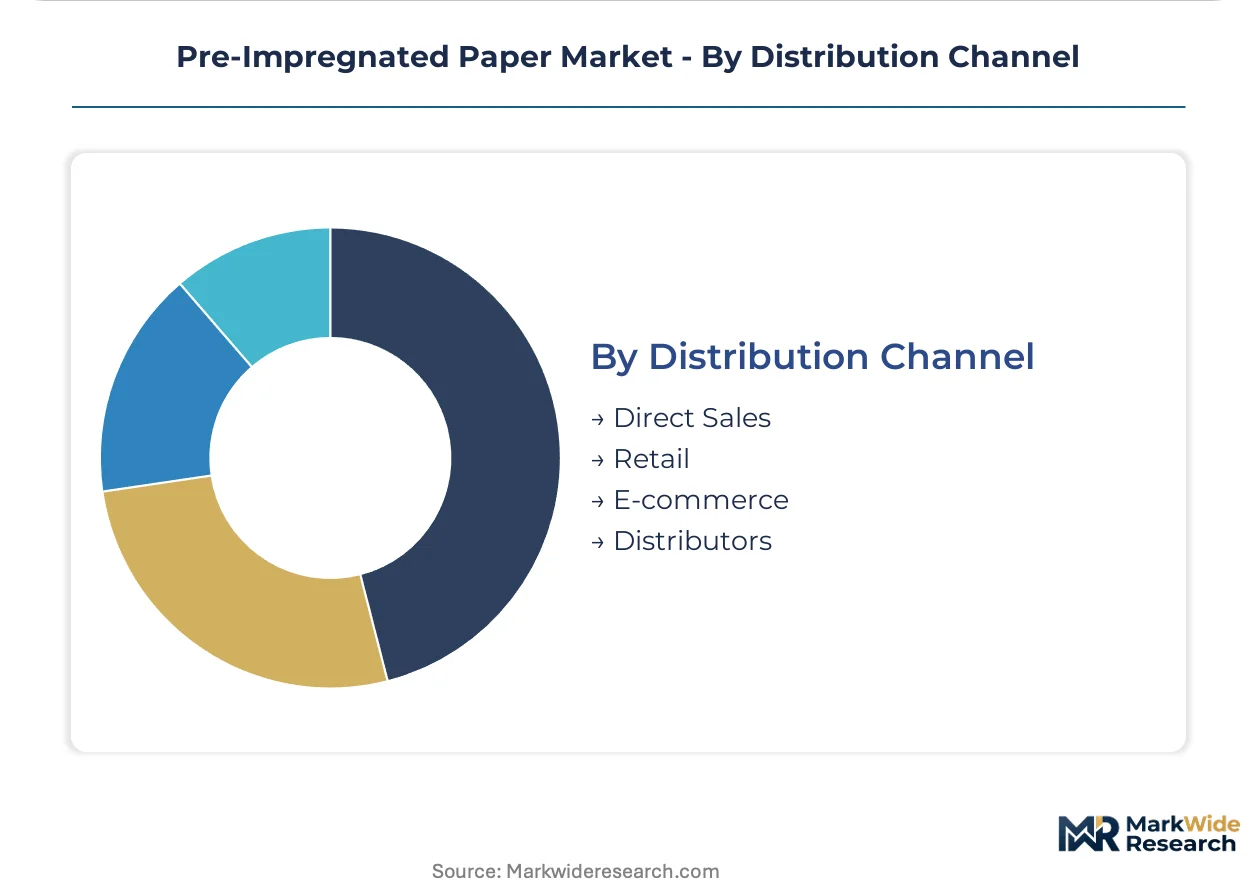
Distribution Channel:
Channel structure reflects the technical intensity of specification-grade procurement versus commoditized volume transactions.
- Direct Sales:Large laminate producers and aerospace tier-ones negotiate annual volume contracts with resin-saturation guarantees and technical service support. Chinese furniture OEMs are consolidating procurement under single-source direct agreements with bonded warehouse arrangements for Vietnamese and Indonesian manufacturing facilities.
- Distributors:Regional stocking distributors serve mid-tier laminate manufacturers and automotive suppliers with inventory management and technical consultation. European distributors maintain qualification documentation for REACH compliance support.
- Retail:Small-volume architectural and design firms source specialty grades through building material retailers.
- E-commerce:Digital platforms capture prototype and R&D sampling volumes with limited technical service attachment.
Direct sales capture the largest contract values; distributor networks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic pulp forests supply specialty-grade wood fibers that anchor European aerospace and electrical insulation supply chains. Chinese manufacturing clusters absorb the largest volume share for decorative laminate exports. Vietnamese furniture fabricators source through bonded warehouse arrangements serving North American retail channels.
China
State-backed construction programs in Guangdong province pull pre-impregnated paper volumes into domestic laminate manufacturing clusters. GB standards for laminate flooring and decorative panels mandate certification protocols that filter supplier access. Shenzhen and Dongguan industrial corridors host export-oriented facilities serving North American furniture retail networks.
Germany
Electrical equipment manufacturers anchor glass fiber pre-preg demand for transformer and motor winding applications. REACH formaldehyde emission thresholds compress phenolic resin qualification timelines for construction material entry. Bavarian industrial zones concentrate laminating equipment retrofits and resin formulation expertise.
United States
EPA regulations under the Toxic Substances Control Act affect phenolic resin import compliance costs for domestic laminate producers. Furniture OEMs consolidate procurement contracts around resin-saturation consistency guarantees. Southeast manufacturing corridors absorb Vietnamese and Indonesian laminate component imports for final assembly.
India
BIS certification requirements for laminate flooring create first-mover positioning for suppliers establishing local testing partnerships. Grid infrastructure investment programs expand addressable scope for electrical insulation grades. Gujarat and Maharashtra industrial corridors expand domestic laminate production capacity annually.
Japan
METI industrial standards govern resin chemistry disclosures for construction material applications in residential surfacing. Automotive OEMs pilot thermoplastic composite alternatives displacing melamine-saturated papers in seat back substrates. Nagoya industrial zones concentrate laminating equipment coordination with aerospace tier-one suppliers.
Pre-Impregnated Paper Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers secure raw material continuity through integrated pulp-to-paper operations. The vendor base stratifies around resin-saturation chemistry expertise and fiber blending specialization. Three archetypes anchor positioning: integrated pulp producers, specialized fiber blenders, and decorative print specialists. Strategic partnerships with laminating equipment vendors and geographic expansion into Southeast Asian furniture export zones represent dominant competitive vectors.
Among European integrated producers, Koehler Paper exemplifies captive pulp supply strategies securing fiber continuity. Ahlstrom-Munksjö occupies a position within specialized fiber blending for technical-grade specifications. Schattdecor AG anchors the decorative print archetype through design library depth and equipment partnership coordination.
| Leading Market Players |
|---|
| Koehler Paper |
| Ahlstrom-Munksjö |
| Impress |
| Felix Schoeller |
| SURTECO GmbH |
| Schattdecor AG |
| Toppan Printing Co Ltd |
| AICA Kogyo Co Ltd |
| Interprint |
| Others |
Value Network & Pricing Analysis
Decorative laminate OEMs in Guangdong province anchor procurement volumes under multi-year contracts with resin-saturation guarantees, compressing spot-market liquidity and hardening premium tier pricing for REACH-certified grades.
Pricing Analysis
Technical service bundling separates contract structures across the Pre-Impregnated Paper Market, with resin formulation support and hot-press calibration included in direct agreements while distributors strip these for price-competitive spot sales. Three-tier pricing structure across aerospace specification, construction-grade certified, and economy furniture tiers reflects volatile-content control and fiber provenance. Cost compression in economy wood fiber grades is intensifying because Vietnamese furniture exporters are consolidating annual volumes under single-source arrangements. Tier-one aerospace subcontractors exhibit least price sensitivity due to 24-36 month qualification lock-in, while mid-tier laminate manufacturers in Indonesia face acute margin pressure from GB certification testing fees.
Supply Chain Analysis
Specialized resin chemist availability in Bavarian industrial zones and Nordic pulp processing regions constrains capacity expansion timelines for technical-grade pre-preg paper output. Manufacturing concentrates in Germany, China, and Japan, with each hub drawing from distinct fiber supply bases: Nordic specialty pulp, South American plantation hardwood, and domestic glass fiber mat production respectively. Raw material dependencies center on melamine resin precursors, phenol feedstocks, and aramid fiber imports. Single-source vulnerability runs through Nordic suppliers controlling aerospace-grade fiber blending capabilities. Distribution runs through direct sales for large laminate producers and regional stocking distributors for mid-tier automotive and construction accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pre-Impregnated Paper Market is consolidating around resin-saturation consistency guarantees as REACH compliance deadlines and Chinese state-backed procurement programs squeeze sub-scale formulators from qualification pipelines.
For Market Incumbents: Anticipate thermoplastic composite substitution in German and Japanese automotive seating programs by securing backward integration into aramid fiber grades for marine and rail fire-retardant applications. Koehler Paper's captive pulp strategy exemplifies raw material continuity defense; replicate this through specialty fiber offtake agreements with Nordic suppliers. Certification investment in Lloyd's Register and DNV approvals unlocks yacht interior contracts with 36-month lock-in periods. For New Entrants and Emerging Players: Mid-tier laminate manufacturers in Gujarat and Maharashtra industrial corridors present accessible entry points as BIS certification requirements filter incumbent supplier access. Digital print-compatible paper grades for Italian and Spanish short-run hospitality contracts offer white-space positioning with lower capital intensity than commodity decorative volumes. Pursue local testing partnerships with Indian standards bodies as the go-to-market anchor. For Investors and Strategic Acquirers: The window for entry favors specialized fiber blenders with existing aerospace qualification relationships over commodity decorative paper assets. Long-term viability hinges on resin formulation expertise concentration among retiring German and Austrian specialists. Watch for automotive OEM thermoplastic pilot program acceleration as the inflection signal triggering accelerated melamine paper asset devaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Fiber Supply | Nordic pulp offtake agreements secure raw material continuity for REACH-certified construction grades. |
| Classification Society Certification Investment | Lloyd's Register and DNV approvals unlock marine interior contracts with extended qualification cycles. |
| Digital Print Surface Energy Optimization | Water-based ink adhesion modifications capture Italian and Spanish short-run laminate production demand. |
| Local Testing Partnership Establishment | BIS certification collaboration in Gujarat and Maharashtra secures preferential procurement from state-backed construction programs. |
| Resin Chemist Technical Training Program | 4-6 year development cycles address formulation expertise scarcity as German and Austrian specialists retire. |
Research Methodology
Independent corroboration across plant managers at European integrated paper mills, procurement leads at Chinese laminate OEMs, and resin formulation specialists in German industrial zones underwrites the qualitative findings in this study. Primary interviews with decorative laminate manufacturers, aerospace tier-one subcontractors, and electrical equipment procurement directors combined with secondary validation from customs trade data, ECHA REACH registration databases, and SEC filings from publicly traded paper producers. Bottom-up volume triangulation across fiber substrate categories and top-down value validation against end-use consumption patterns anchored market sizing.
Historical reference periods spanning pre-pandemic baseline, supply disruption correction, and post-regulatory implementation phases anchored the forecast window construction across the analysis window. Segmentation modeling incorporated fiber substrate type, resin chemistry class, end-use industry vertical, and regional regulatory cluster dimensions. CAGRs derived from weighted average growth across these segments with explicit inputs for Chinese state-backed construction program absorption rates and automotive thermoplastic substitution pace assumptions.
Revisions become necessary when automotive OEM thermoplastic pilot programs accelerate beyond current trial phases, when Nordic pulp supply disruptions extend qualification timelines for aerospace grades, or when Indian BIS certification requirements tighten unexpectedly. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Paper Carrier Bags Market