
 Corrugated Shippers Market | 2026-2036
Corrugated Shippers Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Shippers Market Outlook
The EU Green Deal's packaging waste reduction targets is hardening demand for fiber-based alternatives across European supply chains. International Paper leverages its integrated pulp-to-box network to secure virgin and recycled fiber streams at scale. WestRock Company anchors its position through advanced containerboard recycling infrastructure across North American mills. Smurfit Kappa Group dominates European corrugated production with a dense network of regional sheet plants and converting facilities.
Corrugated shippers are paper-based protective enclosures manufactured from fluted medium laminated between linerboard sheets, typically constructed with burst strengths between 200 and 275 lb per square inch to withstand stacking and transport stresses. Their primary purpose is to contain, cushion, and unitize goods for distribution while enabling efficient palletization and automated handling. Die-cut formats represent the fastest-growing product configuration as brand owners demand shelf-ready presentation with reduced assembly labor. The food and beverage end-use segment sustains the largest volume share, though electronics applications generate superior margin pools due to anti-static and precision-fit specifications.
FDA food contact substance regulations in the United States, EU REACH chemical compliance for printed coatings, and China's GB standards for packaging recyclability collectively shape material selection and coating chemistry across multinational supply chains. These frameworks elevate testing costs for smaller converters while rewarding integrated producers with captive laboratory capabilities. Stakeholders must monitor evolving extended producer responsibility schemes and fiber certification requirements as decisive variables for capacity planning and customer retention.
Market Dynamics
Recycled fiber sourcing mandates from the EU Green Deal are compressing virgin pulp allocation and forcing converters to requalify coating chemistries for food contact compliance across multinational supply chains.
Growth Catalysts
- E-commerce fulfillment density:Food and beverage brands demand shelf-ready die-cut formats that reduce last-mile assembly labor and enable direct-to-shelf merchandising in automated distribution centers.
- REACH chemical compliance:EU coating reformulation requirements accelerate water-based barrier adoption for direct food contact applications, creating specification pull from export-oriented North American converters.
- China's GB recyclability standards:Domestic packaging producers face mandatory fiber recovery rate thresholds that favor corrugated over multi-material alternatives in electronics and appliance segments.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with municipal collection program disruptions and export demand from Asian paper mills, squeezing converter margins during fiber shortages.
- German linerboard concentration:Three integrated producers control over half of European kraftliner capacity, creating supply vulnerability for independent sheet plants during maintenance turnarounds or energy price spikes.
- Plastic barrier substitution:Thin-gauge polyethylene terephthalate clamshells retain cost advantage for moisture-sensitive produce applications where fiber-based alternatives require expensive fluorine-free coatings.
Strategic Opportunities
- India's cold chain expansion:Temperature-controlled food logistics infrastructure gaps create first-mover positioning for insulated corrugated formats with phase-change material integration in pharmaceutical and dairy distribution.
- Extended producer responsibility schemes:France's Citeo packaging fee modulation rewards higher recycled content thresholds, enabling premium positioning for converters with verified post-consumer fiber traceability systems.
- Digital print convergence:Single-pass inkjet integration with rotary die-cutting enables lot-size-one customization for direct-to-consumer beauty and nutraceutical brands without plate changeover downtime.
Industry Challenges
- Food safety auditor scarcity:BRCGS packaging certification audits face 12-16 week scheduling backlogs, delaying qualification for supplier status with major retail and quick-service restaurant chains.
- Legacy ERP integration:Mill scheduling systems from the 1990s lack API connectivity to customer EDI platforms, forcing manual order translation and inventory visibility gaps in vendor-managed inventory programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Shippers Market |
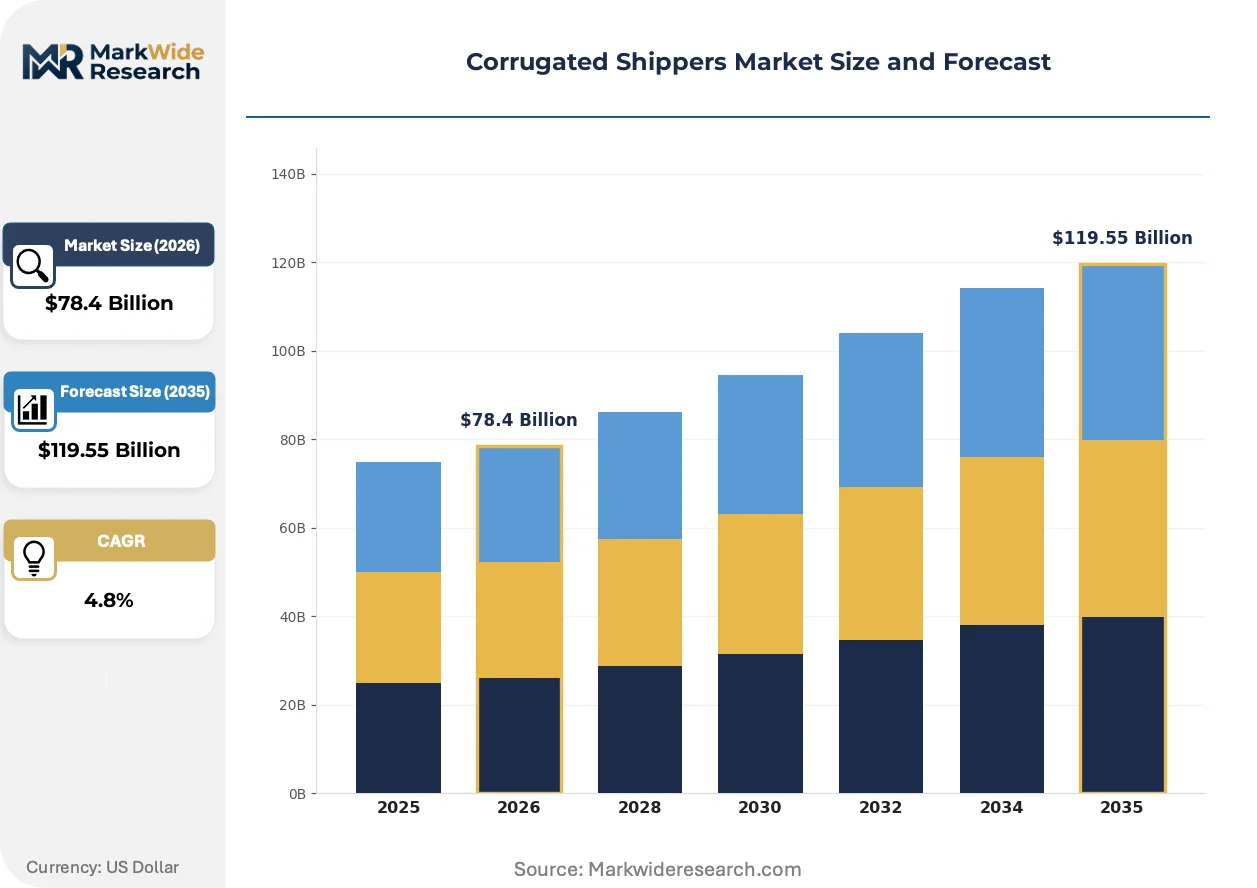
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Container, Half-Slotted Container, Full Telescope Design, Die-Cut End Use Industry: Food & Beverage, Pharmaceuticals, Electronics, Personal Care Packaging Type: Printed, Unprinted, Custom, Standard Distribution Channel: Online, Offline, Direct Sales, Third-Party Retailers |
| Companies Covered | International Paper, WestRock Company, Smurfit Kappa Group, DS Smith, Mondi Group, Packaging Corporation of America, Rengo Co., Ltd., Georgia-Pacific LLC, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Shippers Market Strategic Shifts
Active moisture management and print personalization capabilities are compressing the specification gap between commodity shipping containers and retail-ready packaging, blurring traditional procurement categories.
Fluorine-free grease-resistant coatings derived from plant-based polysaccharides are rewriting food service packaging specifications. Quick-service restaurant chains in the United States and Germany have accelerated qualification timelines from 18 months to 6 months for direct-contact applications. This compression is forcing coating suppliers to abandon legacy solvent-based chemistries before patent cliffs erode barrier performance premiums.
EU Green Deal packaging waste reduction targets now mandate 70% recyclability rates for all fiber-based shipping materials by 2030. The regulation triggers reformulation of wax alternatives and adhesive systems that previously compromised repulpability. Electronics manufacturers exporting from China to European distribution hubs face the steepest compliance ramps, with many accelerating supplier audits to lock in qualified substrate sources ahead of enforcement windows.
Direct procurement relationships between brand owners and integrated containerboard producers are displacing traditional distributor intermediaries in high-volume corrugated categories. Food and beverage multinationals now negotiate mill-direct contracts for annual volumes exceeding 50 million square meters, capturing volume rebates and sustainability traceability that distributors cannot match. This disintermediation concentrates most visibly in Germany and the United States, where manufacturing clusters enable efficient dedicated fleet logistics from mill to converting plant.
Corrugated Shippers Market Segmentation
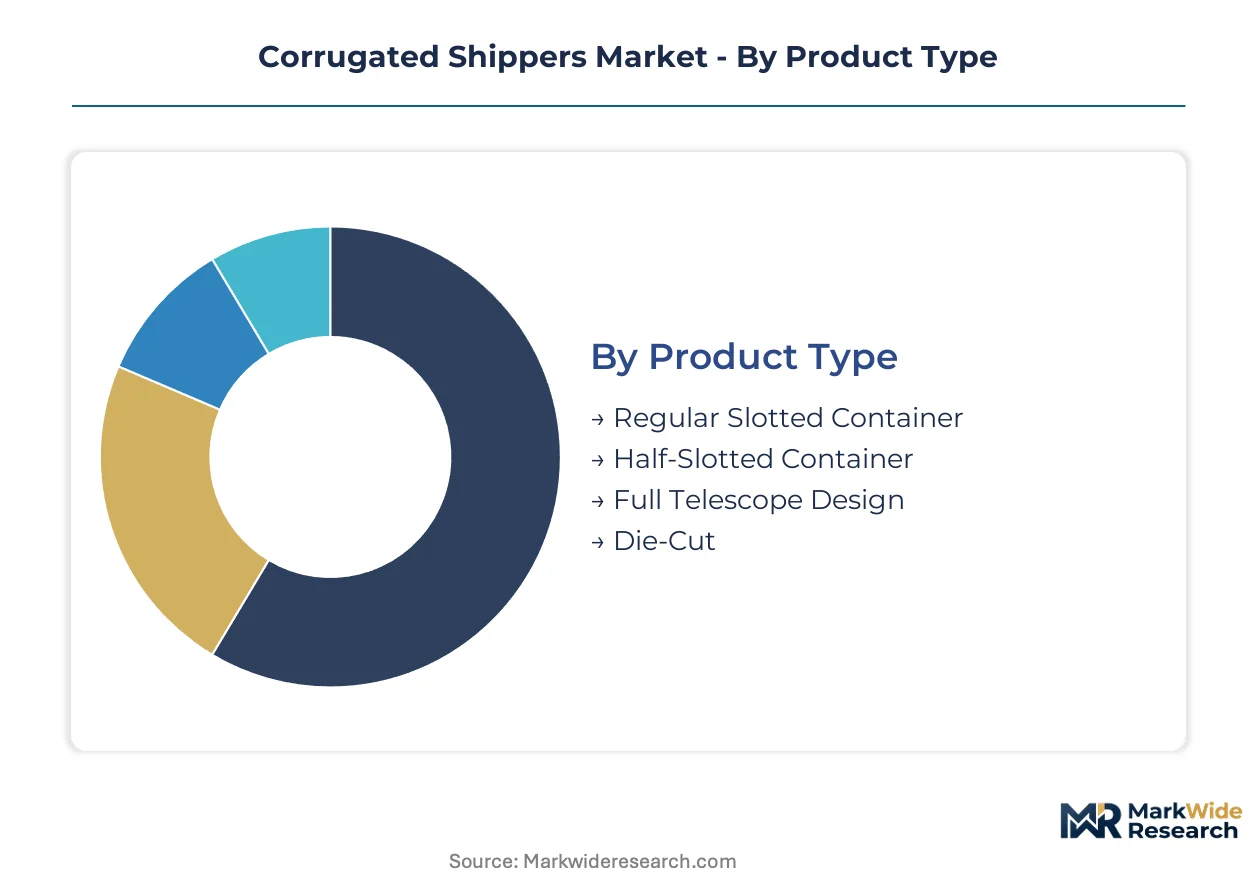
Segmentation in corrugated shippers determines compliance pathways, margin structures, and procurement strategies across multinational supply chains. Food contact certifications, print personalization requirements, and channel-specific logistics demands create divergent specification clusters that reshape converter capacity allocation.
Product Type:
FDA food contact substance regulations apply differentially across formats, with direct-contact applications demanding more rigorous coating documentation than secondary shipping containers.
- Regular Slotted Container:The standard four-flap design with overlapping outer flaps dominates bulk commodity shipping for its structural efficiency and minimal material usage. Demand concentrates in German automotive parts distribution and Chinese electronics export hubs where palletization density drives specification. REACH-compliant water-based coatings are becoming mandatory for EU-bound shipments.
- Die-Cut:Precision-cut formats with integrated locking tabs enable shelf-ready presentation without secondary assembly. Food and beverage brands in the United States and Germany specify these for automated distribution centers where direct-to-shelf merchandising reduces labor costs. Anti-static specifications for electronics applications command premium positioning.
- Half-Slotted Container:Open-top design with bottom flaps only, suited for top-loading applications in manual fulfillment environments.
- Full Telescope Design:Separate top and bottom pieces providing double-wall protection for heavy or fragile items in industrial equipment distribution.
Leading the category by volume: Regular Slotted Container. Growing fastest: Die-Cut.
End Use Industry:
Margin structures diverge sharply across end uses, with precision-fit specifications and barrier requirements creating tiered pricing bands.
- Food & Beverage:The largest volume segment encompassing direct food contact and secondary shipping applications. EU Green Deal recyclability mandates and FDA coating compliance create dual-certification burdens for exporters. German quick-service restaurant chains and U.S. grocery distributors drive specification for fluorine-free grease-resistant alternatives.
- Electronics:Anti-static coatings, precision-fit cushioning, and moisture barrier specifications generate superior margin pools. China's GB standards for packaging recyclability favor corrugated over multi-material alternatives, accelerating qualification timelines for European-bound exports.
- Pharmaceuticals:Temperature-controlled distribution requirements in India's expanding cold chain create demand for insulated formats with phase-change material integration.
- Personal Care:Print personalization and brand presentation requirements favor digital inkjet-compatible substrates for direct-to-consumer beauty and nutraceutical brands.
Food & Beverage dominates absolute volume. Electronics delivers highest margin per square meter.
Packaging Type:
Print capability and customization depth determine converter equipment requirements and customer switching costs.
- Printed:Brand graphics, handling instructions, and regulatory markings applied via flexographic or digital processes. EU REACH compliance for ink chemistries and FDA food contact substance regulations constrain formulation choices for multinational suppliers.
- Custom:Engineered specifications including die-cut dimensions, proprietary locking mechanisms, and integrated handles. Electronics and personal care brands in Germany and the United States specify these for unboxing experience differentiation.
- Unprinted:Plain kraft or white-top linerboard for commodity shipping where branding is secondary to cost minimization.
- Standard:Catalog formats with fixed dimensions and minimal modification, serving high-volume, low-variability supply chains.
Printed formats capture volume leadership. Custom specifications are expanding most quickly as brand owners consolidate SKU rationalization with shelf-ready requirements.
Distribution Channel:
Channel selection determines order fragmentation, lead time compression, and inventory visibility requirements.
- Direct Sales:Mill-direct contracts between integrated producers and high-volume brand owners, displacing traditional distributor intermediaries. Food and beverage multinationals in Germany and the United States negotiate annual volumes exceeding 50 million square meters for sustainability traceability and volume rebates.
- Online:E-commerce fulfillment platforms requiring lot-size-one customization and rapid turnaround. Digital print convergence with rotary die-cutting enables direct-to-consumer beauty brands to personalize packaging without plate changeover downtime.
- Offline:Traditional distributor networks serving fragmented small and mid-sized customers with catalog formats and standard lead times.
- Third-Party Retailers:Packaging distributors and industrial supply houses providing consolidated sourcing for customers below direct-sales thresholds.
Direct Sales leads by revenue concentration. Online channels are gaining share fastest as e-commerce fulfillment density reshapes specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European corrugated consumption, with Duisburg and Dortmund sheet plants feeding automated distribution centers serving German retail and automotive supply chains.
United States
E-commerce fulfillment density in Chicago and Dallas-Fort Worth drives specification for die-cut shelf-ready formats. FDA food contact substance regulations constrain coating chemistries for direct-contact food service applications. The Southeast manufacturing belt from Georgia to the Carolinas concentrates integrated containerboard mills with captive converting capacity.
Germany
Quick-service restaurant chains and grocery distributors in Bavaria and North Rhine-Westphalia accelerate qualification of fluorine-free grease-resistant coatings. EU Green Deal packaging waste reduction targets mandate 70% recyclability rates by 2030, triggering adhesive system reformulation. The Hamburg-Bremen port cluster handles high volumes of export-bound electronics packaging with anti-static specifications.
China
GB standards for packaging recyclability favor corrugated over multi-material alternatives in Shenzhen and Dongguan electronics export hubs. Dual carbon goals compress virgin pulp allocation while expanding recycled fiber infrastructure. Yangtze River Delta converters face compressed lead times for European-bound shipments requiring REACH-compliant water-based barriers.
India
Temperature-controlled pharmaceutical distribution in Maharashtra and Gujarat creates first-mover positioning for insulated corrugated formats. FSSAI food safety regulations elevate BRCGS packaging certification requirements for dairy and nutraceutical exporters. The Delhi-Mumbai industrial corridor attracts integrated producers seeking proximity to fragmented cold chain infrastructure.
Japan
Precision-fit specifications for electronics and robotics components in the Nagoya-Tokyo corridor sustain premium margin pools. METI circular economy guidelines accelerate adoption of fiber-based alternatives to expanded polystyrene cushioning. Osaka-based converters specialize in small-lot digital print integration for cosmetics and premium food brands.
Corrugated Shippers Market Competitive Environment
The competitive structure tilts toward integrated pulp-to-box producers with captive fiber streams and laboratory certification capabilities. Three strategic archetypes dominate: multinational integrated producers with mill networks spanning multiple continents, regional specialists with dense sheet plant footprints in single markets, and independent converters dependent on merchant linerboard supply. Capacity expansion and coating chemistry reformulation represent the dominant competitive moves as regulatory compliance windows compress.
Among North American integrated producers, International Paper and WestRock Company exemplify the scale-driven archetype with backward integration into virgin and recycled fiber streams. Smurfit Kappa Group occupies a parallel position in European markets, representing the regional density model with distributed converting capacity close to end-use clusters. These three anchors demonstrate how certification capabilities and sustainability traceability systems are becoming the decisive variables for retaining multinational brand owner contracts.
| Leading Market Players |
|---|
| International Paper |
| WestRock Company |
| Smurfit Kappa Group |
| DS Smith |
| Mondi Group |
| Packaging Corporation of America |
| Rengo Co., Ltd. |
| Georgia-Pacific LLC |
| Oji Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between BRCGS-audited food contact packaging and commodity shipping containers manifests in both pricing power and supply chain access. Premium converters with captive laboratory capabilities capture sustained margin premiums while independent sheet plants face exclusion from multinational brand owner vendor lists.
Pricing Analysis
Yield-based pricing anchors corrugated shipper contracts, with converters charging per pallet-stacking efficiency rather than pure material weight. Three-tier pricing structure across premium, standard, and economy levels separates BRCGS-certified food contact formats from REACH-compliant export specifications and unprinted commodity kraft. Cost compression in standard-grade segments is intensifying because OCC price volatility transfers directly to converter margins. Small and mid-sized distributors exhibit highest price sensitivity, while integrated producers with mill-direct contracts show least elasticity due to volume rebate structures.
Supply Chain Analysis
Single-source vulnerability sits with German kraftliner production, where three integrated producers control majority European capacity. Raw material flows draw from Swedish and Finnish virgin pulp mills, recycled OCC streams from municipal collection programs, and Chinese containerboard imports for price-sensitive segments. Tariff exposure on coated linerboard imports from Asia threatens independent converters dependent on merchant supply. Distribution runs through dedicated fleet logistics from integrated mill networks to regional converting plants, bypassing traditional distributor intermediaries for volumes exceeding 50 million square meters annually.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance windows are accelerating consolidation as smaller converters lack capital for coating chemistry reformulation and certification laboratory investment. Weaker players face forced exit or acquisition by integrated producers with captive fiber streams.
For Market Incumbents: To counter disintermediation pressure from mill-direct procurement relationships, deepen backward integration into recycled fiber collection infrastructure and expand captive laboratory certification capabilities for dual FDA-REACH compliance. Anchor capacity additions in the Ruhr industrial corridor and Southeast US manufacturing belt to capture dedicated fleet logistics efficiencies for high-volume food and beverage contracts. For New Entrants and Emerging Players: Begin with India's temperature-controlled pharmaceutical distribution segment, where cold chain infrastructure gaps create first-mover positioning for insulated corrugated formats with phase-change material integration. Target Maharashtra and Gujarat dairy exporters facing FSSAI certification requirements that established players have not fully addressed. Pursue digital print convergence partnerships with rotary die-cutting equipment suppliers to enable lot-size-one customization for direct-to-consumer beauty brands. For Investors and Strategic Acquirers: Re-rating potential sits with regional sheet plant specialists with dense converting footprints in single markets given extended producer responsibility scheme implementation creating premium positioning for verified post-consumer fiber traceability. Five-to-ten year viability favors converters with mill-direct relationships and sustainability certification systems already operational. Monitor Citeo packaging fee modulation thresholds in France as the signal indicating which fiber verification systems will command vendor preference.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Captures OCC supply security independent of municipal program disruptions and Asian export demand swings. |
| Fluorine-Free Coating Chemistry Reformulation | Meets compressed 6-month qualification timelines from US and German quick-service restaurant chains. |
| Digital Print Convergence with Rotary Die-Cutting | Enables lot-size-one customization for direct-to-consumer beauty brands without plate changeover downtime. |
| Phase-Change Material Integration for Cold Chain | Addresses infrastructure gaps in Indian pharmaceutical and dairy temperature-controlled distribution. |
| Dual FDA-REACH Certification Laboratory Investment | Retains multinational brand owner contracts as compliance windows compress and testing backlogs extend. |
Study Parameters
Independent corroboration across mill operations executives, corrugated converting plant managers, and food and beverage packaging procurement leads underwrites the qualitative findings. Primary fieldwork with quick-service restaurant chain specification directors and electronics export logistics coordinators in Shenzhen and Dongguan complemented secondary validation from EU ECHA regulatory filings, US FDA food contact substance notifications, and Chinese GB standards documentation. Bottom-up capacity modeling triangulates against top-down consumption estimates from customs trade data and industry association production surveys.
Historical reference periods spanning pre-pandemic baseline through post-regulatory implementation phases anchor the forecast window across the analysis window. Segmentation dimensions include product format, end-use industry vertical, print capability tier, and distribution channel structure. CAGRs derive from trend extrapolation of e-commerce fulfillment density, coating chemistry adoption curves, and mill capacity expansion announcements. Industry-specific inputs incorporate OCC price volatility indices and extended producer responsibility fee modulation schedules.
Underlying measurement precision varies by segment; die-cut shelf-ready formats and electronics anti-static specifications carry tighter precision than commodity unprinted shipping containers. Forecasts reflect assumptions regarding EU Green Deal enforcement timing, REACH coating reformulation adoption rates, and Chinese dual carbon goal implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Paper Packaging Materials Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Paperboard Partition Market